
 Krabbe Disease Treatment Market | 2026-2036
Krabbe Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Krabbe Disease Treatment Market Outlook
Hospital-based procurement of gene therapy interventions is collapsing toward a concentrated tier of academic medical centers with transplant capabilities. Orchard Therapeutics leverages hematopoietic stem cell gene therapy platforms to anchor its position in ultra-rare lysosomal storage disorders. Pfizer Inc. sustains manufacturing scale across biologics networks that serve narrow indication populations. Novartis AG competes through CAR-T infrastructure repurposed for inherited disease modalities.
Krabbe disease treatment encompasses therapeutic interventions targeting galactosylceramidase deficiency, including enzyme replacement formulations requiring intrathecal delivery across the blood-brain barrier and hematopoietic stem cell gene therapies designed to correct the GALC mutation. Gene therapy segments command premium positioning due to one-time curative potential and complex vector manufacturing requirements. Enzyme replacement therapy occupies established reimbursement pathways despite limited central nervous system penetration. Small molecule drugs represent an emerging pipeline category where chaperone compounds aim to stabilize residual enzyme function.
FDA orphan drug exclusivity provisions and EMA priority medicines designation reshape clinical trial investment timelines for developers pursuing Krabbe disease indications. The EU AI Act and FDA guidance on gene therapy manufacturing impose validation standards that filter market access to capitalized sponsors. Stakeholders must monitor regulatory convergence between the FDA's accelerated approval framework and EMA's adaptive pathways to anticipate pivotal trial design requirements.
Market Dynamics
Gene therapy manufacturing capacity is concentrating among academic medical centers with transplant infrastructure, creating supply bottlenecks that reshape competitive positioning across enzyme replacement and stem cell modalities.
Growth Catalysts
- FDA orphan drug exclusivity:Seven-year market exclusivity provisions incentivize developers to pursue ultra-rare indications despite small addressable populations.
- Newborn screening expansion:State-level mandates in New York, Illinois, and Missouri identify presymptomatic infants eligible for early intervention protocols.
- EMA priority medicines pathway:Accelerated assessment timelines compress regulatory review from 210 to 150 days for qualifying therapies.
Market Restraints
- Vector manufacturing scarcity:Lentiviral vector production concentrates at three contract manufacturing organizations in the United States and Europe.
- Blood-brain barrier penetration failure:Intravenous enzyme replacement achieves less than one percent central nervous system bioavailability.
- Reimbursement fragmentation:Medicaid state-level variation creates access disparities for gene therapy candidates across jurisdictions.
Strategic Opportunities
- Chaperone small molecules:Pharmacological stabilizers targeting residual GALC enzyme function offer oral delivery alternatives to invasive modalities.
- Japan's SAKIGAKE designation:Priority review and dedicated consultation pathways accelerate first-in-country approvals for innovative therapies.
- Direct-to-treatment-center distribution:Bypassing wholesale channels reduces cold chain handoffs for temperature-sensitive biologics.
Industry Challenges
- Gene therapy manufacturing workforce:Viral vector production requires specialized cell culture expertise concentrated at limited training programs.
- Long-term follow-up infrastructure:Fifteen-year post-treatment monitoring obligations strain pediatric specialty clinic capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Krabbe Disease Treatment Market |
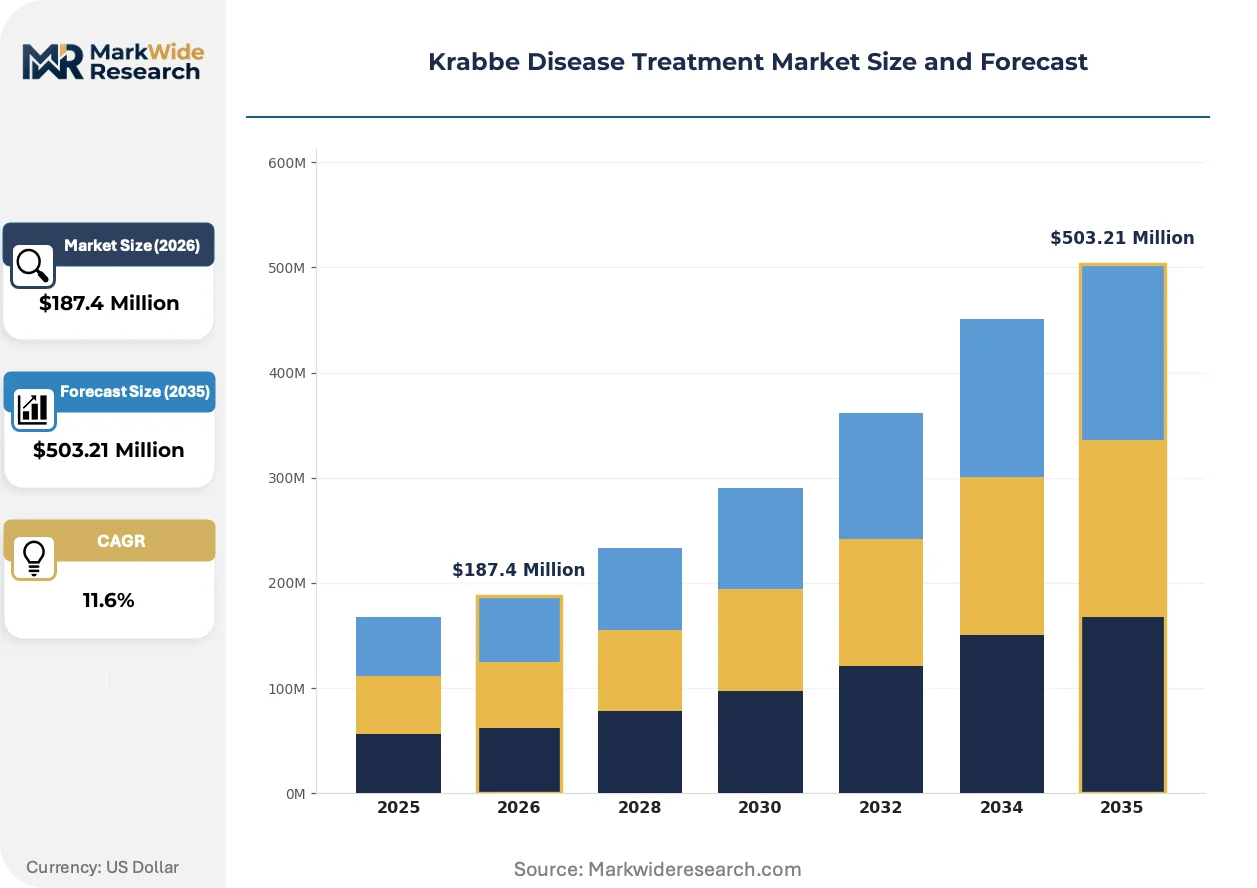
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Small Molecule Drugs, Supportive Care Application: Pediatric Treatment, Symptomatic Management, Clinical Trials, Research & Development End User: Hospitals, Clinics, Research Institutions, Home Care Providers Delivery Mode: Intravenous, Subcutaneous, Oral, Intrathecal |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., AbbVie Inc., Acorda Therapeutics Inc., Sanofi-Aventis SA, Johnson & Johnson Services Inc., GlaxoSmithKline Plc, Orchard Therapeutics, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Krabbe Disease Treatment Market Strategic Shifts
Intrathecal delivery systems are reshaping therapeutic administration routes, while regulatory frameworks adapt to one-time curative modalities that defy traditional reimbursement structures.
Next-generation AAV vectors are fragmenting the gene therapy landscape. These engineered capsids achieve enhanced blood-brain barrier crossing compared to first-generation serotypes. Academic medical centers in Pittsburgh, Milan, and Osaka are adopting the platform for early-phase trials. The technology is fragmenting procurement patterns as hospitals build in-house vector production capabilities rather than relying on external suppliers.
The EU AI Act imposes validation requirements on gene therapy manufacturing algorithms used for quality control and batch release. Developers must document training data provenance and model interpretability for regulatory submissions. European sponsors are responding by segregating AI-dependent processes from traditional analytical methods to maintain fallback compliance pathways.
Hospital pharmacy committees are consolidating purchasing authority for ultra-orphan therapies. Previously decentralized procurement at individual clinician discretion is yielding to centralized value assessment boards that evaluate cost-per-quality-adjusted-life-year. This concentration is most visible in German university hospitals where gene therapy access now requires ethics committee pre-authorization.
Krabbe Disease Treatment Market Segmentation
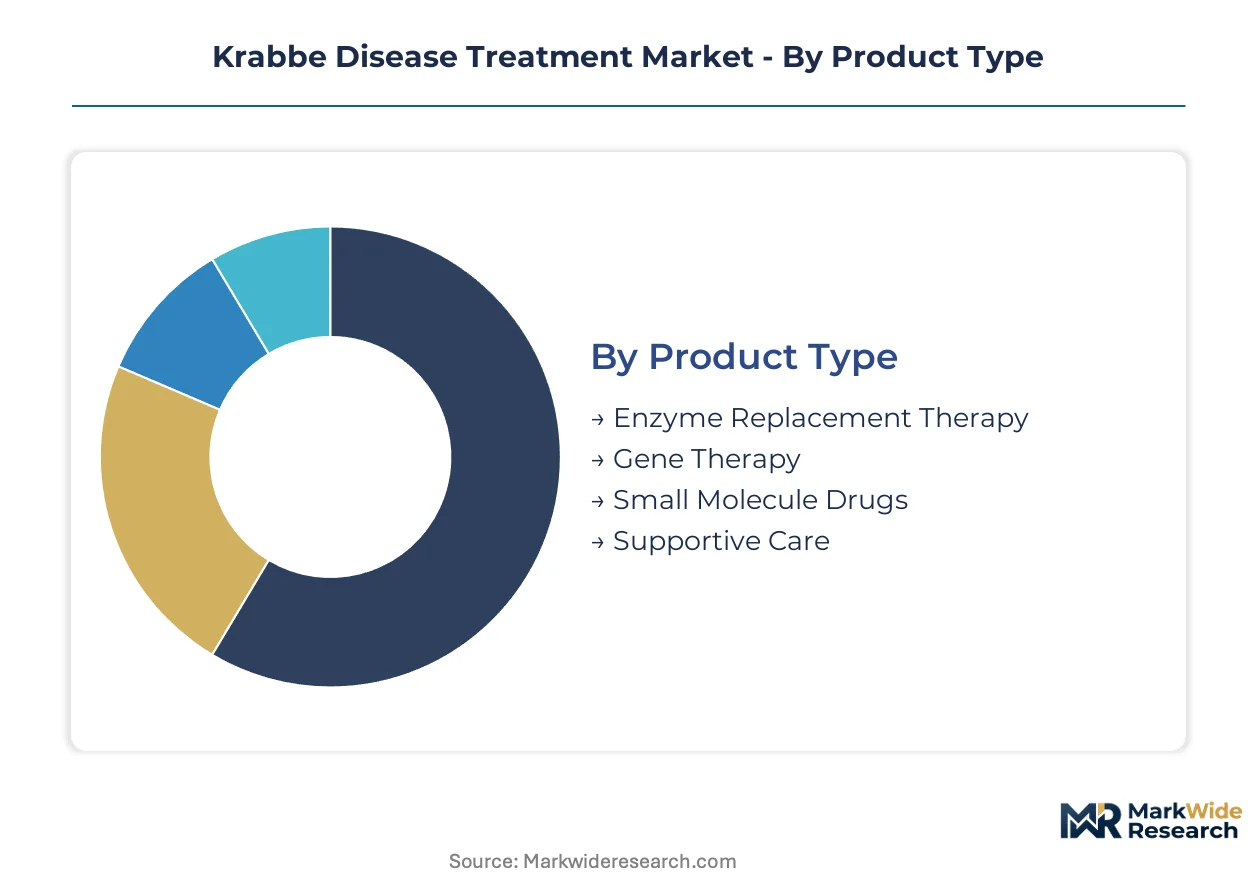
Treatment modality segmentation determines procurement pathways, with gene therapy concentrating at academic transplant centers while enzyme replacement flows through broader hospital networks. Channel configuration directly shapes manufacturer go-to-market strategy and reimbursement negotiation leverage.
Product Type:
Channel-mix varies sharply across modalities: gene therapy requires transplant-capable centers with specialized pharmacy infrastructure, while supportive care distributes through standard wholesale channels.
- Gene Therapy:Lentiviral vector-based hematopoietic stem cell gene therapy delivers corrected GALC enzyme through one-time infusion. Procurement concentrates at Pittsburgh, Milan, and Osaka academic medical centers with in-house vector production capabilities and dedicated pediatric transplant units.
- Enzyme Replacement Therapy:Intravenous recombinant enzyme formulations require cold chain distribution to hospital infusion centers. Demand flows through specialty pharmacy networks serving states with newborn screening mandates, where presymptomatic infant identification drives early treatment initiation.
- Small Molecule Drugs:Oral pharmacological chaperones target residual enzyme stabilization.
- Supportive Care:Symptom management therapies including anticonvulsants and nutritional support.
By volume, enzyme replacement leads. By growth pace, gene therapy is expanding most quickly.
Application:
Cost tier stratification separates curative interventions from chronic management, with pediatric presymptomatic treatment commanding premium pricing against symptomatic palliative protocols.
- Pediatric Treatment:Newborn screening-identified infants receive hematopoietic stem cell transplantation or gene therapy before neurological damage manifests. New York, Illinois, and Missouri state mandates create concentrated demand pools eligible for early intervention.
- Symptomatic Management:Late-infantile and juvenile onset patients receive supportive care focused on seizure control, mobility preservation, and nutritional maintenance. Demand concentrates in tertiary pediatric neurology centers across Germany, Japan, and the United States.
- Clinical Trials:Natural history studies and interventional protocols recruit presymptomatic newborns and early symptomatic patients.
- Research & Development:Preclinical programs span next-generation AAV vectors and blood-brain barrier penetration technologies.
By patient volume, symptomatic management dominates. By value concentration, pediatric treatment is gaining share fastest.
End User:
Customer type determines purchasing authority structure, with hospital pharmacy committees consolidating decision-making previously dispersed across individual clinicians.
- Hospitals:Academic medical centers with transplant infrastructure anchor gene therapy procurement. German university hospitals now require ethics committee pre-authorization for ultra-orphan therapy access, centralizing value assessment through cost-per-quality-adjusted-life-year frameworks.
- Clinics:Community pediatric neurology practices manage supportive care and enzyme replacement monitoring. Medicaid state-level reimbursement variation creates access disparities across United States jurisdictions.
- Research Institutions:Early-phase vector manufacturing and natural history data collection.
- Home Care Providers:Post-transplant monitoring and palliative symptom management.
By treatment value, hospitals capture the majority. By expansion rate, research institutions show the steepest trajectory.
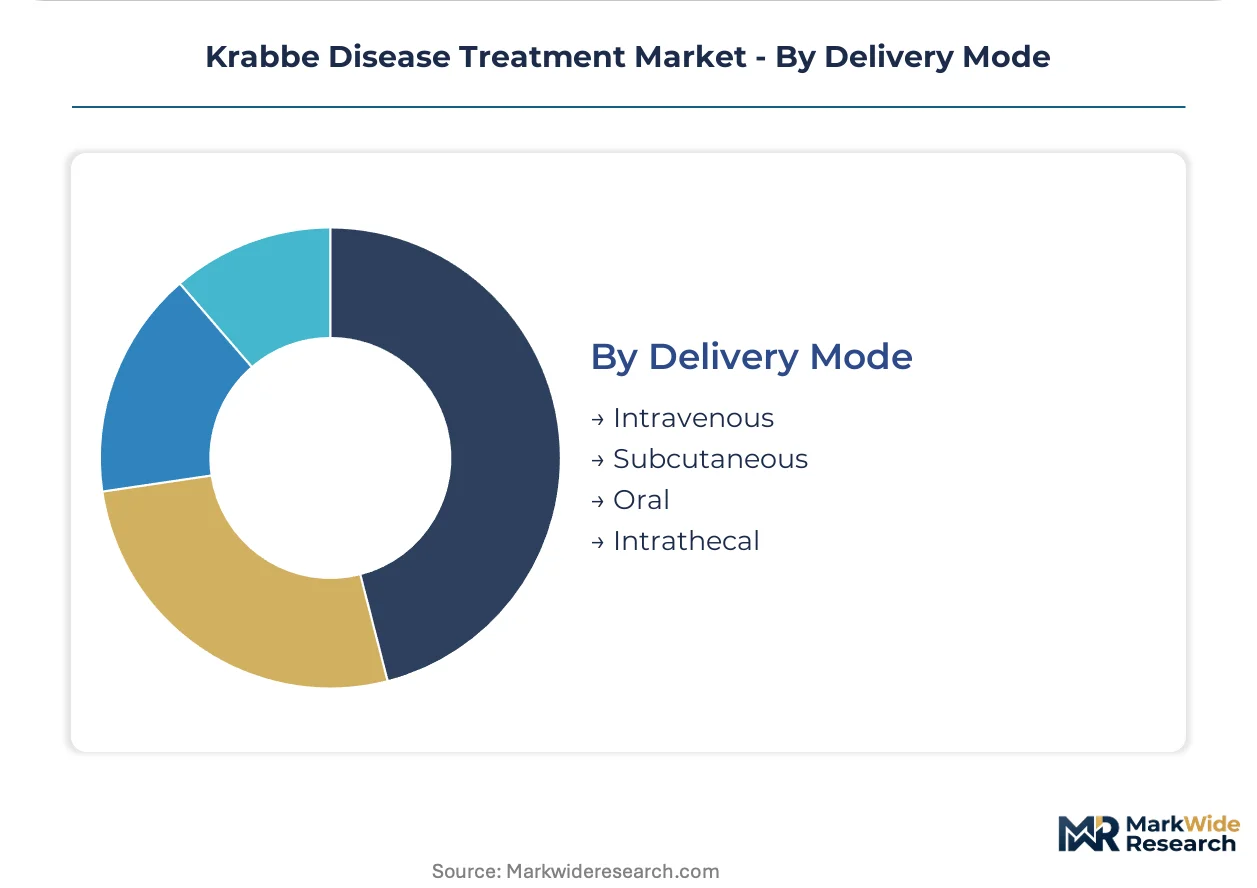
Delivery Mode:
Supply concentration for intrathecal and intravenous routes reflects manufacturing complexity, with lentiviral vector production bottlenecked at three contract manufacturing organizations in the United States and Europe.
- Intrathecal:Direct cerebrospinal fluid delivery bypasses blood-brain barrier limitations that constrain intravenous enzyme replacement to less than one percent central nervous system bioavailability. Administration requires specialized neurosurgical or interventional radiology capacity at quaternary centers.
- Intravenous:Standard infusion protocols for enzyme replacement distribute through hospital outpatient departments and specialty infusion centers. Cold chain requirements limit direct-to-treatment-center distribution models.
- Subcutaneous:Emerging depot formulations for sustained enzyme release.
- Oral:Small molecule chaperones enable non-invasive administration.
By procedure volume, intravenous administration leads. By capability investment, intrathecal delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pittsburgh-to-Milan vector manufacturing corridor anchors intercontinental supply chains for hematopoietic stem cell gene therapies. Specialized cold chain logistics networks connect newborn screening laboratories to academic transplant centers across three continents. Regulatory divergence between FDA accelerated approval and EMA adaptive pathways shapes regional clinical trial placement.
United States
New York, Illinois, and Missouri state mandates drive presymptomatic infant identification through expanded newborn screening panels. FDA orphan drug exclusivity provisions incentivize developers to pursue ultra-rare indications despite limited addressable populations. Pittsburgh and Boston academic medical centers concentrate lentiviral vector manufacturing capabilities and dedicated pediatric transplant infrastructure.
Germany
German university hospitals anchor European gene therapy procurement through centralized value assessment boards evaluating cost-per-quality-adjusted-life-year. EMA priority medicines pathway compresses regulatory review timelines from 210 to 150 days for qualifying therapies. The EU AI Act imposes validation requirements on manufacturing algorithms used for quality control and batch release at facilities in Munich and Heidelberg.
Japan
Japan's SAKIGAKE designation offers priority review and dedicated consultation pathways accelerating first-in-country approvals for innovative therapies. PMDA regulatory frameworks accommodate one-time curative modalities that defy traditional reimbursement structures. Osaka academic medical centers adopt next-generation AAV vector platforms for early-phase trials with enhanced blood-brain barrier crossing capabilities.
United Kingdom
NHS specialized commissioning frameworks concentrate ultra-orphan therapy access at designated supraregional centers in London and Manchester. The MHRA operates recognition routes for FDA and EMA approvals that streamline market entry for gene therapy developers. Cambridge and Oxford research clusters advance preclinical programs spanning chaperone small molecules and blood-brain barrier penetration technologies.
Krabbe Disease Treatment Market Competitive Environment
Concentration sits with large-cap biopharmaceuticals possessing captive viral vector manufacturing networks and hematopoietic stem cell processing infrastructure. The competitive structure fragments across three tiers: integrated multinationals with repurposed CAR-T facilities, mid-cap gene therapy specialists with platform technologies, and emerging chaperone developers pursuing oral delivery alternatives. Dominant competitive moves include strategic partnerships for vector manufacturing capacity and geographic expansion into Japan's SAKIGAKE pathway.
Among integrated biopharmaceuticals, Pfizer Inc., Novartis AG, and Orchard Therapeutics occupy positions spanning enzyme replacement, repurposed CAR-T infrastructure, and dedicated gene therapy platforms respectively. These entities exemplify the capital requirements for lentiviral vector production and long-term post-treatment monitoring infrastructure. Their market presence anchors procurement relationships with academic medical centers in Pittsburgh, Milan, and Osaka where transplant capabilities concentrate.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Acorda Therapeutics Inc. |
| Sanofi-Aventis SA |
| Johnson & Johnson Services Inc. |
| GlaxoSmithKline Plc |
| Orchard Therapeutics |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Next-generation AAV vector adoption is displacing lentiviral platforms in early-phase trials, simultaneously concentrating supply geography around Pittsburgh, Milan, and Osaka academic medical centers while fragmenting pricing power across competing delivery modalities. This substitution dynamic reshapes procurement economics as hospitals build in-house vector production capabilities rather than relying on external contract manufacturing organizations.
Pricing Analysis
Volume-discount tiering structures separate one-time curative gene therapy interventions from chronic enzyme replacement protocols, with transplant-capable academic medical centers commanding preferential pricing through consolidated purchasing authority. Price differentiation hinges on blood-brain barrier penetration efficacy and cold chain complexity, with intrathecal delivery formats carrying premium positioning against intravenous alternatives. Cost compression in enzyme replacement segments is intensifying because newborn screening expansion creates identifiable presymptomatic infant cohorts eligible for early intervention. Medicaid state-level reimbursement variation renders community pediatric neurology practices most price-sensitive, while German university hospital ethics committees demonstrate lowest sensitivity through centralized value assessment frameworks.
Supply Chain Analysis
The United States and Germany anchor lentiviral vector manufacturing, with Japan emerging as a production hub for next-generation AAV capsids engineered for enhanced central nervous system delivery. Raw material dependencies center on plasmid DNA, specialized cell culture media, and GMP-grade reagents sourced from limited qualified suppliers. Single-source vulnerability concentrates at three contract manufacturing organizations controlling viral vector production capacity across North America and Europe. Distribution runs through direct-to-treatment-center models for temperature-sensitive biologics, bypassing wholesale channels to reduce cold chain handoffs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in Krabbe disease treatment are reaching an inflection point as hematopoietic stem cell gene therapy platforms achieve interoperability with CAR-T manufacturing infrastructure, enabling incumbent biopharmaceuticals to repurpose existing capital deployment.
For Market Incumbents: Consolidate manufacturing capacity through captive viral vector networks and hematopoietic stem cell processing infrastructure to defend against mid-cap gene therapy specialists with platform technologies. Prioritize backward integration into lentiviral vector production to reduce dependency on the three dominant contract manufacturing organizations. Secure long-term procurement relationships with Pittsburgh, Milan, and Osaka academic medical centers where transplant capabilities concentrate purchasing authority. For New Entrants and Emerging Players: Japan's SAKIGAKE designation offers priority review and dedicated consultation pathways for first-in-country approvals, creating accessible regulatory fast-tracks for innovative therapies targeting ultra-orphan indications. Target oral pharmacological chaperone development as the most penetrable modality, bypassing invasive administration requirements that constrain enzyme replacement and gene therapy adoption. Pursue direct-to-treatment-center distribution partnerships to reduce cold chain complexity and accelerate commercial traction. For Investors and Strategic Acquirers: FDA's accelerated approval framework for gene therapies reshapes the acquisition landscape by compressing development timelines and validating platform economics for one-time curative modalities. Focus on mid-cap gene therapy specialists with demonstrated lentiviral vector manufacturing capabilities and established relationships with academic transplant centers. Watch for EMA-FDA regulatory convergence on adaptive pathway requirements as the signal indicating platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Natural history studies in New York, Illinois, and Missouri newborn screening programs generate regulatory-grade efficacy data. |
| Regulatory Approval Pathway | EMA priority medicines designation compresses review timelines from standard 210-day windows. |
| Manufacturing Scale-Up | In-house vector production capabilities at Pittsburgh and Milan centers reduce dependency on external suppliers. |
| Pipeline Diversification | Chaperone small molecule programs target residual enzyme stabilization with oral delivery advantages. |
| Reimbursement Strategy | Medicaid state-level harmonization efforts address access disparities across United States jurisdictions. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration across primary interview cycles and secondary validation protocols. Sources included FDA orphan drug filings, EMA priority medicines submissions, ClinicalTrials.gov interventional protocols, and hospital formulary databases. Bottom-up patient flow modeling and top-down market sizing triangulated volume and value estimates across treatment modalities.
Consistency checks validated outputs against external benchmarks including newborn screening mandate expansion timelines and academic medical center transplant capacity disclosures. Segmentation dimensions encompassed treatment modality, patient population stratification, delivery route, and regional regulatory cluster. CAGRs were derived from patient identification rates, treatment initiation patterns, and pricing evolution across the projection horizon. Forecast inputs incorporated vector manufacturing capacity constraints and long-term follow-up infrastructure limitations.
Underlying assumptions cover regulatory pathway stability, newborn screening mandate continuity, and vector manufacturing scale-up feasibility, with deviation risk concentrated in reimbursement fragmentation and blood-brain barrier penetration technology advances. Forecasts reflect documented assumptions with acknowledged sensitivity to EMA-FDA regulatory divergence and AI Act validation requirement implementation. Recalibration cycles align with material shifts in newborn screening policy, vector manufacturing capacity expansion, and gene therapy platform approval milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Menkes Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Von Hippel-Lindau Market