
 UAE Dental Devices Market | 2026-2036
UAE Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Dental Devices Market Outlook
Market Context
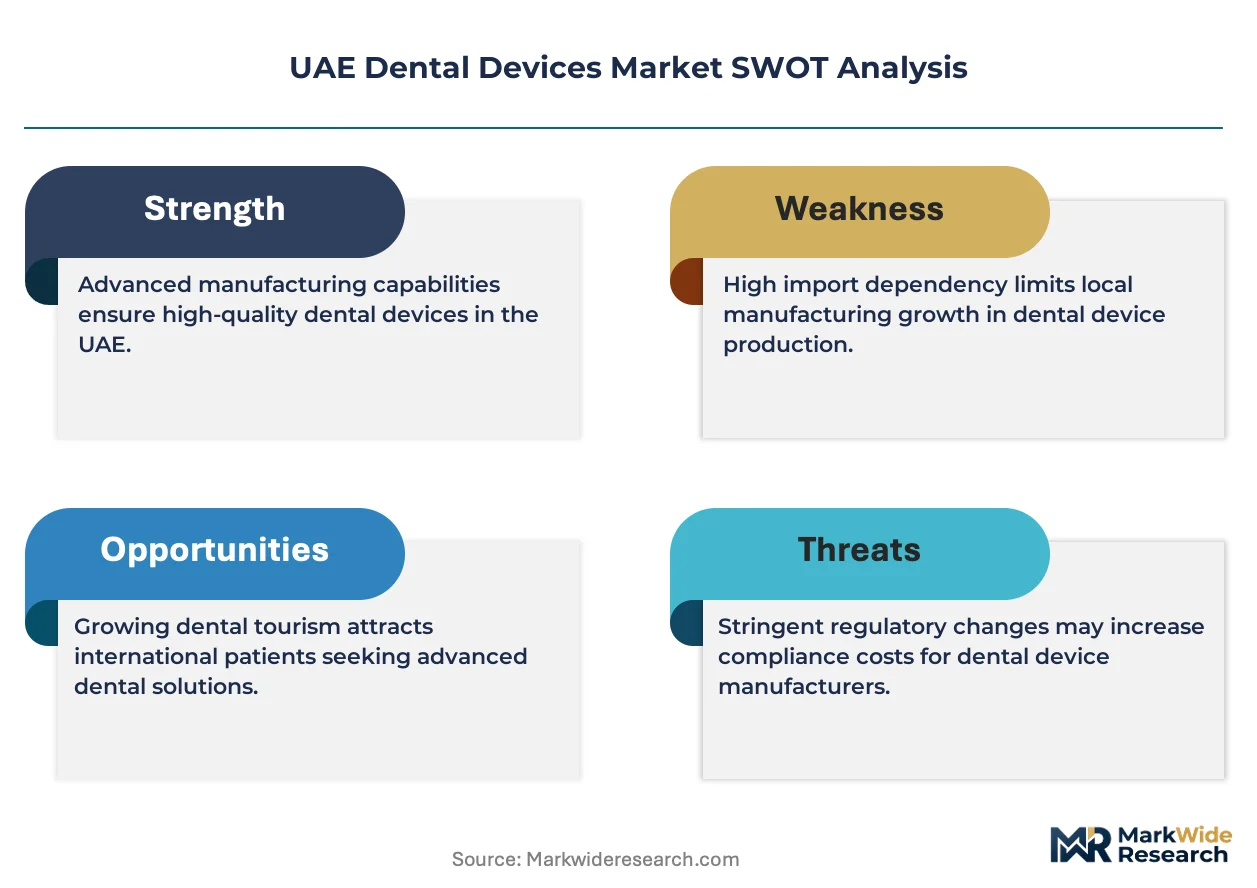
Domestic dental laboratory manufacturing capacity across the Emirates is broadening as free-zone incentives attract precision equipment suppliers. Straumann Holding AG leverages its implantology heritage to anchor premium positioning in Abu Dhabi's specialist clinics. Dentsply Sirona sustains broad portfolio coverage across restorative and digital dentistry segments. Zimmer Biomet competes through orthopedic-to-dental technology transfer and strong hospital system relationships.
Technical Definition and Segments
Dental devices comprise electromechanical instruments, prosthetic components, diagnostic imaging systems, and consumable materials engineered to ISO 6875 biocompatibility standards for intraoral use, primarily serving tooth restoration, alignment correction, and oral disease treatment. The product-type dimension shows implants capturing sustained margin pools due to titanium-zirconium alloy innovation and guided-surgery protocols, while CAD/CAM technology within the technology segment leads volume expansion as chairside milling reduces laboratory turnaround. Digital imaging displaces conventional radiography fastest among technology categories, driven by cone-beam computed tomography adoption for implant planning.
Regulatory Framework
The UAE Ministry of Health and Prevention, through the Drug and Medical Products Regulation Department, enforces medical device registration and post-market surveillance that elevates import barriers for uncertified manufacturers. Dubai Health Authority facility licensing mandates equipment traceability and sterilization validation, shaping procurement criteria across private clinic networks. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks and decide whether to pursue unified certification or maintain separate national regulatory strategies.
Market Dynamics
Chairside digital workflows are compressing laboratory turnaround times across Dubai and Abu Dhabi, forcing distributors to reconfigure inventory models around same-day prosthetic delivery rather than batch shipments from European manufacturing hubs.
Growth Catalysts
- Jebel Ali Free Zone incentives:Customs duty exemptions and full foreign ownership provisions attract precision milling equipment suppliers to cluster near Dubai's logistics corridor, reducing landed costs for CAD/CAM hardware.
- MOHAP registration mandates:The Drug and Medical Products Regulation Department's quality thresholds filter out uncertified imports, elevating margin pools for compliant manufacturers with established UAE dossiers.
- Cone-beam CT adoption:Specialist implantology clinics in Abu Dhabi are replacing panoramic radiography with three-dimensional imaging systems, expanding addressable equipment spend per practice.
Market Restraints
- Titanium-zirconium alloy input costs:Premium implant raw materials face price volatility tied to aerospace sector demand, squeezing gross margins on high-end prosthetic components.
- European supply concentration:Precision milling burs and sintering furnaces depend on German and Swiss original equipment manufacturers, creating single-source vulnerability for UAE distributors.
- ISO 6875 biocompatibility testing timelines:Extended validation periods for novel ceramic formulations delay product registration with MOHAP, compressing effective patent windows.
Strategic Opportunities
- Northern Emirates penetration:Sharjah and Ras Al Khaimah present underdeveloped clinic density relative to Dubai, offering first-mover positioning for equipment financiers.
- AI-powered implant planning:Machine learning algorithms integrated with CBCT datasets enable automated surgical guide generation, converging diagnostic and prosthetic workflows.
- Dubai Healthcare City licensing fast-track:Streamlined facility approvals for specialized dental centers create captive demand for bundled equipment-software-service packages.
Industry Challenges
- Digital dentistry technician scarcity:CAD/CAM design and 3D printing operation skills lag equipment installation rates, forcing clinics to outsource or delay workflow integration.
- Legacy sterilization infrastructure:Older Dubai clinic facilities require capital-intensive retrofitting to meet Dubai Health Authority traceability mandates for instrument tracking systems.
- Interoperability fragmentation:Proprietary scanner file formats block seamless data exchange between competing chairside milling units and third-party laboratory management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Dental Devices Market |
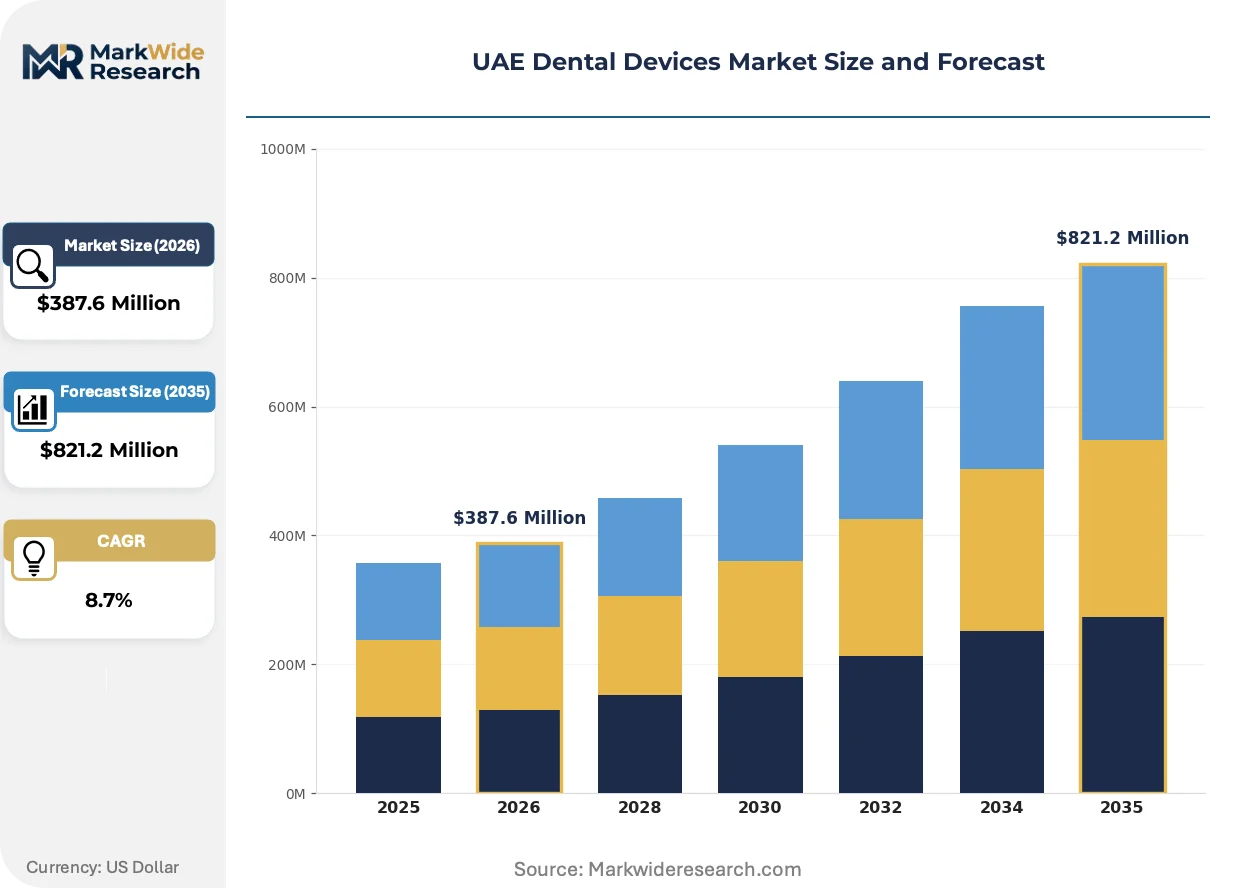
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Orthodontics, Handpieces, Crowns End User: Clinics, Hospitals, Dental Schools, Laboratories Application: Restorative Dentistry, Cosmetic Dentistry, Prosthodontics, Periodontics Technology: Laser Dentistry, CAD/CAM, 3D Printing, Digital Imaging |
| Companies Covered | Straumann Holding AG, Zimmer Biomet, Dentsply Sirona, Planmeca, Carestream Dental, 3M Company, Ivoclar Vivadent AG, Zircon Medical Equipment, Envista Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Dental Devices Market Strategic Shifts
Intraoral scanning and chairside manufacturing are collapsing the traditional laboratory intermediary, redistributing value capture toward clinics with capital deployment capacity and technical staff depth.
Intraoral scanners equipped with photogrammetry arrays are unifying impression-taking and digital model generation into a single chairside procedure. Specialist practices in Dubai Healthcare City are adopting these systems at replacement-cycle velocity, compressing the conventional two-visit crown protocol into same-day delivery and eliminating physical impression material costs entirely.
MOHAP's post-market surveillance requirements are tightening adverse-event reporting obligations for imported dental implants. Manufacturers must now maintain local technical files and complaint-handling infrastructure, raising compliance overhead but creating regulatory moats against gray-market competitors lacking UAE establishment representation.
Clinic procurement committees are consolidating vendor relationships around full-arch solution providers rather than best-of-breed component sourcing. This concentration favors distributors with integrated implant-abutment-prosthetic portfolios and in-country technical training capacity, particularly visible among Abu Dhabi's hospital-affiliated dental centers seeking simplified supply chain management.
UAE Dental Devices Market Segmentation
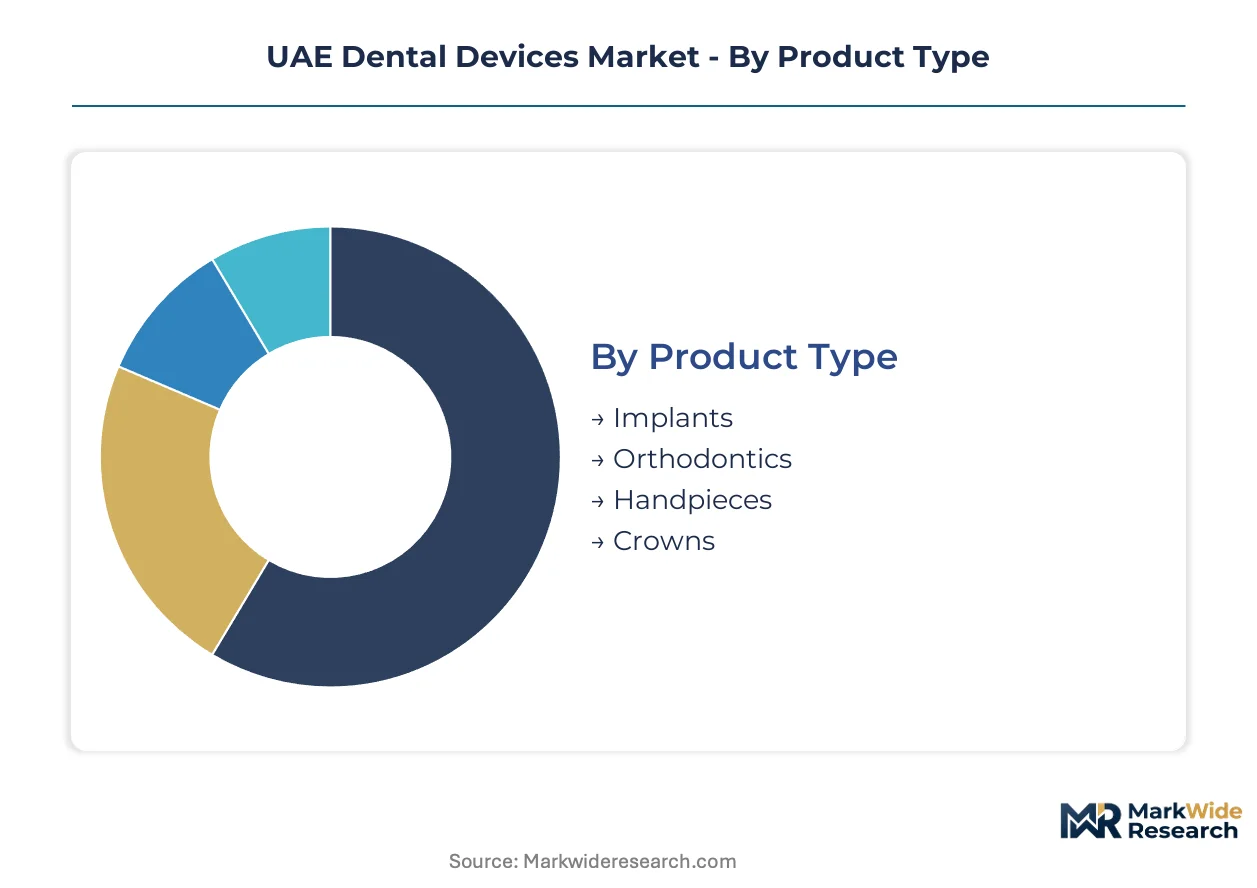
Segmentation reveals how procurement patterns split across clinical settings and technical workflows in the Emirates. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor strategy.
Product Type:
Supply concentration clusters around titanium alloy sourcing corridors through Jebel Ali, with premium positioning commanding dedicated distribution channels.
- Implants:Titanium-zirconium alloy fixtures with surface-etched osseointegration interfaces dominate Abu Dhabi specialist clinics. Dubai Healthcare City implantology centers absorb high-unit-value guided-surgery kits bundled with surgical planning software.
- Orthodontics:Clear aligner systems and lingual bracket technologies serve Dubai's cosmetic dentistry demand. MOHAP registration requirements for biocompatible polymers filter import competition, elevating margin pools for established dossier holders.
- Handpieces:High-speed turbine and electric motor instruments with fiber-optic illumination.
- Crowns:Zirconia and lithium disilicate prosthetic components for chairside milling integration.
Implants absorb the bulk of installed capacity; orthodontics is expanding most quickly.
End User:
Customer type determines procurement sophistication, with facility licensing tier dictating equipment specification ceilings and service contract structures.
- Clinics:Private dental clinics across Dubai and Abu Dhabi drive CAD/CAM hardware installation. Jebel Ali Free Zone proximity reduces landed costs for precision milling equipment, compressing payback periods for chairside digital workflows.
- Hospitals:Hospital-affiliated dental centers in Abu Dhabi consolidate vendor relationships around full-arch solution providers. Dubai Health Authority traceability mandates shape sterilization infrastructure procurement.
- Dental Schools:Training institutions requiring simulation units and educational instrument sets.
- Laboratories:Domestic manufacturing capacity expansion in free zones serving outsourced prosthetic production.
Clinics command the highest equipment spend per outlet; laboratories are gaining share fastest amid chairside workflow displacement.
Application:
Application segmentation tracks how clinical specialization concentrates equipment procurement around procedure-specific technology stacks.
- Restorative Dentistry:Crown, bridge, and filling procedures utilizing composite resins and ceramic systems. Dubai clinic networks prioritize same-day delivery protocols, compressing laboratory intermediary roles.
- Cosmetic Dentistry:Veneer, whitening, and aesthetic alignment services targeting premium patient segments. Abu Dhabi specialist centers bundle imaging, design, and manufacturing into single-visit workflows.
- Prosthodontics:Full and partial denture fabrication with implant-supported prosthetics.
- Periodontics:Gum disease treatment and soft tissue management instrumentation.
Restorative applications absorb the bulk of installed capacity; cosmetic dentistry is climbing the fastest amid medical tourism positioning.
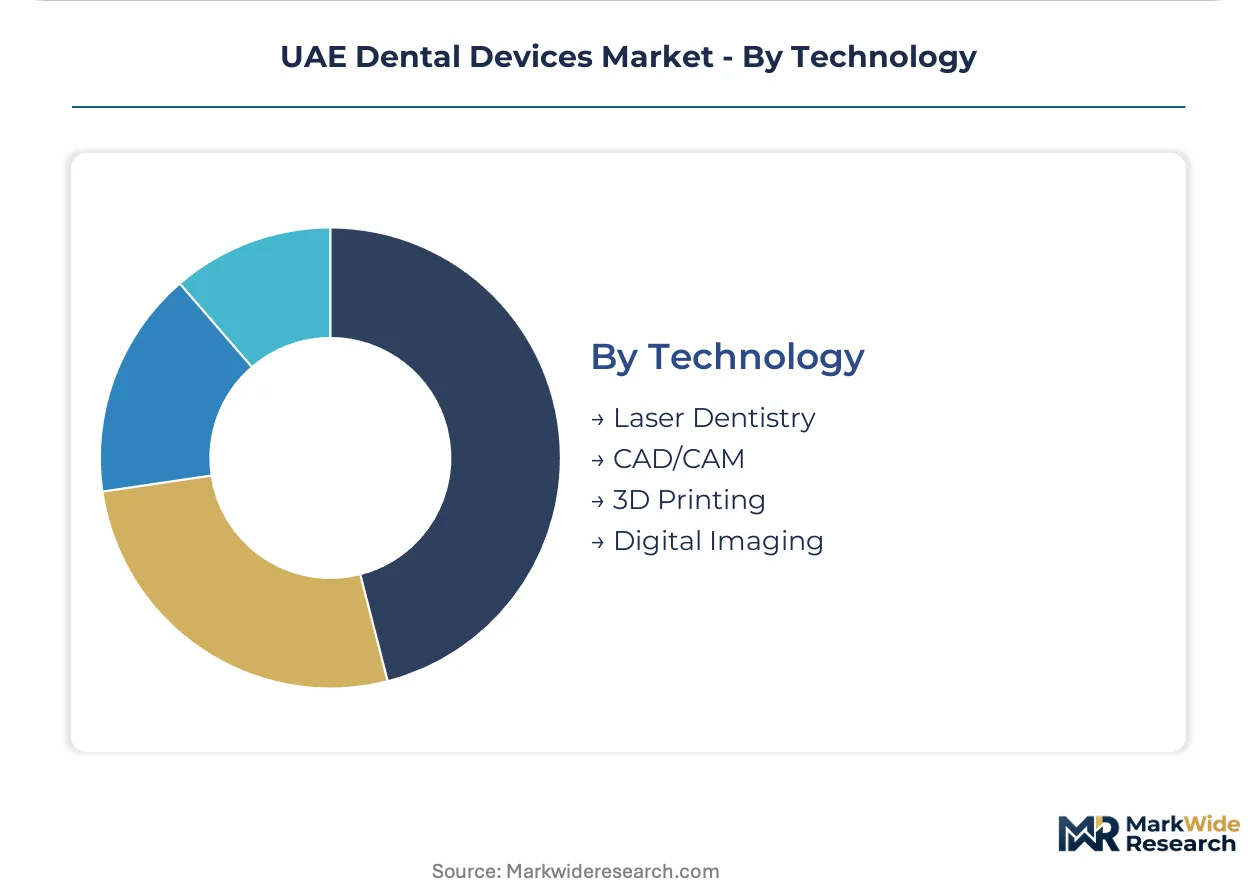
Technology:
Technology segmentation captures the displacement velocity of digital systems against conventional mechanical and chemical methods.
- CAD/CAM:Computer-aided design and manufacturing systems integrating intraoral scanning with chairside milling. Dubai Healthcare City licensing fast-track creates captive demand for bundled equipment-software-service packages.
- Digital Imaging:Cone-beam computed tomography and panoramic radiography systems. Specialist implantology clinics in Abu Dhabi are replacing two-dimensional radiography with three-dimensional imaging for surgical planning.
- Laser Dentistry:Soft and hard tissue laser systems for precision cutting and disinfection.
- 3D Printing:Photopolymer and metal sintering systems for surgical guide and model fabrication.
CAD/CAM absorbs the bulk of installed capacity; digital imaging is gaining share fastest through CBCT replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium-zirconium alloy feedstock flows through Jebel Ali's bonded warehousing corridors anchor procurement economics across the Emirates. Dubai Healthcare City and Abu Dhabi's specialist clusters concentrate demand for precision-milled prosthetics and guided-surgery systems.
Dubai
Private dental clinics in Dubai Healthcare City and Jebel Ali Free Zone drive CAD/CAM hardware installation at replacement-cycle velocity. Dubai Health Authority facility licensing mandates equipment traceability and sterilization validation, elevating procurement thresholds. Jebel Ali's customs duty exemptions attract precision milling equipment suppliers, reducing landed costs for chairside digital workflows.
Abu Dhabi
Hospital-affiliated dental centers in Abu Dhabi consolidate vendor relationships around full-arch solution providers with integrated implant-abutment-prosthetic portfolios. MOHAP registration requirements under the Drug and Medical Products Regulation Department filter uncertified imports, elevating margin pools for compliant manufacturers. Specialist implantology clinics in the capital are replacing panoramic radiography with cone-beam CT systems for surgical planning.
Sharjah
Sharjah presents underdeveloped clinic density relative to Dubai, offering first-mover positioning for equipment financiers targeting mid-market dental practices. The emirate's healthcare regulator enforces facility licensing standards aligned with federal MOHAP quality thresholds. Industrial zones near Sharjah International Airport are attracting domestic dental laboratory manufacturing capacity serving outsourced prosthetic production.
Northern Emirates
Ras Al Khaimah and Fujairah exhibit nascent specialist clinic infrastructure with concentrated demand for basic restorative equipment and consumable materials. Federal MOHAP registration mandates apply uniformly across these emirates, creating compliance barriers for gray-market distributors. Free zone development authorities in Ras Al Khaimah are targeting precision equipment suppliers with land cost advantages versus Dubai and Abu Dhabi.
UAE Dental Devices Market Competitive Environment
Global majors compete with regional champions across technology licensing and distribution reach, producing a tiered structure where premium implantology portfolios anchor one vector and digital workflow bundling anchors another. The vendor base separates into three strategic archetypes: full-solution providers with integrated hardware-software-service offerings, implantology specialists leveraging surface-etching intellectual property, and regional distributors with MOHAP-registered dossiers and local technical training infrastructure. Dominant competitive moves include portfolio diversification into AI-powered surgical planning software and geographic expansion through Dubai Healthcare City licensing fast-track partnerships.
Within the premium-tier implantology segment, Straumann Holding AG and Zimmer Biomet occupy positions defined by titanium-zirconium alloy heritage and orthopedic-to-dental technology transfer respectively. Dentsply Sirona exemplifies the full-solution archetype through broad restorative and digital dentistry coverage. These Swiss and US-origin entities anchor competitive positioning through established MOHAP registration dossiers and in-country technical file maintenance capabilities that create regulatory moats against emerging competitors lacking UAE establishment representation.
| Leading Market Players |
|---|
| Straumann Holding AG |
| Zimmer Biomet |
| Dentsply Sirona |
| Planmeca |
| Carestream Dental |
| 3M Company |
| Ivoclar Vivadent AG |
| Zircon Medical Equipment |
| Envista Holdings |
| Others |
Value Chain & Pricing Dynamics
MOHAP sterilization validation mandates gate qualified supply access and premium-tier pricing eligibility for imported dental devices across the Emirates. Clinics lacking compliant instrument tracking infrastructure face procurement exclusion, while distributors with validated cold-chain capabilities command service-bundling premiums that reshape margin capture toward logistics-integrated vendors.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier implant suppliers from unbundled equipment traders in Dubai Healthcare City. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 6875 certification grade and after-sales technical support depth. Cost compression in economy handpieces intensifies as Jebel Ali Free Zone inventory holders compete on landed cost alone. Hospital-affiliated dental centers in Abu Dhabi exhibit lowest price sensitivity due to consolidated vendor relationships, while independent Sharjah clinics prioritize capital expenditure minimization.
Supply Chain Analysis
Domestic-content incentives in Ras Al Khaimah Economic Zone are reshaping sourcing patterns for precision milling equipment assembly. German and Swiss OEMs anchor upstream supply for CAD/CAM hardware and sintering furnaces, while titanium-zirconium alloy feedstock feeds from aerospace sector corridors. Single-source vulnerability concentrates in ceramic milling burs and photopolymer resins. Distribution runs through Jebel Ali bonded warehousing with last-mile clinic delivery by MOHAP-registered distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where MOHAP registration dossier requirements force gray-market distributors toward exit or acquisition. Surviving vendors will capture expanded margin pools as compliant supply concentrates.
For Market Incumbents: Extend technical training infrastructure across Abu Dhabi hospital systems to deepen switching costs against emerging competitors. Acquire MOHAP-registered dossiers from distressed regional distributors to consolidate import licensing capacity. Surface-etching IP holders like Straumann must defend against orthopedic-to-dental technology transfer from Zimmer Biomet by accelerating AI-powered surgical guide development.
For New Entrants and Emerging Players: Capture Sharjah and Ras Al Khaimah clinic financing demand where incumbent coverage remains thin. Target mid-market practices seeking chairside digital workflow entry without Dubai-tier capital deployment. Partner with Jebel Ali Free Zone precision equipment assemblers for reduced landed cost positioning against European direct imports.
For Investors and Strategic Acquirers: Dubai Healthcare City licensing fast-track approvals for specialized dental centers is the leading indicator that bundled equipment-software-service demand is accelerating. Long-term viability favors full-arch solution providers with integrated implant-abutment-prosthetic portfolios and in-country technical file maintenance. Watch CBCT replacement velocity in Abu Dhabi specialist clinics as the signal for diagnostic imaging consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Dossier Acquisition | Consolidates import licensing capacity and filters gray-market competition from UAE distribution. |
| AI-Powered Surgical Planning Software Development | Converges diagnostic and prosthetic workflows for Abu Dhabi implantology centers. |
| Jebel Ali Free Zone Manufacturing Footprint | Reduces landed costs for CAD/CAM hardware serving Dubai clinic replacement cycles. |
| Hospital System Partnership Consolidation | Captures Abu Dhabi full-arch solution demand through simplified procurement relationships. |
| Technical Training Infrastructure Expansion | Addresses CAD/CAM technician scarcity delaying chairside workflow integration. |
Study Parameters
Document review covered MOHAP medical device registration filings, Dubai Health Authority facility licensing records, and Jebel Ali Free Zone trade statistics, complemented by interviews with dental clinic procurement managers, biomedical engineers at hospital-affiliated centers, GPO contracts managers, and precision equipment distributors. Secondary validation drew from customs import data, ISO certification registries, and cone-beam CT installation tracking. Bottom-up clinic equipment spend estimates triangulated against top-down market value reconstruction.
Segment-level outputs across the projection horizon reflect modeled splits by product type, end-user facility tier, application specialization, and technology adoption velocity. CAGRs derived from equipment replacement cycle analysis, clinic expansion pipeline tracking, and digital workflow penetration curves. Forecast inputs incorporated MOHAP registration timeline assumptions and Dubai Healthcare City licensing approval rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Gulf Cooperation Council regulatory harmonization progress and titanium-zirconium alloy aerospace demand fluctuations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
China Dental Implants Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Dental CAD Market