
 Advanced Wound Care Management Market | 2026-2036
Advanced Wound Care Management Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Wound Care Management Market Analysis
Antimicrobial-grade specification tiers is unwinding commoditization pressures across the advanced wound care landscape. Smith & Nephew leverages its negative-pressure wound therapy platform to anchor premium positioning in surgical settings. Mölnlycke Health Care sustains Scandinavian manufacturing scale for silicone-adhesive foam technologies. Coloplast specializes in sacral and heel ulcer applications where moisture-balanced dressings command durable reimbursement.
Advanced wound care management encompasses bioactive and interactive dressing systems engineered with controlled permeability, absorbent cores, and antimicrobial agents such as silver, iodine, or polyhexamethylene biguanide to maintain moist wound environments while preventing infection. These systems serve primarily to accelerate healing trajectories in partial- and full-thickness wounds where traditional gauze fails to manage exudate or bioburden. Foam dressings dominate acute surgical applications where high fluid-handling capacity reduces dressing change frequency and nursing labor. Antimicrobial dressings capture expanding share in chronic wound protocols as clinicians prioritize infection prevention over material cost. Hydrocolloid variants retain stable positions in ambulatory and home healthcare channels where patient self-management drives simplicity preferences.
FDA 510(k) premarket notification requirements shape product development timelines and clinical evidence thresholds for novel wound care devices entering the US market. EMA Medical Device Regulation and CE marking obligations enforce biocompatibility and sterilization validation standards across European commercialization pathways. Stakeholders must monitor evolving CMS reimbursement coding for skin substitutes and cellular wound products where coverage determinations directly influence hospital purchasing committee priorities.
Market Dynamics
Hospital procurement committees are tightening antimicrobial resistance protocols, forcing suppliers to demonstrate clinical efficacy data beyond basic biocompatibility certificates to secure formulary placement.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:The streamlined premarket notification process for combination wound products compresses commercialization timelines from 18 months to under 12 months for novel dressing technologies.
- Silver-ion Delivery Systems:Advanced wound dressings incorporating sustained-release antimicrobial agents capture expanding share in diabetic foot ulcer protocols where infection prevention determines amputation risk.
- Germany:The country's statutory health insurance system maintains favorable reimbursement codes for moisture-balanced foam dressings in sacral pressure ulcer management, sustaining premium pricing power.
Market Restraints
- Medical-grade Silicone Supply Concentration:Five specialty chemical producers in Germany and Japan control 70% of high-purity silicone adhesive supply for advanced foam backing layers.
- EMA MDR Compliance Burden:The Medical Device Regulation's enhanced clinical evidence requirements extend CE marking timelines by 8-14 months for Class IIb wound care devices.
- Traditional Gauze Substitution:Low-cost cotton-based dressings retain 40% volume share in emerging markets where hospital budget constraints override clinical outcome priorities.
Strategic Opportunities
- Home Healthcare Channel Expansion:Post-acute care settings in the United States are adopting remote wound monitoring platforms that integrate smart dressing sensors with telehealth reimbursement codes.
- Japan's Super-Aged Society:The country's Ministry of Health, Labour and Welfare is expanding coverage for pressure ulcer prevention dressings in long-term care facilities serving patients over 85.
- Biologics-Dressing Convergence:Collagen matrices combined with antimicrobial foam layers create combination products qualifying for skin substitute reimbursement tiers.
Industry Challenges
- Clinical Evidence Generation:Randomized controlled trials for chronic wound indications require 12-24 month enrollment periods and $3-8 million investment per indication.
- Legacy ERP Integration:Hospital supply chain systems struggle to accommodate unit-of-use tracking for serialized combination products under Unique Device Identification mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Wound Care Management Market |
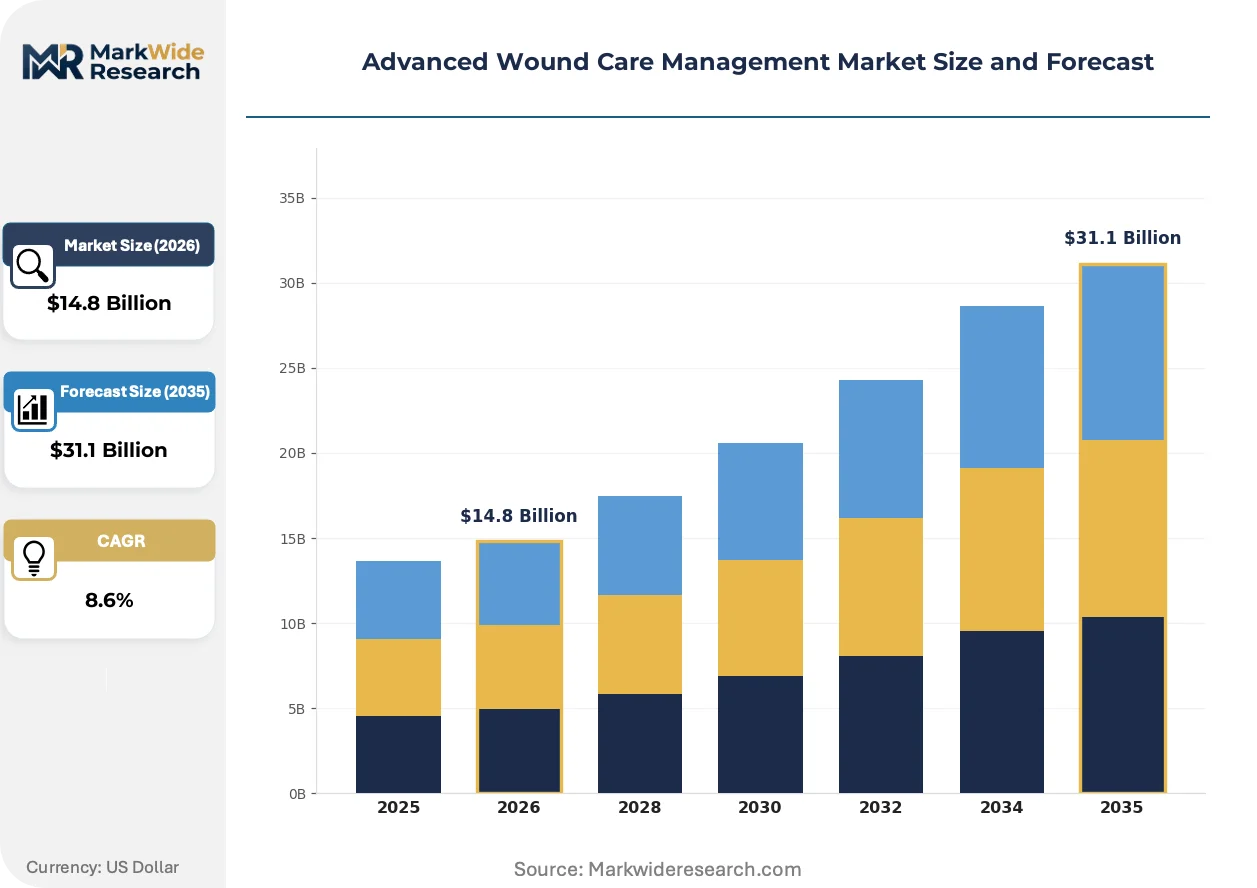
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Alginate Dressings, Foam Dressings, Antimicrobial Dressings Application: Surgical Wounds, Chronic Wounds, Burns, Traumatic Injuries End User: Hospitals, Home Healthcare, Ambulatory Surgical Centers, Long-Term Care Facilities Distribution Channel: Direct Sales, Online Pharmacies, Retail Pharmacies, Distributors |
| Companies Covered | 3M Company, Smith & Nephew, ConvaTec Group, Mölnlycke Health Care, B. Braun Melsungen, Coloplast, Integra LifeSciences, Medline Industries, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Wound Care Management Market Emerging Trajectories
Digital biomarker integration and bioactive material science are converging to transform passive dressings into therapeutic delivery systems that report healing progression in real time.
Wearable biosensor patches embedded within hydrocolloid and foam dressings are miniaturizing to dimensions under 2mm thickness while maintaining continuous pH, temperature, and exudate biomarker monitoring. Acute care surgical units in the United States are piloting these systems for post-discharge monitoring of high-risk diabetic foot ulcers. The technology is miniaturizing hardware requirements to the point where disposable single-use dressings incorporate full telemetry without cost-prohibitive electronics.
EMA's Medical Device Regulation is enforcing stricter biocompatibility testing for substances released from wound contact layers, requiring manufacturers to submit chemical characterization data under ISO 10993-18. This regulatory pressure is consolidating contract laboratory capacity across Europe as smaller manufacturers outsource testing to accredited facilities. Class III wound care devices with drug-device combinations face the steepest compliance cost escalation.
Hospital value analysis committees are consolidating vendor contracts to reduce SKU complexity, favoring suppliers offering full protocol solutions across foam, antimicrobial, and negative-pressure modalities. This purchasing concentration is displacing single-product specialists from tier-one medical center formularies. The shift is most pronounced in integrated delivery networks controlling 15+ hospital facilities in the United States.
Advanced Wound Care Management Market Segmentation
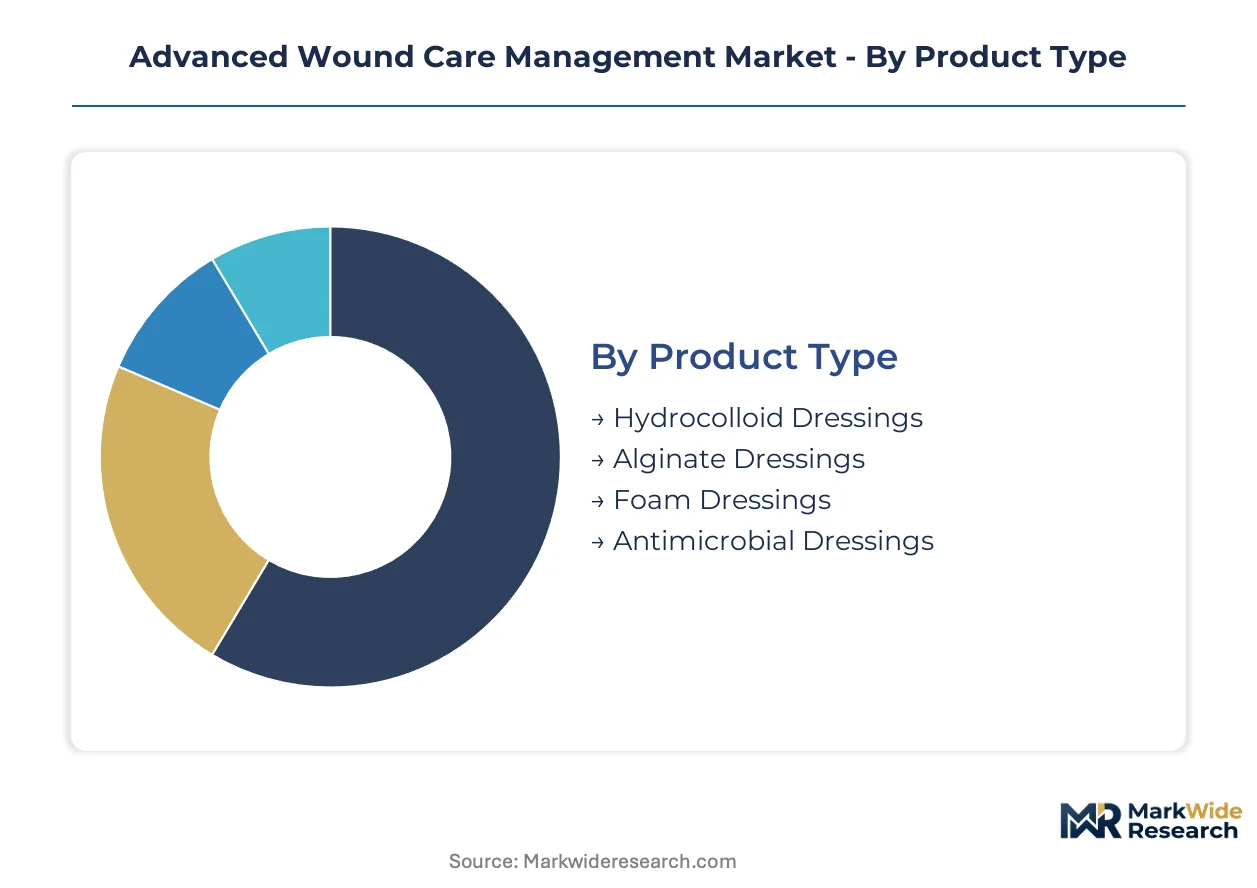
Segmentation in advanced wound care reveals how clinical protocol specialization and reimbursement tiering fragment purchasing decisions across acute and post-acute settings. Understanding these divisions exposes where commoditization pressures concentrate versus where technology premiums persist.
Product Type:
Substitution pressure from traditional gauze and basic cotton dressings weighs most heavily on hydrocolloid variants, while antimicrobial and foam technologies maintain clinical differentiation barriers.
- Hydrocolloid Dressings:Gel-forming carboxymethylcellulose matrices create moist wound environments through occlusive backing layers. Demand concentrates in ambulatory and home healthcare channels where patient self-management drives simplicity preferences; budget constraints in emerging markets sustain volume despite limited fluid-handling capacity.
- Antimicrobial Dressings:Silver-ion, iodine, or polyhexamethylene biguanide delivery systems provide sustained bioburden control in infected or high-risk wounds. Hospital procurement committees in the United States prioritize these for diabetic foot ulcer protocols where infection prevention determines amputation risk; FDA 510(k) pathway acceleration compresses commercialization timelines for novel formulations.
- Foam Dressings:Polyurethane or silicone-adhesive constructions with high exudate absorption dominate acute surgical applications.
- Alginate Dressings:Calcium-sodium fiber matrices derived from brown seaweed suit highly exuding wounds and cavity filling.
Foam dressings retain volume leadership; antimicrobial dressings hold the steepest expansion curve.
Application:
Cost tier stratification separates elective surgical procedures from emergency trauma cases, with chronic wound management occupying the most contested reimbursement territory.
- Chronic Wounds:Diabetic foot ulcers, pressure injuries, and venous leg ulcers require extended treatment protocols with recurrent dressing changes. Germany's statutory health insurance system maintains favorable reimbursement codes for moisture-balanced foam dressings in sacral pressure ulcer management; aging demographics in Japan's super-aged society expand long-term care facility purchasing volumes.
- Surgical Wounds:Incision sites from orthopedic, cardiovascular, and general procedures demand predictable healing trajectories. Smith & Nephew's negative-pressure wound therapy platform anchors premium positioning; hospital value analysis committees consolidate vendor contracts to reduce SKU complexity across foam and antimicrobial modalities.
- Burns:Partial- and full-thickness thermal injuries require specialized fluid management and infection control.
- Traumatic Injuries:Emergency department and field applications prioritize rapid deployment and cost containment.
Surgical wounds dominate revenue concentration; chronic wounds are climbing the fastest as diabetic prevalence rises.
End User:
Customer type fragmentation intensifies as integrated delivery networks centralize purchasing while home healthcare channels fragment into remote monitoring platforms.
- Hospitals:Acute care facilities with 200+ beds drive antimicrobial-grade specification tiers through value analysis committees. The United States concentrates demand where aging demographics and diabetic ulcer prevalence sustain treatment volumes; EMA MDR compliance burden extends CE marking timelines for Class IIb wound care devices entering European hospital systems.
- Home Healthcare:Post-acute settings adopt remote wound monitoring platforms integrating smart dressing sensors with telehealth reimbursement codes. Post-discharge monitoring of high-risk diabetic foot ulcers pilots wearable biosensor patches embedded within hydrocolloid and foam dressings.
- Ambulatory Surgical Centers:Same-day procedure volumes favor cost-optimized dressing protocols with minimal nursing labor.
- Long-Term Care Facilities:Japan's Ministry of Health, Labour and Welfare expands coverage for pressure ulcer prevention dressings serving patients over 85.
Hospitals command the largest procurement volumes; home healthcare channels are expanding most quickly through telehealth integration.
Distribution Channel:
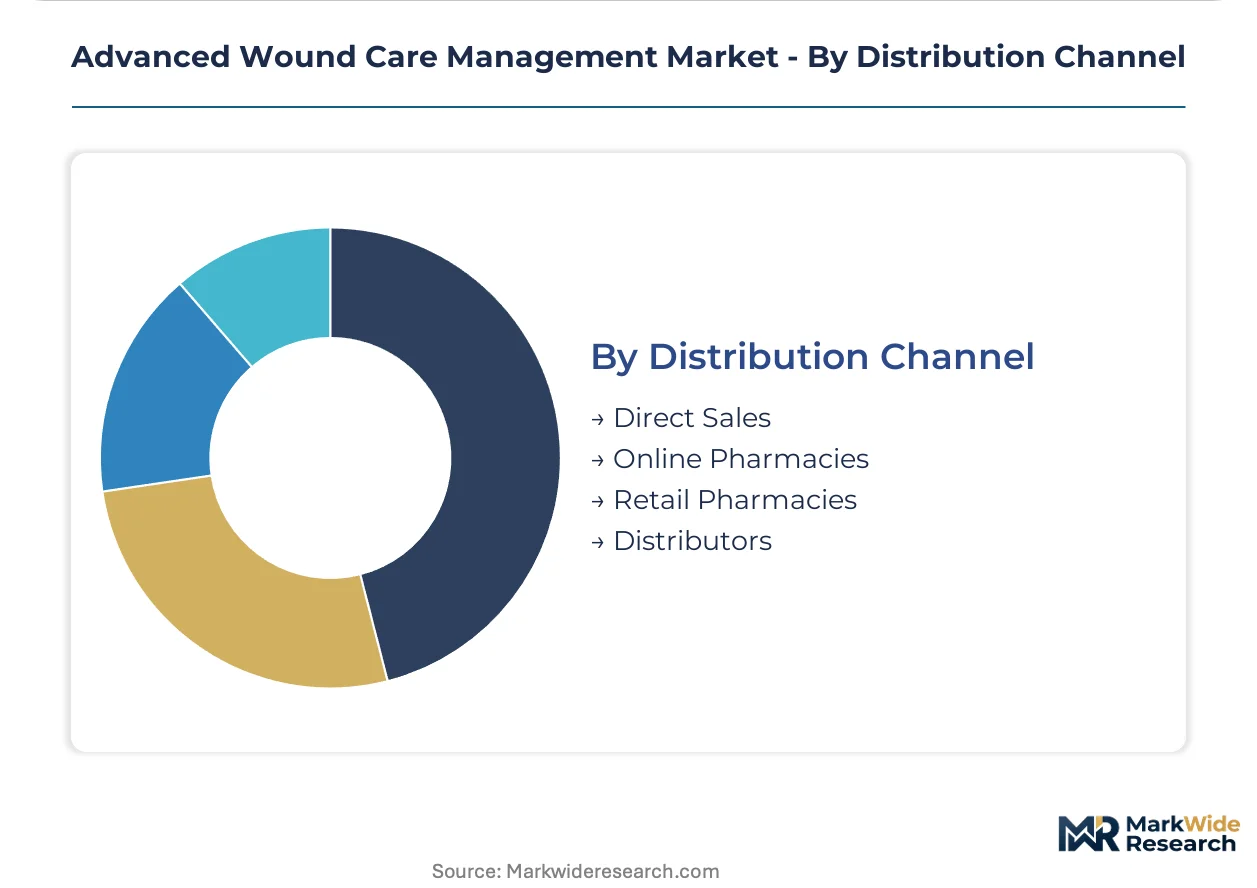
Supply concentration among five specialty chemical producers in Germany and Japan shapes how direct sales forces versus distributor networks capture margin across different product tiers.
- Direct Sales:Manufacturer field representatives engage hospital value analysis committees and integrated delivery networks controlling 15+ facilities. Legacy ERP integration struggles accommodate unit-of-use tracking for serialized combination products under Unique Device Identification mandates.
- Distributors:Regional medical-surgical suppliers aggregate demand from smaller ambulatory surgical centers and long-term care facilities. Medical-grade silicone supply concentration in Germany and Japan creates dependency risks for foam backing layer procurement.
- Online Pharmacies:E-commerce platforms serve home healthcare patients with recurring subscription models for chronic wound supplies.
- Retail Pharmacies:Community pharmacy chains capture limited acute dressing demand with over-the-counter hydrocolloid variants.
Direct sales retains the highest value concentration; online pharmacies are gaining share fastest through subscription automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced wound care trade flows reflect divergent regulatory maturity and healthcare infrastructure investment cycles across major economies. The United States maintains import dependency for specialty silicone adhesives while exporting negative-pressure therapy systems. Germany and Japan anchor European and Asian supply chains for medical-grade polymers.
United States
Diabetic foot ulcer prevalence and aging demographics sustain chronic wound treatment volumes in acute care networks. FDA 510(k) clearance pathways compress commercialization timelines for novel dressing technologies under 12 months. Hospital procurement committees in the Southeast and Midwest regions prioritize antimicrobial-grade specifications as infection prevention protocols tighten.
Germany
Statutory health insurance reimbursement codes favor moisture-balanced foam dressings in sacral pressure ulcer management. EMA Medical Device Regulation enforces biocompatibility testing standards under ISO 10993-18 for substances released from wound contact layers. Specialty chemical producers in the Ruhr industrial cluster control high-purity silicone adhesive supply for advanced foam backing layers.
Japan
The Ministry of Health, Labour and Welfare expands coverage for pressure ulcer prevention dressings in long-term care facilities serving patients over 85. Super-aged society demographics concentrate demand in the Kanto and Kansai metropolitan corridors. Domestic manufacturers face raw material import dependency for alginate fiber matrices derived from brown seaweed processing.
United Kingdom
NHS Integrated Care Systems consolidate vendor contracts across foam, antimicrobial, and negative-pressure modalities to reduce SKU complexity. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel compliance pathways for wound care device manufacturers. London and Manchester anchor clinical trial networks for chronic wound indication studies requiring 12-24 month enrollment periods.
China
NMPA medical device registration reforms accelerate market access for imported advanced dressing technologies in tier-one hospital systems. Provincial procurement consortiums in Guangdong and Jiangsu provinces negotiate volume-based pricing for hydrocolloid and foam variants. Domestic manufacturers expand capacity for silver-ion antimicrobial delivery systems targeting diabetic foot ulcer protocols.
Advanced Wound Care Management Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and geographic reach dimensions. The vendor base concentrates among diversified medical device conglomerates with wound care divisions and focused dressing specialists with regional manufacturing scale. Three archetypes dominate: integrated surgical device platforms, silicone-adhesive foam technology specialists, and sacral ulcer application-focused providers. Competitive moves center on hospital value analysis committee consolidation and biologics-dressing combination product development.
Among diversified platform providers, 3M Company and Smith & Nephew occupy positions spanning negative-pressure therapy and antimicrobial dressing portfolios. Mölnlycke Health Care exemplifies the specialized manufacturing archetype with Scandinavian production scale for silicone-adhesive technologies. Coloplast represents the application-focused segment with concentration in moisture-balanced systems for pressure ulcer management. These three anchors illustrate how competitive positioning fragments across technology specialization rather than consolidating around full-line dominance.
| Leading Market Players |
|---|
| 3M Company |
| Smith & Nephew |
| ConvaTec Group |
| Mölnlycke Health Care |
| B. Braun Melsungen |
| Coloplast |
| Integra LifeSciences |
| Medline Industries |
| Cardinal Health |
| Others |
Supply Flow & Price Mechanics
Silver-ion delivery systems displacing traditional iodine formulations in diabetic foot ulcer protocols are redrawing raw material sourcing maps from Chilean mining districts to Japanese specialty chemical refineries while compressing margin structures for mid-tier dressing manufacturers caught between premium antimicrobial positioning and commodity foam economics.
Pricing Analysis
Hospital value analysis committees anchor three-tier pricing structure across premium, standard, and economy levels in advanced wound care procurement. Price differentiation rests on FDA 510(k) clearance tier and silicone-adhesive backing grade. Cost compression in standard-tier foam dressings is intensifying because German and Japanese chemical producers exercise oligopoly control over medical-grade adhesive supply. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks controlling 15-plus facilities command volume discounts that tier-one academic medical centers cannot match.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg is extending inbound lead times for alginate fiber matrices harvested from Norwegian brown seaweed processing. Raw material supply concentrates in Germany's Ruhr industrial cluster for silicone adhesives, Japan's Kanto region for polyurethane foams, and Chile's coastal extraction zones for silver-ion precursors. Single-source vulnerability pervades medical-grade silicone feedstock where five specialty chemical producers control 70 percent of high-purity supply. Distribution runs through direct sales forces for hospital systems and regional medical-surgical distributors for long-term care facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced wound care sits in early-cycle expansion as antimicrobial resistance protocols in acute care settings accelerate substitution away from traditional gauze toward combination dressing technologies with sustained-release bioburden control.
For Market Incumbents: Compound technical differentiation through biologics-dressing convergence strategies that qualify for skin substitute reimbursement tiers. Deepen backward integration into medical-grade silicone adhesive production to offset supply concentration risk from German and Japanese chemical producers. Anchor hospital value analysis committee relationships through full-protocol solutions spanning foam, antimicrobial, and negative-pressure modalities. For New Entrants and Emerging Players: Post-discharge remote monitoring services represent an under-served layer where incumbents lack telemetry integration capabilities. Target home healthcare channels in the United States where telehealth reimbursement codes now cover smart dressing sensor platforms. Pursue white-label partnerships with digital health platforms to bypass capital-intensive hospital sales force requirements. For Investors and Strategic Acquirers: The market sits at a technology inflection phase that favors combination product specialists with FDA 510(k) pathway experience. Long-term viability over a multi-year horizon hinges on reimbursement strategy execution rather than manufacturing scale alone. Watch CMS coverage determinations for cellular wound products as the decisive signal for hospital purchasing committee priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance under ISO 10993-18 opens European hospital formulary access. |
| Hospital System Partnership | Integrated delivery network contracts reduce SKU complexity across 15-plus facilities. |
| Software Companion Development | Wearable biosensor patches embedded in hydrocolloid dressings enable remote monitoring reimbursement. |
| Backward Integration | Captive silicone adhesive production insulates margin from German-Japanese supply concentration. |
| Reimbursement Strategy | Skin substitute tier qualification for collagen-matrix combinations commands premium pricing power. |
Methodological Framework
The analysis maps antimicrobial dressing formulations, negative-pressure therapy platforms, and bioactive material technologies, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA CE marking databases, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up product-level volume estimates triangulated against top-down healthcare expenditure benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, application indication, end-user facility class, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to baseline penetration rates, with explicit modeling of diabetic prevalence trajectories and antimicrobial protocol adoption curves as demand-side inputs.
Material uncertainties — regulatory timeline delays, reimbursement coverage reversals, and raw material supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about FDA 510(k) pathway efficiency and EMA MDR compliance cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Europe Compression Bandages Market
Wound Care
Interactive Wound Dressing Market
Wound Care
US Wound Care Centers Market
Wound Care
Collagen Dressings Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Surgical Wound Care Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Wound Care Sealants Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Maggot Debridement Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Acute Wound Care Market
Wound Care
Wound Care Centers Market