
 Speech Therapy Services Market | 2026-2036
Speech Therapy Services Market Size, Share, and Industry Trends Forecast 2026-2036
Speech Therapy Services Market Outlook
The capital-intensity divergence between telehealth platform operators and traditional brick-and-clinic providers is reorganizing competitive dynamics in speech therapy delivery. Benchmark Therapies leverages its school-district contracting infrastructure to sustain volume across multiple states. TinyEYE Therapy Services anchors its position through proprietary video-conferencing technology purpose-built for pediatric sessions. Humanus Corporation competes by staffing rural and underserved districts where in-person therapist recruitment lags.
Speech therapy services encompass assessment, diagnosis, and treatment of communication disorders including articulation, fluency, voice, and language processing impairments, typically delivered through structured sessions ranging from 30 to 60 minutes using standardized tools such as the Goldman-Fristoe Test of Articulation or the Clinical Evaluation of Language Fundamentals. The primary purpose spans developmental intervention in children, post-stroke rehabilitation in adults, and degenerative condition management in seniors. Teletherapy as a delivery mode is capturing the fastest expansion as broadband infrastructure and licensure compacts reduce geographic barriers, while individual therapy retains the largest revenue pool due to higher reimbursement rates and personalized care plans. Group therapy occupies a mature position within educational settings where cost efficiency drives district purchasing decisions.
The Centers for Medicare & Medicaid Services shapes demand through reimbursement schedules that determine provider participation, while state-level telehealth parity laws govern cross-border service eligibility and commercial insurance coverage. The FDA regulates software-as-medical-device claims for therapy apps and digital assessment tools, creating compliance thresholds for technology-enabled service models. Stakeholders must monitor evolving interstate licensure compacts and digital therapeutic classification decisions that will determine which platforms qualify for insurance reimbursement.
Market Dynamics
Telehealth parity statutes and interstate licensure compacts are dismantling geographic barriers to speech therapy delivery, redistributing provider capacity from saturated metropolitan corridors to underserved rural districts and cross-border jurisdictions.
Growth Catalysts
- Medicaid expansion in school-based health programs:State education agencies in Texas and California are embedding speech-language pathologists directly into district special-education teams, creating guaranteed reimbursement streams for contracted providers.
- ASHA's interstate compact ratification:The Audiology and Speech-Language Pathology Interstate Compact now enables licensed practitioners to practice across member states without redundant credentialing, accelerating telehealth workforce mobility.
- AI-powered articulation screening tools:Machine-learning algorithms analyzing phoneme production patterns are reducing initial assessment time by half, allowing clinicians to expand caseload capacity within existing session blocks.
Market Restraints
- Reimbursement rate compression from CMS:The 2024 Medicare Physician Fee Schedule reduced conversion factors for outpatient speech therapy by 3.4 percent, squeezing margins for independent practices dependent on fee-for-service revenue.
- Clinical workforce concentration in coastal states:Over 60 percent of ASHA-certified speech-language pathologists practice in California, New York, and Massachusetts, leaving interior states with persistent vacancy rates above 15 percent in rural counties.
- Proprietary assessment licensing costs:Publishers of standardized tools including the Goldman-Fristoe Test of Articulation and CELF-5 impose per-use digital fees that compound operational overhead for high-volume pediatric clinics.
Strategic Opportunities
- Underserved rural districts in the Mountain West:Wyoming, Montana, and Idaho school systems report speech-language pathologist vacancy rates exceeding 25 percent, creating procurement windows for telehealth-enabled contract providers with compact licensure.
- Adult neurogenic rehabilitation post-stroke:The aging demographic in Florida and Arizona is generating demand for intensive aphasia and cognitive-communication intervention that exceeds local inpatient rehabilitation capacity.
- Direct-to-employer occupational health contracts:Large self-insured employers in manufacturing and logistics sectors are adding speech therapy to on-site wellness benefits, bypassing traditional insurance preauthorization requirements.
Industry Challenges
- Telehealth platform interoperability with district student information systems:School-based providers must manually reconcile session documentation across incompatible electronic health record and individualized education plan platforms, consuming administrative hours that reduce billable clinical time.
- ASHA certification maintenance requirements:Practitioners must complete 30 continuing education hours every three years, with specialized coursework in dysphagia and augmentative communication commanding premium pricing and limited geographic availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speech Therapy Services Market |
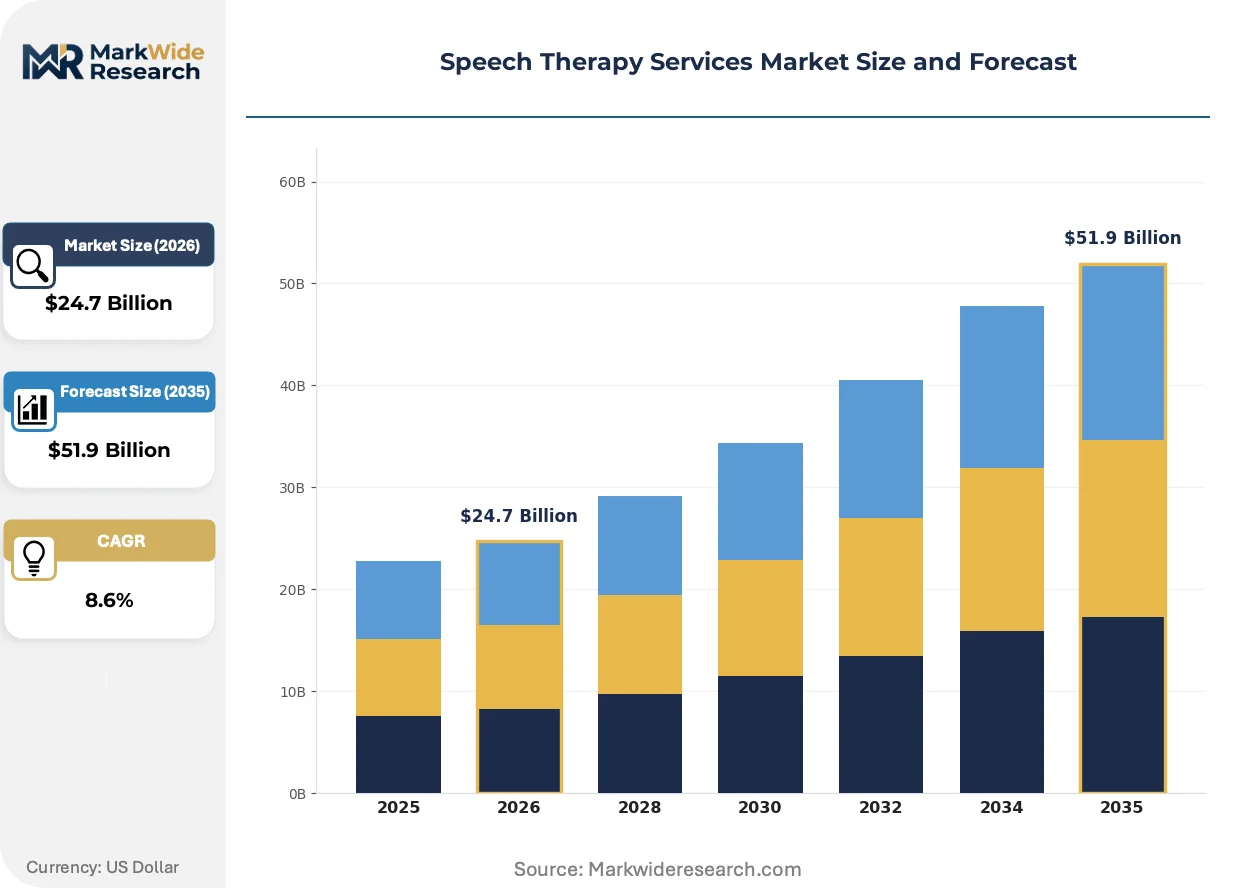
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Individual Therapy, Group Therapy, Teletherapy, Home Health Client Type: Children, Adults, Seniors, Special Needs Delivery Mode: In-person, Online, Hybrid, Mobile Funding Source: Insurance, Self-pay, Scholarships, Educational Grants |
| Companies Covered | Benchmark Therapies, Humanus Corporation, John McGivney Children's Centre, Smart Speech Therapy, Speech Plus, TinyEYE Therapy Services, EBS Healthcare, Reliant Rehabilitation, The Stepping Stones Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speech Therapy Services Market Strategic Shifts
Digital therapeutic platforms and asynchronous practice models are fragmenting the traditional synchronous session monopoly, enabling new service configurations that decouple assessment, intervention, and progress monitoring into modular, technology-mediated components.
Artificial intelligence-driven speech recognition engines trained on pediatric phoneme databases are supplanting manual transcription and real-time scoring during articulation drills. School-district telehealth providers in Texas are deploying these tools to automate homework assignments and parent progress reports. The technology is supplanting 15-20 minutes of previously clinician-led session time, compressing per-patient labor costs while maintaining documentation fidelity for Medicaid audit compliance.
The FDA's evolving software-as-medical-device framework is tightening validation requirements for therapy applications claiming diagnostic or treatment efficacy. Developers of digital articulation screening tools must now submit 510(k) premarket notifications demonstrating equivalence to predicate standardized assessments. Pediatric platform operators are responding by embedding clinical validation studies into product roadmaps, extending development timelines by 12-18 months but securing durable competitive moats against unvalidated competitors.
District procurement officers are consolidating vendor relationships through multi-year managed service agreements that bundle assessment, direct intervention, and indirect consultation under fixed per-pupil pricing. Texas Education Agency cooperative purchasing contracts now favor providers offering guaranteed response-time service level agreements over hourly-rate bidding. This behavioral shift is most visible in Houston and Dallas-Fort Worth independent school districts, where three-year contracts with telehealth-enabled vendors are displacing fragmented local staffing arrangements.
Speech Therapy Services Market Segmentation
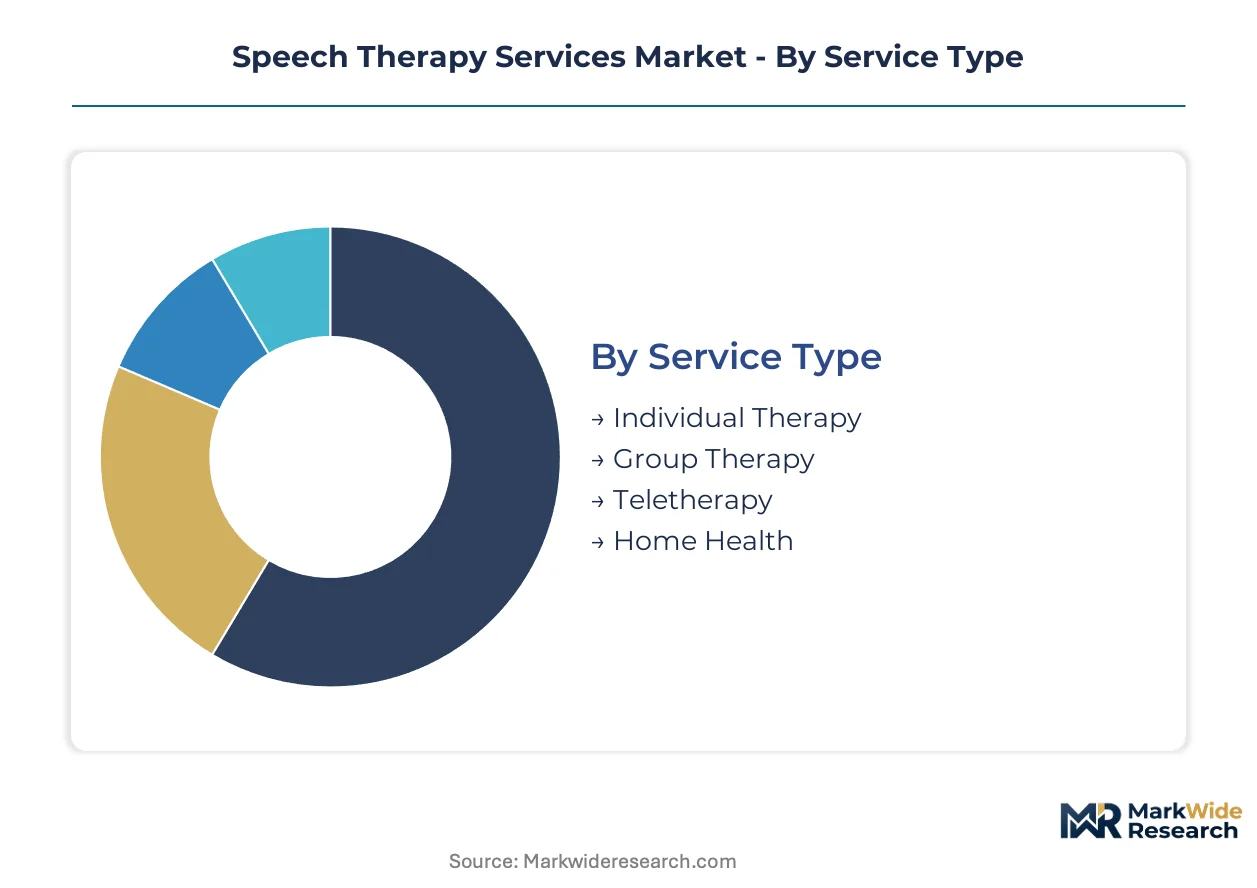
Speech therapy services fragment across four distinct dimensions that determine reimbursement pathways, operational infrastructure requirements, and competitive positioning. Understanding these segment boundaries reveals why telehealth operators and traditional clinic networks pursue fundamentally different capability investments.
Service Type:
Individual therapy flows through insurance-reimbursed outpatient channels, while group and teletherapy segments concentrate in school-district and direct-to-consumer pathways with diverging margin structures.
- Individual Therapy:One-on-one structured sessions lasting 30-60 minutes using standardized assessment tools like the Goldman-Fristoe Test of Articulation. Demand concentrates in Texas and California metropolitan corridors where CMS reimbursement rates sustain higher provider compensation.
- Group Therapy:Cost-efficient delivery to multiple clients simultaneously, predominantly deployed in educational settings where district purchasing decisions prioritize per-pupil economics over individualized attention.
- Teletherapy:Synchronous video-based intervention enabled by proprietary platforms and interstate licensure compacts, capturing expansion as broadband infrastructure penetrates rural districts.
- Home Health:Mobile clinician deployment to residential settings for post-stroke rehabilitation and degenerative condition management in aging populations.
By volume, individual therapy leads. By growth pace, teletherapy is climbing the fastest.
Client Type:
Pediatric cases dominate district-contracted volume, while adult and senior segments drive higher per-session reimbursement through Medicare and commercial insurance channels.
- Children:Developmental intervention addressing articulation, fluency, and language processing impairments, embedded directly into school-based special-education teams through state education agency contracts.
- Adults:Post-stroke rehabilitation and acquired neurogenic communication disorders, generating demand that exceeds inpatient rehabilitation capacity in Florida and Arizona.
- Seniors:Degenerative condition management including aphasia and cognitive-communication intervention, reimbursed through Medicare Physician Fee Schedule schedules.
- Special Needs:Augmentative and alternative communication support for autism spectrum and intellectual disability populations, requiring specialized ASHA certification maintenance.
Children represent the largest addressable population. Seniors are gaining share fastest as demographic aging accelerates.
Delivery Mode:
Channel economics favor in-person delivery for complex diagnostic assessments, while online and hybrid models capture routine intervention volume at compressed labor costs.
- In-person:Traditional clinic-based delivery requiring physical infrastructure and geographic proximity to client populations, sustaining premium pricing through personalized care plans.
- Online:Fully remote synchronous sessions enabled by purpose-built video-conferencing technology, penetrating Mountain West rural districts where vacancy rates exceed 25 percent.
- Hybrid:Alternating in-person and remote sessions, balancing assessment fidelity with logistical convenience for working families and dispersed populations.
- Mobile:Clinician travel to client locations including schools, homes, and workplace wellness centers, common in direct-to-employer occupational health contracts.
In-person delivery retains the revenue pool. Online modes show the steepest expansion trajectory.
Funding Source:
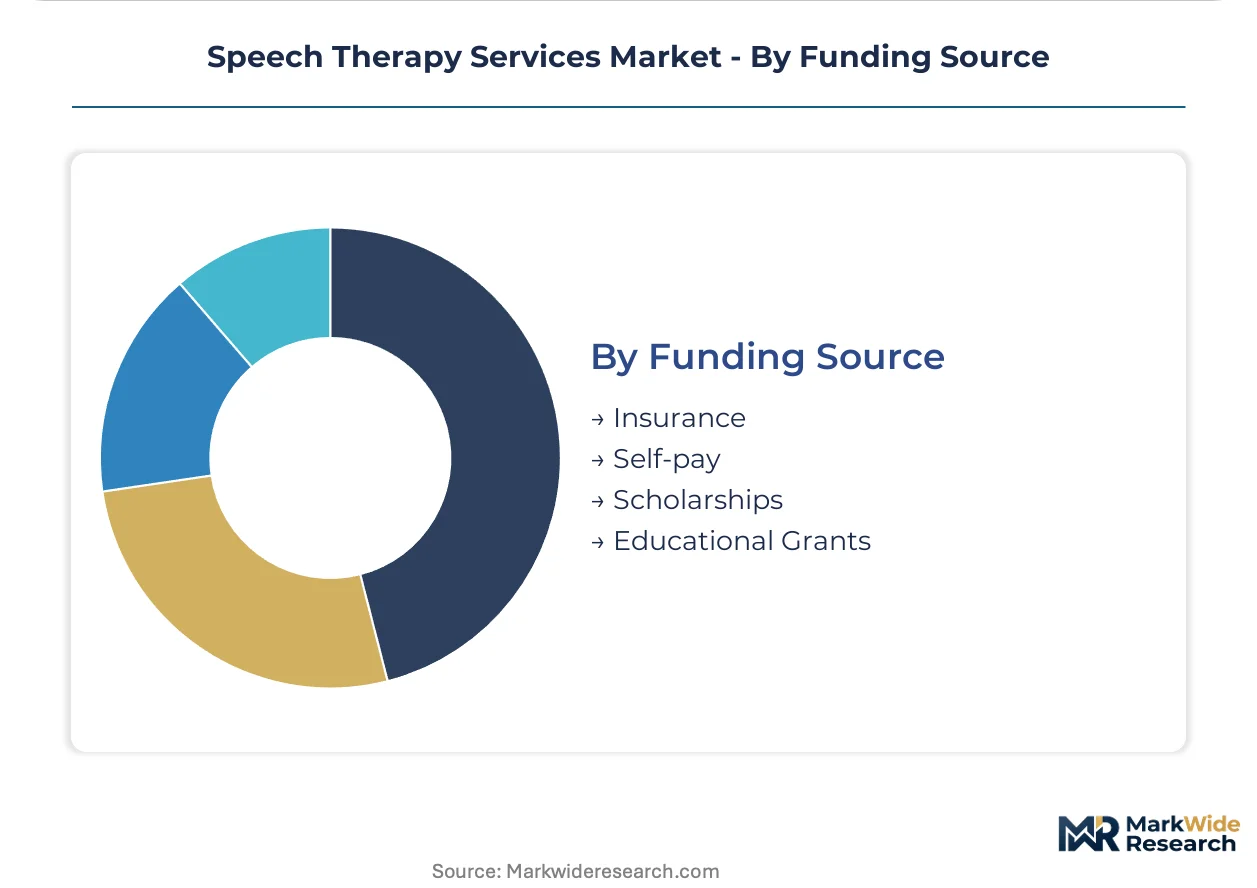
Reimbursement concentration determines provider target segments, with insurance and educational grants sustaining scale operations while self-pay creates direct-to-consumer positioning.
- Insurance:CMS Medicare and Medicaid schedules plus commercial payer contracts, with telehealth parity laws governing cross-border service eligibility.
- Self-pay:Direct consumer payment bypassing preauthorization requirements, emerging in employer-sponsored wellness benefits and concierge service tiers.
- Scholarships:Nonprofit and foundation subsidies for underserved populations, filling gaps where insurance coverage excludes specific diagnostic categories.
- Educational Grants:State and federal special-education funding streams administered through district IEP processes, creating guaranteed procurement volumes.
Insurance dominates transaction volume. Self-pay is expanding most quickly as employers add speech therapy to on-site wellness benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Texas and California metropolitan corridors exceeds interior states by margins exceeding 40 percent, while rural Mountain West districts absorb vacancy-driven premiums that compress provider margins. This asymmetry redistributes service capacity toward telehealth-enabled cross-border delivery models.
United States
Texas and California school districts embed speech-language pathologists directly into special-education teams through state education agency contracts, generating guaranteed Medicaid reimbursement streams. CMS telehealth parity statutes and the ASHA interstate compact enable licensed practitioners to practice across member states without redundant credentialing. Houston and Dallas-Fort Worth independent school districts now favor three-year managed service agreements with telehealth-enabled vendors over fragmented local staffing.
Canada
Provincial health authorities in Ontario and British Columbia expand school-based speech therapy through Ministry of Education special-needs funding envelopes. Health Canada regulates software-as-medical-device claims for therapy applications under the Medical Devices Regulations. Toronto and Vancouver metropolitan clusters concentrate ASHA-certified practitioners, while Prairie provinces rely on telehealth contracts with US-based compact-licensed providers to fill rural vacancies.
United Kingdom
NHS England's Long Term Plan embeds speech and language therapy within integrated care systems for post-stroke rehabilitation and pediatric developmental intervention. The Care Quality Commission inspects digital health platforms delivering remote therapy services under the Health and Social Care Act 2008. London and Southeast England clusters absorb over half of registered speech and language therapists, forcing Northern England and Scotland health boards toward asynchronous telehealth models.
Australia
The National Disability Insurance Scheme funds individualized therapy plans for children with autism spectrum and communication disorders, creating direct-to-provider payment pathways. The Therapeutic Goods Administration classifies AI-powered articulation screening tools as Class I medical devices requiring conformity assessment. Sydney and Melbourne metropolitan areas concentrate private practice capacity, while Queensland and Western Australia rural districts rely on telehealth contracts with interstate providers.
Germany
Statutory health insurance funds reimburse speech therapy through uniform fee schedules administered by the National Association of Statutory Health Insurance Physicians. The Federal Institute for Drugs and Medical Devices regulates digital therapeutic applications under the Medical Devices Regulation EU 2017/745. Bavaria and North Rhine-Westphalia host the densest concentrations of speech therapy practices, while eastern federal states exhibit persistent practitioner shortages addressed through mobile service models.
Speech Therapy Services Market Competitive Environment
Concentration sits with telehealth platform operators and school-district contracting specialists rather than traditional brick-and-mortar clinic networks. The vendor base stratifies across three tiers: proprietary technology developers, staffing-heavy service contractors, and hybrid operators blending both capabilities. Dominant competitive moves include multi-year managed service agreements bundling assessment and intervention under fixed per-pupil pricing, and backward integration into AI-powered screening tools that compress assessment labor costs.
Within the school-district contracting tier, Benchmark Therapies exemplifies the infrastructure-heavy archetype leveraging multi-state service agreements, while TinyEYE Therapy Services anchors the technology-first segment through purpose-built pediatric video-conferencing platforms. Humanus Corporation occupies a position staffing rural and underserved districts where in-person recruitment lags. These three operators collectively represent the strategic divergence between capital-light telehealth delivery and relationship-intensive district procurement.
| Leading Market Players |
|---|
| Benchmark Therapies |
| Humanus Corporation |
| John McGivney Children's Centre |
| Smart Speech Therapy |
| Speech Plus |
| TinyEYE Therapy Services |
| EBS Healthcare |
| Reliant Rehabilitation |
| The Stepping Stones Group |
| Others |
Value Chain & Pricing Dynamics
Scale economies in telehealth platform infrastructure compress per-session delivery costs below brick-and-clinic thresholds, concentrating supply capacity among operators with multi-state licensure compacts and fixed-cost amortization across high-volume school-district contracts. This asymmetry establishes price floors that independent practices cannot match without comparable session density or proprietary technology leverage.
Pricing Analysis
The customization-premium spread separates standard per-pupil district contracts from configured-to-order employer wellness programs and concierge direct-pay tiers. Pricing stratifies across premium, standard, and economy tiers driven by clinician certification level and geographic delivery cost, with ASHA-certified specialists commanding 40 percent spreads over provisionally licensed practitioners. Pricing pressure stems from CMS conversion factor reductions squeezing Medicare-reimbursed outpatient margins. School-district procurement officers exhibit highest price sensitivity, while self-insured employers in manufacturing sectors show lowest sensitivity due to bypassed preauthorization overhead.
Supply Chain Analysis
Inventory and lead-time compression characterizes digital therapeutic deployment, where AI-powered articulation screening tools deploy via cloud infrastructure without physical distribution lag. Supply concentrates in the United States, Canada, and Australia as primary markets for ASHA-certified practitioner training and telehealth platform development. Raw material dependencies center on broadband infrastructure, proprietary video-conferencing software, and standardized assessment licensing from publishers including Pearson and Pro-Ed. Single-source vulnerability runs through interstate licensure compact administration, where compact commission delays disrupt cross-border workforce mobility. Distribution runs through direct-to-district contracting and employer-sponsored benefit administrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative purchasing contracts at Texas Education Agency and California Department of Education, consolidating vendor selection authority among procurement officers managing multi-million-dollar special-education budgets.
For Market Incumbents: Fortify position through backward integration into AI-powered screening tools that compress assessment labor costs, and anchor multi-year managed service agreements with guaranteed response-time SLAs. The threat of unvalidated digital therapeutic competitors receiving FDA 510(k) clearance demands clinical validation investment as defensive priority. For New Entrants and Emerging Players: ASHA certification fast-track programs for rural compact states offer lowest barrier-to-entry positioning. White-space targets include Wyoming, Montana, and Idaho school districts with vacancy rates exceeding 25 percent, and direct-to-employer occupational health contracts in manufacturing corridors bypassing traditional insurance channels. Go-to-market through telehealth-native value propositions emphasizing session documentation automation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth platform operators with embedded district IT systems and multi-year contract backlogs. Long-term viability favors hybrid models blending proprietary technology with staffing capabilities. Acquisition targets should demonstrate interstate compact licensure density and AI validation study completion. The signal to watch is FDA 510(k) clearance velocity for articulation screening algorithms as competitive moat determinant.| Strategic Initiative | Industry Significance |
|---|---|
| Interstate Compact Licensure Expansion | ASHA compact ratification unlocks cross-border practitioner deployment without redundant credentialing. |
| AI-Powered Assessment Integration | FDA 510(k) clearance for phoneme recognition algorithms secures reimbursement eligibility against unvalidated competitors. |
| Multi-Year District Managed Services | Texas Education Agency cooperative purchasing favors guaranteed SLA vendors over hourly-rate competitors. |
| Direct-to-Employer Wellness Contracts | Self-insured manufacturers bypass preauthorization requirements, expanding addressable market beyond insurance channels. |
| Proprietary Platform Development | Purpose-built pediatric video-conferencing technology reduces session dropout rates versus generic telehealth infrastructure. |
Study Parameters
The analysis maps individual therapy, group therapy, teletherapy, and home health delivery modes, each validated through speech-language pathologists, school-district special-education directors, telehealth platform operators, and Medicaid reimbursement specialists. Primary interviews with these stakeholders combined with secondary validation against CMS Medicare Physician Fee Schedule filings, ASHA membership and workforce surveys, FDA 510(k) premarket notification databases, and state education agency procurement records. Bottom-up session volume estimates triangulated against top-down reimbursement flow analysis.
Consistency checks validated outputs against external benchmarks including ASHA-certified practitioner geographic distribution data and district vacancy rate surveys from Mountain West states. The analytical framework modeled service type, client age segment, delivery mode, and funding source dimensions across the projection horizon. CAGRs derived from session volume growth trajectories and reimbursement rate evolution assumptions. Forecast inputs incorporated interstate compact ratification timelines and AI screening tool adoption curves.
Underlying assumptions cover telehealth parity statute stability, compact commission operational capacity, and CMS reimbursement schedule continuity, with deviation risk concentrated in FDA software-as-medical-device reclassification and state-level Medicaid expansion variability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market