
 Antimicrobial Regenerative Wound Matrix Market | 2026-2036
Antimicrobial Regenerative Wound Matrix Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Regenerative Wound Matrix Market Analysis
FDA 510(k) and PMA qualification cycles for combination drug-device wound products is bifurcating the competitive landscape into established cleared portfolios versus pre-clinical aspirants. Smith & Nephew plc leverages its broad regulatory dossier across multiple jurisdictions to sustain hospital contracting relationships. Integra LifeSciences anchors its position through in-house collagen sourcing and controlled manufacturing of regenerative matrices. Organogenesis Inc. differentiates via living cell-based platforms that navigate the most stringent biologic-device hybrid pathways.
An antimicrobial regenerative wound matrix is a bioactive scaffold, typically composed of collagen, extracellular matrix derivatives, or synthetic polymers impregnated with ionic silver, polyhexamethylene biguanide, or other antimicrobial agents, manufactured through lyophilization or electrospinning processes to preserve porous architecture conducive to cellular infiltration and granulation tissue formation; its primary commercial purpose is to simultaneously manage bioburden and accelerate endogenous healing in recalcitrant wounds. Hydrogels dominate current volume due to ease of application in outpatient settings, while nanofiber matrices produced via electrospinning represent the fastest-expanding technology segment as clinicians seek conformable coverage for irregular wound beds. Hospital procurement channels concentrate margin pools in surgical wound and diabetic ulcer applications, whereas home care and long-term care facilities are emerging as volume growth vectors for foam and film formats.
FDA, EMA MDR, and Japan's PMDA collectively govern market access through divergent evidentiary requirements for antimicrobial claims on regenerative devices, with FDA's combination product classification creating the highest regulatory barrier and EMA's MDR transition extending conformity assessment timelines for European suppliers. Health Canada and Australia's TGA maintain aligned but less burdensome pathways that attract mid-tier manufacturers seeking initial regulatory footholds. Stakeholders must monitor evolving FDA guidance on antimicrobial resistance labeling and EU ECHA scrutiny of silver ion environmental release as these frameworks will determine which product formats retain market authorization.
Market Dynamics
FDA's tightening qualification requirements for combination drug-device products are bifurcating competitive positioning between established cleared portfolios and pre-clinical aspirants, forcing manufacturers to front-load clinical evidence generation before commercial entry.
Growth Catalysts
- Chronic wound center expansion:Hospital systems in the United States are consolidating outpatient wound care into specialized facilities that standardize advanced matrix protocols.
- REACH silver ion scrutiny:ECHA's environmental release assessments are accelerating reformulation toward biodegradable antimicrobial alternatives that command premium positioning.
- Electrospinning maturation:Nanofiber manufacturing scale-up is reducing unit costs for conformable matrices targeting irregular wound beds.
Market Restraints
- Collagen supply concentration:Bovine and porcine tissue sourcing clusters in specific agricultural regions expose manufacturers to zoonotic disease quarantine disruptions.
- MDR conformity assessment backlog:EMA's notified body capacity constraints extend European market authorization timelines to 18-24 months for novel matrix submissions.
- Antibiotic-impregnated dressing substitution:Low-cost topical antimicrobial alternatives limit pricing power in long-term care facilities with fixed reimbursement.
Strategic Opportunities
- Japan's PMDA regenerative medicine framework:Conditional approval pathways for combination biologics enable earlier revenue generation from living cell-based platforms.
- Home care channel penetration:Self-application hydrogel formats address the 40% of diabetic ulcer patients managed outside hospital settings.
- Silver-PHMB hybrid formulations:Dual-mechanism antimicrobial loading addresses emerging resistance patterns in chronic wound bioburden.
Industry Challenges
- Lyophilization technician scarcity:Specialized porous scaffold manufacturing requires process engineers with pharmaceutical freeze-drying expertise that outpaces training pipeline output.
- FDA combination product classification disputes:Determination of primary mode of action delays IND meetings and forces redundant clinical trial designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Regenerative Wound Matrix Market |
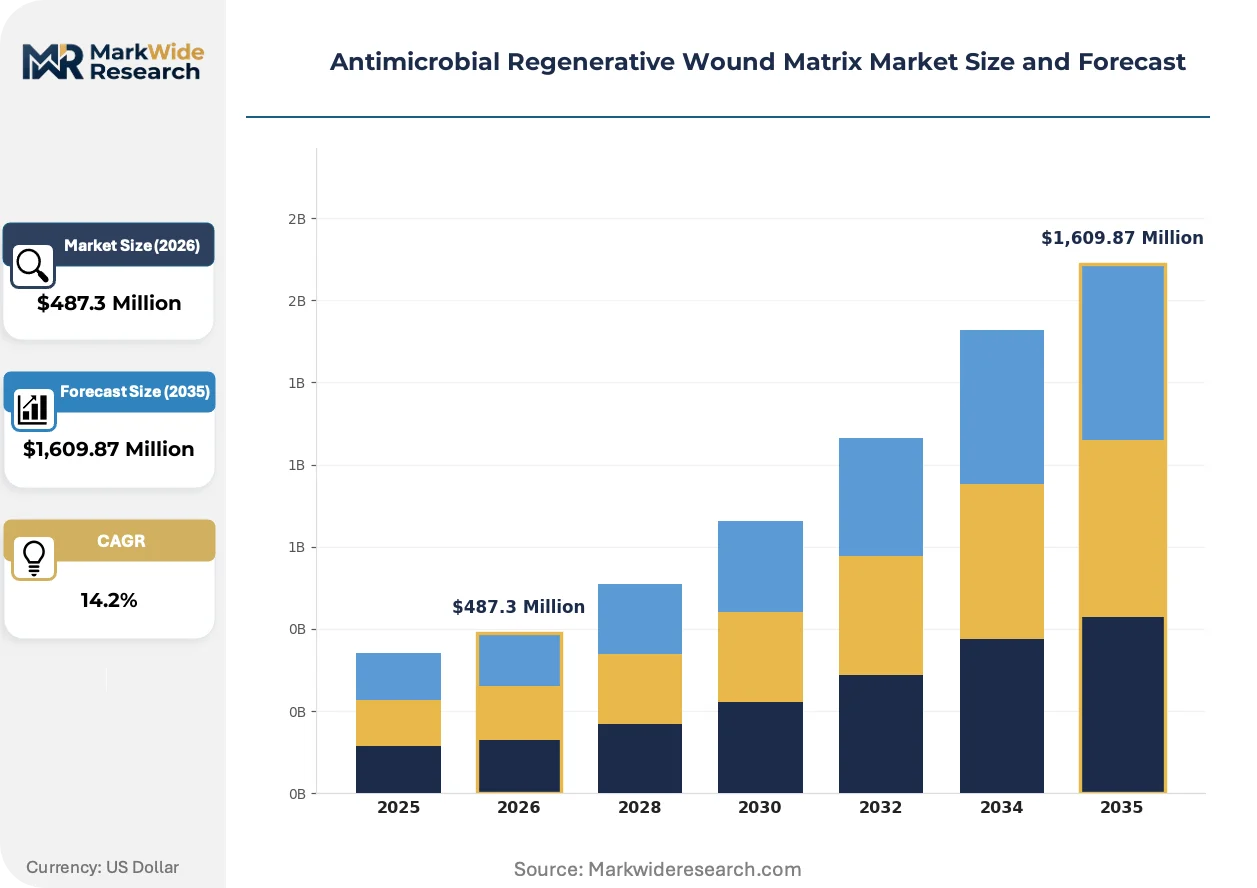
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogels, Foams, Films, Sponges Technology: Electrospinning, 3D Bioprinting, Lyophilization, Nanofibers End User: Hospitals, Home Care, Outpatient Clinics, Long-term Care Facilities Application: Diabetic Ulcers, Surgical Wounds, Burns, Pressure Sores |
| Companies Covered | 3M, Smith & Nephew plc, Integra LifeSciences, DSM Biomedical, Aroa Biosurgery Ltd., Avita Medical, ConvaTec Group plc, Mölnlycke Health Care AB, Organogenesis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Regenerative Wound Matrix Market Emerging Trajectories
Electrospun nanofiber architectures are compressing the performance gap between synthetic scaffolds and biologic matrices, reshaping clinician preference for wound bed conformability.
Electrospinning of polycaprolactone-gelatin blends produces sub-micron fiber networks that mimic native extracellular matrix topography. Burn centers in Germany and Japan are adopting these formats for partial-thickness wound coverage at triple the rate of foam alternatives. The technology is miniaturizing production equipment to point-of-care dimensions, enabling hospital-based scaffold customization.
EMA's MDR transition imposes clinical evidence requirements for antimicrobial claims that previously relied on bench testing alone. European manufacturers must now generate patient-level outcome data for silver ion release kinetics. High-complexity chronic wound applications face the steepest compliance burden, driving portfolio rationalization toward diabetic ulcer and surgical wound segments with established endpoints.
Hospital value analysis committees now mandate health economic evidence for matrix selection, displacing individual surgeon preference. Integrated delivery networks in the United States consolidate purchasing through centralized formularies that tier products by cost-per-healed-wound metrics. This behavioral shift concentrates contract awards among three to four suppliers with robust real-world evidence libraries.
Antimicrobial Regenerative Wound Matrix Market Segmentation
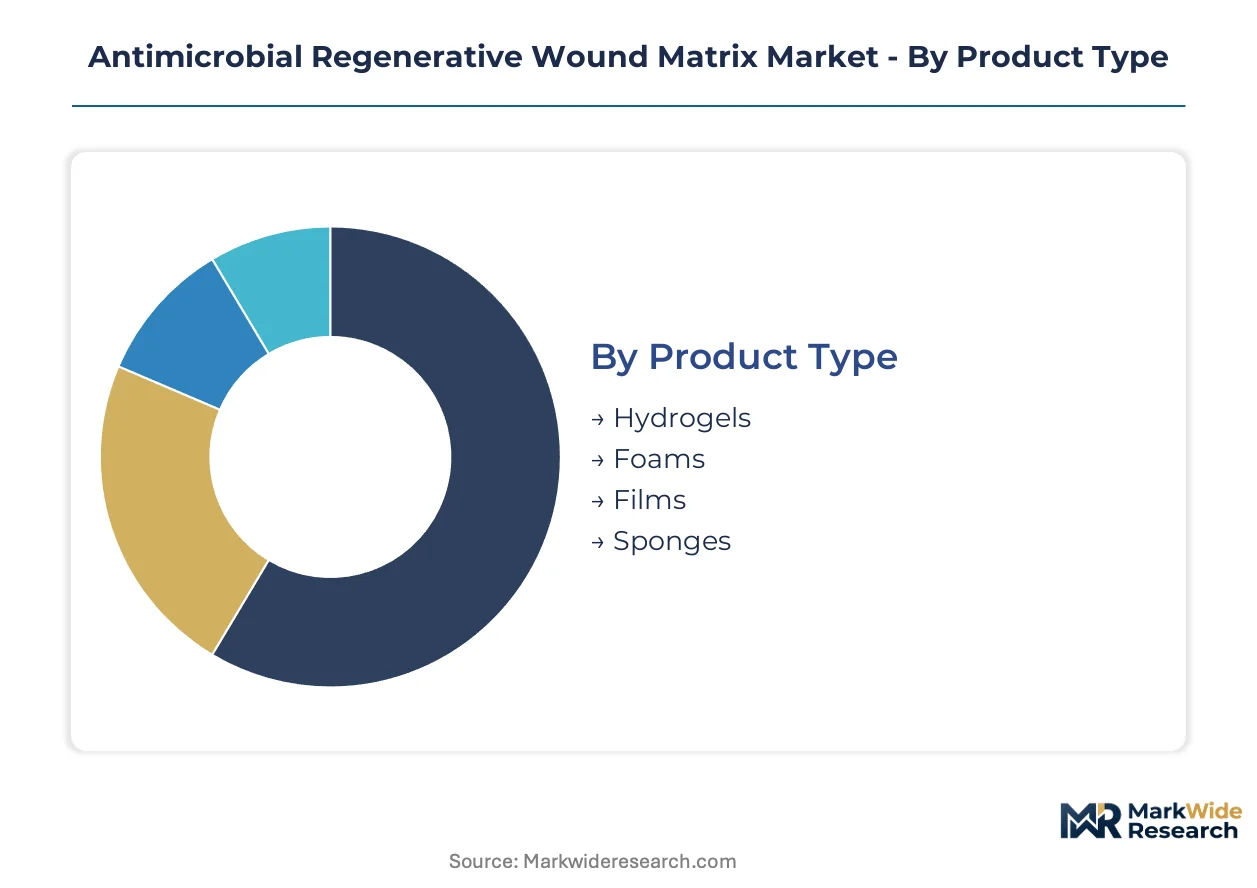
Antimicrobial regenerative wound matrices fragment across four structural dimensions that determine pricing power, regulatory pathway selection, and channel access. Product format and manufacturing technology define the core value proposition, while end-user setting and wound etiology shape commercial strategy.
Product Type:
Domestic consumption concentrates hydrogels and foams in the United States and Germany, while film and sponge exports flow disproportionately toward Japan and emerging Asian wound care markets.
- Hydrogels:Cross-linked polymer networks with silver ion or PHMB loading deliver moisture-retentive environments for autolytic debridement. Hospital outpatient departments in the United States favor hydrogels for diabetic ulcer protocols where patient self-application reduces nursing labor costs.
- Foams:Polyurethane or silicone-based absorbent structures with integrated antimicrobial agents manage moderate-to-heavy exudate in surgical wound settings. German burn centers specify foam matrices for partial-thickness coverage where conformability and thermal insulation converge.
- Films:Semi-permeable polyurethane membranes with surface antimicrobial coating provide vapor-permeable barriers for superficial wounds.
- Sponges:Collagen or gelatin-derived porous scaffolds processed via lyophilization enable rapid hemostasis and cellular infiltration in operative fields.
Hydrogels hold the largest share; momentum sits with foams as hospital value analysis committees prioritize absorbency metrics.
Technology:
Manufacturing method determines regulatory classification burden and unit economics, with electrospinning and 3D bioprinting commanding premium positioning against established lyophilization platforms.
- Electrospinning:High-voltage fiber drawing produces sub-micron scaffolds mimicking native extracellular matrix architecture. Japanese wound specialists adopt electrospun matrices for irregular wound bed conformance where traditional sheet formats fail.
- Lyophilization:Freeze-drying of collagen suspensions preserves porous structures for cellular migration and granulation tissue formation. United States chronic wound centers rely on lyophilized sponges for established reimbursement codes and predictable clinical outcomes.
- 3D Bioprinting:Layer-by-layer deposition of living cells and biomaterials creates patient-specific scaffold geometries.
- Nanofibers:Scaled electrospinning variants optimize surface-area-to-volume ratios for antimicrobial agent release kinetics.
Lyophilization dominates current revenue; nanofibers are expanding most quickly as manufacturing scale reduces per-unit costs.
End User:
Channel concentration shapes margin structure, with hospital procurement commanding volume discounts and home care segments offering pricing power through direct-to-patient models.
- Hospitals:Integrated delivery networks consolidate advanced matrix purchasing through centralized formularies with tiered supplier selection. Surgical services and specialized wound centers within United States hospital systems generate the highest per-procedure matrix utilization rates.
- Home Care:Self-application formats bypass institutional procurement controls and capture reimbursement under durable medical equipment benefits. German home nursing services specify hydrogel and film formats for diabetic ulcer patients managed outside acute settings.
- Outpatient Clinics:Physician office-based wound care facilities with limited storage capacity favor single-use sterile packaging.
- Long-term Care Facilities:Fixed per-diem reimbursement structures in United States skilled nursing facilities constrain matrix selection to lower-cost foam and film alternatives.
Hospitals retain the largest share; home care gains share fastest as remote patient monitoring expands wound care beyond institutional boundaries.
Application:
Wound etiology determines clinical endpoint requirements and regulatory evidence standards, with diabetic ulcers and surgical wounds offering the clearest pathways to market authorization.
- Diabetic Ulcers:Neuropathic foot lesions in diabetic populations require matrices addressing both bioburden management and granulation tissue induction. United States Medicare reimbursement for bioengineered skin substitutes concentrates manufacturer commercial focus on this indication.
- Surgical Wounds:Incisional and excisional sites demand hemostatic and antimicrobial properties to prevent surgical site infection. German hospital procurement specifications prioritize surgical wound matrices with documented reduction in revision surgery rates.
- Burns:Partial and full-thickness thermal injuries require conformable coverage with antimicrobial protection and moisture retention.
- Pressure Sores:Ischemic ulcers in immobilized patients present challenges of exudate management and bacterial colonization in long-term care environments.
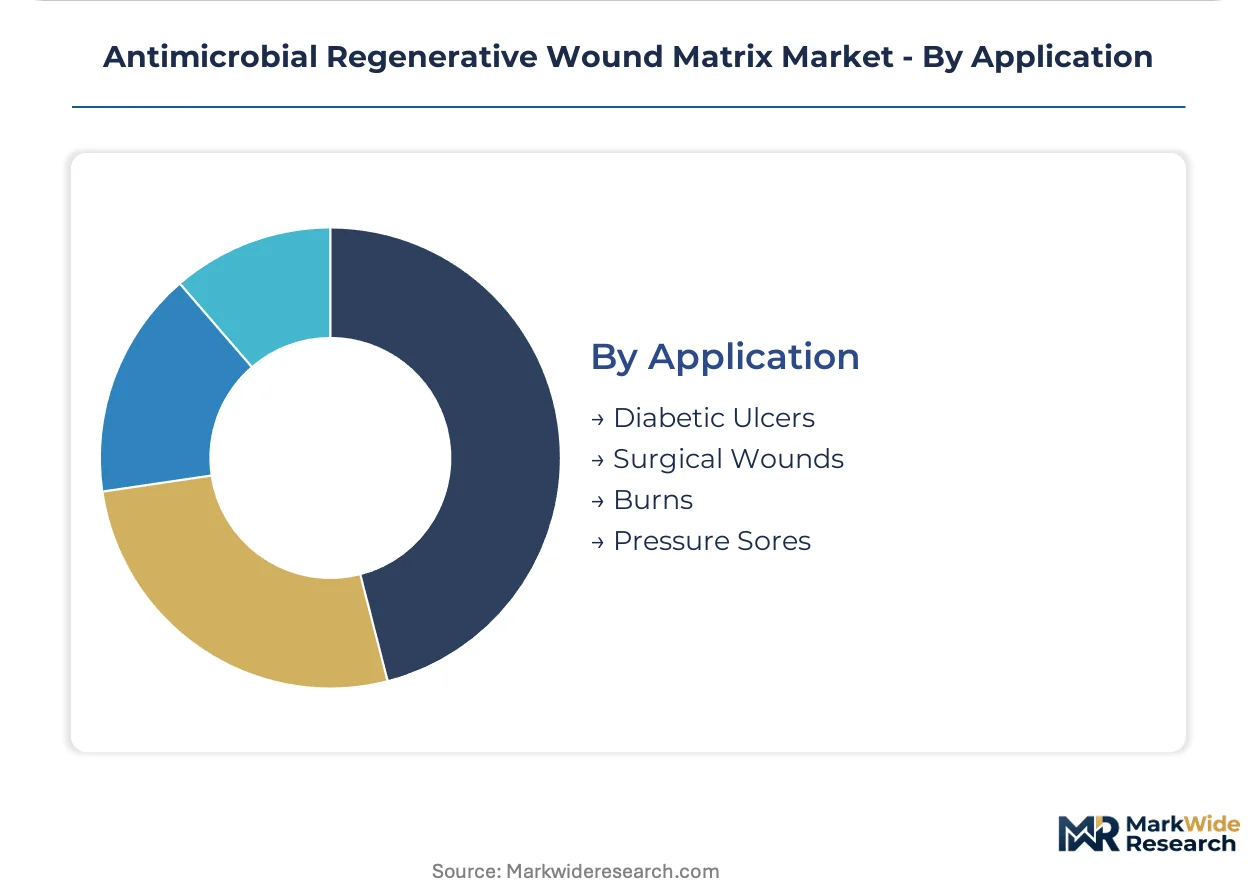
Diabetic ulcers hold the largest share; burns show the steepest expansion trajectory as nanofiber technology penetrates specialized burn center protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's combination product classification for silver-impregnated matrices creates the steepest regulatory barrier among developed wound care markets, while Japan's PMDA conditional approval pathways and Germany's MDR transition timelines generate divergent commercial entry strategies.
United States
Medicare reimbursement for bioengineered skin substitutes drives hospital procurement concentration in diabetic ulcer protocols. FDA PMA and 510(k) pathways for combination drug-device products force manufacturers to front-load clinical evidence generation. Chronic wound centers in Texas and Florida hospital systems standardize advanced matrix protocols through integrated delivery network formularies.
Germany
Burn centers in Bavaria and North Rhine-Westphalia specify foam matrices for partial-thickness coverage where conformability and thermal insulation converge. EMA's MDR transition extends conformity assessment timelines to 18-24 months for novel matrix submissions. Stuttgart and Munich host specialized electrospinning equipment manufacturers serving nanofiber scaffold producers.
Japan
Aging demographics and diabetic prevalence concentrate clinical uptake in Tokyo and Osaka metropolitan wound care facilities. PMDA's regenerative medicine framework enables conditional approval pathways for combination biologics that accelerate revenue generation from living cell-based platforms. Nagoya medical device clusters specialize in lyophilization equipment for collagen scaffold manufacturing.
United Kingdom
NHS England's specialized wound care commissioning drives adoption of antimicrobial matrices in diabetic foot clinics across London and the Midlands. MHRA alignment with EMA MDR requirements imposes clinical evidence standards for antimicrobial claims that previously relied on bench testing. Cambridge and Oxford research corridors host extracellular matrix biomaterial startups.
Australia
TGA maintains aligned but less burdensome pathways than FDA or EMA that attract mid-tier manufacturers seeking initial regulatory footholds. Remote patient monitoring expansion in Queensland and Western Australia extends wound care beyond institutional boundaries into home care channels. Melbourne biomedical manufacturing clusters specialize in collagen sourcing and controlled matrix production.
Antimicrobial Regenerative Wound Matrix Market Vendor Landscape
Listed leaders compete with private specialists across regulatory dossier breadth and manufacturing scale. The competitive landscape bifurcates between established cleared portfolios with broad multi-jurisdictional approvals and pre-clinical aspirants facing front-loaded clinical evidence requirements. Three archetypes dominate: diversified medical technology conglomerates with hospital contracting relationships, specialized regenerative medicine firms with in-house biologic sourcing, and emerging electrospinning technology developers. Dominant competitive moves include strategic partnerships for collagen supply security and technology licensing for nanofiber manufacturing scale-up.
Among diversified medical technology conglomerates, 3M and Smith & Nephew plc exemplify archetypes with broad regulatory dossiers across multiple jurisdictions. Integra LifeSciences occupies a position within the specialized regenerative medicine tier, representing firms with controlled manufacturing of collagen-derived matrices. Organogenesis Inc. anchors the living cell-based platform segment, sitting within the most stringent biologic-device hybrid regulatory pathways.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew plc |
| Integra LifeSciences |
| DSM Biomedical |
| Aroa Biosurgery Ltd. |
| Avita Medical |
| ConvaTec Group plc |
| Mölnlycke Health Care AB |
| Organogenesis Inc. |
| Others |
Supply Flow & Price Mechanics
Electrospinning equipment scale-up in Germany and Japan compresses per-unit nanofiber matrix costs while concentrating margin pools among manufacturers with captive lyophilization capacity. FDA-grade certification requirements create price floors that exclude mid-tier suppliers from hospital integrated delivery network contracts.
Pricing Analysis
Certification level (FDA PMA versus 510(k) versus CE marking under MDR) creates the primary spread across pricing tiers, with combination product classification commanding premiums against standard antimicrobial dressings. Hospital procurement through GPO contracts favors per-unit transactional pricing with volume rebates, while home care channels experiment with direct-to-patient subscription models for chronic ulcer management. Cost compression in standard-grade foams intensifies as antibiotic-impregnated alternatives capture long-term care facility volume. Long-term care facilities with fixed per-diem reimbursement exhibit highest price sensitivity; specialized burn centers demonstrate lowest sensitivity due to outcome-based selection criteria.
Supply Chain Analysis
Lyophilized collagen sponge inventory cycles run 12-18 weeks due to pharmaceutical-grade freeze-drying protocols, constraining responsiveness to hospital demand surges. Bovine and porcine tissue sourcing concentrates in the United States, Australia, and Brazil, with collagen extraction feeding scaffold manufacturing clusters in Massachusetts and Melbourne. Raw material dependencies include pharmaceutical-grade sodium hyaluronate, ionic silver precursors, and cross-linked gelatin networks. Single-source vulnerability in agricultural tissue supply exposes manufacturers to zoonotic disease quarantine disruptions. Distribution runs through hospital GPO contracts, specialty medical distributors, and direct-to-patient home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA combination product dossiers creates switching costs that lock hospital systems into cleared supplier relationships.
For Market Incumbents: Shield market position by deepening backward integration into bovine collagen sourcing through dedicated agricultural partnerships in Australia and the United States. Expand lyophilization capacity in Nagoya and Stuttgart to preempt supply constraints from technician scarcity. Priority defensive investment targets electrospinning scale-up before nanofiber manufacturing commoditizes. For New Entrants and Emerging Players: Anchor in Japan's PMDA conditional approval pathway for living cell-based platforms, where regenerative medicine frameworks enable earlier revenue generation than FDA PMA routes. Target home care hydrogel segments with self-application formats that bypass hospital procurement controls. Go-to-market angle emphasizes direct-to-patient reimbursement under durable medical equipment benefits. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized regenerative medicine firms with in-house biologic sourcing and controlled manufacturing infrastructure. Long-term viability hinges on portfolio breadth across lyophilization and electrospinning platforms rather than single-technology dependence. Acquisition target archetype: mid-tier manufacturers with Health Canada or TGA approvals seeking FDA pathway investment. Signal to watch: FDA guidance publication on antimicrobial resistance labeling requirements as inflection indicator for product format obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Submission Pathway | Combination product classification locks hospital GPO contracts against lower-tier competitors. |
| CE Marking Under MDR | EMA clinical evidence requirements for antimicrobial claims extend European authorization timelines substantially. |
| Hospital System Partnership | Integrated delivery network formulary placement secures volume commitments through value analysis committees. |
| Collagen Supply Security Agreement | Dedicated bovine tissue sourcing in Australia mitigates zoonotic quarantine disruption exposure. |
| Electrospinning Scale-Up Investment | Nanofiber manufacturing capacity expansion reduces unit costs for irregular wound bed conformability. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA filings, EMA MDR transition documentation, and hospital GPO contract databases. Primary interviews engaged regulatory affairs leads at combination product manufacturers, wound center clinical directors, biomedical engineers at integrated delivery networks, and procurement managers at specialty medical distributors. Secondary validation drew from CMS Medicare reimbursement schedules, PMDA regenerative medicine framework guidance, and customs records for collagen raw material trade flows. Bottom-up demand modeling triangulates against top-down market sizing across product format and technology segments.
Segmentation dimensions modeled include product format (hydrogel, foam, film, sponge), manufacturing technology (lyophilization, electrospinning, 3D bioprinting), end-user channel (hospital, home care, outpatient clinic, long-term care), and wound etiology application. CAGRs derive from patient population epidemiology, reimbursement trajectory analysis, and technology adoption curve positioning. Industry-specific forecast inputs incorporate diabetic ulcer incidence projections and chronic wound center expansion rates across the analysis window.
Material uncertainties — FDA guidance revisions on antimicrobial resistance labeling, ECHA silver ion environmental release rulings, and zoonotic disease agricultural disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and reimbursement code maintenance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Wound Closure Devices Market
Wound Care
Wound Cleanser Products Market
Wound Care
North America Wound Care Management Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Europe Compression Bandages Market
Wound Care
Wound Measurement Devices Market
Wound Care
Liquid Bandages Market
Wound Care
Wound Skin Care Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Advanced Wound Management Market