
 Gauze Bandage Rolls Market | 2026-2036
Gauze Bandage Rolls Market Size, Share, and Industry Trends Forecast 2026-2036
Gauze Bandage Rolls Market Foresight
Home care end users is realigning procurement patterns across the gauze bandage rolls value chain as post-operative monitoring shifts outside institutional walls. Medline Industries sustains one of the broadest home-health distribution networks in North America, reaching patients through direct-to-provider channels. Cardinal Health dominates hospital-centric contract purchasing, locking in multi-year supply agreements with integrated delivery networks. Paul Hartmann AG specializes in European wound-care formulations, leveraging its R&D base in Germany to serve clinical segments with higher sterility requirements.
Gauze bandage rolls consist of woven or non-woven absorbent fabric, typically manufactured from cotton, rayon, or synthetic blends in thread counts ranging from 12 to 44 meshes per square inch, designed to manage exudate, protect tissue, and secure primary dressings. Cotton gauze retains the largest installed base across surgical suites due to its established absorption profile and cost predictability, though non-woven variants are capturing share in burn care applications where reduced linting and lower adherence trauma improve patient outcomes. Elastic gauze occupies a narrower but defensible position in fracture immobilization, where controlled compression and conformability command premium positioning over standard woven alternatives.
The FDA enforces Quality System Regulation and 510(k) clearance pathways for sterile gauze classified as medical devices, while the EPA monitors ethylene oxide sterilization emissions that constrain converter capacity in the United States. India's CDSCO mandates BIS certification for imported wound-care textiles, creating a compliance threshold that domestic manufacturers exploit against foreign entrants. Stakeholders must track how sterilization method transitions and evolving home-care reimbursement codes reshape both product specifications and channel economics.
Market Dynamics
Post-acute discharge protocols are compressing hospital length-of-stay windows and pushing wound-care consumption into home settings, forcing manufacturers to reconfigure packaging sizes, sterility claims, and distribution economics for non-institutional buyers.
Growth Catalysts
- Surgical volume expansion in tier-two Indian hospital clusters:Secondary cities are building operating capacity faster than supply chain infrastructure, creating pull-through for basic wound-care consumables.
- EPA ethylene oxide emission constraints:Sterilization capacity limitations in the United States are rewarding converters with alternative validation pathways, tightening supply for laggards.
- Chitosan-coated gauze adoption in burn units:Advanced surface treatments reduce dressing change trauma and accelerate re-epithelialization, commanding premium positioning in specialized care.
Market Restraints
- Raw cotton price volatility:Weather-driven supply fluctuations from major producing regions compress margin predictability for woven gauze specialists.
- Converter concentration in FDA-registered sterilization facilities:Limited ethylene oxide alternatives in the United States create single-point-of-failure risk for sterile product lines.
- Hydrogel and foam dressing substitution:Advanced moisture-retentive technologies capture moderate-to-heavy exudate cases previously managed with layered gauze.
Strategic Opportunities
- Underpenetrated home-care nursing networks in Brazil:Post-operative monitoring infrastructure gaps create white space for sterile gauze bundled with remote patient monitoring protocols.
- India PLI scheme for medical textiles:Domestic manufacturing incentives reward capacity expansion for export-qualified wound-care producers.
- Smart packaging convergence with RFID tracking:Unit-level traceability enables outcome-based reimbursement pilots with integrated delivery networks.
Industry Challenges
- Sterilization validation timeline compression:FDA 510(k) pathway modifications for novel sterilization methods extend product launch cycles.
- Legacy ERP integration with track-and-trace mandates:UDI compliance requirements strain mid-tier converters with dated inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gauze Bandage Rolls Market |
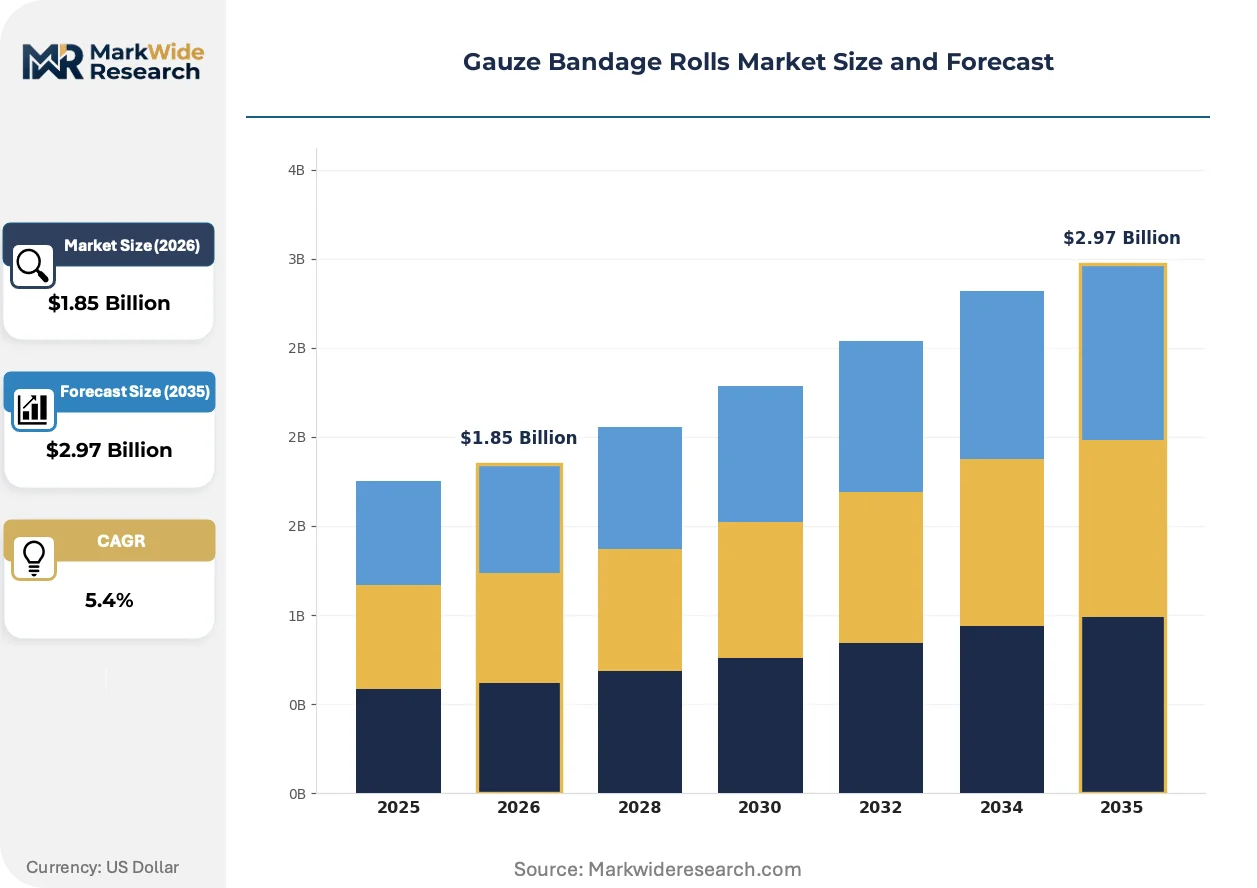
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton Gauze, Non-Woven, Elastic, Adhesive, Rayon Blend Application: Wound Dressing, Surgical Dressing, Burn Care, Fracture Immobilization, First Aid End User: Hospitals, Ambulatory Centers, Home Care, Emergency Services, Clinics Packaging Type: Sterile Packs, Non-Sterile Packs, Multi-Roll Packs, Individually Wrapped, Bulk Bundle |
| Companies Covered | Cardinal Health, Medline Industries, 3M Company, Johnson & Johnson, Paul Hartmann AG, Smith & Nephew, Dynarex Corp., BSN medical, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gauze Bandage Rolls Market Shifts & Advancements
Material science advances and regulatory sterilization transitions are bifurcating product development roadmaps, with capital-rich players investing in alternative validation while smaller converters defend legacy ethylene oxide dependencies.
Antimicrobial-impregnated gauze is absorbing patient volume in surgical site infection prevention protocols. Hospital procurement committees are fast-tracking silver and PHMB-loaded variants into standard order sets. This technology is absorbing share from conventional cotton gauze in orthopedic and cardiovascular procedure lines where infection readmission penalties concentrate financial risk.
India's CDSCO BIS certification requirements for imported wound-care textiles are tightening compliance thresholds. Domestic manufacturers are exploiting this friction to capture share from foreign entrants in government hospital tenders. Tier-two and tier-three hospital clusters are responding by consolidating procurement around validated local suppliers with established import-substitution track records.
Direct-to-patient distribution models are emerging through specialized home-care pharmacy networks. Traditional distributor markups are compressing as integrated delivery networks negotiate consignment arrangements for post-discharge supplies. This pattern is most visible in United States Medicare Advantage plans where bundled payment structures incentivize cost control across the acute-to-post-acute continuum.
Gauze Bandage Rolls Market Segmentation
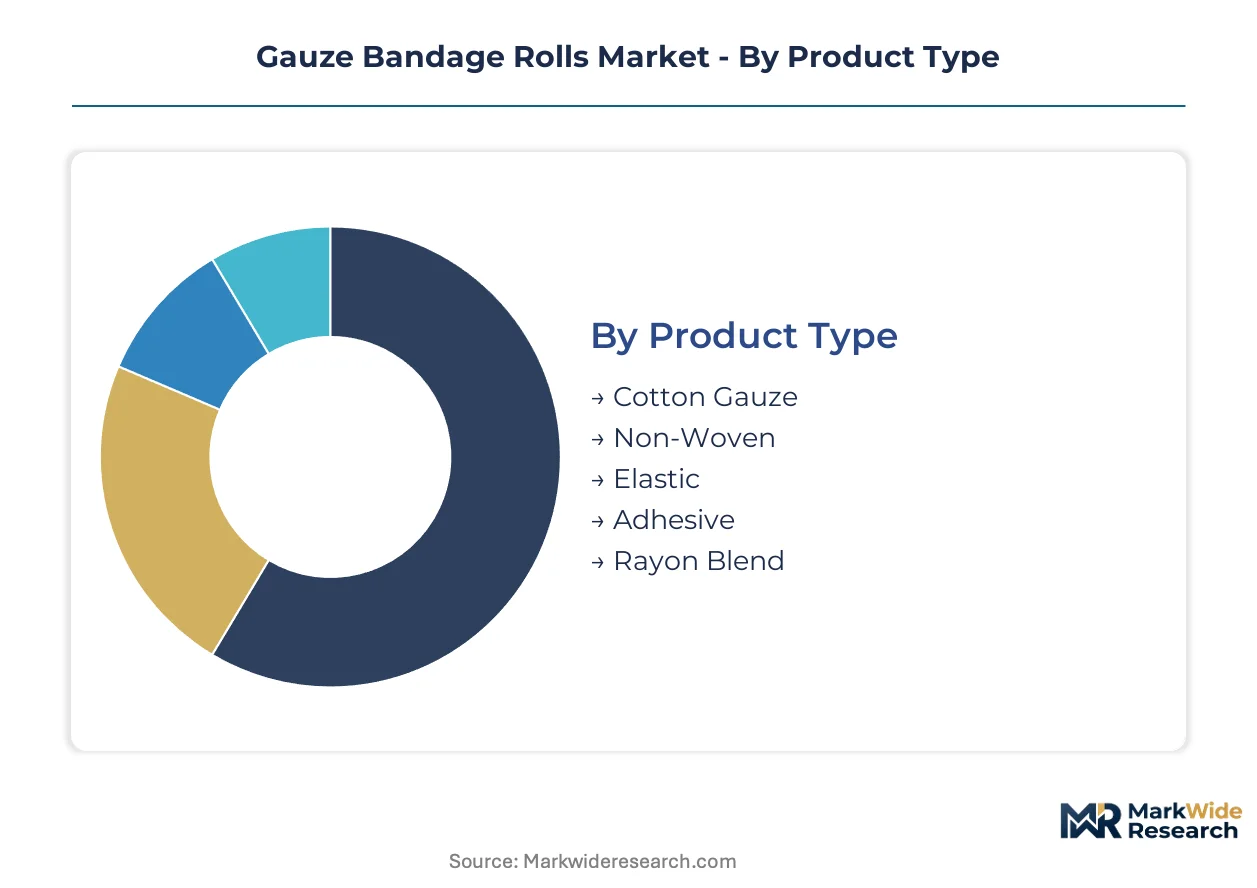
Product configuration choices in gauze bandage rolls determine sterilization pathways, distribution economics, and reimbursement eligibility. Manufacturers align capacity investments with end-use concentration patterns across institutional and home-care channels.
Product Type:
Converter capacity concentrates around legacy cotton processing, though alternative materials are capturing specialized applications.
- Cotton Gauze:Woven absorbent fabric manufactured from bleached cotton in mesh counts from 12 to 44 per square inch, retaining dominant position across surgical suites in India and the United States due to established absorption predictability and cost transparency. Raw cotton price volatility compresses margin stability for dedicated weavers.
- Non-Woven:Spun-laid or melt-blown synthetic fiber constructions eliminate linting and reduce dressing adherence trauma, commanding premium positioning in burn units where re-epithelialization speed drives procurement decisions. Demand is climbing fastest in tertiary care centers with dedicated wound management protocols.
- Elastic:Cotton-spandex or synthetic rubber interwoven constructions deliver controlled compression for fracture immobilization and lymphedema management, occupying defensible niche with higher unit economics than standard woven alternatives.
- Adhesive:Self-adherent cohesive bandage formulations eliminate the need for clips or tape, penetrating sports medicine and veterinary applications where rapid application speed matters.
- Rayon Blend:Semi-synthetic cellulose-based compositions offer intermediate absorbency between cotton and fully synthetic variants, serving cost-sensitive institutional buyers seeking performance differentiation without full premium positioning.
Cotton Gauze absorbs the bulk of installed capacity; Non-Woven is expanding most quickly.
Application:
Clinical use case determines sterility grade, packaging configuration, and regulatory pathway requirements.
- Wound Dressing:Primary or secondary coverage for exuding injuries across acute and chronic presentations, representing the largest volume absorption channel as post-acute discharge protocols shift monitoring outside hospital walls. Home care nursing networks in Brazil and India are pulling sterile variants into direct-to-patient distribution models.
- Surgical Dressing:Operating room and procedure suite applications demanding validated sterilization documentation, with antimicrobial-impregnated variants fast-tracking into orthopedic and cardiovascular order sets where infection readmission penalties concentrate financial risk.
- Burn Care:Specialized management of partial-thickness and full-thickness thermal injuries requiring low-adherence surfaces and exudate control, with chitosan-coated gauze commanding premium positioning in dedicated burn centers.
- Fracture Immobilization:Compression and padding applications beneath casts and splints, where elastic gauze conformability reduces pressure point complications.
- First Aid:Consumer and occupational health kit components, typically non-sterile and bulk-packaged, with procurement concentrating through industrial safety distributors and retail pharmacy chains.
Wound Dressing captures the greatest shipment volume; Surgical Dressing offers the steepest expansion trajectory as infection prevention protocols tighten.
End User:
Customer type dictates packaging scale, sterility claims, and channel economics across the value chain.
- Hospitals:Integrated delivery networks and standalone facilities purchasing through group purchasing organizations, locking in multi-year supply agreements with tier-one converters. India's tier-two hospital clusters are outpacing inventory buildouts, creating supply tension for basic consumables.
- Ambulatory Centers:Outpatient surgery and procedure facilities with compressed supply room footprints, favoring just-in-time delivery models and consolidated SKU portfolios.
- Home Care:Post-discharge patients and visiting nurse services absorbing larger gauze volumes as length-of-stay windows compress, forcing manufacturers to reconfigure packaging sizes and sterility claims for non-institutional buyers.
- Emergency Services:Pre-hospital and disaster response applications requiring ruggedized packaging and extended shelf stability, with procurement running through municipal and federal emergency preparedness budgets.
- Clinics:Physician office and urgent care settings with intermediate volume requirements, often sourcing through distributor intermediaries rather than direct manufacturer relationships.
Hospitals dominate absolute consumption; Home Care is gaining share fastest as reimbursement codes evolve.
Packaging Type:
Packaging configuration determines sterilization validation burden, shelf life, and unit economics at point of use.
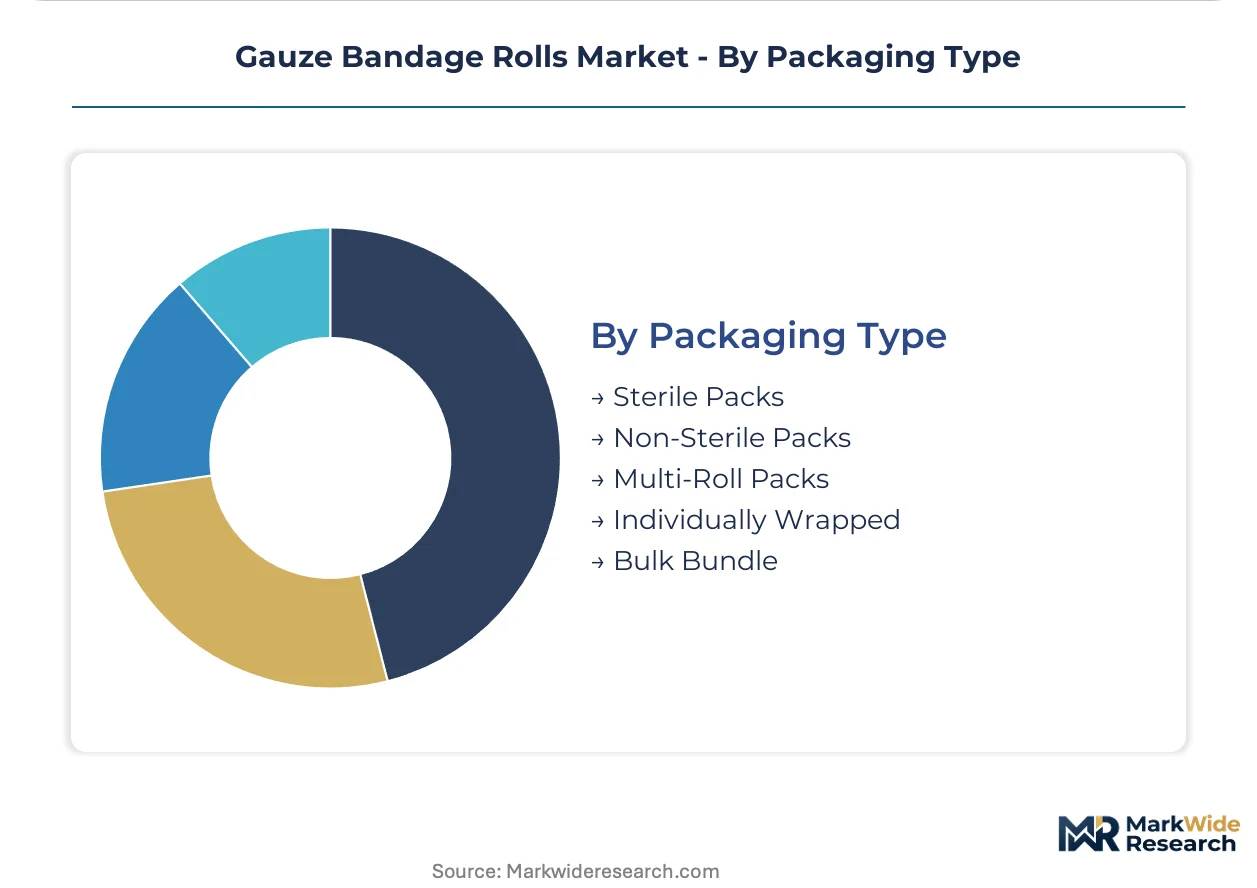
- Sterile Packs:Individual or multi-unit configurations validated to FDA 510(k) or CDSCO requirements, mandatory for invasive procedure applications. EPA ethylene oxide emission constraints are compressing supply timelines for non-compliant converters.
- Non-Sterile Packs:Clean-room manufactured products without terminal sterilization, serving first aid, veterinary, and industrial applications where aseptic technique is not required.
- Multi-Roll Packs:Intermediate quantity configurations balancing storage efficiency with consumption rate matching, penetrating ambulatory centers and smaller clinic settings.
- Individually Wrapped:Single-unit sterile presentations enabling precise inventory tracking and waste reduction, aligning with UDI compliance mandates and consignment arrangement economics.
- Bulk Bundle:Large-quantity non-sterile shipments for high-throughput institutional laundries and central supply operations, minimizing per-unit packaging cost.
Sterile Packs command the greatest production capacity allocation; Individually Wrapped is climbing fastest as track-and-trace mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in South and Southeast Asia while consumption concentrates in North American and European healthcare systems. This geographic split creates trade flow dependencies and regulatory friction points that shape procurement economics across the value chain.
United States
Hospital consolidation into integrated delivery networks concentrates purchasing power among fewer buyers, compressing margins for contract-dependent suppliers. EPA emission constraints on ethylene oxide sterilization facilities have tightened converter capacity, forcing manufacturers toward alternative validation pathways. The Midwest industrial corridor hosts legacy textile processing infrastructure that now faces retrofit burdens for compliance with updated FDA Quality System Regulation standards.
Germany
Specialized wound-care R&D facilities in the Baden-Württemberg region drive premium product development for clinical segments with elevated sterility requirements. EMA medical device regulations and CE marking protocols under the EU MDR create compliance thresholds that favor established domestic converters over import competition. The country's central European logistics position enables distribution efficiency into neighboring markets with harmonized regulatory recognition.
India
Tier-two hospital clusters in cities like Jaipur, Lucknow, and Coimbatore are expanding surgical capacity faster than supply chain infrastructure can match, creating inventory tension for basic consumables. CDSCO BIS certification mandates for imported wound-care textiles erect barriers that domestic manufacturers exploit in government hospital tenders. The PLI scheme for medical textiles is accelerating capacity buildout among export-qualified producers in Gujarat and Tamil Nadu.
Brazil
Underdeveloped post-operative monitoring infrastructure creates white space for sterile gauze bundled with remote patient monitoring protocols in home-care nursing networks. ANVISA medical device registration requirements slow foreign product entry, preserving market share for validated local distributors. São Paulo's healthcare procurement concentration dominates national contract allocation, marginalizing smaller regional hospital systems.
China
Raw cotton processing scale and synthetic fiber manufacturing density position the country as a cost-competitive converter base for export markets. NMPA medical device classification and GB standards compliance create dual-track regulatory complexity for products serving domestic versus international customers. The Yangtze River Delta manufacturing belt concentrates woven textile capacity that supplies both finished goods and intermediate materials to regional assemblers.
Gauze Bandage Rolls Market Competitive Landscape
Top-tier vendors anchor hospital-centric contract purchasing, while mid-scale converters defend position in specialized applications and regional distribution. The market structure reflects tiered consolidation: a handful of integrated health systems suppliers lock in multi-year agreements with major delivery networks, while smaller players compete on flexibility and niche certification. Three archetypes dominate: scale-driven contract manufacturers, R&D-intensive specialty formulators, and regionally focused distribution specialists. Competitive moves concentrate on sterilization capacity expansion and backward integration into raw textile processing to secure margin control.
Among North American distributors, Cardinal Health and Medline Industries exemplify the scale-driven archetype, with the former representing hospital-centric contract consolidation and the latter anchoring home-health network penetration. Paul Hartmann AG occupies a position within the European specialty tier, reflecting the R&D-intensive formulator model concentrated in German wound-care innovation clusters. These three names illustrate how geographic origin and organizational structure map onto divergent strategic positioning across institutional versus post-acute channels.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| 3M Company |
| Johnson & Johnson |
| Paul Hartmann AG |
| Smith & Nephew |
| Dynarex Corp. |
| BSN medical |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Integrated delivery network consolidation into multi-year supply agreements is compressing spot-market liquidity and forcing converters toward contract-based capacity allocation with tiered volume discounts. This procurement concentration rewards sterilization-validated suppliers with pricing power while marginalizing non-compliant inventory.
Pricing Analysis
Short lead-time premiums command measurable spreads over standard contract pricing as EPA ethylene oxide emission constraints tighten sterilization queue availability. Three-tier pricing structure across antimicrobial-impregnated premium, validated sterile standard, and non-sterile economy levels reflects certification burden differentials. Cost compression in cotton-woven tiers is intensifying because raw fiber volatility outpaces converter hedging capacity. Home-care nursing networks exhibit highest price sensitivity due to reimbursement code constraints, while burn centers demonstrate lowest sensitivity given outcome-critical procurement protocols.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand through consignment arrangements, while distributor intermediaries serve ambulatory and clinic segments. Manufacturing gravity centers on India, China, and Vietnam for woven textile processing, with Germany and the United States anchoring specialty sterilization and R&D functions. Raw cotton draws from Mississippi Delta, Gujarat, and Xinjiang growing regions, with synthetic fiber feeds from Yangtze River Delta petrochemical complexes. Single-source vulnerability concentrates in FDA-registered ethylene oxide sterilization facilities, where converter queue access determines product launch viability. Distribution runs through group purchasing organization contracts for hospital systems and specialized home-care pharmacy networks for post-acute channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA sterilization emission constraints and CDSCO import certification tightening are accelerating margin compression for undifferentiated converters, forcing asset-light exits and consolidation around validated capacity holders.
For Market Incumbents: Deepen backward integration into raw cotton ginning and weaving operations in Gujarat and Tamil Nadu to capture PLI scheme incentives and insulate against fiber price volatility. Expand alternative sterilization validation capacity beyond ethylene oxide dependencies to defend against EPA queue bottlenecks. Lock multi-year consignment arrangements with Medicare Advantage-integrated delivery networks before reimbursement code stabilization freezes channel access. For New Entrants and Emerging Players: Enter via underpenetrated home-care nursing networks in Brazil's São Paulo and Rio de Janeiro metropolitan corridors, where post-operative monitoring infrastructure gaps create white space for sterile gauze bundled with remote patient monitoring protocols. Target tier-two Indian hospital clusters in Jaipur, Lucknow, and Coimbatore facing inventory buildout deficits against surgical volume expansion. Pursue ANVISA fast-track registration to bypass incumbent distributor relationships in government hospital tenders. For Investors and Strategic Acquirers: The window for entry favors sterilization-validated mid-cap converters with established CDSCO track records and export-qualified capacity under India's PLI scheme. Long-term viability hinges on regulatory compliance moats deepening over the projection horizon, rewarding platforms with dual FDA-CDSCO validation pathways. Acquisition targets should demonstrate captive raw textile processing and alternative sterilization method approvals. Monitor EPA ethylene oxide facility closure announcements as inflection indicators for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Method Diversification | Gamma and e-beam validation reduces EPA ethylene oxide queue dependency for launch timelines. |
| Backward Integration into Raw Cotton Processing | Gujarat-based ginning operations capture PLI incentives and insulate margin from commodity volatility. |
| Home-Care Distribution Partnership | Medicare Advantage consignment arrangements lock post-acute channel access before reimbursement stabilization. |
| CDSCO Export Qualification | BIS certification enables government hospital tender participation against import substitution mandates. |
| Antimicrobial Coating R&D Investment | Chitosan and silver-impregnated formulations command premium positioning in infection-prevention protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and home-care nursing coordinators. FDA 510(k) clearance databases, CDSCO import registration logs, EPA emission compliance reports, and Indian textile export statistics provided validation cross-checks. Bottom-up shipment estimates from converter capacity utilization triangulated against top-down healthcare expenditure allocation models.
Segment-level modeling tracked product type, application, end user, and packaging configuration dimensions across the projection horizon. Volume forecasts incorporated surgical procedure growth trajectories, post-acute discharge protocol penetration rates, and sterilization capacity expansion pipelines. Value outputs reflected raw material cost pass-through elasticity, certification premium persistence, and channel markup compression dynamics. CAGRs derived from logistic growth curve fitting against historical consumption patterns and policy-driven inflection assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA sterilization regulatory acceleration or Indian import tariff recalibration scenarios. Periodic stress-testing of base assumptions is recommended, particularly around cotton commodity price trajectories and home-care reimbursement code evolution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Global Traditional Wound Management Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Italy Wound Care Market
Wound Care
Vascular Dressings Market
Wound Care
Maggot Debridement Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
US Burn Care Centers Market
Wound Care
Wound Management Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Advanced Wound Management Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Surgical Wound Care Market
Wound Care
Venous Skin Ulcer Treatment Market