
 Smart Bandages and Smart Wound Dressings Market | 2026-2036
Smart Bandages and Smart Wound Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bandages and Smart Wound Dressings Market Intelligence
Hospital procurement dominance is unwinding as home care agencies and long-term care facilities gain purchasing share for connected wound management systems. Smith & Nephew leverages its negative-pressure portfolio to anchor post-acute channel relationships. 3M Company sustains material science leadership through proprietary adhesive platforms that reduce skin trauma during dressing changes. Coloplast A/S differentiates via urology-to-wound-care cross-selling infrastructure across European and North American home health networks.
Smart bandages and smart wound dressings comprise advanced wound care substrates integrated with biosensors, conductive polymers, or drug-eluting matrices that monitor exudate pH, temperature, or infection biomarkers and transmit data wirelessly to clinical decision systems; these devices primarily serve to reduce healing time, prevent hospital-acquired infections, and enable remote patient monitoring outside institutional settings. Hydrocolloid and foam variants dominate current volume due to established reimbursement codes and clinician familiarity, while wireless-enabled sensor dressings represent the fastest-expanding margin pool as payors pilot value-based contracts for chronic wound management. Antimicrobial technology segments occupy defensive positions against antibiotic-resistant pathogens, though nanotechnology coatings face manufacturing scale constraints that limit near-term cost competitiveness.
FDA 510(k) digital health guidance and EU MDR Class IIa requirements for active therapeutic devices are tightening clinical evidence standards for sensor-integrated dressings, directly shaping R&D investment priorities and market access timelines. HIPAA interoperability rules in the United States and GDPR health data provisions in Europe constrain cloud architecture choices for wireless transmission platforms, favoring vendors with compliant infrastructure investments. Stakeholders must monitor FDA breakthrough device designations and EU notified body capacity bottlenecks to calibrate regulatory capital deployment against commercial launch windows.
Market Dynamics
The transition from institutional to home-based wound care is compressing traditional hospital procurement hierarchies and forcing sensor-integrated dressing vendors to build direct-to-provider distribution capabilities.
Growth Catalysts
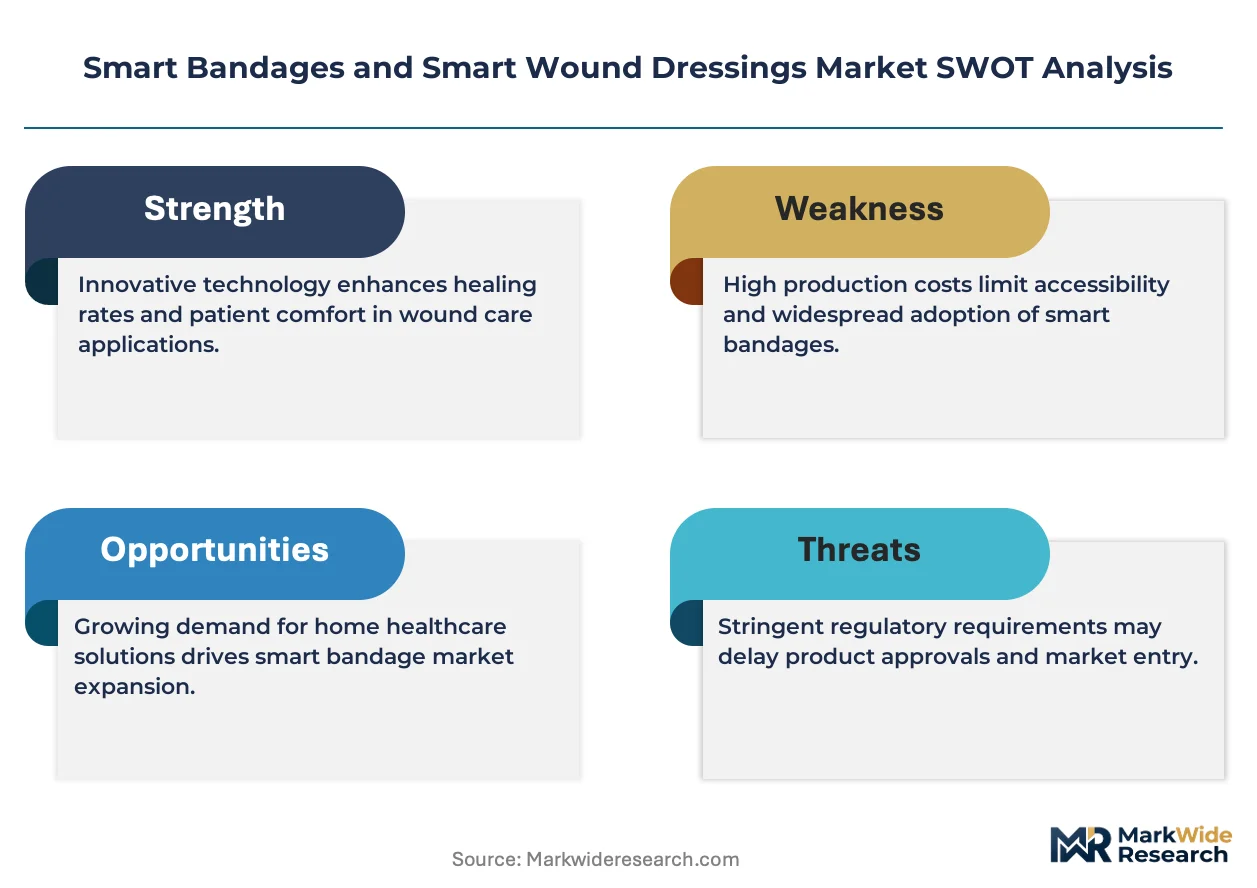
- FDA 510(k) digital health pathway:The streamlined clearance mechanism for software-enabled medical devices accelerates commercialization timelines for wireless biosensor dressings seeking post-acute market entry.
- Home health agency networks:Medicare reimbursement shifts toward remote patient monitoring codes enable long-term care facilities to bill for connected dressing data transmission.
- Conductive polymer substrates:Advances in flexible electronics manufacturing reduce per-unit sensor costs and expand addressable patient populations beyond premium surgical segments.
Market Restraints
- Silver and copper nanomaterial inputs:Antimicrobial coating supply chains face price volatility from mining concentration in Chile and Peru, compressing gross margins for advanced dressing manufacturers.
- EU MDR Class IIa clinical evidence requirements:The expanded notified body scrutiny for active therapeutic devices extends regulatory timelines and consumes R&D capital before revenue realization.
- Conventional negative-pressure wound therapy:Established reimbursement codes and clinician training infrastructure create switching friction against sensor-integrated alternatives in hospital settings.
Strategic Opportunities
- Rural health clinic networks:Underserved geographies in the United States lack specialist wound care access, creating first-mover advantage for remote monitoring platform vendors.
- GDPR-compliant edge computing architectures:European data localization requirements favor vendors with regional cloud infrastructure investments over centralized US-based systems.
- AI-enabled predictive analytics:Integration of machine learning algorithms with continuous pH and temperature monitoring enables infection early-warning systems that justify premium pricing.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of materials science, wireless communications, and clinical validation requires hybrid skill sets that command premium compensation and extend hiring timelines.
- HIPAA interoperability certification:Health data exchange standards mandate complex API development and third-party auditing that delays product launches by 12-18 months.
- Legacy electronic health record integration:Hospital IT systems require custom middleware development to ingest real-time dressing sensor data, fragmenting deployment resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bandages and Smart Wound Dressings Market |
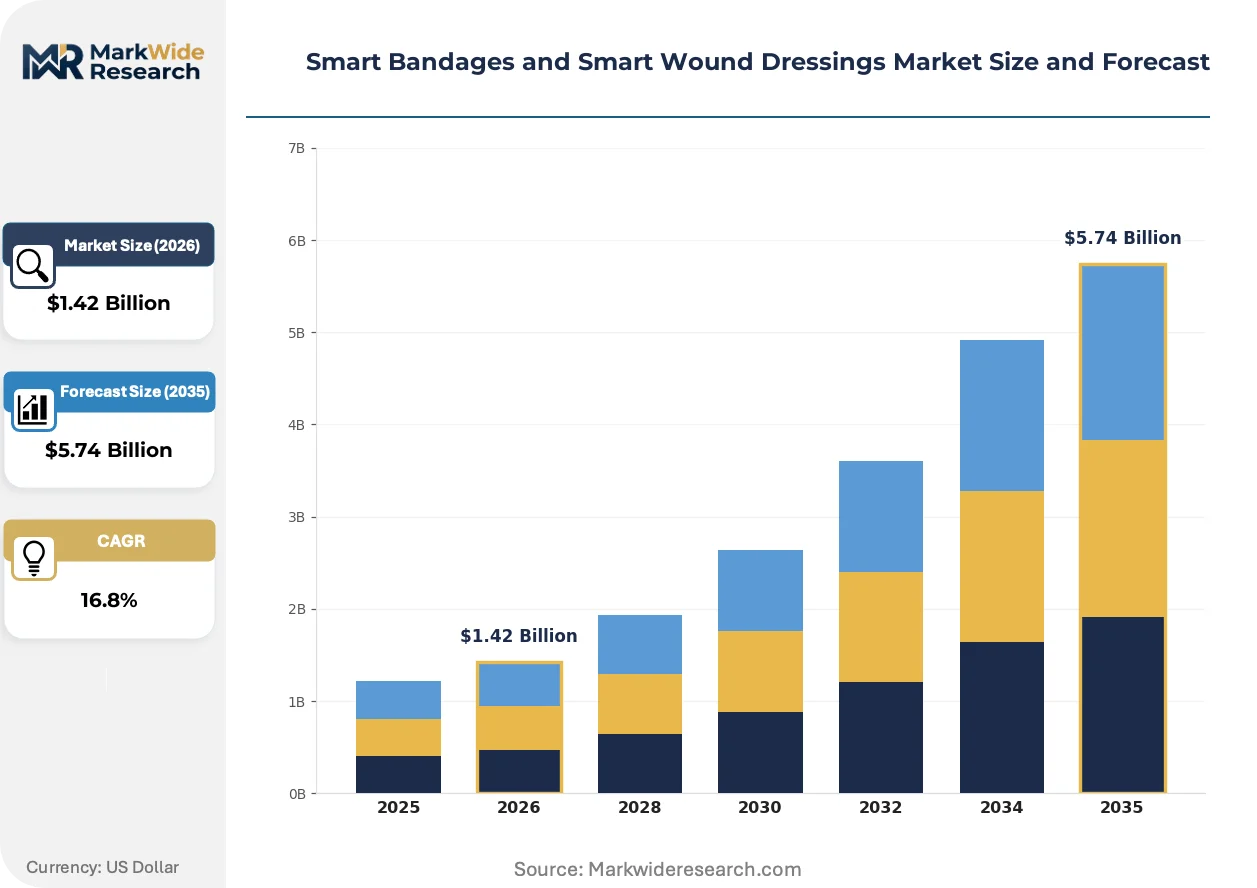
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid, Foam, Film, Composite Technology: Smart Sensors, Antimicrobial, Nanotechnology, Wireless End User: Hospitals, Home Care, Clinics, Long-Term Care Application: Chronic Wounds, Acute Wounds, Surgical Sites, Burns |
| Companies Covered | Johnson & Johnson, Coloplast A/S, Medtronic, Baxter International Inc., Acelity L.P. Inc., 3M Company, ConvaTec Group, Integra LifeSciences Corporation, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bandages and Smart Wound Dressings Market Strategic Shifts & Innovations
Wireless biosensor miniaturization and cloud-native clinical platforms are converging to enable continuous wound monitoring outside traditional care settings, restructuring how healing outcomes are measured and reimbursed.
Printed electronics using graphene and silver nanowire inks is decomposing the cost barrier between passive and active wound dressings. Home health agencies in the United States are piloting these substrates for diabetic foot ulcer management. The technology is decomposing the historical distinction between monitoring devices and consumable dressings into single-use integrated products.
EU MDR Class IIa requirements for active therapeutic devices are tightening clinical evidence standards for sensor-integrated dressings entering European markets. Manufacturers must now generate prospective clinical data rather than relying on predicate device equivalence. German notified bodies are experiencing capacity bottlenecks that extend review timelines and favor larger vendors with dedicated regulatory affairs teams.
Post-acute care procurement is consolidating purchasing decisions through integrated delivery networks and group purchasing organizations. Independent home health agencies are losing negotiating leverage as regional health systems centralize wound care supply contracts. This concentration is most visible in the United States, where Medicare Advantage plans are steering patients toward network-affiliated home care providers with standardized technology platforms.
Smart Bandages and Smart Wound Dressings Market Segmentation
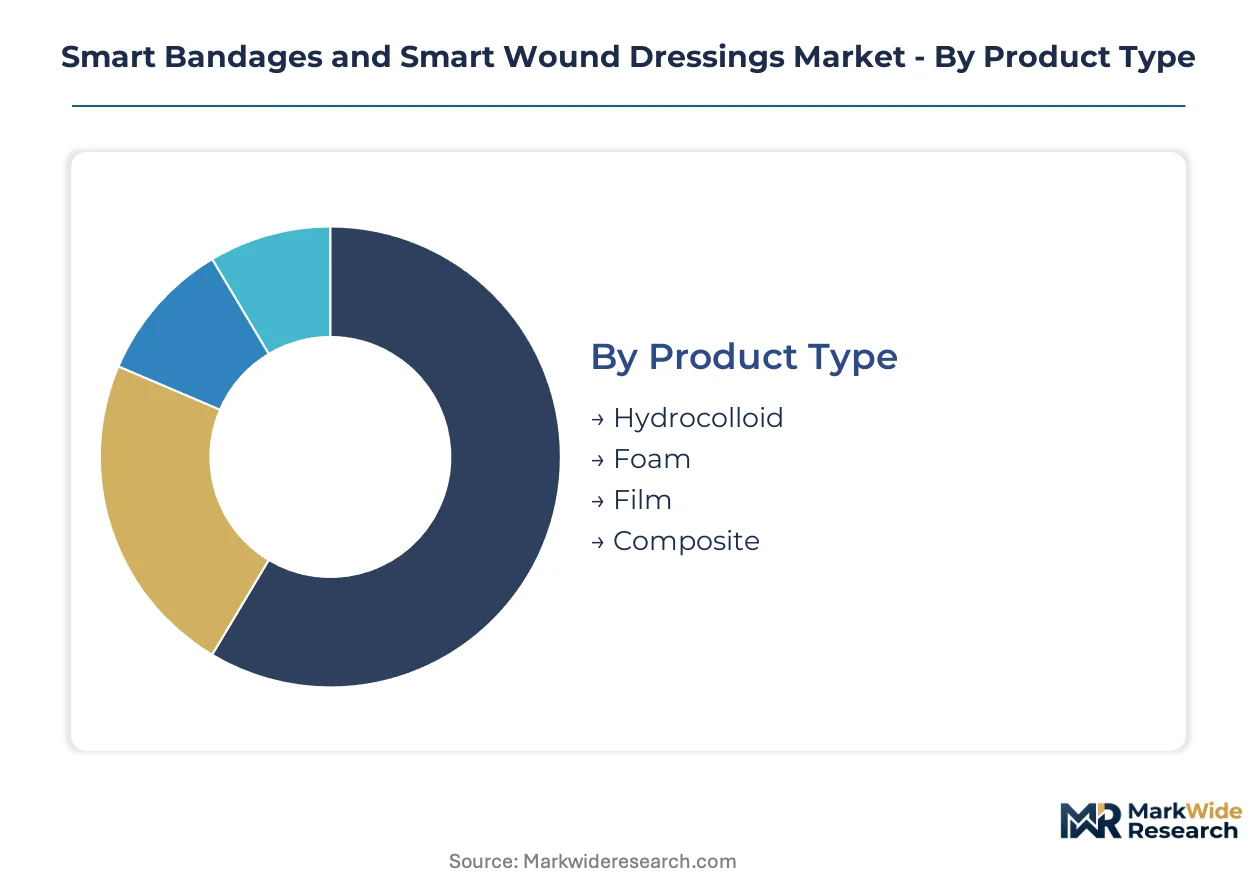
Smart bandages and smart wound dressings require granular segmentation to capture divergent margin profiles across substrate technologies, sensing capabilities, and care settings. Each dimension reveals distinct procurement hierarchies and reimbursement pathways that shape vendor positioning.
Product Type:
Margin pools concentrate in composite substrates that integrate multiple functional layers, while foam and hydrocolloid variants defend volume positions through established reimbursement codes.
- Hydrocolloid:Gel-forming substrates composed of carboxymethylcellulose, pectin, and gelatin that absorb exudate while maintaining moist wound environments. Demand concentrates in United States home care networks where Medicare Advantage plans favor familiar dressing categories with predictable billing pathways.
- Foam:Polyurethane or silicone-based absorbent layers with vapor-permeable backings designed for moderate-to-heavy exudate management. Long-term care facilities in Germany and France are expanding procurement of foam variants with integrated pressure redistribution for pressure ulcer prevention protocols.
- Film:Thin polyurethane membranes with adhesive perimeters that enable moisture vapor transmission while blocking bacterial ingress.
- Composite:Multi-layer constructions combining absorbent cores, barrier films, and contact layers for complex wound presentations.
Hydrocolloid holds installed capacity. Composite is rotating up the share rankings.
Technology:
Wireless-enabled platforms command premium pricing tiers, while antimicrobial coatings defend baseline positions against hospital-acquired infection liability.
- Smart Sensors:pH, temperature, and impedance biosensors printed onto flexible substrates using conductive polymer inks. United States integrated delivery networks are piloting these for post-surgical remote monitoring where CMS remote patient monitoring codes enable reimbursement.
- Antimicrobial:Silver, iodine, or polyhexamethylene biguanide (PHMB) eluting matrices that suppress bacterial colonization. Hospital procurement committees in Japan favor antimicrobial dressings for surgical site infection reduction given METI quality metrics tied to reimbursement penalties.
- Nanotechnology:Copper or zinc oxide nanoparticle coatings with enhanced surface area-to-volume ratios for antimicrobial efficacy.
- Wireless:Bluetooth Low Energy or NFC-enabled dressings transmitting sensor data to cloud platforms.
Antimicrobial technology holds installed capacity. Wireless is climbing the fastest among technology segments.
End User:
Procurement authority is migrating from hospital supply chains toward home care agencies as reimbursement frameworks evolve for remote monitoring.
- Hospitals:Acute care facilities with centralized purchasing through group purchasing organizations and value analysis committees. United States hospital systems are consolidating wound care contracts under integrated delivery network umbrellas, reducing vendor count per network.
- Home Care:Medicare-certified home health agencies and private duty nursing services. United Kingdom NHS Integrated Care Boards are expanding procurement of connected dressings for diabetic foot ulcer management to reduce amputation rates and emergency admissions.
- Clinics:Outpatient wound care centers and physician office-based procedures.
- Long-Term Care:Skilled nursing facilities and assisted living residences with pressure ulcer prevention mandates.
Hospitals hold installed capacity. Home Care is rotating up the share rankings.
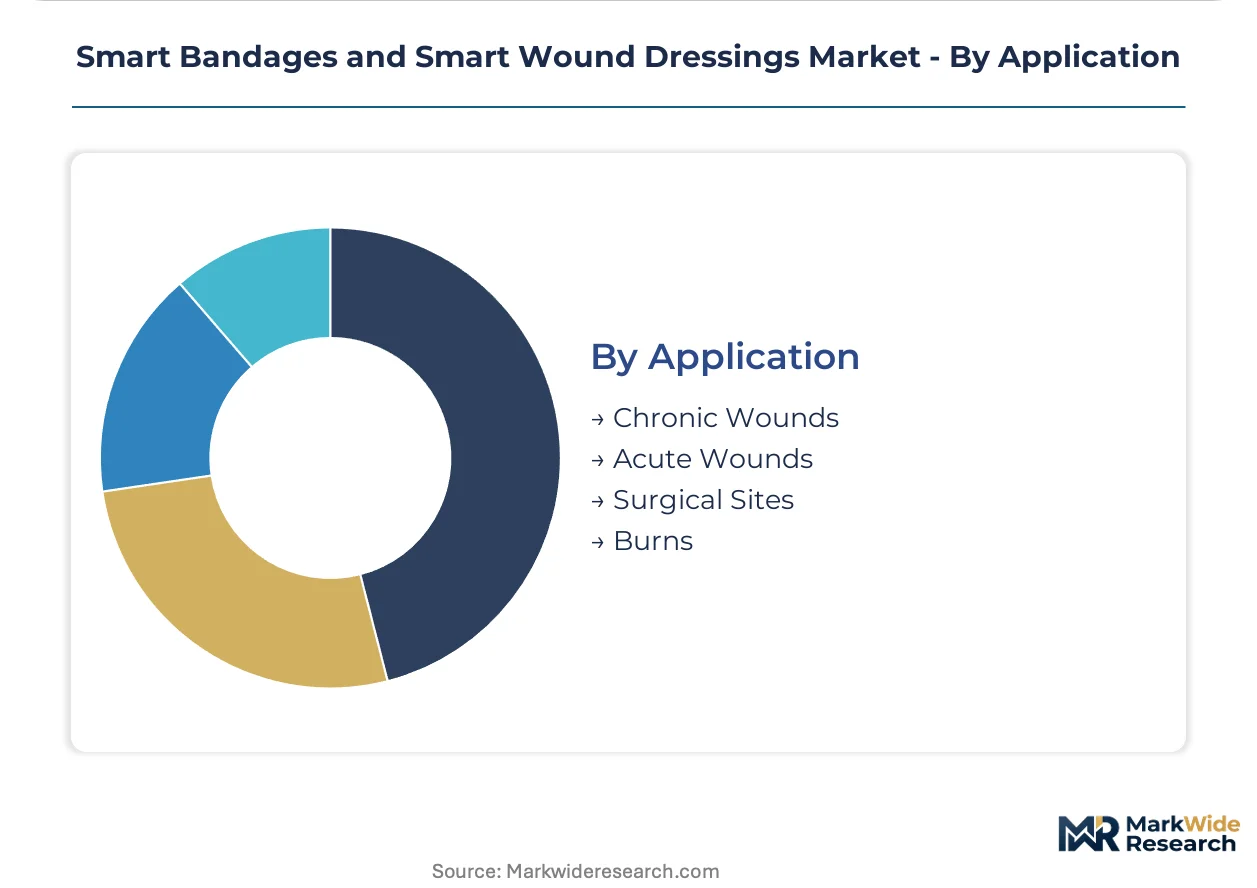
Application:
Chronic wound categories sustain recurring revenue models through extended treatment durations, while surgical applications concentrate volume in shorter cycles.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries with healing trajectories exceeding four weeks. United States wound care clinics are prioritizing sensor-integrated dressings for diabetic foot ulcers given CMS quality measures linking amputation rates to facility reimbursement.
- Acute Wounds:Traumatic injuries, abrasions, and lacerations requiring rapid closure and infection prevention. Emergency departments in Australia are expanding procurement of antimicrobial composite dressings for trauma presentations under TGA streamlined approval pathways.
- Surgical Sites:Incisional wounds from operative procedures requiring post-discharge monitoring.
- Burns:Partial-thickness and full-thickness thermal injuries requiring specialized moisture management and infection control.
Chronic Wounds hold installed capacity. Surgical Sites is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites Europe's distribution dominance for advanced wound care substrates, while Singapore's biomedical manufacturing hub anchors Asia-Pacific sensor integration capabilities.
United States
Medicare remote patient monitoring reimbursement codes drive home health agency procurement of connected dressings. FDA 510(k) digital health guidance accelerates commercialization timelines for wireless biosensor platforms. Greater Boston's medtech cluster concentrates venture capital deployment into conductive polymer startups targeting post-surgical monitoring applications.
Germany
Integrated care contracts under statutory health insurance expand procurement of sensor-integrated dressings for chronic wound management. EU MDR Class IIa requirements tighten clinical evidence standards for active therapeutic devices entering European markets. The Rhine-Ruhr industrial corridor hosts manufacturing scale-up facilities for printed electronics using graphene and silver nanowire substrates.
United Kingdom
NHS Integrated Care Boards prioritize connected dressing procurement to reduce diabetic foot ulcer amputation rates and emergency admissions. GDPR health data provisions constrain cloud architecture choices for wireless transmission platforms, favoring vendors with regional infrastructure investments. The Cambridge-Oxford-London golden triangle anchors academic-industry partnerships developing AI-enabled predictive analytics for infection early-warning systems.
Japan
METI quality metrics tied to reimbursement penalties drive hospital procurement of antimicrobial dressings for surgical site infection reduction. PMDA streamlined approval pathways for software-enabled medical devices accelerate market entry for wireless biosensor platforms. The Kansai region's electronics manufacturing base supplies flexible printed circuit substrates for miniaturized wound monitoring sensors.
Australia
TGA streamlined approval pathways expand emergency department procurement of antimicrobial composite dressings for trauma presentations. The country's national pharmaceutical regulator maintains alignment with FDA breakthrough device designation criteria for sensor-integrated platforms. Sydney's biomedical precinct hosts clinical validation trials for pH and temperature monitoring dressings targeting rural health clinic networks.
Smart Bandages and Smart Wound Dressings Market Key Industry Players
Listed leaders compete with private specialists across regulatory capital deployment and channel access capabilities. The vendor base stratifies into three tiers: diversified medtech conglomerates with negative-pressure portfolios, adhesive and materials science specialists with proprietary substrate platforms, and emerging sensor-technology ventures with digital health focus. Dominant competitive moves include M&A activity targeting wireless biosensor capabilities and strategic partnerships with integrated delivery networks for post-acute channel penetration.
Within the diversified medtech tier, Johnson & Johnson and Medtronic exemplify scale-driven players with established hospital procurement relationships and regulatory affairs infrastructure spanning multiple geographies. Coloplast A/S represents the specialized channel archetype, leveraging cross-selling infrastructure across European and North American home health networks. Smith & Nephew occupies a position anchoring post-acute relationships through negative-pressure wound therapy installed base and clinician training programs.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Coloplast A/S |
| Medtronic |
| Baxter International Inc. |
| Acelity L.P. Inc. |
| 3M Company |
| ConvaTec Group |
| Integra LifeSciences Corporation |
| Smith & Nephew |
| Others |
Cost & Logistics Intelligence
Printed electronics capacity utilization above eighty percent in German manufacturing clusters compresses per-unit sensor costs and establishes price floors that smaller substrate vendors cannot match. Scale economies in conductive polymer roll-to-roll processing concentrate bargaining power among three European material suppliers, forcing downstream dressing manufacturers into long-term offtake commitments that lock in margin structures.
Pricing Analysis
Volume-discount tiering separates enterprise integrated delivery network contracts from independent home health agency spot purchases. Three-tier pricing structure across premium wireless-enabled sensor dressings, standard antimicrobial composites, and economy hydrocolloid base layers reflects certification grade differentiation and FDA 510(k) clearance status. Cost compression in the economy tier is intensifying because Chinese substrate entrants are undercutting European material costs by fifteen to twenty percent on comparable foam backings. Independent home health agencies exhibit highest price sensitivity due to thin Medicare reimbursement margins, while United States hospital systems accept premium tier pricing for liability reduction and outcome guarantees.
Supply Chain Analysis
Chile and Peru anchor silver and copper nanomaterial mining concentration for antimicrobial coating inputs. South Korea and Taiwan supply flexible printed circuit substrates for biosensor miniaturization. Raw material dependencies rest on graphene ink formulations from German chemical specialists and silver nanowire dispersions from Japanese electronics material firms. Single-source vulnerability concentrates in Chilean copper concentrate exports, where labor disruptions at major mines have triggered input price spikes. Distribution runs through Port of Rotterdam pharmaceutical logistics corridors for European markets and Singapore biomedical manufacturing hubs for Asia-Pacific sensor integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote patient monitoring data subscriptions expand recurring revenue pools faster than consumable dressing hardware sales, transforming vendor economics toward software-attach models. Cloud platform licensing and predictive analytics modules now generate margin multiples exceeding substrate manufacturing by a factor of three.
For Market Incumbents: Compound installed base advantages in negative-pressure wound therapy by bundling sensor-integrated dressings into existing clinician training programs and GPO contract renewals. Defend against emerging conductive polymer startups by acquiring FDA 510(k) clearance for wireless platforms before reimbursement codes solidify. Prioritize backward integration into silver nanomaterial supply through offtake agreements with Chilean mining consortiums to offset input volatility. For New Entrants and Emerging Players: Rural health clinic networks in the United States represent the most penetrable segment, where specialist wound care access gaps exceed two hundred miles in twelve states. Target Medicare Advantage plan technology pilots by offering GDPR-compliant edge computing architectures that incumbent cloud-centralized platforms cannot match. Pursue direct-to-provider distribution bypassing consolidated integrated delivery network procurement hierarchies. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid material-digital ventures with FDA breakthrough device designations and proprietary conductive polymer patents. Five-to-ten year viability hinges on reimbursement code expansion rather than clinical efficacy alone. Acquisition target archetype: sensor-technology ventures with CMS remote patient monitoring billing pathway validation and hospital system pilot contracts. Watch FDA 510(k) clearance velocity for wireless biosensor dressings as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Digital Health Pathway | Accelerates commercialization timelines for wireless biosensor dressings seeking post-acute market entry under streamlined software-enabled device guidance. |
| Hospital System Partnership | Integrated delivery network contracts consolidate purchasing decisions and reduce vendor count per network through standardized technology platforms. |
| Software Companion Development | AI-enabled predictive analytics integration with continuous pH monitoring justifies premium pricing through infection early-warning capabilities. |
| CE Marking Pathway | EU MDR Class IIa clinical evidence requirements favor larger vendors with dedicated regulatory affairs teams over emerging entrants. |
| Reimbursement Strategy | Medicare remote patient monitoring code alignment enables home health agency billing for connected dressing data transmission. |
Research Approach
Cross-validation between primary interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR notified body submissions, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up demand modeling triangulates against top-down market sizing across substrate technology, sensing capability, and care setting segmentation dimensions.
Sensitivity analysis frameworks test forecast robustness across regulatory approval timeline scenarios and reimbursement code adoption curves. The analytical framework models product type, technology tier, end-user channel, and application severity dimensions throughout the forecast period. CAGRs derive from weighted average growth contributions across segment-level demand trajectories, incorporating conductive polymer cost reduction curves and wireless biosensor adoption elasticity estimates.
Forecasts assume regulatory continuity in FDA 510(k) digital health guidance and EU MDR Class IIa active therapeutic device requirements; material policy shifts would require re-modeling. Specific risk factors that could revise projections include notified body capacity bottlenecks extending European approval timelines, silver nanomaterial supply disruptions from Chilean labor actions, and HIPAA interoperability rule changes affecting cloud architecture compliance costs. Recalibration cycles align with material shifts in CMS reimbursement code expansions and breakthrough device designation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Care Sealants Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Dental Wound Dressings Market
Wound Care
Advanced Wound Management Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Wound Closure Devices Market
Wound Care
Wound Closure Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Alginate Dressing Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Wound Retractor Market
Wound Care
Wound Drainage Devices Market
Wound Care
North America Wound Care Management Market
Wound Care
Global Wound Dressings Market