
 Global Defense Tactical Radio Market | 2026-2036
Global Defense Tactical Radio Market Size, Share, and Industry Trends Forecast 2026-2036
Global Defense Tactical Radio Market Intelligence
The Software Communications Architecture (SCA) standard, a legacy of the US JTRS program, is unwinding as the primary gatekeeper for market entry. This shift opens opportunities beyond traditional prime contractors. L3Harris Technologies leverages its extensive portfolio of SCA-compliant and non-SCA radios to serve diverse mission needs. Thales Group competes on its strength in waveform development and secure communications, particularly within European and export markets. General Dynamics Corporation sustains its position through deep integration with armored vehicle platforms.
A defense tactical radio is a ruggedized, secure communication device engineered for military field operations. These systems operate across HF, VHF, and UHF bands, utilizing advanced AES-256 encryption to ensure secure voice and data transmission. While vehicular radios constitute a large segment tied to platform modernization cycles, handheld and manpack radios represent the fastest-growing product types due to soldier-level digitization initiatives. Software Defined Radio architecture has become the baseline technology, displacing legacy single-purpose systems across all applications.
Market access is governed by stringent military specifications and national security regulations, including the US International Traffic in Arms Regulations (ITAR) and NATO Standardization Agreements (STANAGs). These frameworks mandate specific encryption, anti-jamming, and waveform interoperability standards, defining the competitive landscape. Vendors must therefore decide whether to pursue proprietary, high-performance systems or align with emerging open-architecture consortiums to ensure future relevance.
Market Dynamics
The fundamental dynamic is the transition from proprietary, single-vendor radio systems toward open-architecture frameworks. This shift, driven by military requirements for multi-vendor interoperability and faster technology upgrades, is reconfiguring the supply chain and competitive landscape for tactical communications.
Growth Catalysts
- Soldier Modernization Programs:National initiatives in countries like India and Poland to equip individual soldiers with networked handheld and manpack radios are creating significant volume demand for new systems.
- Software Defined Radio Architecture:The widespread adoption of SDR technology enables over-the-air updates and new waveform installations, extending the service life of hardware and driving software-related revenue streams.
- NATO Standardization Agreements:Compliance with STANAGs for waveforms and security protocols is a primary driver for procurement within NATO countries, ensuring interoperability during multinational operations and creating a defined market for compliant vendors.
Market Restraints
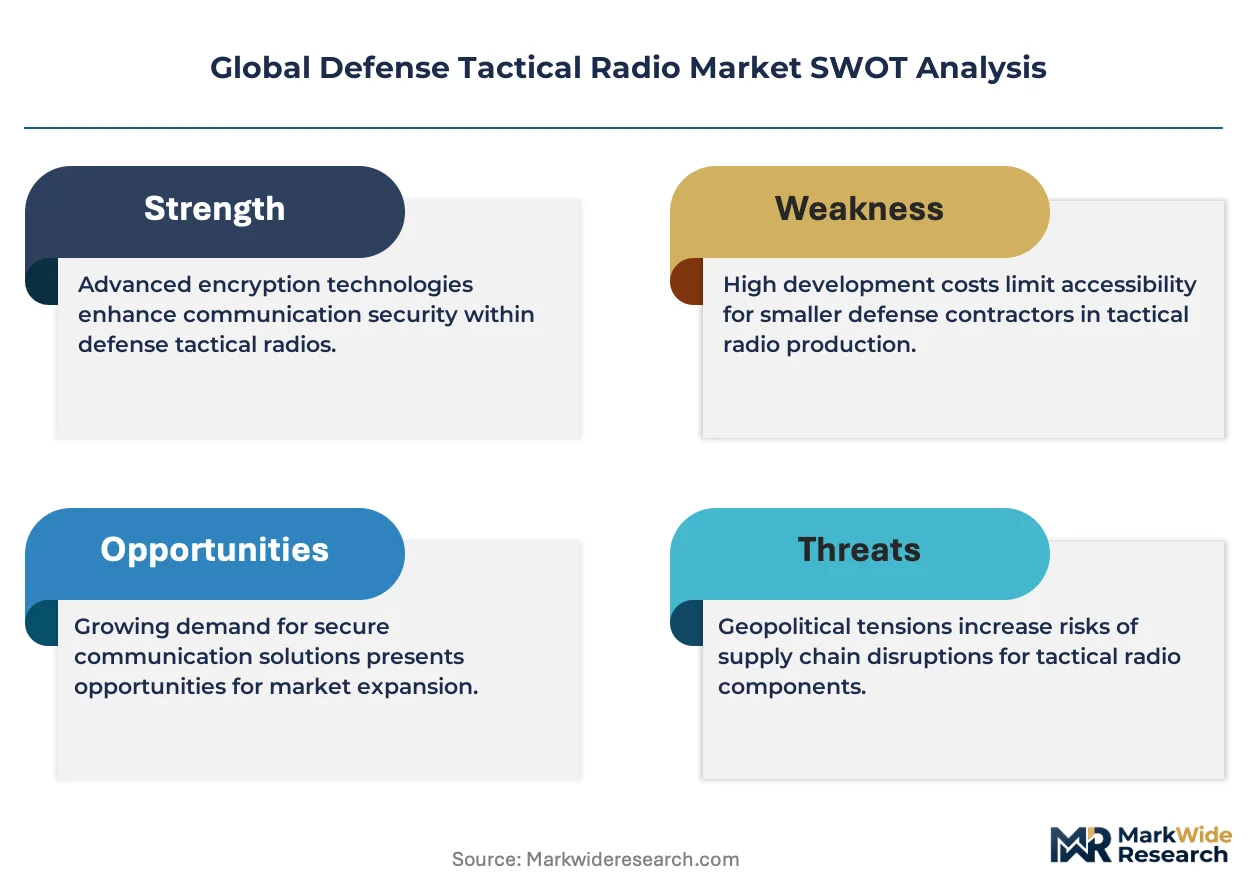
- Export Controls:The US International Traffic in Arms Regulations (ITAR) strictly govern the export of sensitive radio technologies, limiting access to certain markets and creating complex licensing hurdles for manufacturers.
- High Development Costs:The significant investment required for ruggedization, military-standard (MIL-STD) testing, and advanced AES-256 encryption certification presents a substantial barrier to entry for non-incumbent firms.
- Spectrum Scarcity:Increasing congestion and electronic warfare threats in the VHF and UHF bands create significant technical challenges, demanding costly and complex anti-jamming and frequency-hopping capabilities.
Strategic Opportunities
- Unmanned Systems Integration:Developing specialized data links for unmanned aerial and ground vehicles (UAS/UGV) creates a new market for high-throughput, low-latency tactical communications not tied to traditional soldier or vehicle platforms.
- Hybrid 5G Networks:The convergence of tactical waveforms with commercial 5G standards offers the potential to create resilient hybrid networks, enabling new services and high-bandwidth applications in permissible environments.
- Eastern European Modernization:Nations across Eastern Europe are accelerating defense spending and replacing legacy Soviet-era communication systems, creating significant opportunities for Western-standard tactical radio providers.
Industry Challenges
- Legacy System Integration:Military end-users face considerable technical and financial challenges in ensuring new Software Defined Radios can interoperate with the vast and diverse inventory of existing legacy communication systems.
- Evolving Cyber Threats:The transition to IP-based networked radios expands the vulnerability to cyberattacks beyond jamming, demanding continuous software security updates and a new skill set for field maintenance personnel.
- RF and Software Talent Scarcity:A persistent shortage of engineers possessing dual expertise in both radio frequency engineering and modern software development practices slows down product development cycles and innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Defense Tactical Radio Market |
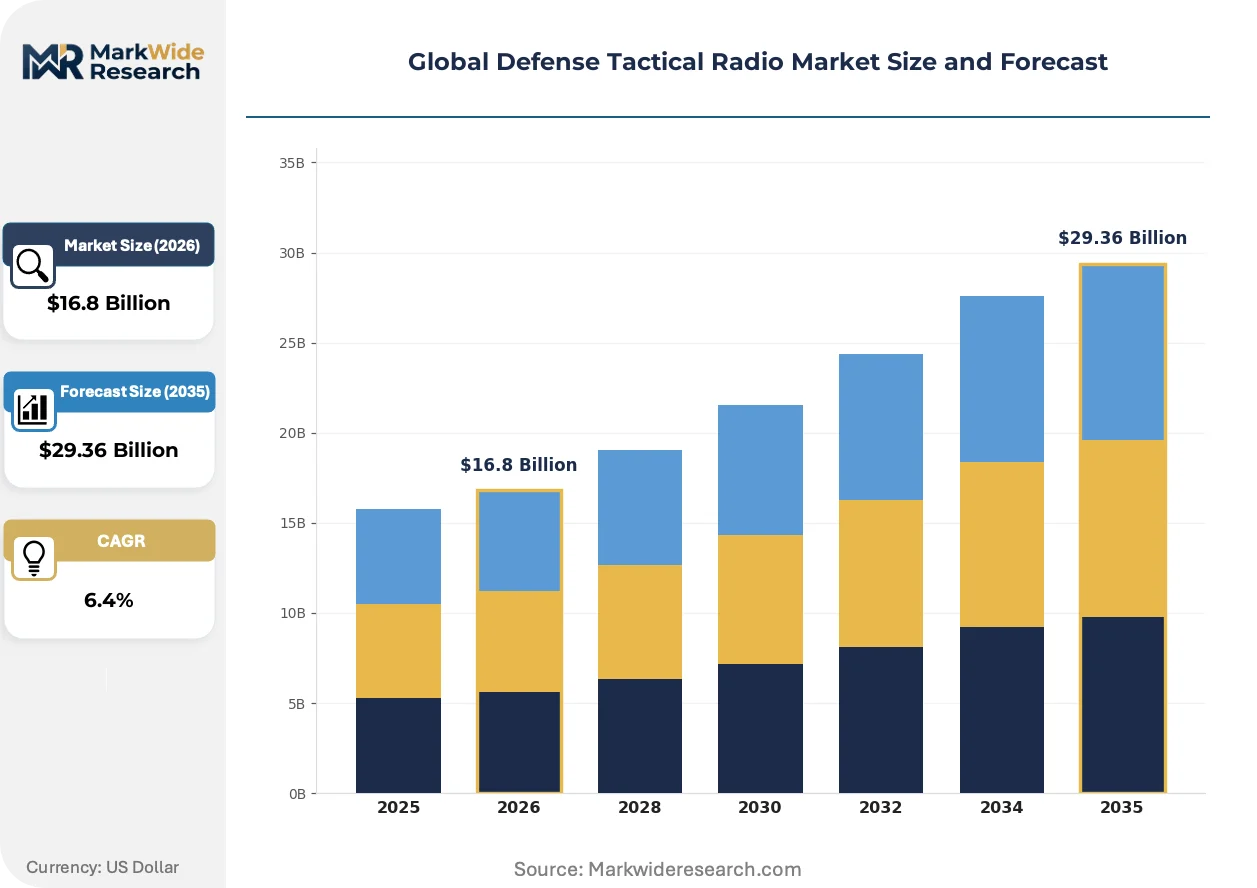
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manpack Radios, Vehicular Radios, Handheld Radios, Base Station Radios Technology: Software Defined Radio, Frequency Hopping, Digital Modulation, Encryption Technology Application: Land Combat, Naval Operations, Airborne Communication, Border Surveillance End User: Army Units, Navy Fleets, Air Force Squadrons, Coastal Security Forces |
| Companies Covered | L3Harris Technologies, Thales Group, General Dynamics Corporation, BAE Systems, Raytheon Technologies, Northrop Grumman Corporation, Leonardo S.p.A., Elbit Systems Ltd., Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Defense Tactical Radio Market Strategic Shifts & Innovations
A fundamental shift is underway where the value proposition migrates from ruggedized hardware to the software defining radio capability. This transition prioritizes waveform agility and network resilience at the tactical edge over traditional hardware-centric performance metrics.
Software Defined Radio (SDR) architecture provides a reconfigurable hardware platform that can be updated with new software. Military forces worldwide are mandating SDR for new procurements to ensure future-proofing. This technology is decomposing the vertically integrated radio system, separating the hardware platform from the waveform and application software and opening the market to specialized developers.
The gradual unwinding of the US military's strict Software Communications Architecture (SCA) as the exclusive standard is a significant policy shift. This change reduces barriers for vendors with non-SCA but capable open-architecture systems. The tactical radio market is now seeing a diversification of software frameworks beyond the original JTRS program's legacy.
Military acquisition is moving from single-vendor contracts to a modular, "best-of-breed" approach for tactical communications. This disrupts the model where a prime contractor provides a complete proprietary system, favoring an ecosystem of specialized hardware and software vendors. This procurement pattern is most evident in Australia and the United Kingdom, which prioritize agile multi-vendor integration.
Global Defense Tactical Radio Market Segmentation
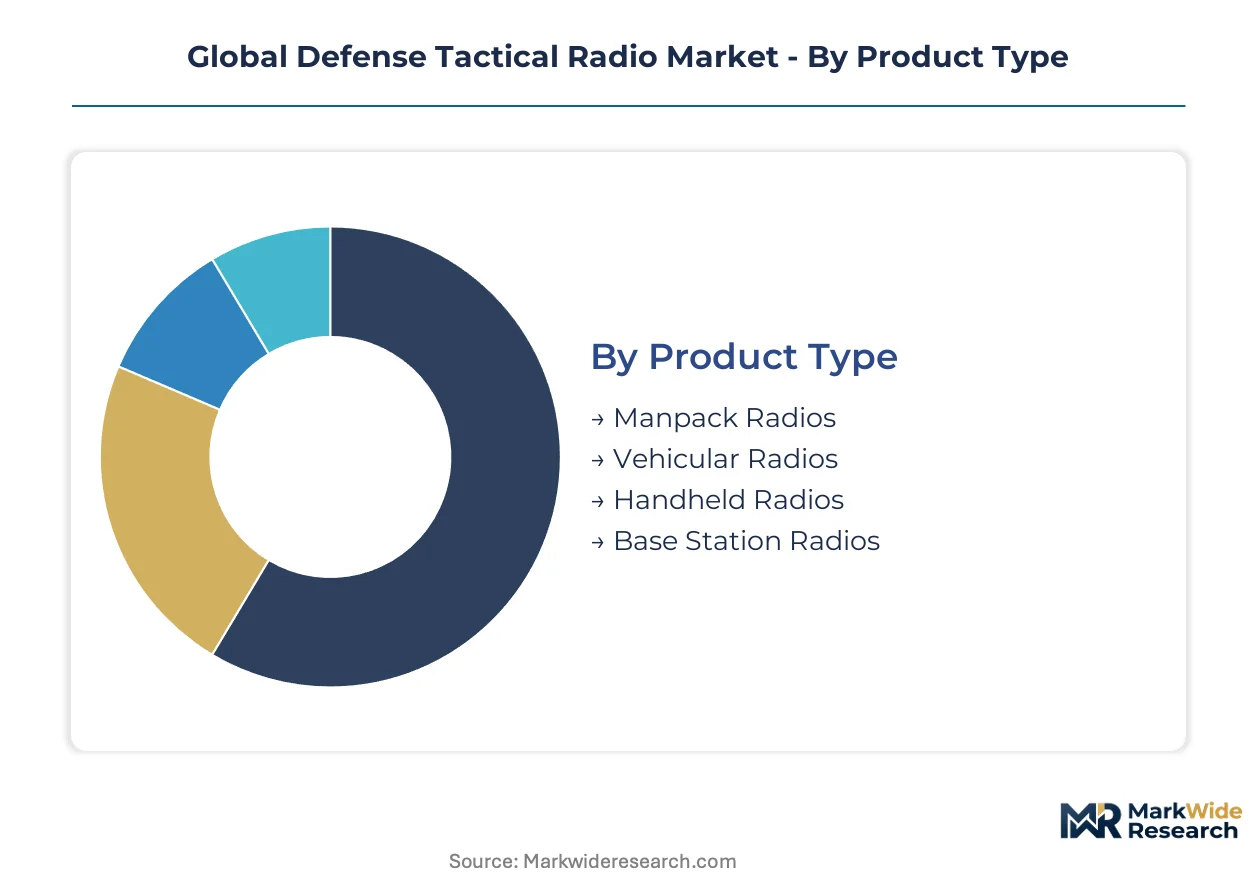
The Global Defense Tactical Radio Market is segmented to provide a detailed understanding of the diverse product offerings, technological advancements, operational applications, and military end-users driving procurement decisions. This granular analysis helps identify specific areas of investment and strategic focus for manufacturers and defense agencies worldwide.
Product Type:
Margin pools within product types are increasingly shifting towards software-centric capabilities embedded within hardware, rather than the hardware itself. This reflects the push for reconfigurable systems.
- Vehicular Radios:These robust communication systems are integrated into armored vehicles and command platforms, providing long-range, high-power communications for mobile operations. Modernization cycles for ground forces, particularly in nations like India and Poland, drive significant demand.
- Handheld Radios:Compact and lightweight devices designed for individual soldiers, these radios facilitate secure voice and data exchange at the tactical edge. Soldier digitization initiatives across NATO allies are fueling their rapid expansion.
- Manpack Radios:Portable, higher-power communication units carried by individual soldiers or small teams, offering extended range and data capabilities beyond handheld devices. These are critical for dismounted operations requiring robust network access.
- Base Station Radios:Fixed or semi-fixed communication hubs providing command and control capabilities, often serving as relays or primary communication nodes for larger operational areas. These units form the backbone of field communication networks.
The dominant share belongs to Vehicular Radios, while Handheld Radios are closing the gap fastest.
Technology:
Cost tiers for defense tactical radio technologies are dictated by the complexity of embedded algorithms and the level of security certification required. Advanced encryption and anti-jamming features command premium pricing.
- Software Defined Radio:This technology provides a reconfigurable hardware platform that can be updated with new waveforms and functionalities via software, ensuring future-proofing and interoperability. Military forces globally, including the US and UK, mandate SDR for new procurements.
- Encryption Technology:Advanced cryptographic algorithms, such as AES-256, are integrated to secure voice and data transmissions against interception and eavesdropping, meeting stringent national security regulations. This is a non-negotiable requirement for all modern tactical radios.
- Frequency Hopping:A spread spectrum technique that rapidly changes carrier frequencies to avoid detection and jamming, enhancing communication resilience in contested electromagnetic environments. This capability is essential for operations in Eastern Europe.
- Digital Modulation:Techniques that convert analog voice and data into digital signals for more efficient, secure, and error-resilient transmission across various frequency bands. This forms the basis for modern battlefield communication.
Software Defined Radio technology is currently the most impactful, and Encryption Technology is experiencing significant innovation.
Application:
The volume of tactical radio deployments varies significantly by application, with ground-based operations historically consuming the largest quantities due to the sheer number of personnel and vehicles. Each application demands specific ruggedization and performance characteristics.
- Land Combat:Tactical radios are essential for ground forces, enabling secure communication between infantry, armored units, and command centers during dismounted and mounted operations. This application accounts for the largest proportion of radio deployments.
- Naval Operations:Specialized radios support ship-to-ship, ship-to-shore, and internal vessel communications, often requiring robust anti-corrosion features and integration with complex naval combat systems. These systems must withstand harsh maritime environments.
- Airborne Communication:Radios integrated into aircraft provide secure voice and data links for pilots, ground control, and air-to-air coordination during missions. These systems prioritize lightweight design and high-speed data transfer.
- Border Surveillance:Communication systems for border patrol units facilitate secure information exchange regarding threat detection, personnel coordination, and intelligence gathering in remote or challenging terrains. These often require extended battery life.
Land Combat applications drive the highest procurement volumes, while Naval Operations require the most complex system integrations.
End User:
Customer type influences procurement specifications and quantities, with large national defense organizations procuring extensive fleets of diverse radio types. Smaller, specialized units often require tailored solutions.
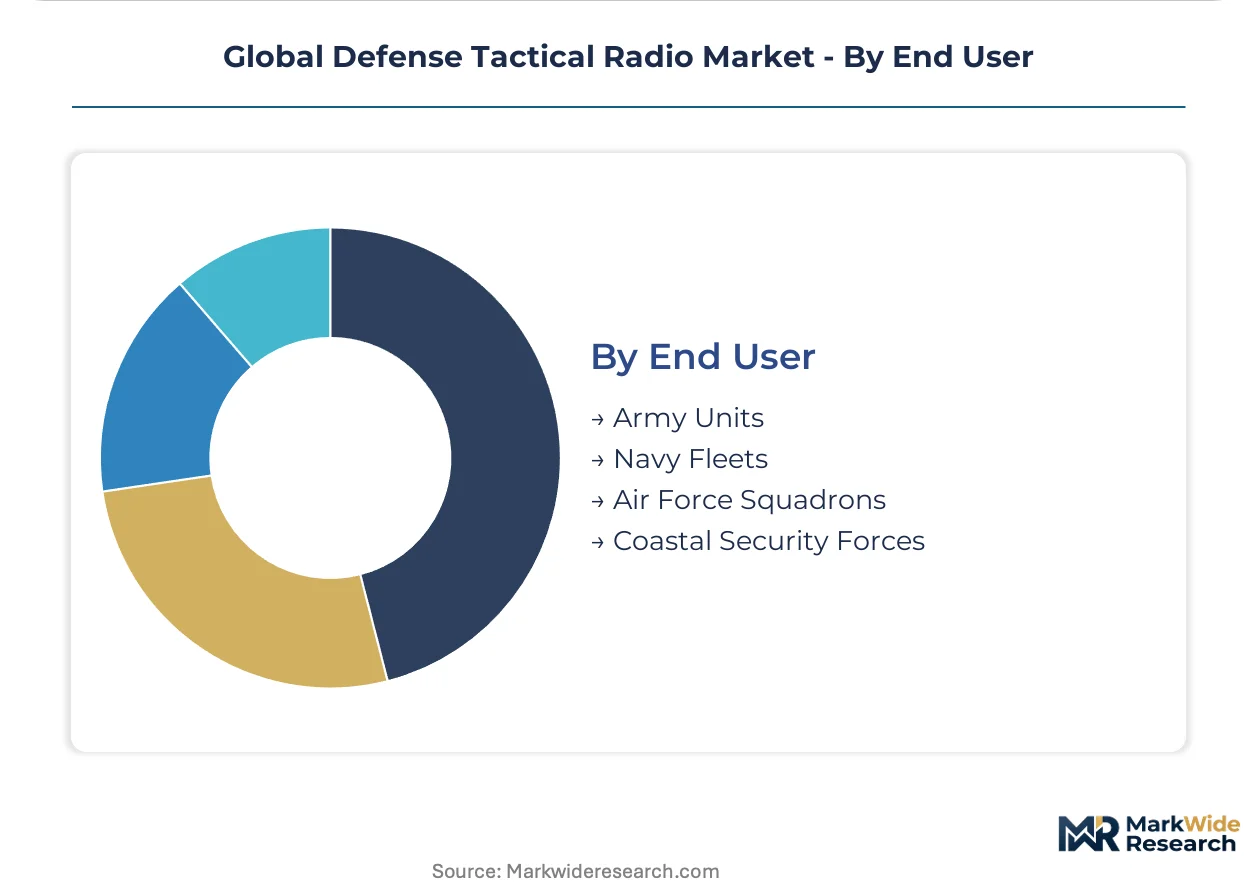
- Army Units:The largest end-user segment, equipping soldiers, vehicles, and command posts with a wide array of handheld, manpack, and vehicular radios for battlefield connectivity. Modernization programs in countries like India focus heavily on army communication upgrades.
- Navy Fleets:Procure specialized radios for surface vessels, submarines, and naval aviation, emphasizing robust, redundant, and secure communication systems for maritime environments. Integration with existing combat systems is a critical factor.
- Air Force Squadrons:Utilize tactical radios for air-to-ground, air-to-air, and ground-to-air communications, demanding highly reliable and interoperable systems. These systems support both combat and transport aircraft.
- Coastal Security Forces:Deploy tactical radios for surveillance, interdiction, and communication along coastlines and territorial waters, often requiring resilient systems capable of operating in challenging coastal conditions. These forces often overlap with naval capabilities.
Army Units represent the largest purchasing segment, and Coastal Security Forces are exhibiting expanding demand for specialized equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global defense spending commitments underwrite the strategic importance of key regions in the tactical radio market. Modernization programs and evolving geopolitical landscapes drive demand for advanced communication systems. These factors ensure sustained investment across major military powers.
United States
Military modernization initiatives and continuous network upgrades propel demand for advanced tactical radios. The US International Traffic in Arms Regulations (ITAR) strictly governs sensitive radio technology exports. Defense contractors in the Washington D.C. area focus on developing next-generation secure communication platforms.
India
Extensive ground force communication network upgrades and soldier digitization initiatives generate substantial demand. The Indian government's Production Linked Incentive (PLI) scheme encourages domestic defense electronics manufacturing. Bengaluru serves as a prominent hub for defense electronics research and development.
Poland
Soldier modernization programs and the imperative for NATO interoperability drive significant procurement. Compliance with NATO Standardization Agreements (STANAGs) for waveforms and security protocols guides defense acquisitions. Warsaw-based defense technology companies actively integrate Western-standard communication systems.
United Kingdom
Agile multi-vendor integration strategies and future soldier programs increase demand for modular tactical solutions. The Ministry of Defence (MOD) procurement standards prioritize open-architecture systems. Farnborough serves as a significant center for aerospace and defense innovation.
Germany
Army digitization programs and the need for secure, interoperable communications drive investment. The Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support (BAAINBw) sets stringent procurement standards. Munich hosts a concentration of high-tech defense industries, specializing in advanced electronics.
Global Defense Tactical Radio Market Key Industry Players
Listed leaders compete with private specialists across the defense tactical radio market's technology and integration capabilities. The market structure exhibits consolidation among established prime contractors, alongside a fragmented landscape of specialized technology firms. These prime contractors often act as system integrators, while niche providers focus on specific components or software. Strategic partnerships and technology licensing agreements represent dominant competitive moves among market participants.
Within the established prime contractor archetype, L3Harris Technologies exemplifies broad portfolio integration across SCA-compliant and non-SCA radios, serving diverse mission needs. Thales Group, a European-based company, occupies a strong position through its expertise in waveform development and secure communications, particularly within European and export markets. General Dynamics Corporation, a large US-based defense contractor, anchors its presence through deep integration with armored vehicle platforms, sustaining its competitive standing. These major players continuously adapt their offerings to evolving military specifications and national security regulations.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Thales Group |
| General Dynamics Corporation |
| BAE Systems |
| Raytheon Technologies |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Elbit Systems Ltd. |
| Rohde & Schwarz |
| Others |
Cost & Logistics Intelligence
US International Traffic in Arms Regulations (ITAR) strictly governs the export of sensitive radio technologies, gating both supply qualification and price differentiation for advanced systems. These regulations dictate which manufacturers can compete in specific markets and influence the cost structures for compliant products.
Pricing Analysis
Volume-discount tiering structures characterize procurement for defense tactical radios, with larger national defense organizations securing more favorable terms for bulk orders. Pricing stratifies across premium, standard, and economy tiers based on certification level, such as MIL-STD compliance, and the extent of customization required. Cost compression in hardware is intensifying due to the commoditization of SDR components, influencing overall system pricing. Army units, requiring vast quantities of standard handheld radios, exhibit higher price sensitivity compared to specialized air force squadrons needing highly customized airborne systems.
Supply Chain Analysis
Inventory management for defense tactical radios involves extended lead times due to stringent military specifications and complex certification processes. Geographic supply concentration for critical components centers on the United States, Germany, and Israel, which host specialized manufacturers. Raw material dependencies include advanced semiconductors for processing, specialized RF components for signal transmission, and robust materials for ruggedized casings. Single-source vulnerability for niche encryption modules represents a significant structural risk. Distribution runs through direct sales channels to defense ministries and prime contractors, alongside specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The defense tactical radio market is undergoing a platform-economics inflection, driven by the widespread adoption of Software Defined Radio (SDR) architecture. This shift fosters an ecosystem where software and hardware components can be sourced independently, promoting interoperability.
For Market Incumbents: Shield core contracts from erosion by proactively embracing open-architecture standards and modular design principles. Deepen software development capabilities, particularly for advanced waveforms and cybersecurity features, to maintain a competitive edge against agile software-centric firms. Acquire specialized waveform developers to expand proprietary intellectual property and enhance system integration expertise. Invest in R&D for AI-driven cognitive radio solutions, a key lever against evolving electronic warfare threats.
For New Entrants and Emerging Players: Integration complexity for multi-vendor systems represents a significant service-layer gap where incumbents under-serve. Target specialized data links for unmanned aerial and ground vehicles, a growing white-space not tied to traditional platforms. The Eastern European modernization initiatives offer a penetrable segment for Western-standard tactical radio providers. Partner with smaller defense integrators to offer niche waveform development and secure mobile application solutions, providing a focused go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across software development for waveforms, but upwards for advanced RF hardware and specialized encryption modules. The long-term viability of this market is anchored in sustained global defense spending and continuous technology refresh cycles. Identify and acquire software-defined networking specialists or cybersecurity firms focused on tactical communications. Increased military spending on hybrid 5G network trials is a signal to watch as an inflection indicator for future growth areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Next-Gen SDR Platform | Introduces advanced reconfigurable hardware capable of supporting future waveforms and communication protocols. |
| Platform Integration: Tactical Radios with Commercial 5G | Enables resilient hybrid networks and high-bandwidth applications in permissible operational environments. |
| Strategic Partnership: Cybersecurity Firms | Enhances radio security against evolving cyber threats, protecting critical voice and data transmissions. |
| Acquisition of Specialist Firm: Low-Latency Data Links | Secures expertise in high-throughput communication for unmanned systems, expanding market reach. |
| Geographic Expansion: R&D Hubs in Eastern Europe | Capitalizes on accelerated defense spending and replacement of legacy Soviet-era communication systems. |
Research Approach
Cross-validation between primary interviews with defense procurement officers and secondary analysis of defense budgets anchors the qualitative findings of this study. The research involved discussions with military communication specialists, R&D leads at prime contractors, and policy analysts specializing in defense technology. Secondary data sources included US DoD budget documents, NATO defense spending reports, national defense strategy white papers, and company annual reports. This approach ensured bottom-up and top-down triangulation for robust market insights.
Sensitivity analysis forms a core component of the forecast framework across the analysis window. The quantitative model integrates segmentation dimensions including Product Type, Technology, Application, End User, and waveform complexity. Compound annual growth rates were derived from historical growth trends, projected defense spending, and technology adoption curves. Military modernization program timelines and geopolitical conflict intensity served as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in regimes such as US ITAR and NATO STANAGs; material policy shifts would require re-modeling. The analysis acknowledges that unforeseen geopolitical conflicts or rapid shifts in electronic warfare capabilities represent risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Aviation Cyber Security Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Ballistics Targeting Software Market
Defense Cybersecurity
Electronic Countermeasures Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Asia-Pacific Missiles and Missile Defense Systems Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Automotive Cybersecurity Service Market