
 South Korea Satellite Communication Market | 2026-2036
South Korea Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Satellite Communication Market Insights
Defense procurement is shifting toward resilient space-based networks as Seoul prioritizes sovereign satellite capabilities for command and intelligence. Hanwha Group leverages its defense-industrial base to anchor terrestrial integration with orbital assets. KT Sat Co. Ltd sustains broadcast and broadband service leadership through geostationary capacity. Intellian Technologies Inc. specializes in maritime and mobility terminals, competing against European and domestic rivals for naval and commercial vessel contracts.
South Korea satellite communication encompasses ground stations, space segments, and user terminals operating across C, Ku, Ka, and emerging Q/V bands with orbital altitudes from 300 to 35,786 kilometers, designed to provide uninterrupted connectivity for defense, maritime, and remote terrestrial applications. Broadcasting services retain mature revenue streams from direct-to-home television distribution, while low Earth orbit technology captures the fastest structural expansion as constellation deployments reduce latency for government and enterprise users. Earth observation applications concentrate margin pools in dual-use analytics where scientific research and military surveillance requirements overlap.
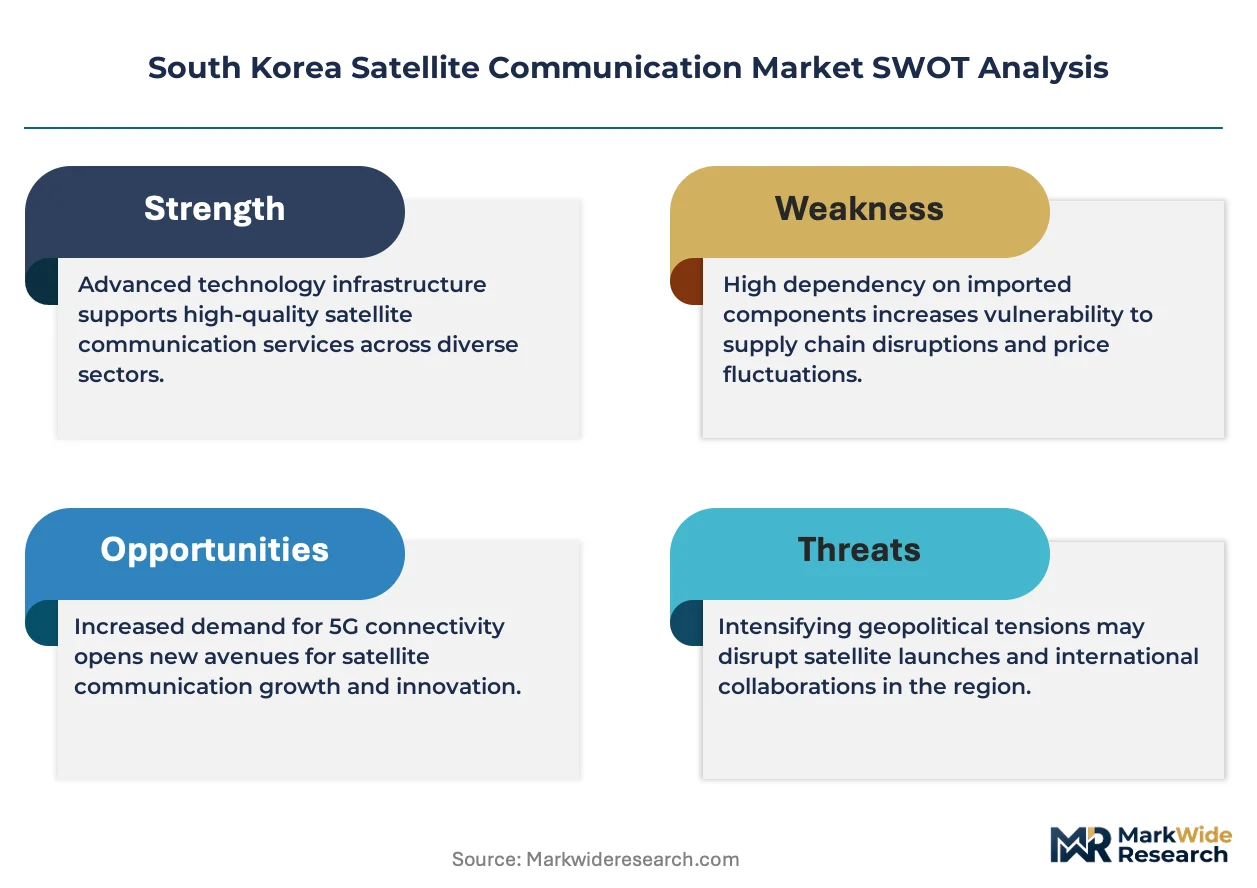
MFDS spectrum coordination rules intersect with Ministry of Science and ICT licensing frameworks to shape orbital slot allocation and terminal certification requirements for domestic operators. The Korean government's K-Network 2030 strategy and national space development plans channel public investment toward indigenous launch and satellite manufacturing capabilities. Stakeholders must monitor how regulatory alignment between civilian spectrum management and defense frequency prioritization affects market access timelines for commercial constellation services.
Market Dynamics
K-Network 2030 policy directives are compressing deployment timelines for low Earth orbit constellations while MFDS spectrum coordination creates certification bottlenecks for terminal manufacturers seeking dual-use military-civilian approvals.
Growth Catalysts
- Defense frequency prioritization:Ministry of National Defense allocation of dedicated military bands accelerates sovereign satellite procurement for command-and-control networks previously dependent on foreign relay capacity.
- Busan maritime corridor:Container shipping and offshore energy operators drive terminal demand for vessel-to-shore connectivity across the Korea Strait and East China Sea routes.
- Geostationary broadcast resilience:KT Sat's orbital slot holdings sustain direct-to-home television distribution as a recurring revenue anchor while LEO infrastructure scales.
Market Restraints
- Launch cost volatility:Dependence on Naro Space Center and foreign launch providers exposes constellation operators to payload pricing fluctuations and slot availability constraints.
- Domestic component concentration:Seoul's aerospace cluster houses most satellite manufacturing and ground station assembly, creating single-point vulnerability for supply continuity.
- Spectrum scarcity:MFDS coordination rules limit Ka-band allocation for commercial operators when defense applications assert preemptive claims during emergency protocols.
Strategic Opportunities
- Gyeonggi Province underpenetration:Industrial zones outside Seoul's aerospace cluster lack dedicated satellite backhaul for smart factory deployments and autonomous logistics systems.
- Q/V band convergence:Terrestrial 5G millimeter-wave infrastructure and satellite feeder links share component ecosystems, enabling dual-use equipment manufacturing at scale.
- Green New Deal space incentives:Carbon monitoring and emissions verification mandates create demand for Earth observation analytics serving domestic climate compliance frameworks.
Industry Challenges
- Orbital mechanics talent scarcity:Constellation operators compete with semiconductor and automotive sectors for propulsion and guidance system engineers trained in domestic universities.
- Dual-use certification complexity:Terminal manufacturers navigate parallel MFDS type approval and Defense Acquisition Program Administration security clearance processes that extend product launch timelines.
- Legacy geostationary integration:Hybrid network architectures require protocol bridging between established Ku-band broadcast systems and emerging LEO mesh topologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Satellite Communication Market |
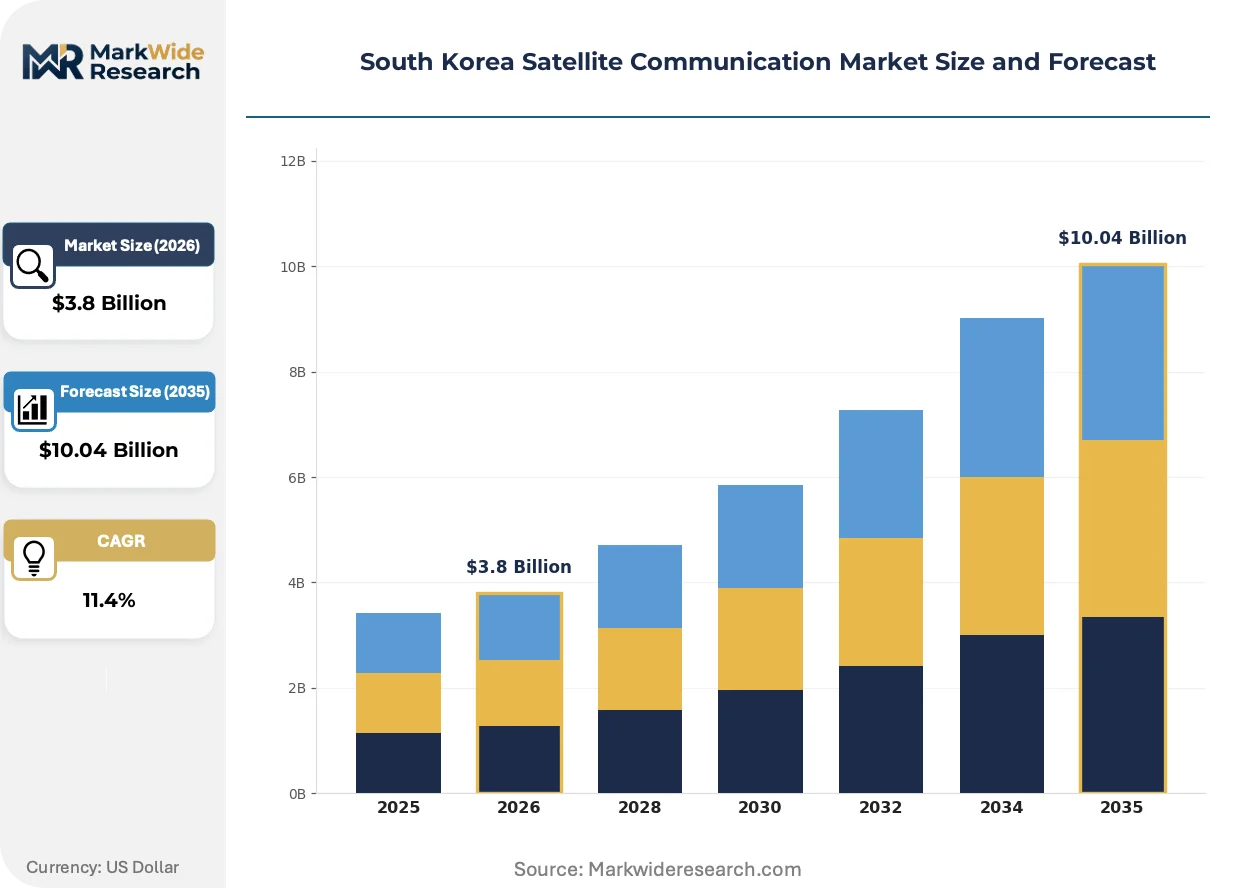
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadcasting, Internet Services, Data Communication, Earth Observation End User: Government, Telecommunications, Broadcasting Companies, Research Institutions Technology: Geostationary Satellites, Low Earth Orbit, Medium Earth Orbit, Hybrid Systems Application: Military, Emergency Services, Commercial, Scientific Research |
| Companies Covered | SES S.A., Hanwha Group, Intellian Technologies Inc., KT Corporation, WIWORLD, KT Sat Co. Ltd, KNS Inc., Samsung Electronics, Thales Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Satellite Communication Market Trends and Innovations
Software-defined payload architectures are compressing satellite refresh cycles while regulatory frameworks struggle to synchronize civilian spectrum licensing with defense orbital priorities.
Software-defined radio transponders are unifying multiple frequency bands and waveforms onto reprogrammable hardware platforms. Defense and maritime operators adopt these payloads to reduce dedicated equipment inventories across C, Ku, and Ka-band missions. This technology is unifying previously separate broadcast, broadband, and narrowband service lines into single-satellite platforms that operators reconfigure from ground control.
MFDS orbital slot coordination rules now mandate interference compatibility testing with adjacent national registrations before domestic licensing approval. This procedural layer extends market access timelines for commercial constellation services seeking to share spectrum with government priority users. Small satellite operators in Seoul's aerospace cluster respond by pre-coordinating filings with Ministry of Science and ICT to secure provisional authorizations.
Seoul-based systems integrators now bundle satellite connectivity with terrestrial fiber and 5G as unified service contracts rather than standalone offerings. Enterprise buyers in manufacturing and logistics verticals favor single-vendor accountability for hybrid network performance. This bundling pattern concentrates procurement decisions among defense-affiliated conglomerates with integrated terrestrial infrastructure holdings.
South Korea Satellite Communication Market Segmentation
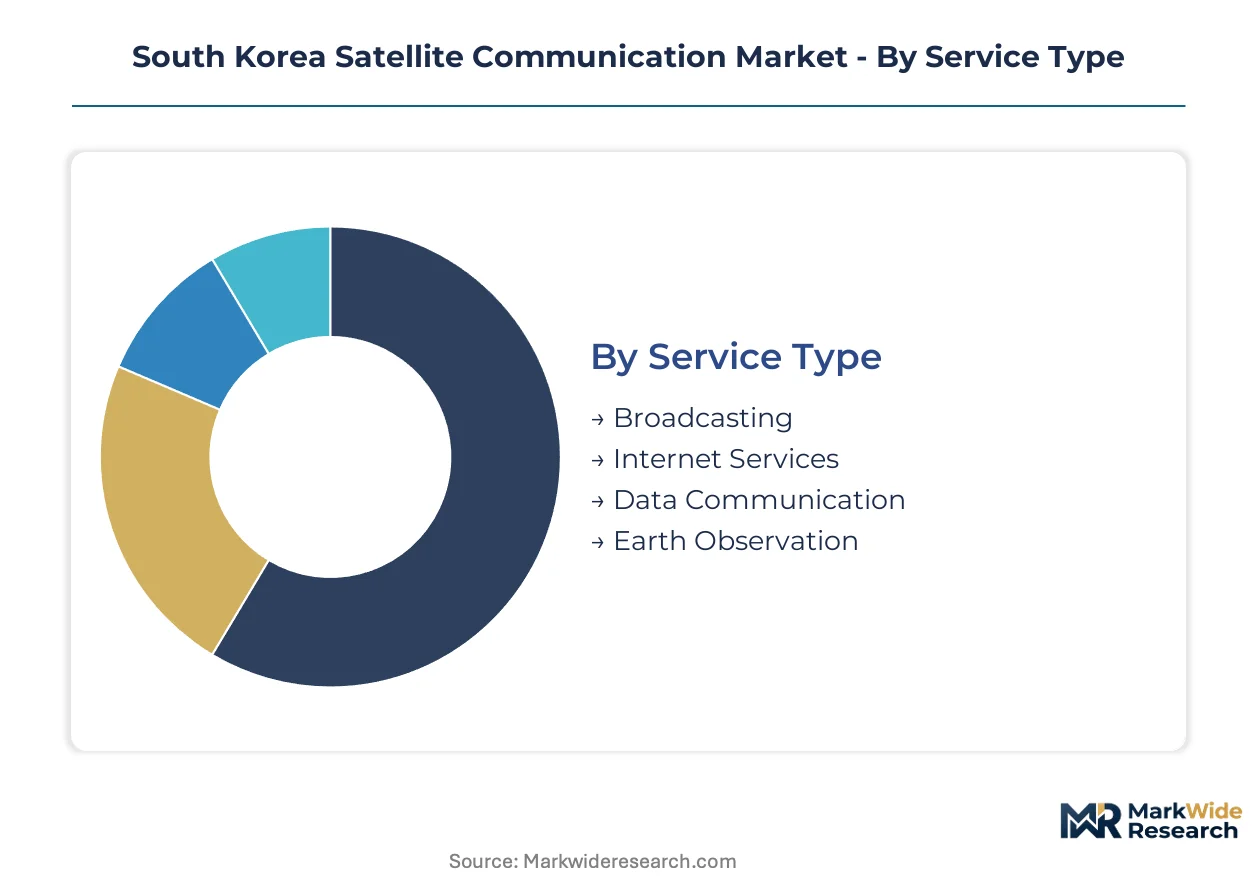
Satellite communication procurement in South Korea follows distinct upgrade cycles across service types and orbital technologies. MFDS licensing frameworks and K-Network 2030 deployment schedules create asynchronous replacement timelines that reshape vendor positioning.
Service Type:
Broadcast infrastructure replacement cycles stretch 12-15 years for geostationary transponders, while low Earth orbit service refresh compresses to 3-5 years as constellation operators deploy iterative generations.
- Broadcasting:Direct-to-home television distribution relies on Ku-band transponders with 15-year design lifespans. Seoul metropolitan area households and rural Jeolla Province communities sustain this segment as KT Sat maintains orbital slot continuity.
- Internet Services:Maritime connectivity and remote industrial backhaul drive Ka-band terminal deployment across Busan container terminals and offshore energy platforms. Latency-sensitive enterprise applications in Gyeonggi Province smart factories accelerate demand for low Earth orbit broadband.
- Data Communication:Narrowband IoT and machine-to-machine links serve logistics fleets and agricultural monitoring networks.
- Earth Observation:Dual-use imagery and radar analytics support climate verification mandates under Green New Deal frameworks.
Broadcasting sits at the top of the volume ranking, with Internet Services climbing the fastest.
End User:
Procurement concentration varies sharply by buyer sophistication, with defense and telecommunications operators commanding dedicated spectrum allocation while research institutions compete for shared orbital resources.
- Government:Ministry of National Defense and Korea Forest Service operate sovereign networks for command-and-control and disaster response. Dedicated X-band and military Ka-band allocations bypass commercial licensing queues.
- Telecommunications:KT Sat and regional ISPs lease transponder capacity for backhaul extension. 5G network densification in Seoul's aerospace cluster drives hybrid satellite-terrestrial integration contracts.
- Broadcasting Companies:KBS, MBC, and SBS maintain direct-to-home distribution through long-term orbital slot leases.
- Research Institutions:KAIST and Korea Astronomy and Space Science Institute share experimental Q/V band allocations for atmospheric propagation studies.
Government procurement commands premium pricing tiers, with Telecommunications expanding most quickly as commercial constellation services scale.
Technology:
Orbital altitude selection determines capital intensity and operational flexibility, with geostationary assets requiring single heavy launches versus distributed small satellite deployments.
- Geostationary Satellites:Fixed orbital positions at 35,786 kilometers enable persistent regional coverage with three-satellite constellations. KT Sat's Mugunghwa series anchors broadcast and broadband service continuity across the Korean peninsula and maritime exclusive economic zones.
- Low Earth Orbit:Constellations at 300-1,200 kilometers reduce propagation delay for real-time applications. K-Network 2030 indigenous deployment targets sovereign capability in this domain previously dominated by foreign operators.
- Medium Earth Orbit:O3b-style architectures at 8,000 kilometers balance latency and coverage for maritime trunk routes.
- Hybrid Systems:Ground segment integration combines geostationary broadcast resilience with low Earth orbit broadband responsiveness.
Geostationary Satellites retain revenue leadership, with Low Earth Orbit gaining share fastest as domestic launch capabilities mature.
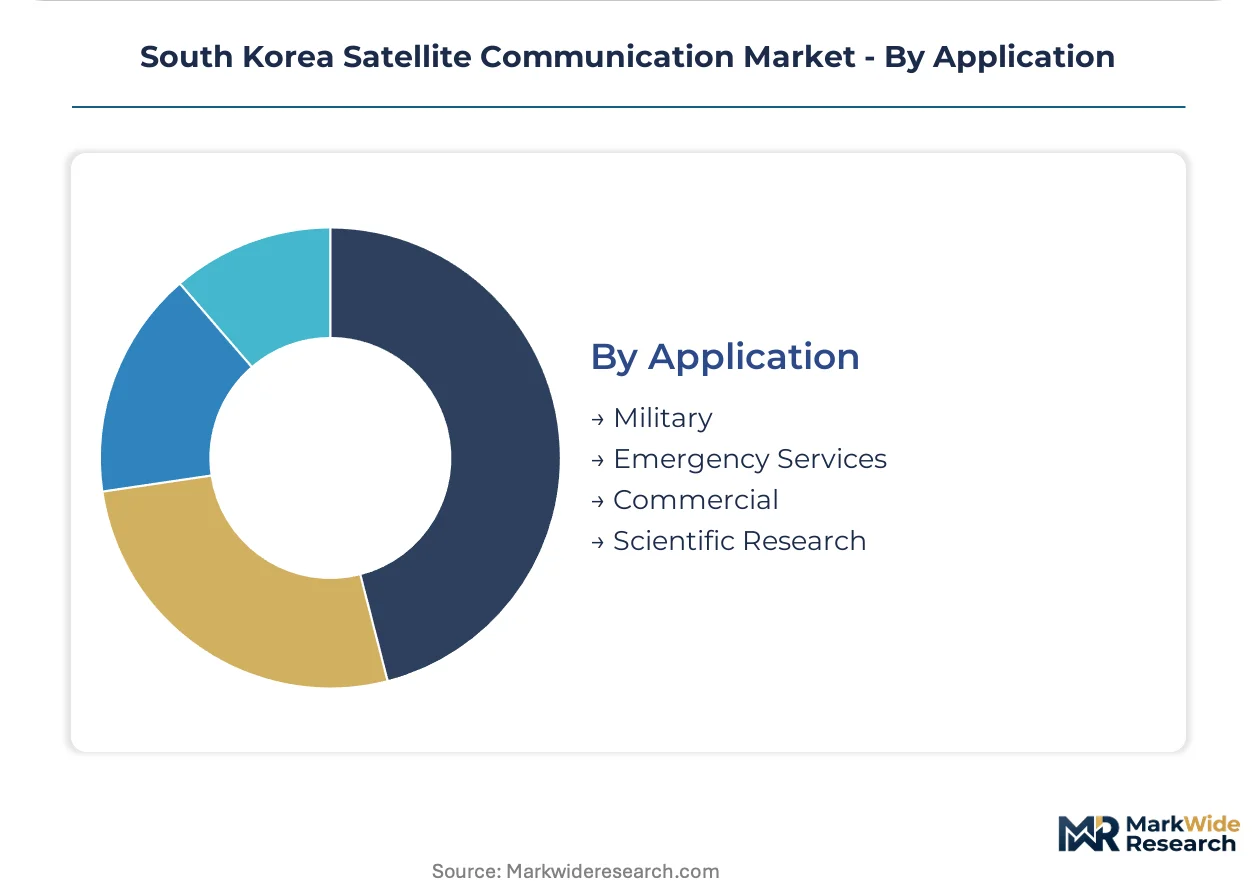
Application:
Mission-critical requirements impose divergent certification standards, with military terminals undergoing Defense Acquisition Program Administration security review while commercial equipment follows MFDS type approval.
- Military:Encrypted X-band and military Ka-band networks support joint operations and intelligence dissemination. Hanwha Group integration of terrestrial and orbital assets addresses sovereign command requirements.
- Emergency Services:Korea Forest Service and National Fire Agency deploy portable terminals for wildfire and flood response in Gangwon Province mountain terrain.
- Commercial:Maritime shipping, aviation, and remote enterprise connectivity drive volume terminal production.
- Scientific Research:Polar and atmospheric studies utilize specialized downlink protocols for high-data-rate sensor returns.
Commercial applications generate highest unit volumes, with Military procurement expanding most steeply under defense modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics shape investment flows as constellation operators weigh MFDS certification timelines against foreign licensing alternatives. South Korea's aerospace cluster attracts capital seeking integrated terrestrial-satellite procurement pathways unavailable in jurisdictions with fragmented spectrum governance.
Seoul Capital Area
Defense procurement and broadcast infrastructure anchor demand in the metropolitan core. K-Network 2030 implementation channels public investment toward indigenous low Earth orbit capabilities concentrated in Seongnam and Pangyo technology corridors. Satellite manufacturing and ground station assembly cluster in Guro Digital Complex, where systems integrators bundle hybrid connectivity contracts.
Busan-Ulsan
Maritime shipping and offshore energy operators drive terminal procurement across the Korea Strait corridor. Port automation and vessel-to-shore connectivity requirements compress deployment timelines for Ka-band equipment. Ulsan's shipbuilding yards integrate satellite terminals into newbuild specifications, creating captive demand for mobility-focused hardware.
Daegu-Gyeongbuk
Smart factory deployments and autonomous logistics systems generate backhaul demand in industrial zones outside Seoul's aerospace cluster. Defense-affiliated suppliers locate precision manufacturing facilities near Daegu to access Defense Acquisition Program Administration certification pathways. The region's underpenetration relative to capital-area infrastructure creates procurement opportunities for distributed constellation services.
Daejeon-Sejong
Research institutions and government agencies concentrate spectrum coordination and orbital slot allocation functions in this administrative hub. Korea Astronomy and Space Science Institute and KAIST operate experimental Q/V band facilities for atmospheric propagation studies. Public R&D investment flows through Sejong's science ministry complexes, shaping domestic licensing precedents for emerging frequency bands.
Gwangju-Honam
Agricultural monitoring networks and climate verification mandates under Green New Deal frameworks drive Earth observation analytics demand. Rural broadband gaps in Jeolla Province sustain geostationary Ku-band service subscriptions for direct-to-home distribution. Regional industrial policy targets satellite-enabled precision agriculture as a diversification vector from traditional manufacturing.
South Korea Satellite Communication Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense-integrated conglomerates commanding sovereign procurement channels while component suppliers compete for terminal volume contracts. The vendor base concentrates around three strategic archetypes: terrestrial infrastructure owners extending into orbital assets, pure-play satellite operators leasing transponder capacity, and maritime-focused hardware specialists. Consolidation pressure intensifies as hybrid network contracts favor single-vendor accountability. Dominant competitive moves include backward integration into payload manufacturing and strategic partnerships for foreign launch capacity access.
Within the defense-integrated tier, Hanwha Group anchors terrestrial-orbital system bundling for military and government clients. KT Sat Co. Ltd exemplifies the broadcast-broadband hybrid operator archetype through geostationary orbital slot holdings. Intellian Technologies Inc. occupies a position among maritime terminal specialists competing for naval and commercial vessel contracts against European rivals. These three entities represent distinct competitive vectors: sovereign capability integration, established service continuity, and mobility-focused hardware specialization.
| Leading Market Players |
|---|
| SES S.A. |
| Hanwha Group |
| Intellian Technologies Inc. |
| KT Corporation |
| WIWORLD |
| KT Sat Co. Ltd |
| KNS Inc. |
| Samsung Electronics |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Defense frequency prioritization under MFDS rules forces constellation operators to absorb premium certification costs for dual-use terminals, compressing margins on commercial-grade equipment and accelerating supplier consolidation toward defense-integrated conglomerates with captive compliance capabilities.
Pricing Analysis
Distributor margins on maritime terminals range from 15-22 percent for Ka-band equipment serving Busan container operators, while direct-to-government contracts eliminate intermediary markups entirely. Three-tier pricing structure across military-grade, industrial-certified, and standard commercial levels reflects Defense Acquisition Program Administration security clearance tiers rather than pure performance differentiation. Pricing pressure stems from KT Sat's bundled hybrid connectivity contracts that commoditize standalone satellite backhaul in Seoul's aerospace cluster. Small constellation operators exhibit highest price sensitivity, while Ministry of National Defense procurement maintains premium tolerance for sovereign capability assurance.
Supply Chain Analysis
K-Network 2030 local-content mandates reshape sourcing toward Seoul's Guro Digital Complex and Pangyo technology corridor, displacing foreign component flows for ground station assembly. Satellite manufacturing draws from South Korean domestic payload integration, Japanese precision components, and US semiconductor suppliers for software-defined radio chipsets. Gallium nitride amplifiers, carbon-fiber composite structures, and radiation-hardened electronics constitute critical input dependencies. Single-source vulnerability concentrates in foreign launch provider slots for constellation deployment. Distribution runs through defense-affiliated systems integrators bundling terrestrial fiber and orbital assets as unified service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement shifts from standalone transponder leases toward integrated hybrid network performance guarantees that favor vendors with terrestrial infrastructure holdings.
For Market Incumbents: Deploy sovereign capability certification as a lever to lock out foreign constellation competitors seeking MFDS licensing approval. Anchor procurement relationships through K-Network 2030 implementation partnerships with Ministry of Science and ICT. Extend backward integration into indigenous launch vehicle component manufacturing to reduce Naro Space Center slot dependency. Counter emerging pure-play LEO operators by bundling geostationary broadcast resilience with low-latency broadband responsiveness. For New Entrants and Emerging Players: Systems integrators lacking satellite heritage present the most accessible channel partner type for maritime terminal specialization targeting Busan-Ulsan shipbuilding automation. White-space concentration sits in Gyeonggi Province smart factory backhaul outside Seoul's aerospace cluster, where distributed constellation services bypass incumbent terrestrial infrastructure. Daegu-Gyeongbuk defense supplier zones offer procurement pathway access through Defense Acquisition Program Administration certification co-location. Position around Q/V band convergence with 5G millimeter-wave equipment sharing component ecosystems. For Investors and Strategic Acquirers: Asymmetric upside sits with maritime terminal specialists possessing dual-use military-civilian certification pipelines and captive shipbuilder relationships. Long-term viability favors vendors integrating software-defined payload architectures that compress satellite refresh cycles across the analysis window. Acquisition target archetype: mid-scale ground station assemblers with MFDS type approval track records and Seoul cluster proximity. Monitor Defense Acquisition Program Administration budget acceleration as sovereign satellite procurement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Integration | Unifies C, Ku, and Ka-band missions onto reprogrammable hardware platforms for defense operators. |
| Dual-Use Certification Streamlining | Compresses parallel MFDS and Defense Acquisition Program Administration approval timelines for terminal manufacturers. |
| Hybrid Network Bundling | Combines geostationary broadcast resilience with LEO broadband responsiveness as unified enterprise contracts. |
| Indigenous Launch Capacity Investment | Reduces Naro Space Center slot dependency and foreign payload pricing volatility for constellation operators. |
| Q/V Band Component Convergence | Leverages shared ecosystems between terrestrial 5G millimeter-wave and satellite feeder link equipment manufacturing. |
Research Methodology
Multiple input streams — structured interviews with satellite systems engineers, procurement officers at maritime operators, and regulatory affairs specialists at MFDS — were reconciled against Defense Acquisition Program Administration filing records and Korea Astronomy and Space Science Institute technical documentation. Secondary validation incorporated Ministry of Science and ICT spectrum allocation databases, Naro Space Center launch manifests, and customs records for ground station component imports. Bottom-up terminal shipment estimates and top-down transponder capacity utilization figures underwent cross-referencing to establish analytical consistency.
Historical deployment trajectories of KT Sat's Mugunghwa series and K-Network 2030 budget authorizations were cross-referenced against panel input from constellation operators and defense contractors. Segmentation modeling spanned service type, orbital technology, end-user category, and regional procurement cluster dimensions. CAGRs were derived from iterative reconciliation of supply-side capacity announcements and demand-side contract visibility. Industry-specific forecast inputs included MFDS licensing queue projections and Defense Acquisition Program Administration modernization program schedules.
Revisions become necessary when MFDS spectrum reallocation decisions, foreign launch provider availability shocks, or K-Network 2030 budget reprioritizations materialize outside baseline assumptions. Forecasts reflect documented procurement timelines and sovereign capability investment commitments subject to parliamentary appropriation cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Internet Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
China Satellite Imagery Services Market
Satellite
India Satellite Communication Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
4K Satellite Broadcasting Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Global Remote Sensing Services Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
Medium and Large Satellite Market
Satellite
Satellite Payload Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Europe Small Satellite Market
Satellite
Global Satellite Propulsion System Market