
 Electronic Countermeasures Market | 2026-2036
Electronic Countermeasures Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Countermeasures Market Insights
Israel's domestic production base is reshaping regional supply dynamics for electronic countermeasures. Northrop Grumman leverages extensive radar jamming expertise to anchor US Navy programs. Raytheon Technologies sustains broad-spectrum capabilities across airborne and maritime platforms. BAE Systems dominates European electronic warfare modernization through its UK manufacturing footprint.
Electronic countermeasures encompass hardware and software systems designed to disrupt, deceive, or deny adversary use of the electromagnetic spectrum, typically operating across radio frequency bands from 3 MHz to 40 GHz with solid-state and traveling wave tube transmitters. Their primary purpose is to protect military platforms, critical infrastructure, and communication networks from detection, targeting, or interference. Jamming devices and signal intelligence platforms lead procurement volumes due to sustained defense agency budgets, while directed energy weapons represent the fastest-expanding technology segment as kilowatt-class laser systems mature. Spoofing systems command premium margins where GPS denial and navigation warfare requirements intensify among naval forces and air operations units.
The US Department of Defense electromagnetic spectrum superiority strategy, NATO standardization agreements for electronic warfare interoperability, and FCC spectrum allocation rules collectively shape product certification and foreign market access for countermeasure suppliers. Compliance with ITAR export controls and emerging EU defense procurement directives increasingly determines which vendors participate in allied nation programs. Stakeholders must monitor how semiconductor export restrictions and gallium nitride supply chain localization alter component sourcing strategies and platform cost structures.
Market Dynamics
Gallium nitride semiconductor technology is compressing transmitter size and power density thresholds, forcing legacy traveling wave tube architectures toward obsolescence in next-generation jamming platforms.
Growth Catalysts
- US electromagnetic spectrum superiority strategy:Pentagon procurement directives mandate resilient countermeasures against peer-state electronic warfare threats, accelerating platform modernization cycles across airborne and maritime domains.
- NATO standardization agreements:Electronic warfare interoperability requirements drive cross-border procurement alignment, creating consolidated demand pools for jamming and spoofing systems among member defense agencies.
- Directed energy weapons maturation:Kilowatt-class laser systems are transitioning from experimental to deployable status, opening new capability categories for electromagnetic denial missions.
Market Restraints
- Gallium nitride substrate concentration:Foundry capacity for high-purity GaN-on-SiC wafers clusters in East Asian manufacturing hubs, exposing supply chains to export control disruptions.
- ITAR export control friction:US State Department licensing requirements delay technology transfer to allied programs, constraining vendor participation in multinational electronic warfare initiatives.
- Traveling wave tube substitution pressure:Solid-state transmitters are displacing vacuum electron devices in mid-power applications, stranding specialized manufacturing equipment and technical labor pools.
Strategic Opportunities
- Israeli domestic production expansion:Indigenous defense industrial base development creates alternative sourcing corridors for NATO-adjacent nations seeking non-US electronic countermeasure suppliers.
- GPS denial and navigation warfare:Naval forces and air operations units are intensifying spoofing system procurement, commanding premium margins for precision navigation warfare capabilities.
- EU defense procurement directives:Emerging European Union sourcing rules favor continental manufacturing footprints, advantaging vendors with UK or continental European production assets.
Industry Challenges
- Electromagnetic spectrum engineering talent scarcity:Specialized RF warfare design expertise concentrates within defense contractor workforces, limiting workforce mobility and program scaling flexibility.
- Platform integration complexity:Legacy aircraft and maritime vessels require extensive electrical and thermal retrofitting to accommodate solid-state jamming systems, extending deployment timelines.
- FCC spectrum allocation compliance:Civilian frequency coordination requirements constrain test and evaluation protocols, compressing development windows for wideband countermeasure systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Countermeasures Market |
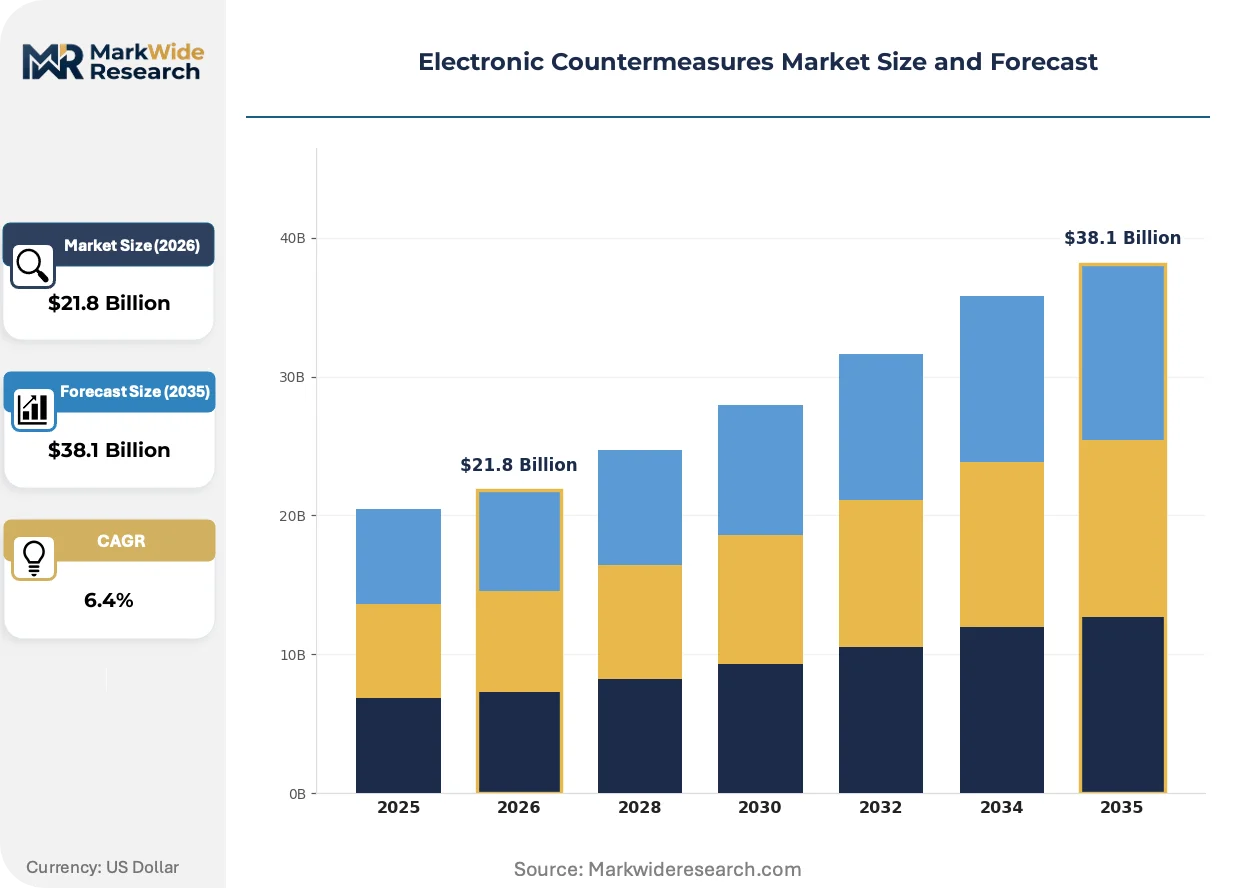
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jamming Devices, Spoofing Systems, Decoys, Directed Energy Weapons, Signal Intelligence Technology: Radar Jamming, Communication Disruption, Infrared Countermeasures, Electronic Surveillance, Cyber Defense, Signal Deception Application: Military Defense, Maritime Security, Aerospace Protection, Border Surveillance, Telecommunications Security, Law Enforcement End User: Defense Agencies, Naval Forces, Air Operations, Homeland Security, Intelligence Units, Police Departments |
| Companies Covered | Northrop Grumman, Raytheon Technologies, BAE Systems, L3Harris Technologies, Lockheed Martin, Thales Group, General Dynamics, Leonardo, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Countermeasures Market Trends and Innovations
Active electronically scanned arrays are converging with software-defined radio architectures, collapsing the boundary between dedicated jamming platforms and multi-function sensor systems across defense procurement programs.
GaN high-electron-mobility transistors are hybridizing radio frequency power amplification with digital beamforming control, enabling real-time spectrum adaptation in contested electromagnetic environments. US Navy airborne electronic attack squadrons are fielding these hybrid transmit-receive modules at accelerated procurement tempos. The technology is hybridizing hardware-defined jamming payloads into reconfigurable software platforms, compressing platform-specific development cycles.
EU defense procurement directives are mandating cross-border electronic warfare interoperability certification, forcing subsystem vendors toward standardized interface protocols. Industrial consequence includes mandatory disclosure of encryption and modulation schemes to national certification bodies. Naval forces across France, Germany, and Italy are most affected, consolidating supplier qualification processes through the European Defence Agency.
Defense agencies are unbundling electronic countermeasure hardware procurement from sustainment services, fragmenting traditional prime contractor roles. System integrators now compete separately from component suppliers and in-service support providers. This pattern is most visible in United Kingdom Royal Air Force fast-jet protection programs, where platform OEMs, jamming subsystem vendors, and through-life support contractors now submit distinct bids.
Electronic Countermeasures Market Segmentation
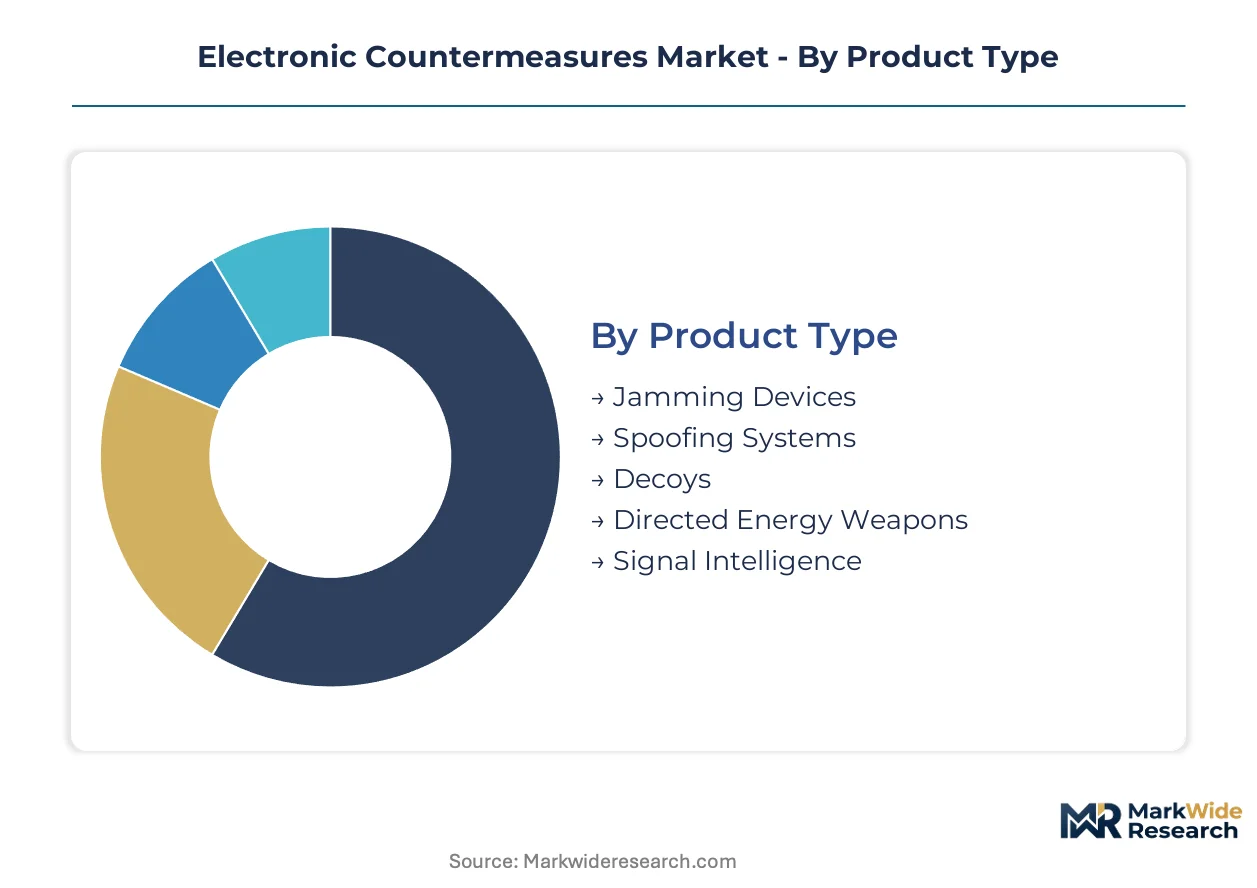
Electronic countermeasures fragment across multiple technical and operational dimensions, each carrying distinct procurement protocols and integration requirements. Defense agencies prioritize segments offering electromagnetic spectrum dominance with minimal platform retrofit burden. Procurement patterns diverge sharply between legacy hardware refresh cycles and emerging directed energy investments.
Product Type:
Use-case spectrum spans spectrum denial through physical destruction, with procurement volumes clustering around mature jamming architectures and experimental directed energy platforms.
- Jamming Devices:Solid-state and traveling wave tube transmitters operating across 3 MHz to 40 GHz bands dominate current procurement volumes. US Navy airborne electronic attack squadrons and NATO member defense agencies are accelerating fleet-wide retrofits with gallium nitride-based compact transmitters, though legacy platform thermal constraints limit deployment speed.
- Directed Energy Weapons:Kilowatt-class laser systems are transitioning from experimental to deployable status for electromagnetic denial missions. Naval forces across France, Italy, and the United States are funding prototype integration programs, with kilowatt-class thresholds now achievable through improved thermal management and beam control subsystems.
- Spoofing Systems:GPS denial and navigation warfare capabilities command premium margins where precision interference is required.
- Decoys:Expendable RF emitters and infrared flares protect high-value platforms from terminal guidance threats.
- Signal Intelligence:Passive collection systems support electronic order of battle development without active emission signatures.
The dominant share belongs to Jamming Devices, while Directed Energy Weapons is closing the gap fastest through naval procurement acceleration.
Technology:
Cost tier stratification separates mature hardware-defined systems from software-reconfigurable architectures requiring substantial R&D investment.
- Radar Jamming:Active electronically scanned arrays converging with software-defined radio architectures are collapsing boundaries between dedicated jamming platforms and multi-function sensors. Northrop Grumman anchors US Navy programs with extensive expertise in this domain, while BAE Systems dominates European modernization through UK manufacturing footprints.
- Communication Disruption:Wideband RF power amplifiers with real-time spectrum adaptation enable contested environment operations. GaN high-electron-mobility transistors hybridizing with digital beamforming control are compressing development cycles for platform-specific payloads.
- Infrared Countermeasures:Directed infrared countermeasure turrets protect rotary-wing and transport aircraft from man-portable air defense threats.
- Electronic Surveillance:Passive emitter mapping supports targeting without revealing receiver positions.
- Cyber Defense:RF-enabled network intrusion capabilities bridge electronic and information warfare domains.
- Signal Deception:Modulation scheme replication creates false target indications for adversary processing chains.
Radar Jamming commands the largest installed base, though Communication Disruption is expanding most quickly through software-defined architecture adoption.
Application:
Customer type concentration clusters around sovereign defense procurement with stringent ITAR and national security classification barriers.
- Military Defense:Peer-state electronic warfare threats drive Pentagon electromagnetic spectrum superiority strategy implementation. Platform modernization cycles across airborne and maritime domains prioritize resilient countermeasures with minimal crew workload burdens.
- Maritime Security:Naval forces intensify spoofing system procurement for navigation warfare requirements in contested littoral environments. Surface combatants and auxiliary vessels require hardened GPS denial capabilities against precision guidance threats.
- Aerospace Protection:Fast-jet and transport aircraft programs demand integrated self-protection suites with multi-spectral coverage.
- Border Surveillance:Ground-based electronic surveillance supports counter-intrusion operations with persistent spectrum monitoring.
- Telecommunications Security:Critical infrastructure protection extends countermeasure concepts to civilian communication networks.
- Law Enforcement:Tactical RF disruption capabilities support hostage rescue and counter-terror operations with controlled collateral effects.
Military Defense retains overwhelming procurement priority, while Maritime Security is gaining share fastest through Indo-Pacific fleet expansion programs.
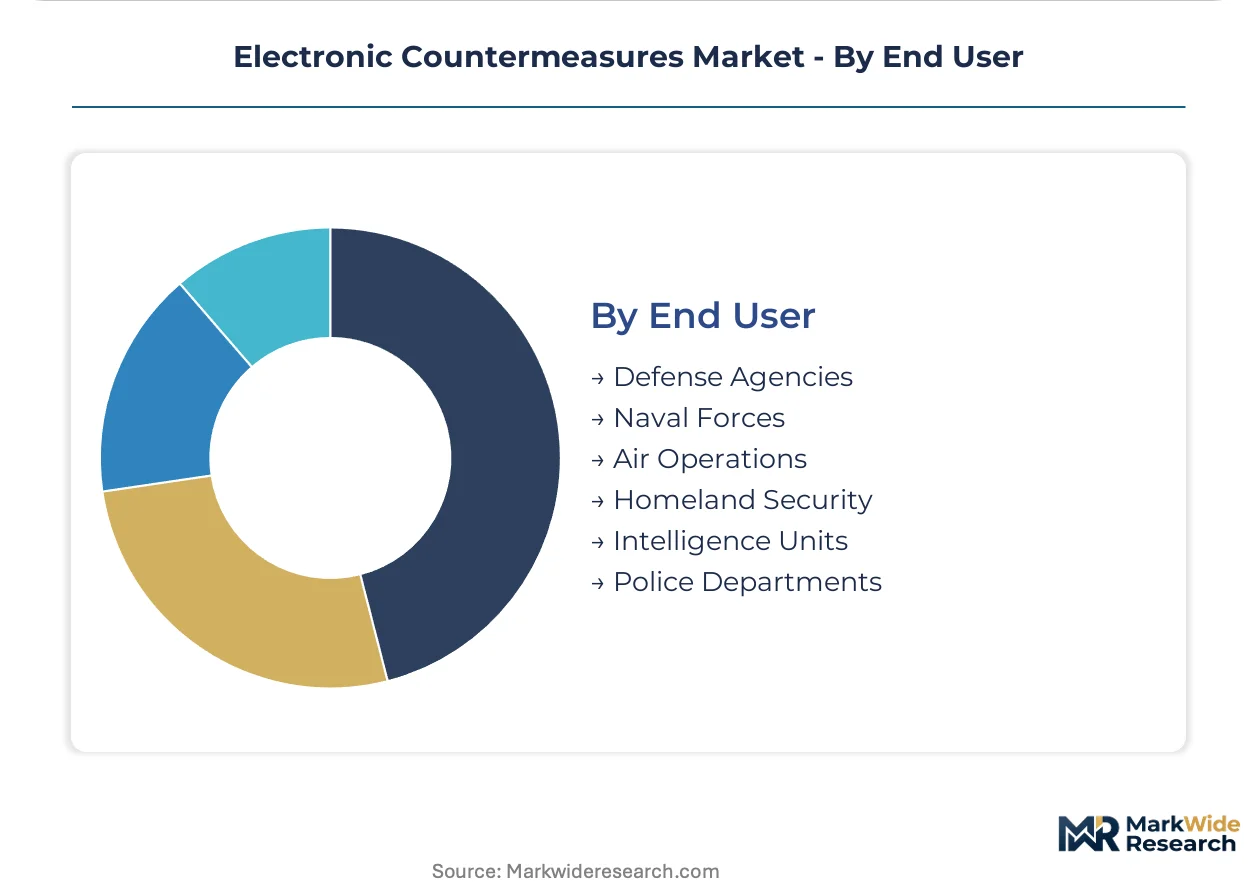
End User:
Supply concentration for qualified vendors shapes competitive access across classified and unclassified procurement channels.
- Defense Agencies:Pentagon procurement directives and NATO standardization agreements create consolidated demand pools with interoperability certification requirements. Cross-border alignment forces subsystem vendors toward standardized interface protocols with mandatory encryption disclosure to national bodies.
- Naval Forces:Surface and submarine platforms require extensive electrical and thermal retrofitting for solid-state jamming integration, extending deployment timelines.
- Air Operations:Fast-jet protection programs unbundle hardware procurement from sustainment services, fragmenting traditional prime contractor roles.
- Homeland Security:Domestic counter-terror applications operate under FCC spectrum allocation constraints that compress test and evaluation windows.
- Intelligence Units:Clandestine technical collection demands minimal signature platforms with exotic frequency coverage.
- Police Departments:Tactical RF disruption procurement faces civil liberties review and restricted frequency authorization protocols.
Defense Agencies control the largest budget authority, though Naval Forces are climbing the fastest through directed energy weapon maturation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pentagon's electromagnetic spectrum superiority strategy anchors procurement velocity in the United States, while NATO interoperability requirements and semiconductor export controls reshape sourcing corridors across allied defense industrial bases.
United States
US Navy airborne electronic attack squadrons and Army electronic warfare units drive fleet-wide retrofits with gallium nitride transmitters. FCC spectrum allocation rules constrain test protocols for wideband countermeasure systems, compressing development windows. Defense contractors cluster around Washington DC metro, Baltimore corridor, and Southern California aerospace hubs where platform integration expertise concentrates.
Israel
Indigenous defense industrial base development creates alternative sourcing corridors for NATO-adjacent nations seeking non-US suppliers. Israeli military procurement directives prioritize electromagnetic spectrum dominance in contested regional environments. Elbit Systems and Rafael anchor production in Haifa and Tel Aviv metropolitan clusters with specialized RF warfare design capabilities.
United Kingdom
Royal Air Force fast-jet protection programs unbundle hardware procurement from sustainment services, fragmenting traditional prime contractor roles. UK export control regulations and EU defense procurement directive alignment shape vendor qualification processes. BAE Systems dominates manufacturing in Lancashire and Hampshire with extensive radar jamming integration facilities.
France
Naval forces intensify spoofing system procurement for navigation warfare requirements in contested littoral environments. French defense procurement agency DGA mandates cross-border electronic warfare interoperability certification through European Defence Agency frameworks. Thales Group anchors development in Paris-Saclay cluster with directed energy weapon prototype integration programs.
Germany
Bundeswehr electronic warfare modernization prioritizes resilient countermeasures against peer-state threats through NATO standardization agreements. German ITAR compliance protocols and EU defense procurement directives determine vendor access to multinational programs. Rheinmetall and Hensoldt concentrate manufacturing in Bavaria and Baden-Württemberg with solid-state transmitter production capabilities.
Electronic Countermeasures Market Competitive Landscape
Platform-integrated primes and component-specialist suppliers split the market through divergent certification pathways. The vendor base concentrates around sovereign defense procurement channels with stringent ITAR and national security classification barriers. Three archetypes dominate: electromagnetic spectrum engineering houses with captive RF design expertise, diversified aerospace conglomerates with platform integration mandates, and emerging directed energy specialists transitioning experimental laser systems to deployable status. Competitive moves center on gallium nitride supply chain localization and cross-border strategic partnerships to circumvent export control friction.
Among US-based platform integrators, Northrop Grumman and Raytheon Technologies exemplify the diversified aerospace archetype with extensive radar jamming expertise anchoring Navy programs. BAE Systems represents the European electromagnetic spectrum engineering house positioned through UK manufacturing footprints. These three occupy positions defined by sovereign defense procurement channel access rather than interchangeable commercial competition.
| Leading Market Players |
|---|
| Northrop Grumman |
| Raytheon Technologies |
| BAE Systems |
| L3Harris Technologies |
| Lockheed Martin |
| Thales Group |
| General Dynamics |
| Leonardo |
| Elbit Systems |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific semiconductor freight corridors from Kaohsiung to Long Beach anchor cost dynamics across the electronic countermeasures value chain, where gallium nitride substrate concentration in East Asian foundries amplifies downstream price differentiation between ITAR-compliant and non-controlled system tiers.
Pricing Analysis
Price spreads between US-manufactured and Israeli-sourced jamming platforms reach substantial premiums driven by ITAR compliance overhead and FCC certification requirements. Three-tier pricing structure across ITAR-restricted, NATO-interoperable, and commercial-grade systems reflects certification grade and after-sales service bundling. Cost compression in mid-power solid-state transmitters is intensifying because traveling wave tube substitution accelerates, squeezing legacy vacuum electron device margins. Defense agencies exhibit lowest price sensitivity due to electromagnetic spectrum superiority mandates, while homeland security procurement shows highest sensitivity to unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for high-purity GaN-on-SiC wafer sourcing. Foundry capacity clusters in Taiwan, Japan, and South Korea, drawing from specialized semiconductor-grade silicon carbide substrates and high-purity gallium metal feedstocks. Single-source vulnerability concentrates in epitaxial growth equipment where Japanese and German toolmakers control critical deposition technology. Distribution runs through defense contractor prime channels with captive integration teams rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic countermeasures sit in early-cycle expansion as kilowatt-class directed energy weapons transition from experimental to deployable status, opening entirely new procurement categories beyond traditional jamming hardware.
For Market Incumbents: Pre-empt solid-state transmitter obsolescence by accelerating gallium nitride supply chain localization in domestic foundries before export control tightening strands legacy traveling wave tube manufacturing. Lock in electromagnetic spectrum engineering talent through captive RF warfare design centers in Washington DC metro and Southern California aerospace clusters. Vertical integration into GaN epitaxial growth capabilities hedges against East Asian substrate concentration risks. For New Entrants and Emerging Players: NATO-adjacent nations seeking non-US electronic countermeasure suppliers represent the most penetrable entry point, particularly where EU defense procurement directives favor continental manufacturing footprints. Directed energy weapon subsystem specialization offers white-space access as naval prototype programs multiply across France, Italy, and the United States. Position through European Defence Agency interoperability certification as the go-to-market angle to bypass traditional prime contractor barriers. For Investors and Strategic Acquirers: Electromagnetic spectrum engineering houses with captive RF design expertise and established national security clearances present the highest long-term viability acquisition profile across the 5-10 year horizon. Monitor directed energy weapon prototype-to-production conversion rates as the critical inflection signal for capability shift timing. GaN semiconductor supply chain localization announcements from defense primes indicate strategic positioning against export control disruption.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Supply Chain Localization | Captive foundry investments in US and European manufacturing hubs reduce ITAR transfer friction. |
| Directed Energy Weapon Prototyping | Naval kilowatt-class laser integration programs with French DGA and US Navy accelerate capability maturation. |
| European Defence Agency Certification | Cross-border interoperability mandates force encryption disclosure and standardize subsystem interfaces. |
| Platform Integration Unbundling | UK Royal Air Force fast-jet protection programs separate hardware procurement from through-life support contracts. |
| Electromagnetic Spectrum Talent Acquisition | Specialized RF warfare design expertise concentration limits workforce mobility and program scaling flexibility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Pentagon electromagnetic spectrum program officers, NATO electronic warfare interoperability leads, GaN semiconductor foundry engineering directors, and defense contractor platform integration specialists. Secondary validation drew from FCC spectrum allocation filings, US Department of Defense electromagnetic spectrum superiority strategy documents, European Defence Agency certification protocols, and SEC 10-K disclosures from listed defense primes. Bottom-up component demand modeling and top-down defense budget allocation analysis were triangulated to anchor volume estimates.
Calibration against historical procurement cycles and technology substitution patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, application domain, and end-user procurement channel. CAGRs were derived from fitted growth curves adjusted for platform modernization cycle timing and directed energy weapon adoption S-curve positioning. Forecast inputs incorporated gallium nitride transmitter substitution rates and NATO standardization agreement implementation timelines.
Practitioners should monitor semiconductor export control expansion and electromagnetic spectrum engineering talent migration for early signals of supply constraint intensification. Forecasts reflect assumptions about GaN foundry capacity expansion and ITAR licensing velocity that could revise materially if geopolitical friction escalates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Military Computers Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Asia-Pacific Defense Market