
 Tactical Radio Market | 2026-2036
Tactical Radio Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Radio Market Insights
The EU Green Deal's push for sustainable electronics procurement is expanding requirements for energy-efficient and reduced-carbon manufacturing across defense supply chains. L3Harris Technologies Inc. leverages its software-defined radio portfolio to sustain technology leadership in programmable waveform architectures. Thales Group anchors European demand through deep relationships with French and British defense ministries. Rheinmetall AG competes in the vehicular radio segment with platforms engineered for NATO interoperability standards.
A tactical radio is a portable or vehicle-mounted transceiver operating across HF, VHF, and UHF bands with encryption, frequency hopping, and anti-jam capabilities designed for military and first-responder communications in contested electromagnetic environments. Handheld radio units dominate procurement volumes among dismounted infantry units requiring lightweight, battery-operated voice and data links. Software Defined Radio technology leads investment flows as programmable architectures allow firmware updates without hardware replacement, extending platform lifecycles across multiple operational theaters. Base station radio systems occupy higher margin pools due to integration complexity and long-term maintenance contracts tied to command center infrastructure.
FCC spectrum allocation rules in the United States, EU CE marking requirements under the Radio Equipment Directive, and NATO STANAG interoperability standards collectively shape product certification pathways and cross-border procurement eligibility for tactical radio manufacturers. The EU AI Act's emerging provisions for autonomous signal processing are beginning to influence R&D roadmaps for next-generation cognitive radio systems. Stakeholders must monitor how national spectrum reallocation decisions and encryption export control frameworks reshape competitive access to allied defense markets.
Market Dynamics
Software-defined radio architectures are compressing hardware replacement cycles across NATO procurement programs, forcing incumbents to pivot from fixed-platform manufacturing toward firmware-centric service models that extend operational lifespans without physical upgrades.
Growth Catalysts
- NATO STANAG interoperability mandates:Allied defense ministries require cross-border waveform compatibility, creating captive demand for certified platform ecosystems that lock out non-compliant suppliers.
- EU Green Deal procurement rules:Sustainable electronics requirements under the EU Green Deal are redirecting defense budgets toward energy-efficient manufacturing processes and reduced-carbon supply chains.
- Spectrum reallocation in contested theaters:Military operators face jamming-intensive environments in Eastern Europe and the Indo-Pacific, accelerating frequency-agility investments across HF, VHF, and UHF bands.
Market Restraints
- GaN and GaAs substrate cost volatility:Power amplifier materials face supply concentration from Chinese rare earth processing, squeezing margins on high-frequency transmitters.
- Encryption export control friction:US International Traffic in Arms Regulations and EU dual-use restrictions fragment procurement eligibility for non-allied customers.
- Analog-to-digital transition stranded assets:Legacy inventory depreciation pressures defense ministries with sunk costs in hardware-fixed platforms nearing obsolescence.
Strategic Opportunities
- Cognitive radio R&D under EU AI Act provisions:Autonomous signal processing regulations are opening funding pathways for machine-learning-enabled spectrum sensing in next-generation platforms.
- First-responder crossover applications:Emergency services agencies in Germany and Australia are adopting militarized encryption standards for disaster response networks.
- Software update subscription models:Firmware-as-a-service recurring revenue streams are displacing one-time hardware sales across dismounted infantry procurement programs.
Industry Challenges
- RF engineer talent scarcity:Specialized microwave design expertise concentrates in defense contractor clusters around Huntsville, Toulouse, and Munich, constraining scaling capacity.
- NATO certification timeline compression:Security accreditation for new waveforms averages 18-24 months, delaying field deployment against evolving electronic warfare threats.
- Multi-band antenna integration complexity:Handheld form factors impose severe power-budget tradeoffs between range, battery life, and thermal management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Radio Market |
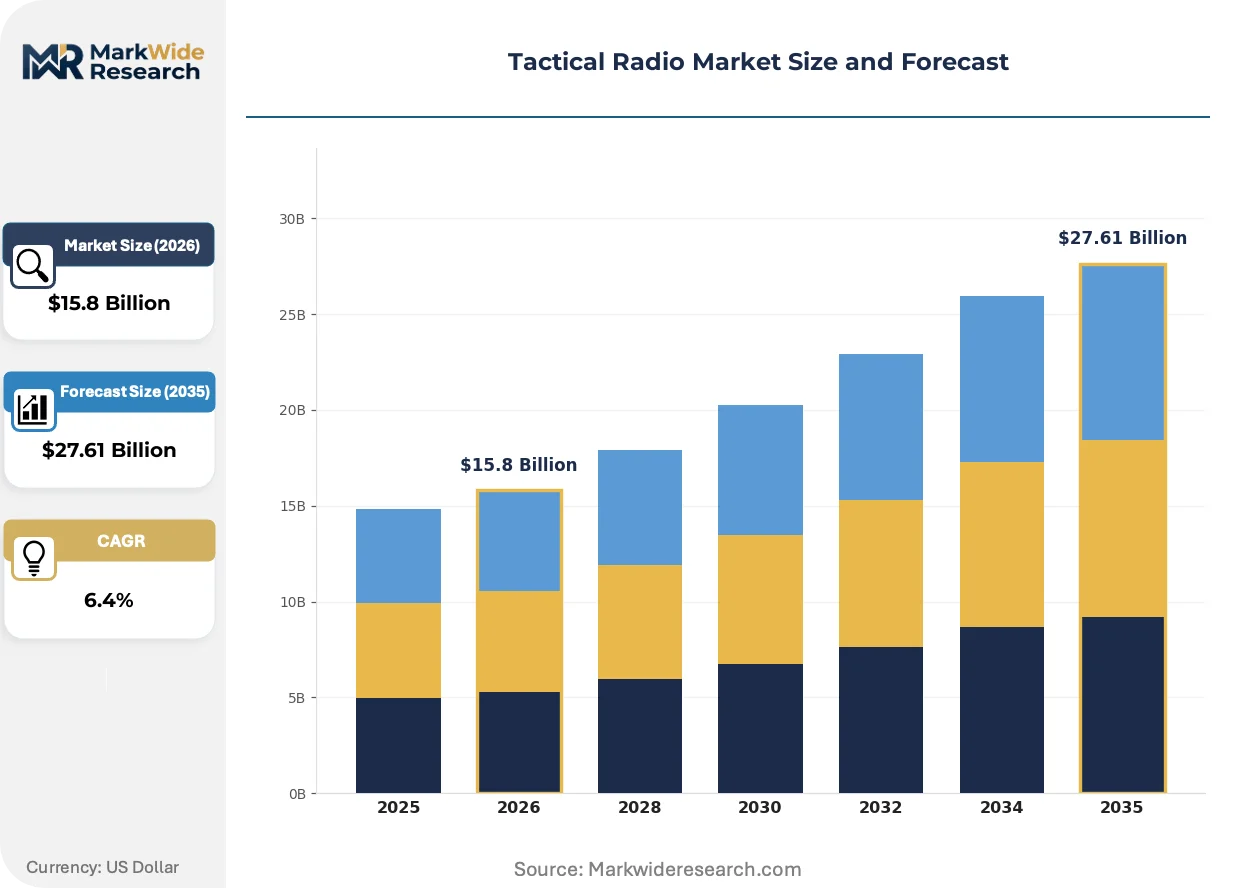
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Radio, Vehicular Radio, Base Station Radio, Manpack Radio Technology: Software Defined Radio, Frequency Hopping, Direct Sequence Spread Spectrum, Analog Modulation End User: Defense Forces, Emergency Responders, Law Enforcement, Security Agencies Deployment: Field Operations, Command Centers, Remote Surveillance, Communication Relays |
| Companies Covered | BAE Systems PLC, L3Harris Technologies Inc., RTX Corporation, Motorola Solutions Inc., Leonardo S.P.A., General Dynamics Corporation, Thales Group, Rheinmetall AG, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Radio Market Trends and Innovations
Waveform programmability is collapsing the traditional boundary between radio hardware and software layers, enabling defense primes to compete on algorithmic performance rather than manufacturing scale alone.
Software-defined radio technology is unifying previously separate HF, VHF, and UHF transceiver functions onto single reprogrammable chipsets. Dismounted infantry units across NATO member states are field-testing these platforms at battalion scale during rotational deployments. This convergence is compressing supplier ecosystems by eliminating specialized narrowband manufacturers who cannot match firmware update velocities.
EU CE marking requirements under the Radio Equipment Directive are tightening electromagnetic compatibility testing for cross-border military procurement eligibility. Manufacturers must now demonstrate compliance with RED cybersecurity provisions before accessing French, German, or British defense tenders. Vehicular radio platforms face the steepest certification burden due to integration complexity with legacy NATO command vehicles.
Defense procurement offices are consolidating vendor relationships around full-spectrum communication system integrators rather than discrete radio suppliers. The British Army's Morpheus program and Australia's Land 200 initiative exemplify this bundling shift toward single-contractor responsibility for voice, data, and electronic warfare coordination. This concentration is most advanced in Anglo-American procurement frameworks where budget pressures favor total-cost-of-ownership contracting over component-level competition.
Tactical Radio Market Segmentation
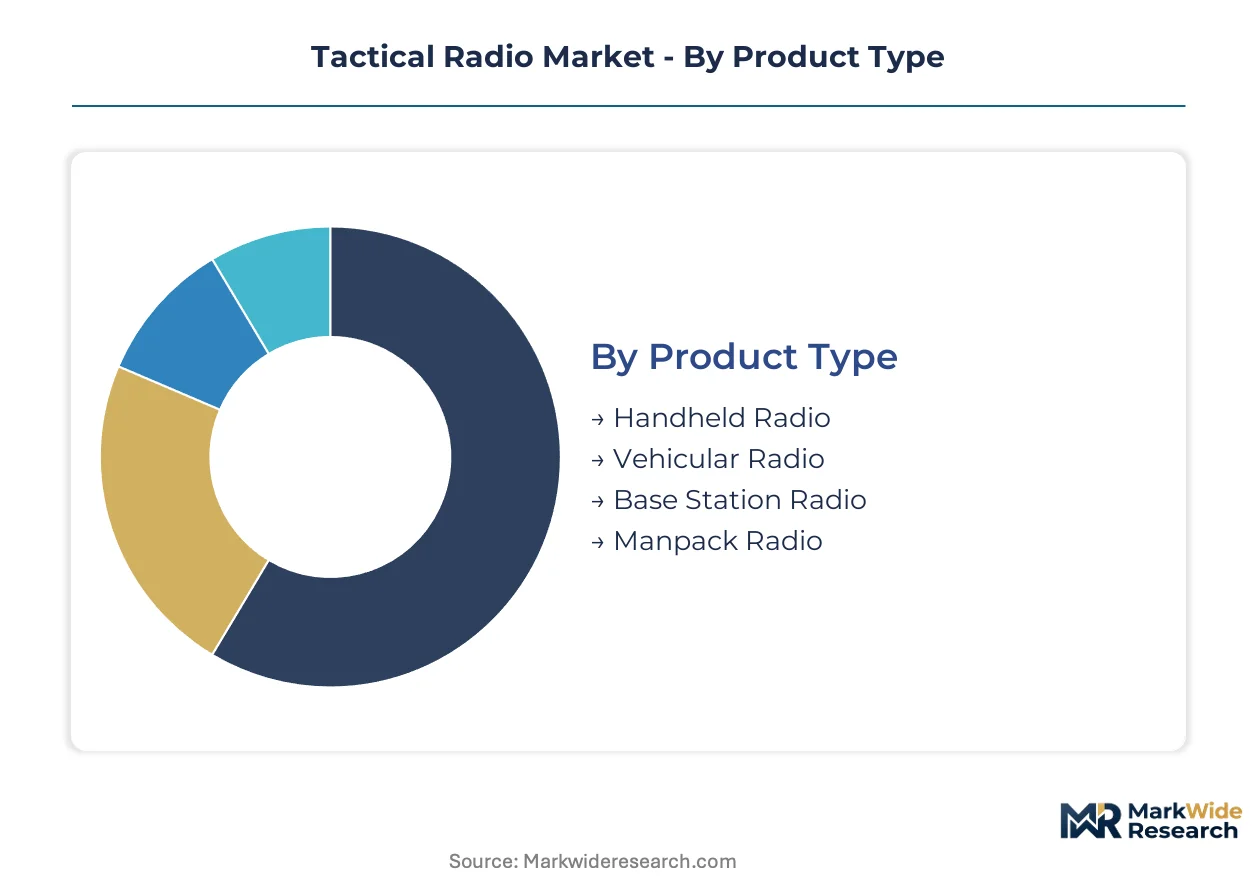
Procurement cycles for tactical radios diverge sharply across product form factors and operational roles, with upgrade timelines stretching from months for handheld units to decades for base station infrastructure. Defense ministries structure replacement budgets around these heterogenous lifecycles, creating tiered investment horizons that reshape supplier relationships and technology roadmaps.
Product Type:
Replacement urgency varies dramatically by platform mobility, with dismounted infantry systems cycling fastest and fixed infrastructure persisting across multiple operational theaters.
- Handheld Radio:Battery-operated transceivers under two kilograms dominate procurement volumes among NATO dismounted infantry and special operations units. German and Australian defense ministries are accelerating field replacements of legacy analog units with encrypted digital platforms under national modernization programs. Volume placements concentrate in Handheld Radio; the faster expansion belongs to Vehicular Radio.
- Vehicular Radio:Ruggedized platforms engineered for armored vehicle integration must satisfy NATO STANAG interoperability standards across HF, VHF, and UHF bands. French and British procurement offices bundle these systems into broader command vehicle upgrade contracts, extending supplier relationships across fifteen-year maintenance cycles. Rheinmetall AG competes aggressively in this segment with platforms certified for NATO-wide deployment.
- Base Station Radio:Fixed-site infrastructure with integrated power amplification and antenna arrays anchors command center communications networks.
- Manpack Radio:Backpack-configurable systems bridge the mobility gap between handheld and vehicular platforms for extended patrol operations.
Margin structures invert the volume hierarchy, with fixed infrastructure commanding premium pricing through integration complexity and long-term service obligations.
Technology:
Architecture transitions are compressing supplier ecosystems, as programmable platforms displace hardware-fixed alternatives that cannot match firmware update velocities.
- Software Defined Radio:Reprogrammable chipsets unifying HF, VHF, and UHF functions onto single platforms enable waveform updates without hardware replacement. L3Harris Technologies Inc. leverages its SDR portfolio to sustain technology leadership across NATO procurement programs, while Thales Group anchors European demand through French and British defense ministry relationships. SDR platforms are gaining share fastest as militaries prioritize spectrum agility in contested electromagnetic environments.
- Frequency Hopping:Rapid pseudorandom frequency switching provides anti-jam protection against electronic warfare threats in Eastern European and Indo-Pacific theaters. Defense forces across NATO member states mandate this capability for frontline units operating within adversarial jamming range.
- Direct Sequence Spread Spectrum:Wideband signal spreading techniques enhance low-probability-of-intercept characteristics for sensitive communications.
- Analog Modulation:Legacy hardware-fixed architectures face accelerated obsolescence as encryption and interoperability requirements harden.
Investment flows concentrate on programmable architectures; stranded asset risk accumulates most heavily in hardware-fixed legacy inventory.
End User:
Budget authority fragmentation across defense and civilian agencies creates divergent certification pathways and procurement timelines.
- Defense Forces:National military procurement offices command the largest program budgets, with multi-year contracting horizons and stringent NATO STANAG compliance requirements. The United States, Germany, and Australia anchor demand through structured modernization programs replacing analog systems with encrypted digital networks.
- Emergency Responders:German and Australian disaster response agencies are adopting militarized encryption standards, creating crossover demand for hardened commercial platforms.
- Law Enforcement:Police tactical units require interoperable communications with military and emergency services during coordinated operations.
- Security Agencies:Intelligence and protective services demand specialized form factors with enhanced low-probability-of-intercept capabilities.
Procurement scale concentrates with Defense Forces; regulatory complexity is expanding fastest for Emergency Responders as civilian agencies adopt military-grade security standards.
Deployment:
Operational context determines power budget constraints, environmental hardening requirements, and integration complexity with broader command systems.
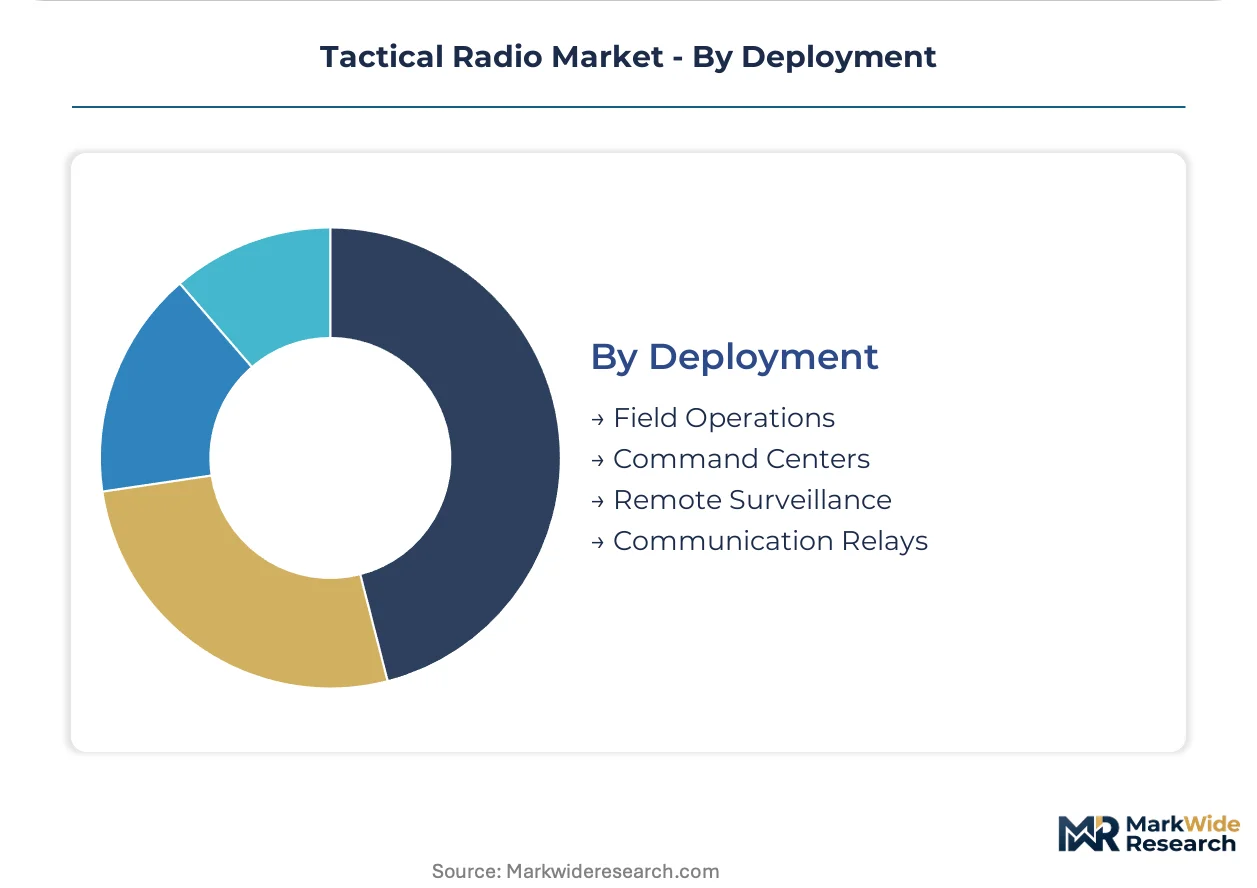
- Field Operations:Dismounted and vehicular platforms operating at the tactical edge face severe tradeoffs between battery life, thermal management, and transmission range. FCC spectrum allocation rules in the United States and EU CE marking requirements under the Radio Equipment Directive shape product certification for cross-border procurement eligibility.
- Command Centers:Fixed-site installations with reliable power infrastructure prioritize integration breadth over portability.
- Remote Surveillance:Unattended sensor relay platforms demand ultra-low power consumption for extended autonomous operation.
- Communication Relays:Aerial and elevated repeater systems extend network coverage beyond line-of-sight limitations.
Integration requirements concentrate in Command Centers; environmental stress is most acute for Field Operations platforms subject to contested electromagnetic conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Huntsville, Alabama anchors North American defense electronics manufacturing, hosting concentrated radio frequency engineering talent pools that supply NATO-aligned tactical communications programs across multiple allied nations.
United States
The Pentagon's Handheld, Manpack, and Small Form Fit program drives encrypted digital radio procurement through L3Harris Technologies and RTX Corporation supply relationships. FCC spectrum allocation rules under Part 90 govern military and first-responder frequency coordination. Defense contractor clusters in Huntsville and San Diego sustain firmware development velocity for software-defined architectures fielded across Army and Marine Corps units.
Germany
The Bundeswehr's digitization roadmap accelerates vehicular radio replacements in armored vehicle fleets through Rheinmetall AG platform integration. EU CE marking requirements under the Radio Equipment Directive mandate electromagnetic compatibility certification for cross-border NATO STANAG compliance. Industrial concentrations in Munich and Düsseldorf host microwave engineering centers serving Franco-German defense procurement frameworks.
Australia
The Land 200 Phase 2B program structures tactical communications modernization around single-contractor system integration for voice, data, and electronic warfare coordination. TGA-equivalent defense certification pathways align with Five Eyes intelligence-sharing encryption standards. Melbourne and Canberra host program management offices managing Indo-Pacific theater interoperability requirements with US and UK forces.
United Kingdom
The British Army's Morpheus program consolidates tactical radio procurement under full-spectrum communication system integrators rather than discrete component suppliers. EU AI Act provisions are beginning to shape cognitive radio research funding for autonomous signal processing capabilities. Bristol and London defense ministry offices coordinate waveform certification timelines averaging eighteen to twenty-four months for new platform deployments.
France
Thales Group anchors domestic demand through deep relationships with the Direction Générale de l'Armement for encrypted battlefield networks. REACH and RoHS compliance requirements intersect with defense procurement rules under the EU Green Deal sustainable electronics framework. Toulouse and Paris metropolitan clusters concentrate RF engineering expertise for NATO-wide vehicular radio platform certification.
Tactical Radio Market Competitive Landscape
The competitive structure tilts toward full-spectrum system integrators consolidating previously fragmented component supply relationships. Defense procurement offices in Anglo-American frameworks now favor single-contractor responsibility over tiered vendor ecosystems. Two archetypes dominate: established defense primes with firmware-centric service models, and specialized vehicular platform engineers with NATO STANAG certification depth. Competitive moves concentrate on strategic partnerships for waveform interoperability and capacity expansion in software-defined radio chipsets.
Among US-based defense primes, L3Harris Technologies Inc. and RTX Corporation exemplify the firmware-centric archetype, occupying positions that emphasize programmable waveform architectures over hardware-fixed manufacturing. Rheinmetall AG represents the European vehicular specialization vector, anchoring NATO interoperability certification for armored platform integration. Thales Group sits within the Franco-British defense ministry relationship tier, sustaining technology positioning through encrypted network program continuity.
| Leading Market Players |
|---|
| BAE Systems PLC |
| L3Harris Technologies Inc. |
| RTX Corporation |
| Motorola Solutions Inc. |
| Leonardo S.P.A. |
| General Dynamics Corporation |
| Thales Group |
| Rheinmetall AG |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal sustainable electronics procurement mandates gate qualified supplier access and premium-tier pricing eligibility for tactical radio manufacturers serving NATO defense ministries. Compliance with REACH substance restrictions and reduced-carbon manufacturing requirements separates certified suppliers from commodity competitors, concentrating margin pools among firms with verified green supply chains.
Pricing Analysis
Value-based pricing anchored to mission uptime and waveform interoperability outcomes dominates NATO procurement frameworks. Three-tier pricing structure across certified-mission, standard-tactical, and economy-commercial levels reflects NATO STANAG compliance grade and encryption export licensing status. Pricing pressure stems from firmware-as-a-service subscription models displacing perpetual hardware licenses. Dismounted infantry procurement offices exhibit highest price sensitivity; command center infrastructure buyers prioritize integration reliability over unit cost.
Supply Chain Analysis
NATO STANAG certification and EU CE marking under the Radio Equipment Directive gate supplier qualification, compressing eligible vendor pools for cross-border defense tenders. Gallium nitride substrate processing concentrates in China and the United States; rare earth magnet supply draws from Chinese refining operations. Single-source vulnerability in GaN wafer supply threatens power amplifier production timelines. Distribution runs through defense prime contractor ecosystems rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tactical radio market consolidation accelerates as firmware-centric service models strand hardware-fixed platform manufacturers with depreciating legacy inventories. NATO procurement offices favor single-contractor system integration, forcing component specialists into acquisition or exit.
For Market Incumbents: Anchor technology positioning through captive software-defined radio chipset development and NATO waveform certification depth. Acquire specialized vehicular platform engineers in Germany and France to secure armored vehicle integration relationships. Threat of cognitive radio R&D funding concentration under EU AI Act provisions demands algorithmic investment acceleration. For New Entrants and Emerging Players: Digital-channel defense procurement platforms offer route-to-market bypass of traditional prime contractor capture. Target Australian Land 200 and British Army Morpheus program subcontractor tiers where system integrators seek qualified component suppliers. White-space exists in emergency responder crossover segments adopting militarized encryption standards. For Investors and Strategic Acquirers: Bundeswehr digitization roadmap acceleration is the leading indicator that European vehicular radio replacement demand is entering sustained expansion phase. Acquisition target archetype: mid-cap vehicular platform specialists with NATO STANAG certification and fifteen-year maintenance contract visibility. Signal to monitor: EU AI Act cognitive radio research funding allocation announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Chipset Development | Programmable architectures extend platform lifecycles across multiple NATO operational theaters without hardware replacement. |
| NATO STANAG Waveform Certification | Cross-border interoperability compliance locks out non-certified suppliers from allied defense procurement pools. |
| Firmware-as-a-Service Subscription Launch | Recurring revenue streams displace one-time hardware sales across dismounted infantry modernization programs. |
| Emergency Responder Market Entry | German and Australian disaster response agencies adopt militarized encryption standards for hardened commercial platforms. |
| Cognitive Radio R&D Investment | EU AI Act autonomous signal processing provisions open funding pathways for machine-learning-enabled spectrum sensing. |
Research Methodology
Document review covered defense ministry procurement databases, NATO standardization agreements, and FCC spectrum allocation filings, complemented by interviews with program managers at L3Harris Technologies, Thales Group, and Rheinmetall AG. Primary fieldwork engaged RF engineering directors, defense procurement officers, and electromagnetic compatibility testing laboratory heads. Secondary validation drew from SEC 10-K defense segment disclosures, EU Official Journal tender notices, and Australian Department of Defence annual reports. Bottom-up unit shipment estimates and top-down defense budget allocation analysis were triangulated against contractor revenue segment reporting.
Historical contract award patterns were cross-referenced against procurement panel input from Five Eyes defense ministry officials. Segmentation modeling covered product form factor, technology architecture, end-user category, and deployment context across the projection horizon. CAGRs were derived from fitted trend analysis of encrypted digital radio replacement cycles and software-defined platform adoption curves. Forecast inputs included NATO member state defense expenditure trajectories and spectrum reallocation policy announcements.
Inputs from classified program briefings were available through the study window; gaps in future waveform specification timelines introduce uncertainty bands around deployment acceleration scenarios. Forecasts reflect documented assumptions regarding EU Green Deal procurement rule implementation velocity and rare earth supply chain stability. Stakeholders should weight assumptions against their own operating context and national security clearance access levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Inertial Navigation System Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
High-End Inertial Systems Market