
 Aviation Cyber Security Market | 2026-2036
Aviation Cyber Security Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Cyber Security Market Intelligence
Managed security service subscriptions for continuous threat monitoring is realigning how aviation operators procure cyber defense, shifting capital expenditure into recurring operational models. Honeywell International Inc. leverages its avionics heritage to embed security into connected aircraft platforms. BAE Systems plc sustains defense-grade encryption capabilities across military and dual-use aviation contracts. Cisco Systems Inc. competes through network-layer visibility products tailored to airport IT infrastructure.
Aviation cyber security encompasses protective technologies, protocols, and services engineered to safeguard aircraft systems, air traffic networks, and airport data infrastructure from unauthorized access, disruption, or exploitation, typically operating across encrypted communication channels with sub-millisecond latency requirements for real-time avionics integrity. Its primary purpose is to ensure continuous safety-critical operations while preserving passenger data confidentiality and cargo chain custody across interconnected global aviation ecosystems. Identity and access management solutions command substantial deployment share as multi-operator airport environments proliferate user credential complexity. Cloud-based and hybrid deployment architectures represent the fastest-expanding configuration category, driven by airline desires to reduce on-site security operations center overhead while retaining sovereign data controls over flight-critical systems.
The FAA mandates cyber risk management frameworks under evolving special conditions for connected aircraft systems, while EASA enforces design assurance levels that embed security into avionics certification pathways. The EU AI Act and NIS2 Directive further compel airport operators and air navigation service providers to maintain incident reporting regimes and supply chain security audits. Stakeholders must weigh sovereign data residency requirements against cloud-native threat intelligence velocity when architecting next-generation aviation security stacks.
Market Dynamics
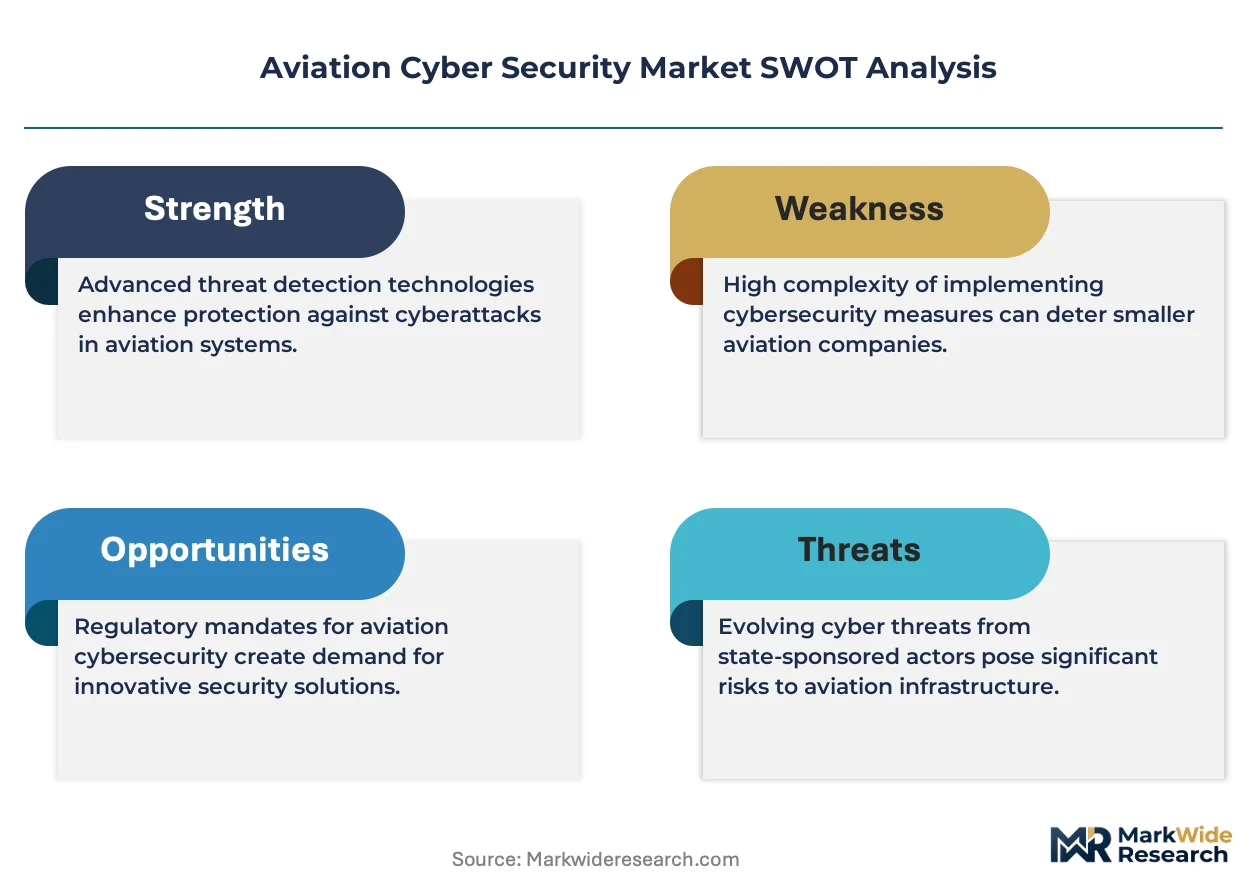
Flight deck digitization and connected aircraft architectures are forcing aviation operators to rebuild cyber defense from perimeter firewalls toward embedded system integrity. This structural shift elevates real-time threat detection above retrospective audit compliance.
Growth Catalysts
- NIS2 Directive mandates:European airport operators must deploy continuous monitoring systems and report incidents within 24 hours, accelerating procurement of managed security services.
- Zero-trust architecture adoption:Airlines retrofit legacy fleet networks with micro-segmentation to isolate avionics from passenger Wi-Fi and in-flight entertainment systems.
- Germany:Frankfurt and Munich airport modernization programs prioritize identity and access management for multi-tenant ground handling environments.
Market Restraints
- Semiconductor supply concentration:Specialized aviation-grade secure processors depend on limited foundry capacity in Taiwan, creating 18-24 month procurement lead times.
- FAA special conditions friction:Connected aircraft certification requires extensive documentation of cyber risk mitigation, extending type certificate amendment timelines.
- Qualified personnel scarcity:Aviation cyber security engineering demands dual expertise in DO-178C software assurance and threat intelligence analysis, constraining vendor scaling.
Strategic Opportunities
- France:Paris-Charles de Gaulle and Orly infrastructure upgrades create demand for cloud-native security operations centers with sovereign data controls.
- AI-driven anomaly detection:Machine learning models trained on flight data recorder patterns enable predictive threat identification before system compromise.
- United Kingdom CAA framework:Emerging guidance on aviation cyber resilience provides first-mover advantage for vendors aligning product roadmaps to certification pathways.
Industry Challenges
- DO-326A/ED-202A compliance complexity:Airframers struggle to harmonize security objectives across variant-specific aircraft configurations while maintaining common type certification.
- Multi-stakeholder coordination:Airport operators, airlines, ground handlers, and air navigation service providers maintain incompatible security incident classification systems, fragmenting response protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Cyber Security Market |
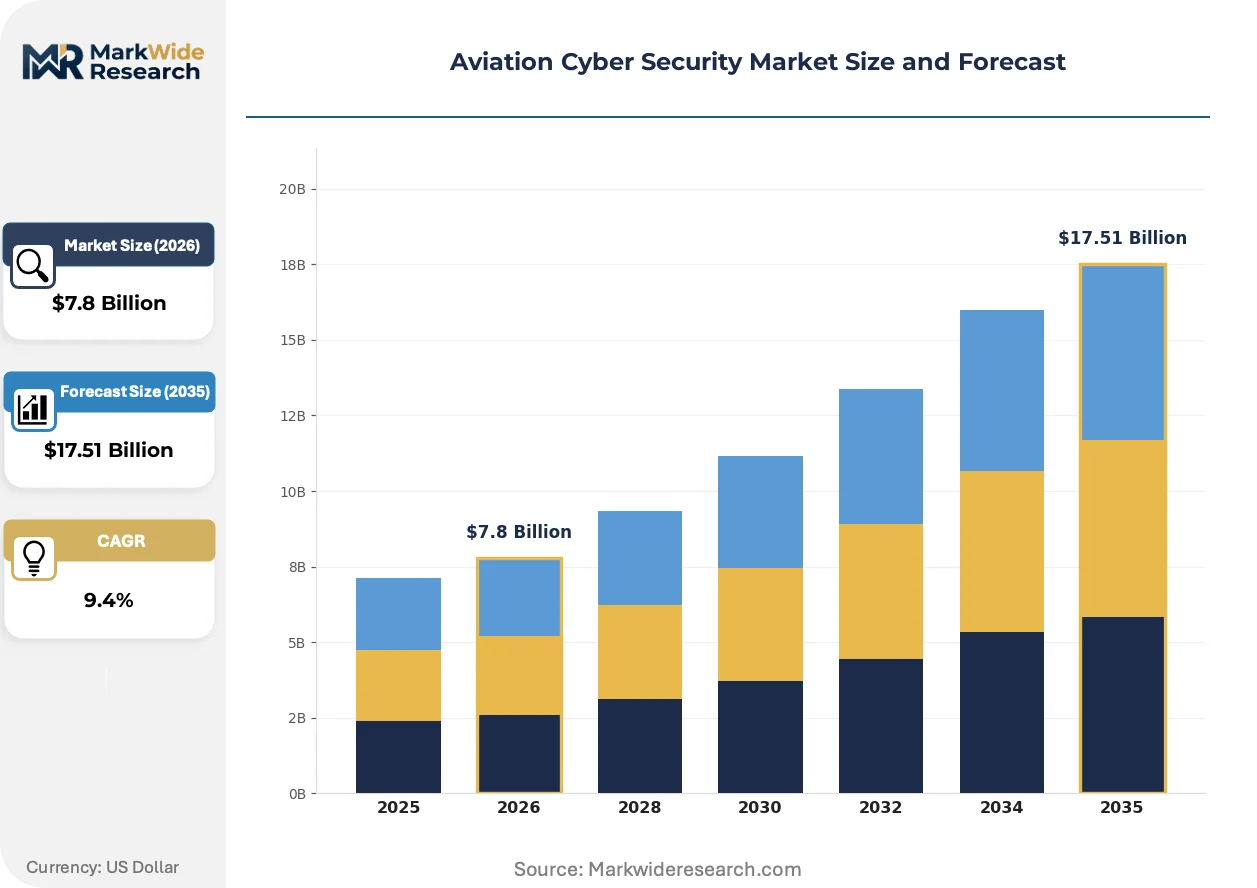
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Firewall, Intrusion Detection System, Data Loss Prevention, Encryption, Identity & Access Management, Security Information & Event Management Deployment: Cloud-Based, On-Premises, Hybrid, Managed Security Services Application: Air Traffic Control, Passenger Data Protection, Aircraft Systems Security, Airport Infrastructure Protection, Cargo Management Systems End User: Airlines, Regulatory Authorities, Airport Operators, Defense Contractors |
| Companies Covered | Honeywell International Inc., BAE Systems plc, Cisco Systems Inc., Palo Alto Networks Inc., Northrop Grumman Corporation, Thales Group, Raytheon Technologies Corporation, Leidos Holdings Inc., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Cyber Security Market Strategic Shifts & Innovations
Security-by-design principles are displacing bolt-on protection as aircraft systems architects embed cryptographic verification into avionics data buses from initial specification.
Hardware security modules with tamper-resistant key storage are unifying previously separate encryption domains for flight management, communications, and navigation systems. Tier-one avionics suppliers integrate these modules into line-replaceable units to reduce certification burden for airlines. This consolidation is unifying vendor accountability and compressing supply chain complexity for end operators.
EASA design assurance processes now mandate security objectives alongside functional safety targets under evolving certification memoranda. Airframers must demonstrate threat mitigation effectiveness through structured assurance cases. European narrowbody and regional jet programs face the most intensive scrutiny as regulators close historical gaps between airworthiness and cyber resilience.
Airline security operations are consolidating around subscription-based continuous monitoring rather than discrete penetration testing cycles. Managed detection and response providers displace in-house security operations center investments at mid-size carriers. This pattern is most visible in the United Kingdom and Germany where labor costs and skill scarcity accelerate outsourcing decisions.
Aviation Cyber Security Market Segmentation
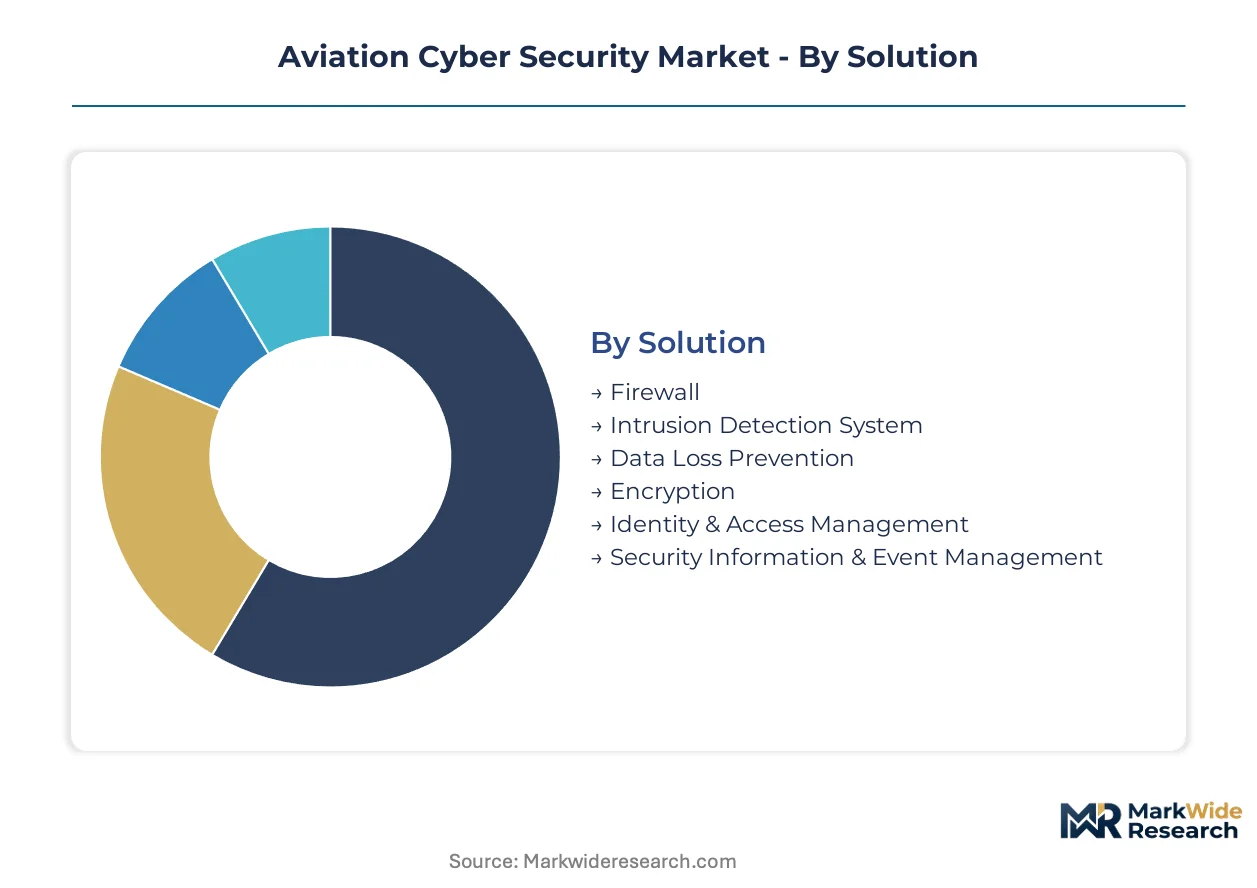
Aviation cyber security procurement patterns diverge sharply across solution types, deployment architectures, and operational applications. Understanding these segment boundaries reveals where capital deployment concentrates and which configurations airlines and airports prioritize under tightening regulatory pressure.
Solution:
Capital intensity varies dramatically across protective technologies, with hardware-anchored solutions demanding substantial upfront investment while software-centric offerings shift spending toward recurring operational models.
- Identity & Access Management:Multi-factor authentication platforms and privileged access controls govern credential complexity across multi-operator airport environments. Frankfurt and Munich modernization programs prioritize these systems for ground handling tenant segregation.
- Encryption:Hardware security modules with tamper-resistant key storage unify previously separate cryptographic domains for flight management, communications, and navigation systems. Tier-one avionics suppliers integrate these into line-replaceable units to compress airline certification burdens.
- Security Information & Event Management:Centralized log correlation platforms aggregate telemetry from disparate aviation subsystems.
- Firewall:Perimeter defense appliances segment aircraft networks from ground infrastructure.
- Intrusion Detection System:Real-time anomaly monitoring for avionics data buses and cabin networks.
- Data Loss Prevention:Passenger PII and cargo chain custody protection across booking and logistics platforms.
Identity & Access Management absorbs the bulk of installed capacity; Encryption is expanding most quickly as EASA design assurance mandates harden avionics certification pathways.
Deployment:
Procurement models across aviation operators reveal a decisive tilt toward externalized security operations, driven by qualified personnel scarcity and the complexity of maintaining sovereign data controls.
- Managed Security Services:Continuous threat monitoring subscriptions displace in-house security operations center investments at mid-size carriers. United Kingdom and Germany labor costs accelerate outsourcing decisions.
- Hybrid:Split architectures retain flight-critical system controls on-premises while pushing passenger-facing analytics to cloud environments. Paris-Charles de Gaulle infrastructure upgrades specify these configurations for sovereign data requirements.
- Cloud-Based:Native threat intelligence velocity attracts carriers accepting third-party infrastructure for non-safety systems.
- On-Premises:Legacy stack preservation among risk-averse operators with established security operations center staffing.
Hybrid deployments dominate new procurement cycles; Managed Security Services are climbing the fastest as NIS2 Directive incident reporting obligations tighten.
Application:
Operational criticality determines investment sequencing, with safety-of-flight systems commanding regulatory attention and passenger-facing platforms driving compliance expenditure.
- Aircraft Systems Security:Embedded protection for flight management computers, communications suites, and navigation equipment. FAA special conditions require extensive cyber risk documentation for connected aircraft type certificates.
- Passenger Data Protection:GDPR-aligned confidentiality controls for booking, biometric, and loyalty program databases. EU AI Act automated decision-making constraints amplify deployment scope.
- Air Traffic Control:Ground-to-air datalink integrity and ground network segmentation for air navigation service providers.
- Airport Infrastructure Protection:Baggage handling, access control, and building management system defenses.
- Cargo Management Systems:Supply chain custody verification and customs integration security.
Aircraft Systems Security anchors the highest per-unit spending; Passenger Data Protection is gaining share fastest under European regulatory compulsion.
End User:
Budget authority and procurement sophistication diverge across stakeholder types, with commercial operators balancing operational imperatives against regulatory mandates.
- Airlines:Fleet-wide retrofit programs and connected aircraft security integration. Zero-trust architecture adoption drives micro-segmentation between avionics and passenger Wi-Fi domains.
- Airport Operators:Multi-tenant environment governance and ground handler access provisioning. NIS2 Directive continuous monitoring obligations accelerate procurement.
- Defense Contractors:Military aviation dual-use platforms with defense-grade encryption requirements.
- Regulatory Authorities:Certification framework development and oversight technology deployment.
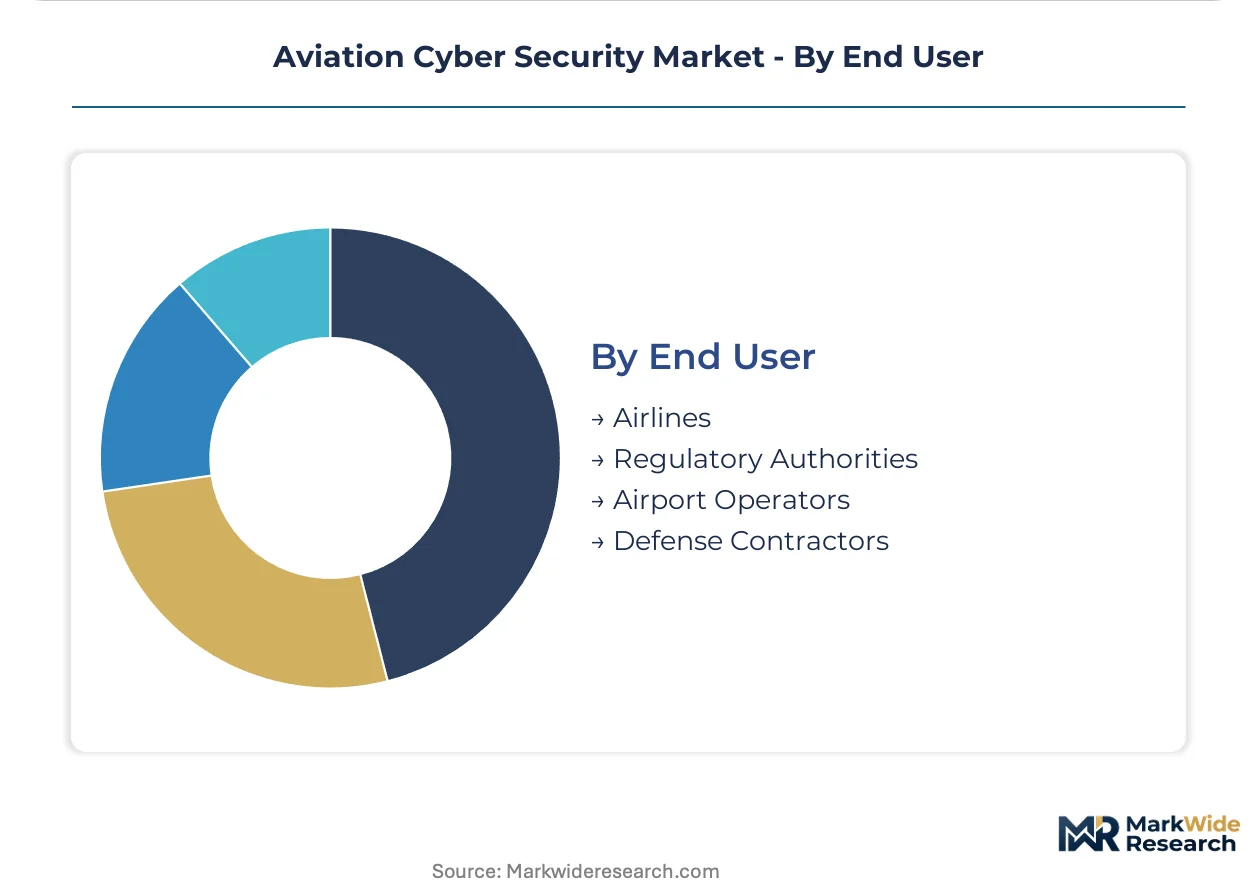
Airlines commit the largest absolute expenditure; Airport Operators are scaling fastest under European critical infrastructure redesignation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of aviation cyber security solutions concentrates in the United States and Europe, while consumption accelerates across airport modernization programs in Germany, France, and the United Kingdom. European regulatory pressure from the EU AI Act and NIS2 Directive is outpacing procurement timelines elsewhere.
Germany
Frankfurt and Munich airport modernization programs drive demand for identity and access management systems in multi-tenant ground handling environments. The NIS2 Directive mandates continuous monitoring and 24-hour incident reporting for critical infrastructure operators. Bavaria hosts clusters of avionics suppliers integrating hardware security modules into line-replaceable units for airline retrofit programs.
France
Paris-Charles de Gaulle and Orly infrastructure upgrades specify hybrid cloud-native security operations centers with sovereign data controls. EASA design assurance processes now mandate security objectives alongside functional safety targets for narrowbody certification pathways. Île-de-France concentrates defense-grade encryption specialists serving dual-use aviation contracts.
United Kingdom
The UK CAA framework on aviation cyber resilience provides first-mover positioning for vendors aligning product roadmaps to emerging certification pathways. NIS2 Directive transposition compels airport operators to deploy managed detection and response services. London and Southeast England host airline security operations consolidating around subscription-based continuous monitoring models.
United States
FAA special conditions for connected aircraft systems require extensive cyber risk documentation, extending type certificate amendment timelines for commercial fleets. The FAA mandates cyber risk management frameworks under evolving special conditions. California and Washington aerospace clusters embed security-by-design principles into avionics data bus specifications from initial system architecture.
Canada
Transport Canada alignment with ICAO cyber security standards drives procurement for air navigation service providers managing transborder datalink integrity. Federal critical infrastructure designation compels continuous monitoring investments at Toronto Pearson and Vancouver International. Ontario and Quebec host airline operations outsourcing security operations center functions to managed service providers.
Aviation Cyber Security Market Key Industry Players
Top-tier vendors anchor defense-grade encryption and avionics-integrated platforms, while mid-tier specialists compete on managed security service velocity and cloud-native deployment flexibility. Market structure tilts toward consolidated accountability as hardware security module consolidation compresses supply chain complexity for airline operators. Three archetypes dominate: avionics heritage suppliers embedding security into connected aircraft platforms, network-layer visibility providers targeting airport IT infrastructure, and managed detection and response specialists displacing in-house security operations. Competitive moves concentrate on strategic partnerships for certification pathway alignment and portfolio diversification across safety-critical and passenger-facing systems.
Within the avionics-integrated tier, Honeywell International Inc. and BAE Systems plc exemplify heritage suppliers leveraging embedded platform positions. Honeywell represents the avionics-to-security extension archetype, while BAE Systems occupies the defense-grade encryption specialist position spanning military and dual-use contracts. Cisco Systems Inc. anchors the network-layer visibility provider archetype, competing through airport IT infrastructure products. These three companies illustrate the competitive fault lines between embedded system integrity and perimeter defense approaches.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| BAE Systems plc |
| Cisco Systems Inc. |
| Palo Alto Networks Inc. |
| Northrop Grumman Corporation |
| Thales Group |
| Raytheon Technologies Corporation |
| Leidos Holdings Inc. |
| Lockheed Martin Corporation |
| Others |
Cost & Logistics Intelligence
Specialized aviation-grade secure processors from Taiwan foundries cascade through tiered pricing structures as hardware security module consolidation compresses supplier margins while elevating certification premiums for DO-178C compliant components.
Pricing Analysis
Cost-down pressure on mid-tier managed security service subscriptions accelerates because airline procurement teams benchmark against hyperscaler pricing benchmarks. Three-tier pricing structure across defense-grade, commercial-aviation, and general-enterprise levels separates EASA-certified avionics modules from airport perimeter appliances. Certification tier and sovereign data residency requirements drive price differentiation. Regional carriers exhibit highest price sensitivity; defense contractors demonstrate lowest.
Supply Chain Analysis
EASA and FAA certification gates constrain supplier qualification to a narrow tier of foundries and systems integrators with proven airworthiness documentation. Hardware security module production concentrates in Taiwan, Germany, and the United States. Supply chains draw from specialized secure silicon, tamper-resistant enclosures, and aviation-qualified firmware stacks. Single-source vulnerability persists for DO-178C certified software tooling. Distribution runs through tier-one avionics OEMs and managed security service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation cyber security vendors are racing to deepen upstream control over certified hardware production and downstream capture of continuous monitoring subscriptions.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by securing exclusive supply agreements with Taiwan foundries for aviation-grade secure processors. Pursue EASA design assurance pre-certification for integrated hardware-software stacks to extend amendment timelines that freeze out competitors. For New Entrants and Emerging Players: Enter via managed detection and response subscriptions for mid-size European carriers under NIS2 Directive pressure, where qualified personnel scarcity accelerates outsourcing decisions. Target United Kingdom airline security operations consolidating around subscription models. Position through sovereign data control guarantees. For Investors and Strategic Acquirers: EASA publication of security-objective mandates for narrowbody programs is the leading indicator that certification-aligned vendors will command acquisition premiums. Frame long-term viability around decade-long fleet retrofit cycles and recurring service revenue. Monitor FAA special conditions expansion for connected aircraft as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Alignment | EASA design assurance memoranda embed security objectives alongside functional safety targets for airframers. |
| Hardware Security Module Integration | Tier-one avionics suppliers consolidate previously separate encryption domains into line-replaceable units. |
| Managed Security Service Expansion | Continuous monitoring subscriptions displace in-house security operations center investments at mid-size carriers. |
| Sovereign Data Center Partnership | Paris-Charles de Gaulle infrastructure upgrades specify hybrid architectures with French data residency. |
| Zero-Trust Architecture Retrofit | Airlines micro-segment legacy fleet networks to isolate avionics from passenger Wi-Fi domains. |
Research Approach
Document review covered FAA special conditions filings, EASA certification memoranda, and EU NIS2 Directive implementation guidance, complemented by interviews with airline chief information security officers, airport operations directors, avionics platform engineers, and managed security service provider executives. Secondary sources included airframer SEC disclosures, airport authority procurement records, and aviation regulatory dockets. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-level projections across solution type, deployment architecture, application domain, and end-user category fed into consolidated value estimates across the analysis window. CAGRs derived from regression against fleet modernization timelines, regulatory compliance deadlines, and outsourcing penetration curves. Forecast inputs incorporated connected aircraft delivery schedules and NIS2 Directive enforcement phase transitions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or FAA certification timeline extensions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Electronic Countermeasures Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Asia-Pacific Missiles and Missile Defense Systems Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Europe Cyber Weapons Market