
 Ballistics Targeting Software Market | 2026-2036
Ballistics Targeting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistics Targeting Software Market Outlook
ITAR compliance is decoupling legacy vendors from emerging defense procurement channels, forcing software providers to restructure their engineering and data-handling architectures. Raytheon Technologies leverages its captive aerospace supply chain to sustain end-to-end certification for classified targeting environments. Lockheed Martin anchors its position through deep integration with next-generation fire control systems across multiple service branches. BAE Systems competes by controlling sovereign European defense data pathways that sit outside direct U.S. regulatory jurisdiction.
Ballistics targeting software comprises computational platforms that process projectile dynamics, atmospheric conditions, and weapon-system parameters to generate real-time firing solutions with sub-minute-of-angle precision. These systems serve military sniper teams, artillery units, and precision marksmanship training programs by collapsing complex external ballistics into actionable reticle adjustments or automated weapon guidance. Trajectory analysis products dominate current military procurement volumes due to their foundational role in long-range engagement protocols, while AI-powered systems represent the fastest-expanding technology tier as neural networks compress wind-reading and Coriolis calculations into predictive models that previously required dedicated meteorological support. Cloud-based solutions remain nascent in deployed combat environments where electromagnetic denial and data sovereignty concerns restrict off-premise processing, though law enforcement training centers increasingly accept hybrid architectures for simulator networks.
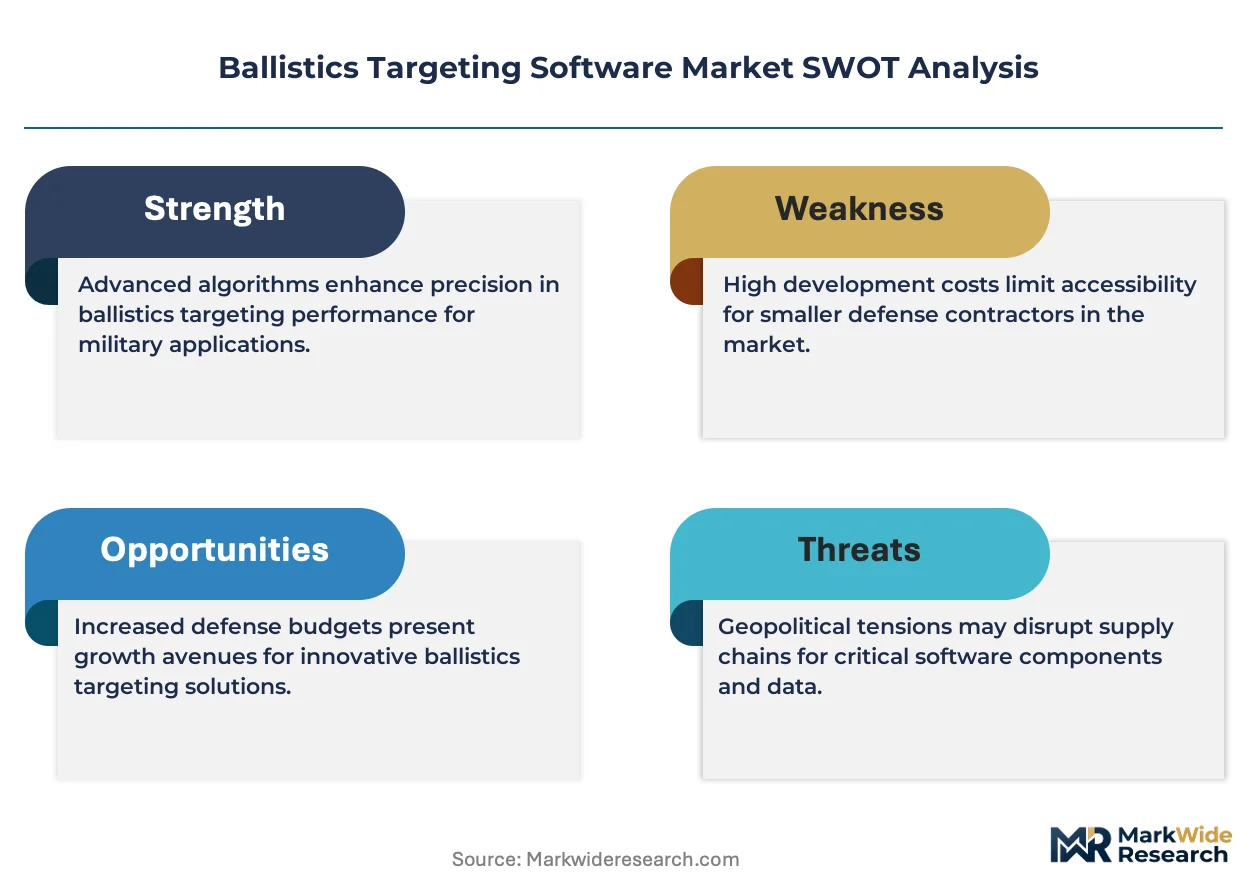
The U.S. Department of State's Directorate of Defense Trade Controls enforces ITAR classifications that restrict ballistics algorithm exports without validated licenses, while the U.S. Department of Commerce's Bureau of Industry and Security administers parallel EAR controls on commercial encryption modules embedded within targeting software. European defense procurement operates under the EU Green Deal's emerging digital sustainability disclosure requirements and national security carve-outs that permit member states to bypass standard competition rules for sensitive military software acquisitions. Stakeholders must monitor whether emerging EU AI Act risk classifications will sweep predictive targeting algorithms into high-risk categories that trigger mandatory conformity assessments and operational logging obligations.
Market Dynamics
AI-powered predictive algorithms are compressing meteorological dependencies into real-time firing solutions, restructuring procurement priorities across NATO defense ministries and law enforcement training authorities.
Growth Catalysts
- ITAR Compliance Mandates:The U.S. International Traffic in Arms Regulations now require validated licenses for ballistics algorithm exports, creating captive demand for domestic engineering architectures that process classified targeting data.
- Artillery Modernization Programs:Military procurement offices are absorbing specialized trajectory analysis licenses to support long-range engagement protocols requiring sub-minute-of-angle precision.
- Law Enforcement Training Budgets:Precision marksmanship programs in the United States are expanding simulator network deployments that integrate hybrid cloud architectures for scenario-based ballistics instruction.
Market Restraints
- Input Cost Volatility:Specialized GPU clusters for neural network training face supply concentration in Taiwan semiconductor fabrication facilities.
- Technical Limitation:Electromagnetic denial environments restrict cloud-based processing in deployed combat theaters, forcing redundant on-premise hardware investments.
- Regulatory Friction:The EU AI Act's emerging risk classifications threaten to sweep predictive targeting algorithms into high-risk categories requiring mandatory conformity assessments.
Strategic Opportunities
- Underpenetrated European Sovereign Pathways:BAE Systems and continental competitors are building defense data architectures outside direct U.S. regulatory jurisdiction to capture EU member state procurement.
- Convergence of LiDAR and Neural Networks:Wind-reading sensors fused with machine learning models enable autonomous atmospheric compensation without dedicated meteorological support teams.
- India's Defense Indigenization:The country's PLI scheme and DGFT localization mandates are creating import-substitution openings for ballistics software engineered to BIS standards.
Industry Challenges
- ITAR Certification Timeline:The U.S. Department of State's Directorate of Defense Trade Controls processes licensing applications through multi-month validation queues that delay revenue recognition.
- Legacy Fire Control Integration:Next-generation AI modules must interface with decades-old weapon system architectures that lack standardized data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistics Targeting Software Market |
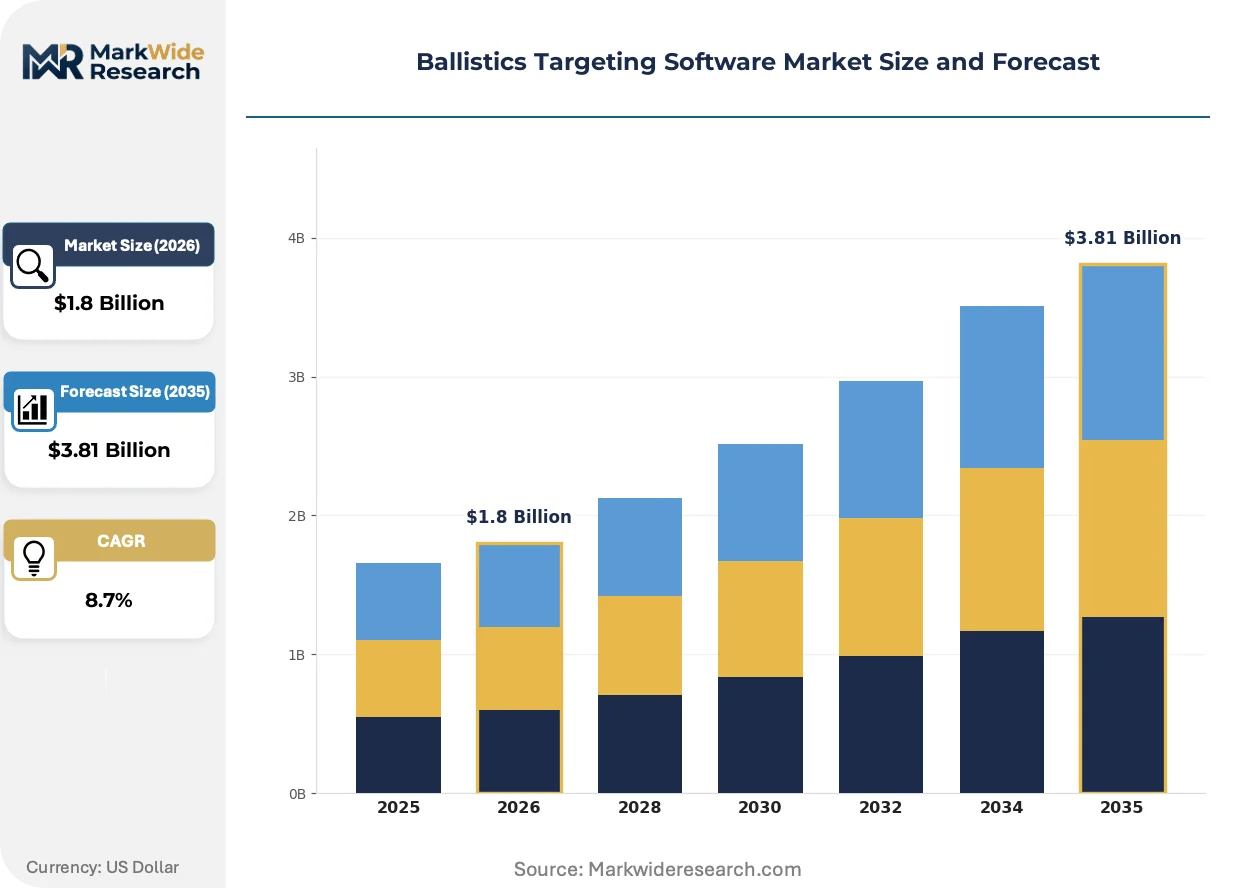
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Software, Trajectory Analysis, Impact Prediction, Calibration Tools End User: Defense Contractors, Law Enforcement Agencies, Military Units, Outdoor Enthusiasts Technology: Cloud-Based Solutions, On-Premise Software, Mobile Applications, AI-Powered Systems Application: Training Simulations, Range Operations, Forensics Analysis, Target Acquisition |
| Companies Covered | Raytheon Technologies, Lockheed Martin, BAE Systems, Northrop Grumman Corporation, Applied Ballistics, Sierra Bullets, Nikon Inc., Horus Vision Reticle Technologies, Sniper Tools Design, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistics Targeting Software Market Strategic Shifts
Neural network architectures are collapsing external ballistics computation into predictive models that previously required dedicated atmospheric support teams, rewiring competitive advantage around data sovereignty and algorithmic certification.
Edge-deployed inference engines are absorbing Coriolis and spin-drift calculations that previously demanded cloud connectivity. Sniper teams and forward artillery observers are adopting these hardened units in electromagnetic-contested environments where satellite uplinks face jamming threats. This compression is absorbing the middleware layer between sensor arrays and firing solutions, reducing latency to sub-second response windows.
The EU AI Act's risk-based classification framework is reclassifying predictive targeting algorithms as high-risk automated decision systems. European defense procurement offices must now document conformity assessments and operational logging for software acquisitions that integrate neural network components. Member states are responding through national security carve-outs that permit sensitive military software acquisitions to bypass standard competition rules.
Law enforcement training centers are unbundling perpetual licenses in favor of subscription-based simulator access. Municipal procurement offices prefer operational expenditure models that align software costs with annual training cycle intensity. This preference shift concentrates most visibly in United States metropolitan police departments modernizing their precision marksmanship programs through hybrid cloud architectures.
Ballistics Targeting Software Market Segmentation
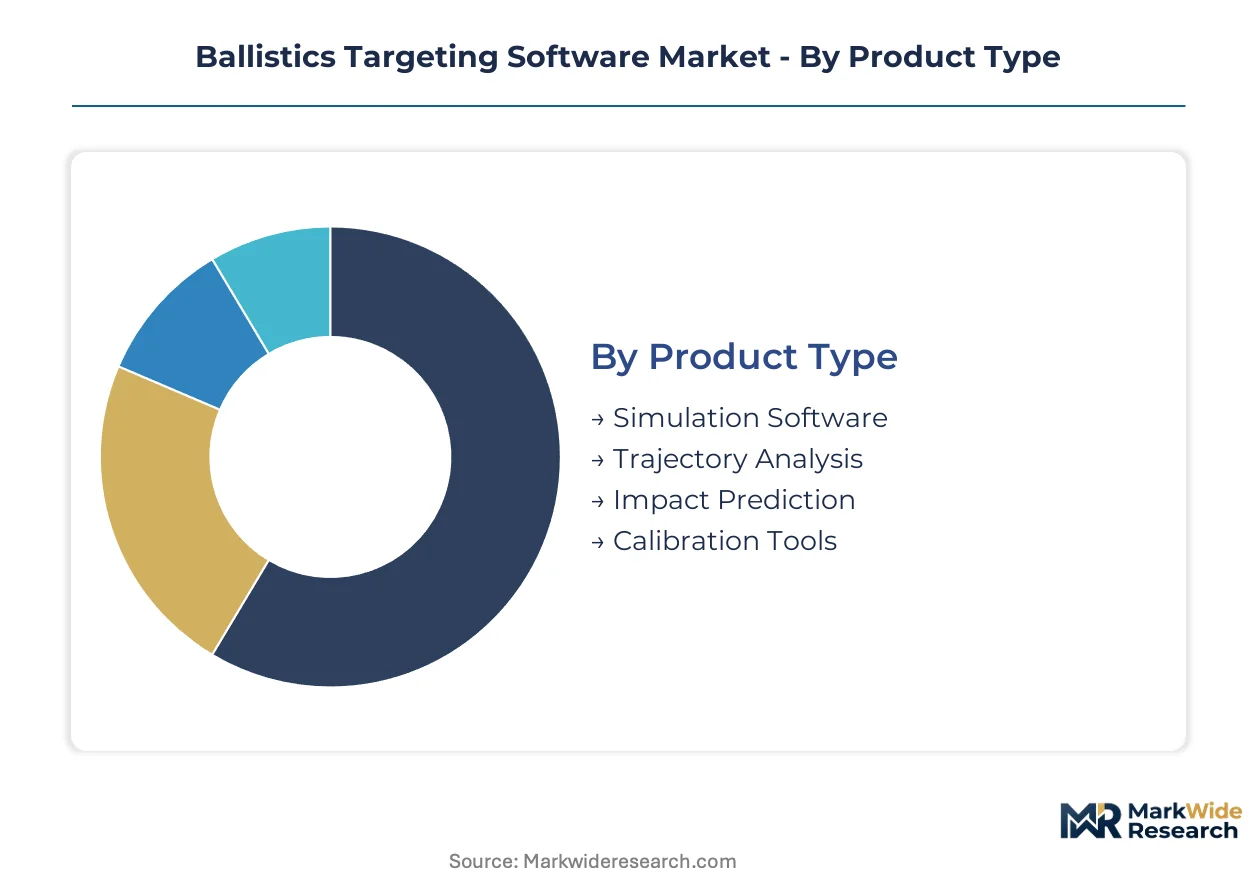
Ballistics targeting software segments diverge sharply by capital intensity and regulatory exposure, with defense-grade systems demanding multi-year ITAR certification investments while commercial training modules deploy through standardized licensing frameworks. Understanding these structural divides reveals where procurement budgets concentrate and which technology tiers attract venture backing.
Product Type:
Capital intensity peaks in trajectory analysis platforms that require classified algorithm development and dedicated secure facilities, while simulation software leverages reusable codebases that amortize engineering costs across civilian and military deployments.
- Simulation Software:Virtual environments replicate atmospheric conditions, weapon recoil, and ballistic drop for repeatable training scenarios without live ammunition expenditure. Municipal law enforcement agencies in the United States absorb the majority of procurement volumes for indoor range simulators that compress annual marksmanship qualification costs.
- Trajectory Analysis:Computational engines process six-degrees-of-freedom projectile models against real-time meteorological feeds to generate firing solutions for sniper teams and artillery batteries. Defense contractors across NATO member states dominate demand following tightened export control frameworks that restrict algorithm transfers without validated licensing.
- Impact Prediction:Terminal ballistics modules calculate penetration dynamics and fragmentation patterns for munitions selection.
- Calibration Tools:Weapon-zeroing utilities align optical systems with barrel harmonics and ammunition lot variations.
Most installed capacity flows through Trajectory Analysis. Expansion is steepest in Simulation Software.
End User:
Customer type determines pricing architecture, with defense contractors accepting multi-year enterprise agreements that embed compliance overhead while outdoor enthusiasts purchase through direct-to-consumer digital storefronts.
- Defense Contractors:Prime integrators embed ballistics modules into fire control systems for armored vehicles, naval guns, and precision strike packages. These engagements span hardware-software co-development cycles that lock vendors into decade-long sustainment relationships.
- Military Units:Special operations forces and forward artillery observers procure hardened edge-computing units for electromagnetic-contested environments where cloud connectivity fails. Budget authority concentrates in United States Special Operations Command and British Army precision fires programs.
- Law Enforcement Agencies:Metropolitan police departments subscribe to simulator networks for scenario-based officer training.
- Outdoor Enthusiasts:Long-range shooting hobbyists purchase mobile applications with basic atmospheric inputs and drop-table outputs.
Defense Contractors command the highest contract values per seat. Law Enforcement Agencies are expanding most quickly as municipal training budgets modernize.
Technology:
Deployment architecture splits between sovereign data requirements that mandate on-premise installation and operational flexibility that favors cloud-based delivery models.
- AI-Powered Systems:Neural network architectures compress wind-reading and Coriolis calculations into predictive models that previously required dedicated meteorological support teams. United States military modernization programs anchor demand as procurement offices prioritize firing solution speed over legacy manual inputs.
- On-Premise Software:Air-gapped installations process classified targeting data within secure facilities that satisfy ITAR custody requirements. European defense ministries increasingly specify these architectures to maintain sovereign control over sensitive ballistic algorithms.
- Cloud-Based Solutions:Hybrid architectures serve law enforcement training centers with elastic compute for scenario rendering.
- Mobile Applications:Smartphone-deployed calculators target precision shooting hobbyists with consumer-grade GPS and barometric sensors.
On-Premise Software retains the largest installed base. AI-Powered Systems are climbing the fastest as neural network training costs decline.
Application:
Use case determines integration complexity, with target acquisition demanding real-time sensor fusion while forensics analysis operates on stored datasets with relaxed latency requirements.
- Training Simulations:Scenario-based instruction platforms replicate engagement geometry, atmospheric variability, and decision stress for skill development without live-fire resource consumption. United States metropolitan police departments and military marksmanship schools absorb the majority of procurement as they replace legacy paper-based qualification protocols.
- Target Acquisition:Real-time firing solution generation for sniper teams and precision strike platforms requires sub-second latency from sensor input to reticle adjustment. Forward-deployed military units in electromagnetic-denial theaters drive demand for hardened edge inference engines.
- Range Operations:Commercial shooting facilities manage lane allocation, scoring, and safety monitoring through integrated software stacks.
- Forensics Analysis:Crime scene reconstruction tools calculate bullet trajectories from impact evidence for investigative and judicial proceedings.
Training Simulations deploy the widest seat count. Target Acquisition commands the steepest expansion trajectory as AI inference migrates to tactical edge hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense software engineering talent clusters in the United States, United Kingdom, Germany, Israel, and India, with each jurisdiction cultivating distinct regulatory postures toward classified algorithm development and sovereign data control.
United States
Special Operations Command and Army precision fires programs absorb the majority of military procurement volumes for hardened edge-computing units. The Department of State's Directorate of Defense Trade Controls enforces ITAR classifications that restrict ballistics algorithm exports without validated licenses. Huntsville, Alabama anchors a concentration of defense contractors integrating AI modules into next-generation fire control systems.
United Kingdom
British Army marksmanship schools and metropolitan police precision training programs drive demand for simulator network deployments. The UK operates under national security carve-outs that permit sensitive military software acquisitions to bypass standard EU competition rules. London and the Southeast concentrate systems integrators serving NATO interoperability requirements.
Germany
Bundeswehr artillery modernization and federal police tactical training budgets expand procurement of trajectory analysis platforms. The KBA and federal procurement offices coordinate with EU Green Deal digital sustainability disclosure requirements for defense acquisitions. Bavaria hosts engineering clusters developing sovereign European defense data pathways outside direct U.S. regulatory jurisdiction.
Israel
Israel Defense Forces precision strike units and export-oriented defense technology firms create dual-use demand for predictive targeting algorithms. The country's national security regulator maintains strict custody requirements for classified ballistic software development. Tel Aviv and Haifa anchor startup ecosystems fusing LiDAR sensors with neural network architectures for autonomous atmospheric compensation.
India
Defense indigenization mandates under the PLI scheme and DGFT localization requirements create import-substitution openings for ballistics software engineered to BIS standards. Indian Army artillery modernization and paramilitary precision training programs absorb specialized trajectory analysis licenses. Bengaluru and Hyderabad concentrate software engineering talent serving domestic defense procurement channels.
Ballistics Targeting Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels, with prime integrators leveraging decade-long sustainment relationships against agile vendors capturing municipal training budgets. The vendor base separates into three strategic archetypes: aerospace-defense conglomerates with captive certification infrastructure, sovereign European systems houses controlling non-U.S. data pathways, and precision shooting specialists serving law enforcement and consumer segments. Competitive moves concentrate on ITAR compliance architecture restructuring and AI inference engine miniaturization for electromagnetic-contested environments.
Within the aerospace-defense conglomerate tier, Raytheon Technologies and Lockheed Martin occupy positions defined by end-to-end ITAR certification and multi-service branch integration depth. BAE Systems exemplifies the sovereign European archetype, anchoring defense data architectures outside direct U.S. regulatory jurisdiction to capture EU member state procurement. Among precision application specialists, Applied Ballistics sits within the segment serving law enforcement training centers and long-range shooting enthusiasts through streamlined licensing frameworks.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Lockheed Martin |
| BAE Systems |
| Northrop Grumman Corporation |
| Applied Ballistics |
| Sierra Bullets |
| Nikon Inc. |
| Horus Vision Reticle Technologies |
| Sniper Tools Design |
| Others |
Value Chain & Pricing Dynamics
Defense software engineering talent clusters in Huntsville, Alabama and Tel Aviv, Israel concentrate classified algorithm development capabilities that command wage premiums driving three-tier spreads between ITAR-certified enterprise systems and commercial training modules.
Pricing Analysis
Bundled hardware-software sustainment contracts dominate defense procurement while unbundled SaaS subscriptions capture municipal law enforcement training budgets. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-certified fire control integrations from hybrid cloud simulator networks and consumer mobile applications. Price differentiation hinges on certification grade and after-sales service intensity. Cost compression in commercial tiers is intensifying because GPU cluster supply constraints elevate neural network training overhead. Law enforcement agencies exhibit highest price sensitivity; defense contractors accept decade-long enterprise agreements embedding compliance premiums.
Supply Chain Analysis
Workforce availability for secure facility engineering constrains output in the United States, Israel, and Germany where cleared personnel pipelines face recruitment bottlenecks. Specialized GPU clusters for neural network training draw from Taiwan and South Korea fabrication capacity. Cryptographic modules and hardened edge processors feed from U.S. captive aerospace supply chains. Single-source vulnerability in Taiwan semiconductor fabrication threatens training algorithm development timelines. Distribution runs through prime integrator direct sales for defense tiers and value-added reseller networks for law enforcement deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ITAR licensing mandates and EU AI Act risk classifications continuously elevate compliance investment thresholds that consolidate procurement around certified incumbents.
For Market Incumbents: Anchor multi-service branch integration depth through captive ITAR certification infrastructure that emerging entrants cannot replicate within viable timelines. Deepen backward integration into sovereign European data architectures to preempt BAE Systems' jurisdictional advantage. Prioritize AI inference engine miniaturization for electromagnetic-contested environments where cloud dependency disqualifies competitor offerings. For New Entrants and Emerging Players: Capture India's PLI scheme localization openings by engineering BIS-standard trajectory analysis modules for Indian Army artillery modernization programs. Exploit municipal law enforcement training budget expansion through subscription-based simulator networks that bypass defense-grade certification barriers. Pursue direct-to-consumer mobile application channels where atmospheric input calculators face minimal regulatory friction. For Investors and Strategic Acquirers: Defense technology conglomerates with captive aerospace supply chains represent the most active acquirer category in this space, prioritizing ITAR-compliant algorithm portfolios over standalone commercial training assets. Long-term viability centers on neural network architecture differentiation compressed into edge-deployable inference engines. Monitor EU AI Act conformity assessment documentation requirements as inflection indicator for European procurement accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Certification Architecture Restructuring | Validates algorithm exports through State Department licensing queues that competitors cannot bypass. |
| Edge Inference Engine Miniaturization | Enables sub-second firing solutions in electromagnetic-denial theaters where satellite uplinks fail. |
| Sovereign European Data Pathway Construction | Captures Bundeswehr and British Army procurement outside direct U.S. regulatory jurisdiction. |
| LiDAR-Neural Network Convergence | Fuses wind-reading sensors with machine learning to eliminate dedicated meteorological support teams. |
| Hybrid Cloud Simulator Network Expansion | Aligns operational expenditure models with U.S. metropolitan police department training cycle intensity. |
Study Parameters
Bottom-up defense contractor procurement modeling reconciled against top-down semiconductor supply chain tracking forms the analytical core of this study. Primary interviews with Special Operations Command program officers, ITAR compliance directors at prime integrators, municipal police training coordinators, and neural network engineering leads at Israeli defense startups combined with secondary validation against Directorate of Defense Trade Controls licensing disclosures, SEC 10-K filings, EU procurement databases, and Indian DGFT localization mandates. Triangulation across these sources yields volume estimates segmented by product type, end user, deployment technology, and application use case.
Historical trendline analysis of military modernization program budget authorizations and law enforcement precision training expenditure patterns anchored the projection framework. Segmentation dimensions modeled include product architecture, customer type, deployment sovereignty requirements, and regional regulatory cluster across the analysis window. CAGRs derived from algorithmic diffusion curves for AI-powered systems versus legacy trajectory analysis platforms, with neural network training cost decline curves and ITAR licensing queue duration data serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; ITAR-classified defense procurement carries tighter precision than commercial outdoor enthusiast applications where direct-to-consumer sales lack centralized reporting. Forecasts reflect documented assumptions regarding electromagnetic denial environment prevalence and EU AI Act enforcement timing. Material deviation in Taiwan semiconductor supply continuity or State Department licensing velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Aviation Cyber Security Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Military Computers Market