
 Cyber Weapons Market | 2026-2036
Cyber Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Cyber Weapons Market Intelligence
Subscription-based access to zero-day exploits is pivoting the market from single-tool sales toward continuous capability delivery. This model ensures users have access to the latest offensive techniques. Lockheed Martin Corporation leverages its defense integration expertise for cyber-physical threat systems. BAE Systems specializes in advanced threat intelligence for national security clients.
Cyber weapons are software tools designed to infiltrate, disrupt, or damage computer systems by exploiting specific vulnerabilities, such as unpatched CVEs. Their primary purpose is achieving strategic objectives like espionage or sabotage. Malware and ransomware represent the most deployed types of cyber weapons. Government Defense Agencies and Intelligence Services are the principal end-user segments, driving procurement for both offensive and defensive missions.
The Wassenaar Arrangement attempts to govern export controls on intrusion software, a key market component. National bodies like the US Department of Commerce's Bureau of Industry and Security (BIS) and China's MIIT enforce country-specific rules on technology proliferation. These regulations shape market access for private sector developers. Navigating the ethical lines between offensive capability development and defensive investment remains the core strategic challenge.
Market Dynamics
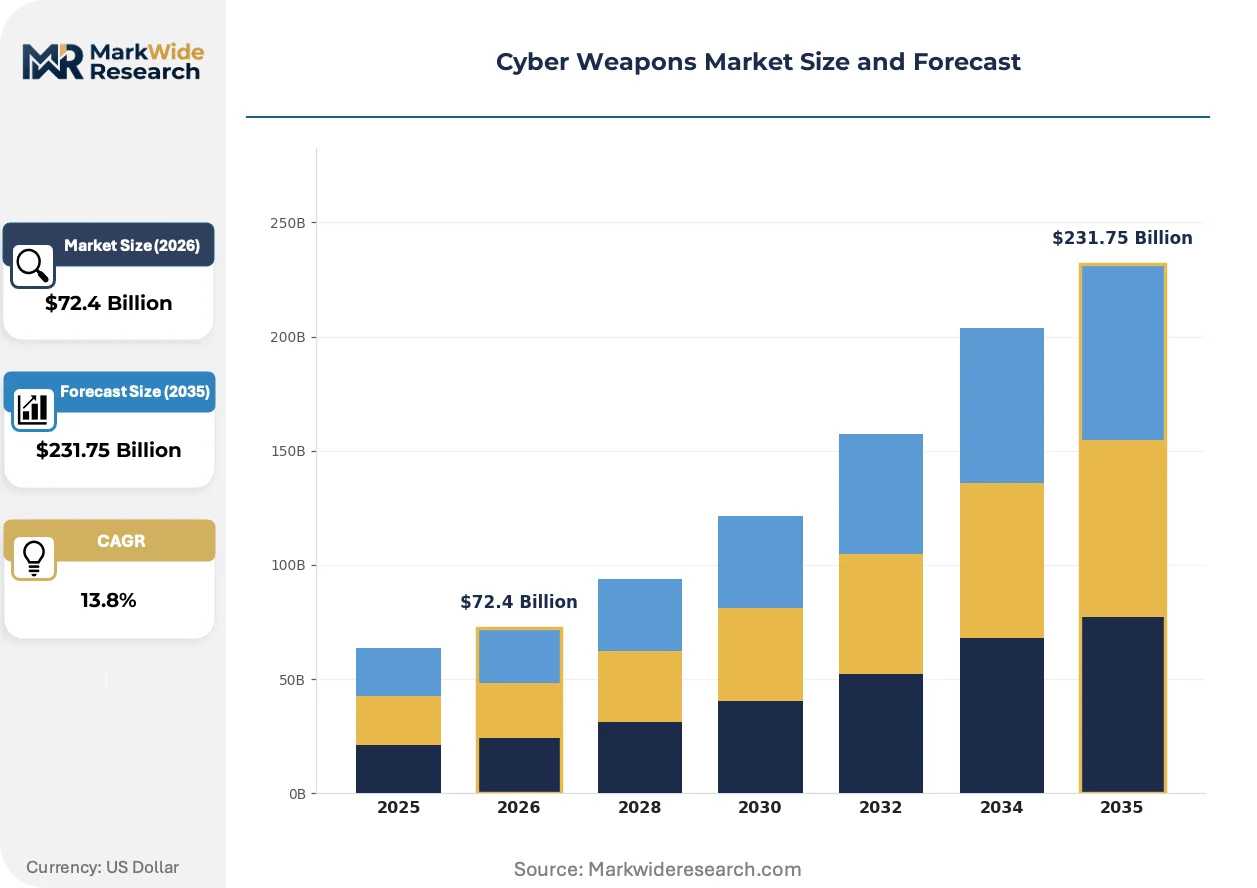
The central dynamic shaping the market is the escalating cycle of state-level offensive capability development clashing with nascent international efforts to regulate their proliferation. This tension between strategic military buildup by government defense agencies and the export controls of frameworks like the Wassenaar Arrangement defines the market's growth trajectory and legal boundaries.
Growth Catalysts
- Advanced Persistent Threats:The increasing sophistication and frequency of state-sponsored APT campaigns targeting critical infrastructure and government networks directly compel nations to invest in their own offensive and counter-cyber arsenals for deterrence and retaliation.
- Vulnerability Proliferation:A continuous stream of newly discovered software vulnerabilities, including unpatched common vulnerabilities and exposures (CVEs), provides the raw material for weapon development, creating a constant demand for new exploits.
- Geopolitical Competition:Intense strategic rivalry among nations, particularly the United States, Russia, and China, fuels a cyber arms race, driving national budgets for the procurement and in-house development of sophisticated cyber tools.
Market Restraints
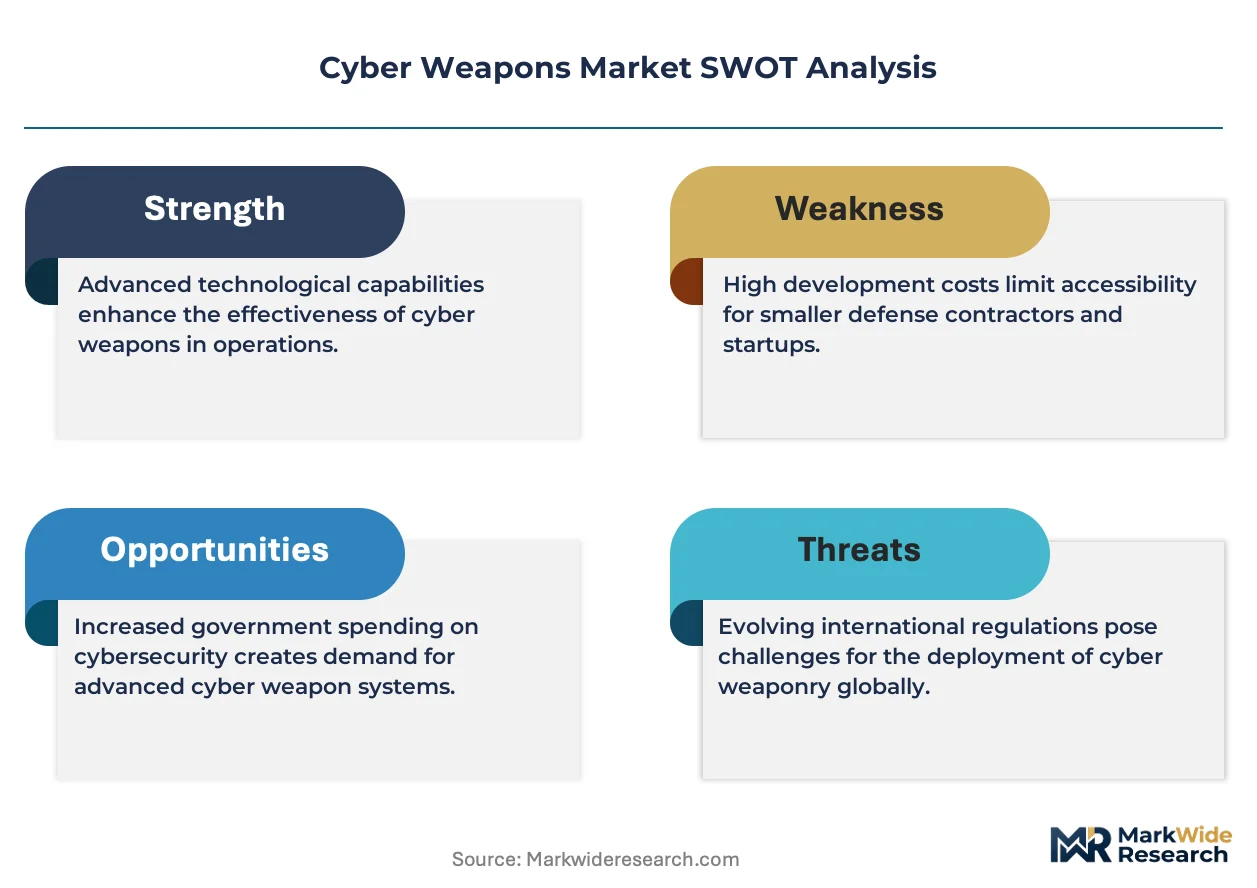
- Export Control Regimes:Multilateral agreements like the Wassenaar Arrangement and national rules from bodies such as the US Bureau of Industry and Security (BIS) create significant compliance burdens and restrict sales to certain countries, limiting market access for private developers.
- Perishability of Exploits:The value of zero-day exploits is inherently temporary, as they are rendered ineffective once the underlying vulnerability is discovered and patched by software vendors, creating high product turnover and investment risk.
- Risk of Unintended Escalation:The potential for a deployed cyber weapon to be captured, reverse-engineered, and used against its creator or allies, or to cause unintended collateral damage, imposes a significant strategic restraint on its use.
Strategic Opportunities
- AI-Powered Autonomous Agents:The convergence of artificial intelligence with exploit development platforms presents an opportunity to create autonomous cyber agents capable of identifying vulnerabilities and executing multi-stage attacks without direct human intervention.
- Cyber-Physical Systems Targeting:Expanding connectivity in industrial control systems (ICS) and operational technology (OT) opens a new frontier for cyber weapons designed to disrupt or disable physical infrastructure, such as power grids and water treatment facilities.
- Defensive Capability Transfer:There is a significant opportunity in providing allied nations, which lack advanced domestic development capabilities, with controlled access to defensive and counter-intelligence cyber tools and training packages.
Industry Challenges
- Scarcity of Elite Talent:A severe global shortage of highly skilled personnel with expertise in reverse engineering, vulnerability research, and exploit development creates a bottleneck, constraining the capacity of both state agencies and private firms.
- Attribution Ambiguity:The inherent difficulty in definitively and rapidly attributing cyber attacks to a specific actor complicates deterrence and response, making it challenging for policymakers to justify retaliatory actions.
- Legacy System Integration:Government agencies face significant technical hurdles in integrating cutting-edge cyber tools with older, often disparate, military command, control, and intelligence platforms, delaying operational readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyber Weapons Market |
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $231.75 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Malware, Ransomware, Trojans, Spyware, Rootkits Deployment: Cloud-Based, On-Premises, Hybrid, Edge Application: Cyber Espionage, Sabotage, Intellectual Property Theft, Disruption of Communications, Financial Fraud End User: Government Defense Agencies, Intelligence Services, Critical Infrastructure Operators, Security Research Organizations |
| Companies Covered | BAE Systems, Lockheed Martin Corporation, Northrop Grumman Corporation, General Dynamics Corporation, The Boeing Company, Raytheon Technologies Corporation, Airbus, L3Harris Technologies, Inc., Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyber Weapons Market Strategic Shifts & Innovations
The market is undergoing a professionalization, shifting from artisanal, bespoke tool creation toward an industrialized model of scalable capability development and delivery. This evolution is marked by the adoption of sophisticated software development practices and new commercial models that prioritize continuous access over single-asset ownership.
Automated exploit generation platforms represent a significant technological evolution. These systems use machine learning algorithms to analyze software for vulnerabilities and automatically develop functional exploit code. Government intelligence services and highly advanced threat groups are the primary adopters, accelerating their development cycles from weeks to days. This technology is unifying the discrete tasks of vulnerability discovery, exploit coding, and payload integration into a single, streamlined workflow.
Export control policies are formalizing the legitimate channels for cyber weapon sales. Regulations from the US Department of Commerce's Bureau of Industry and Security (BIS) and China's Ministry of Industry and Information Technology (MIIT) define strict rules for the transfer of intrusion software. This regulatory pressure forces private sector developers to build robust compliance programs to secure licenses for government contracts. The primary entities affected are specialized offensive security firms, which must now navigate complex legal frameworks to operate.
Subscription-based access is replacing the traditional one-time sale of individual tools. This "Exploit-as-a-Service" model provides customers with ongoing access to a curated and continuously updated portfolio of exploits for a recurring fee. The model disrupts the single-purchase transaction, offering users sustained capability rather than a depreciating asset. This trend is most prominent among the defense and intelligence agencies of the United States and Israel, which value persistent access to the latest offensive techniques.
Cyber Weapons Market Segmentation
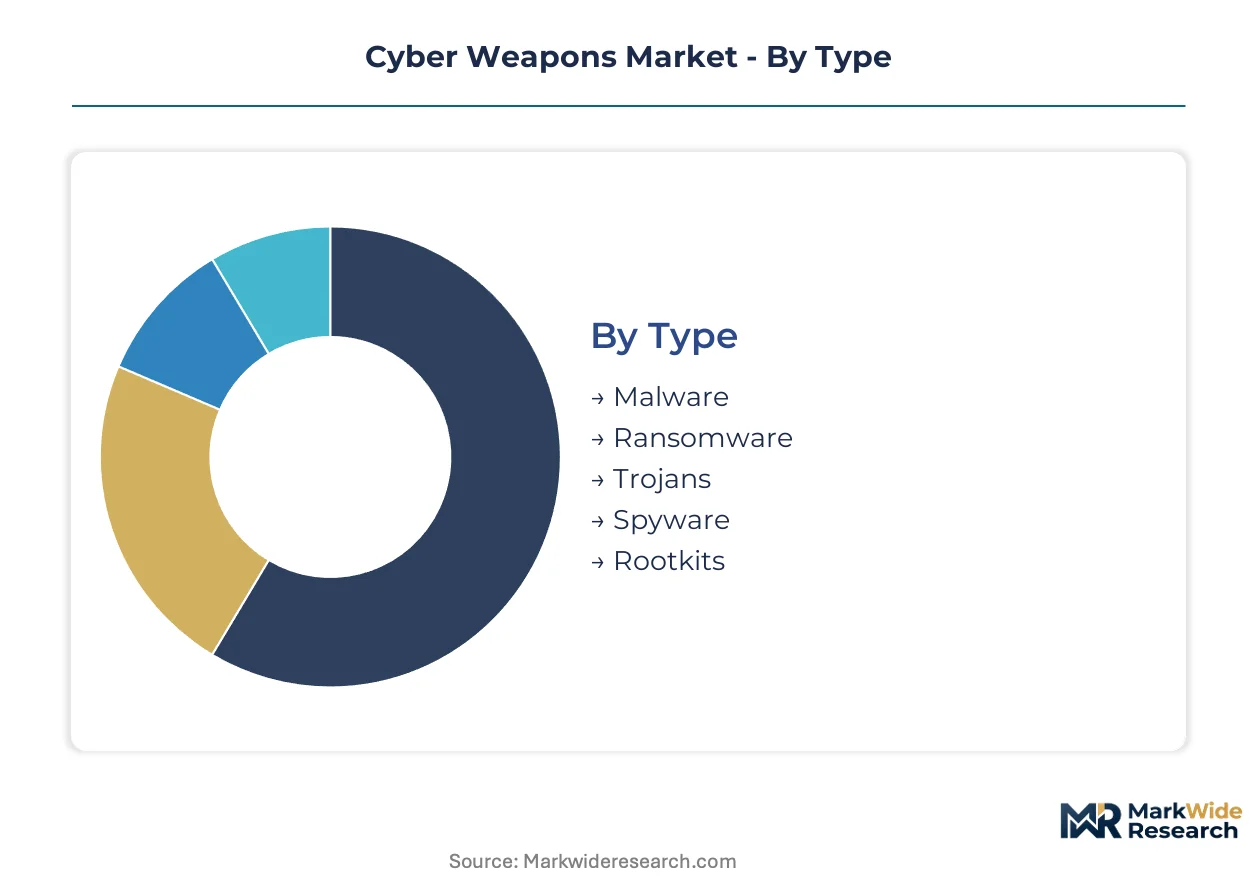
The segmentation analysis provides a granular view of the cyber weapons market, dissecting its various components to understand demand drivers and technological shifts. This detailed breakdown helps identify where specific offensive capabilities are being developed and deployed. Understanding these segments is crucial for strategic planning and regulatory oversight.
Type:
Supply concentration in the cyber weapons market increasingly favors sophisticated malware development platforms.
- Malware:Malware encompasses a broad category of malicious software designed to infiltrate or damage computer systems without user consent. Demand for advanced malware is concentrating in government defense agencies for offensive cyber operations, driven by the need for persistent access to adversary networks.
- Ransomware:Ransomware is a specific type of malware that encrypts a victim's files, demanding payment for their release. Its demand is primarily concentrated among financially motivated threat actors, but state-sponsored groups also employ it for disruption and revenue generation.
- Trojans:Trojans masquerade as legitimate software to gain unauthorized access, often for data exfiltration or remote control.
- Spyware:Spyware collects information about a user's activity without their knowledge, frequently used by intelligence services for surveillance.
- Rootkits:Rootkits provide privileged, stealthy access to a computer, enabling attackers to maintain hidden control over compromised systems.
Today's leader: Malware. Tomorrow's challenger: Ransomware.
Deployment:
The deployment models for cyber weapons vary significantly based on the target environment and operational requirements.
- Cloud-Based:Cloud-based deployment involves hosting cyber weapon infrastructure and operations within public or private cloud environments. Demand for cloud-based solutions is concentrating due to their scalability, global reach, and perceived anonymity for offensive operations.
- On-Premises:On-premises deployment refers to managing and operating cyber weapon systems directly within an organization's internal infrastructure. Government defense agencies prefer on-premises solutions for sensitive operations requiring maximum control and data sovereignty.
- Hybrid:Hybrid deployment integrates both cloud and on-premises components, offering flexibility and combining the benefits of both approaches.
- Edge:Edge deployment places cyber weapon capabilities closer to target networks, reducing latency and enabling attacks on distributed systems.
The market is evolving towards more distributed and flexible deployment architectures to enhance operational agility.
Application:
Cyber weapon applications are directly driven by the strategic objectives of their end-users.
- Cyber Espionage:Cyber espionage involves using cyber weapons to illegally obtain secret or sensitive information from individuals, competitors, or foreign governments. Intelligence services primarily utilize these tools to gather critical intelligence, supporting national security interests.
- Sabotage:Sabotage applications aim to disrupt, damage, or destroy critical systems, often targeting industrial control systems or national infrastructure. Government defense agencies use sabotage tools for strategic military objectives, impacting adversary capabilities.
- Intellectual Property Theft:This application focuses on stealing proprietary information, trade secrets, and research data from corporations or research institutions.
- Disruption of Communications:Cyber weapons in this category aim to disable or interfere with communication networks, impacting military command and control or civilian services.
- Financial Fraud:Financial fraud applications leverage cyber tools to illicitly acquire funds or financial information from individuals and organizations.
The diversification of applications reflects the expanding range of strategic goals achievable through cyber operations.
End User:
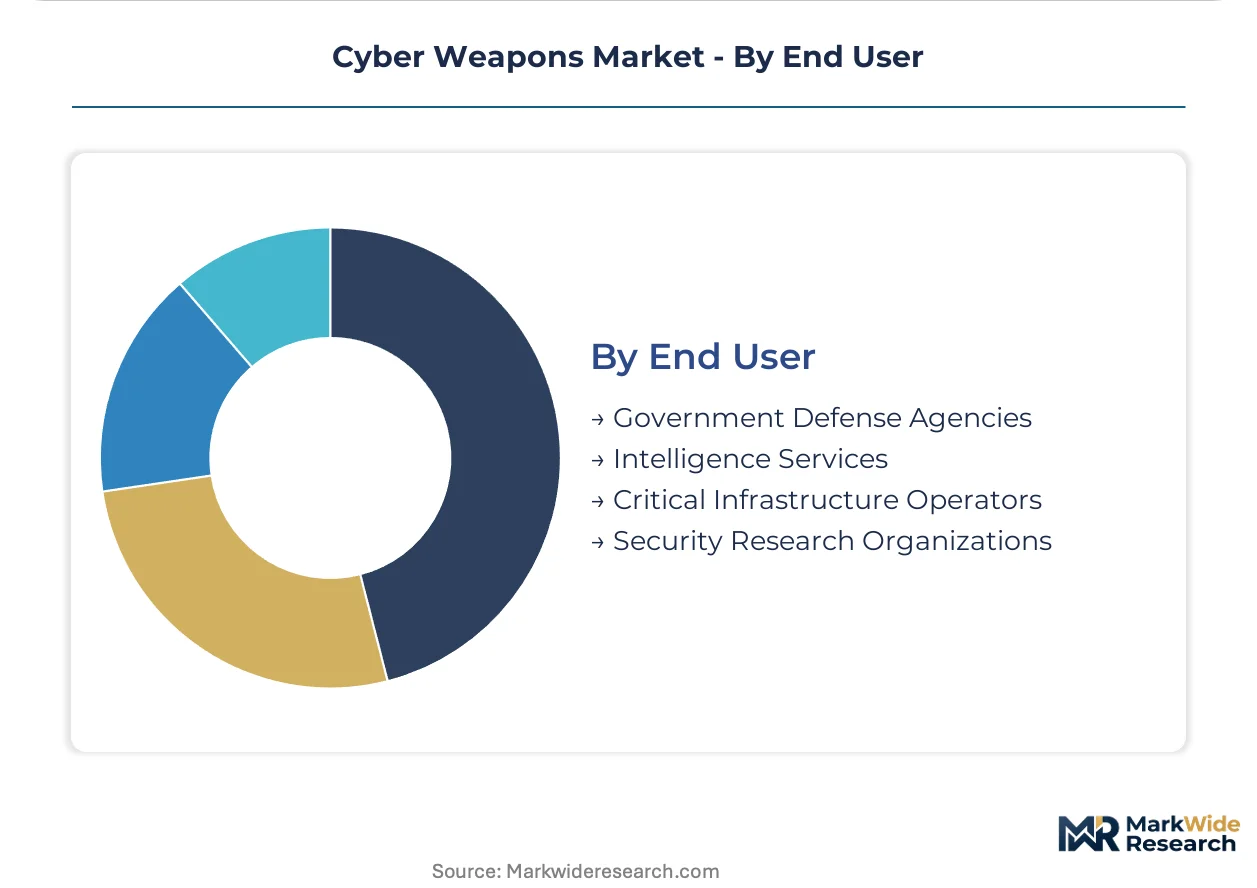
The volume of cyber weapon procurement is heavily concentrated among specific government and defense entities.
- Government Defense Agencies:These agencies acquire cyber weapons for both offensive and defensive missions, including intelligence gathering, deterrence, and strategic retaliation. Demand is concentrating in the United States, Israel, and Russia, reflecting geopolitical competition and advanced capabilities.
- Intelligence Services:Intelligence services utilize cyber weapons for covert operations, espionage, and counter-intelligence, operating within strict national security frameworks. Their demand centers on stealthy, persistent access tools for long-term surveillance and data exfiltration.
- Critical Infrastructure Operators:These operators primarily focus on defensive cyber tools, but some acquire limited offensive capabilities for active defense or threat hunting.
- Security Research Organizations:These organizations develop and analyze cyber weapons for vulnerability research, penetration testing, and understanding threat actor methodologies.
Government entities remain the dominant force shaping the demand and development trajectory of the cyber weapons market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consistently drives significant cyber weapons procurement, while Russia's strategic investments reflect its long-standing focus on offensive capabilities. This global market sees diverse national priorities shaping development and deployment. Geopolitical competition intensifies demand across key regions.
United States
Demand for advanced cyber weapons in the United States stems from persistent APT campaigns and critical infrastructure protection needs. The US Department of Commerce's BIS enforces stringent export controls on intrusion software. Silicon Valley and Washington D.C. serve as hubs for both private sector innovation and government agency procurement.
Russia
Russia's investment in cyber offensive tools is fueled by geopolitical competition and national security objectives. The country maintains strict internal regulations on cyber technology development and use. Moscow's defense contractors actively develop state-sponsored malware for strategic operations.
Israel
Israel's demand concentrates on sophisticated cyber espionage tools and counter-cyber capabilities due to regional threats. The Israeli Ministry of Defense oversees technology exports and dual-use item controls. Tel Aviv's vibrant cybersecurity sector fosters innovation in offensive and defensive technologies.
China
China's cyber weapons market is driven by intellectual property theft and national defense modernization goals. The Ministry of Industry and Information Technology (MIIT) regulates domestic cyber product development and foreign technology acquisition. Beijing and Shenzhen host numerous state-backed research institutes advancing cyber warfare capabilities.
United Kingdom
The United Kingdom focuses on developing advanced threat intelligence and defensive capabilities against state-sponsored attacks. The UK government implements export controls aligned with the Wassenaar Arrangement for intrusion software. London's financial district and Cheltenham's GCHQ drive demand for sophisticated cyber defense and offense tools.
Cyber Weapons Market Key Industry Players
Top-tier vendors anchor the market's offensive cyber capability development, often integrating cyber tools into broader defense systems, while specialized firms focus on niche exploit research and vulnerability discovery. The market exhibits a tiered structure, with a few large defense contractors alongside numerous boutique security companies and government-backed entities. Strategic archetypes include integrated defense providers, pure-play cyber security specialists offering exploit-as-a-service, and state-affiliated research organizations. Strategic partnerships for technology sharing and targeted M&A activity to acquire specific expertise are dominant competitive moves.
On the premium-tier vector, Lockheed Martin Corporation exemplifies large-scale defense integration, leveraging its extensive expertise across complex cyber-physical threat systems for critical government defense agencies. BAE Systems, a UK-based aerospace and defense company, represents advanced threat intelligence and national security solutions, specializing in sophisticated offensive and defensive cyber capabilities. Northrop Grumman Corporation further occupies a significant position among integrated defense providers, focusing on advanced cyber warfare capabilities for government clients and intelligence services. These entities collectively anchor the market's high-end, strategic cyber weapon development and deployment, often operating under strict national security frameworks.
| Leading Market Players |
|---|
| BAE Systems |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| The Boeing Company |
| Raytheon Technologies Corporation |
| Airbus |
| L3Harris Technologies, Inc. |
| Leonardo S.p.A. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers and integrated defense contractors shape supply behavior in the cyber weapons market. Their strategic objectives and operational costs dictate pricing discipline, often prioritizing national security over pure commercial margins.
Pricing Analysis
Capacity additions in Israel and the United States are reshaping price floors for advanced cyber tools. The market predominantly uses subscription-based "Exploit-as-a-Service" and project-based development models. Price differentiation stems from customization levels, the exclusivity of zero-day exploits, and comprehensive after-sales integration support. Pricing pressure stems from the scarcity of elite talent and continuous R&D investment, making government defense agencies the least price-sensitive buyers.
Supply Chain Analysis
Elite cybersecurity talent supply rests on specialized academic programs and government intelligence agencies in the United States, Israel, and Russia. Supply concentration for advanced cyber weapons originates from these nations, alongside China. Raw material dependencies include vulnerability research data and high-performance computing infrastructure. A key supply chain risk involves single-source vulnerability for niche zero-day exploits and regulatory restrictions on their export. Distribution runs through direct sales channels to government defense agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cyber weapons market is entering a late-cycle quality story, driven by a demand shift toward premium, continuously updated offensive capabilities. Government defense agencies prioritize persistent access to sophisticated zero-day exploits over single-purchase tools.
For Market Incumbents:Deepen strategic partnerships with national intelligence services to secure early access to critical vulnerability research. Incumbents must invest heavily in AI-powered automated exploit generation platforms to mitigate the perishability of zero-day exploits. This vertical integration into vulnerability discovery counters the threat posed by emerging specialized firms offering Exploit-as-a-Service models. Maintaining control over the entire exploit lifecycle ensures sustained competitive advantage.
For New Entrants and Emerging Players:US Department of Commerce's BIS export controls in the United States open a window for new entrants specializing in compliant cyber weapon development. Target the underpenetrated segment of defensive capability transfer to allied nations lacking advanced domestic development. Focus on cyber-physical systems targeting for critical infrastructure as a niche application. A compliance-first approach, emphasizing legitimate channels for technology transfer, provides a strong go-to-market angle.
For Investors and Strategic Acquirers:Valuations sit cheapest among boutique offensive security firms possessing strong intellectual property in exploit development but limited distribution networks. Long-term viability favors entities with proprietary vulnerability research capabilities and AI-driven exploit development platforms. Target niche exploit developers or talent pools specializing in specific industrial control systems. The signal to watch is increased regulatory clarity on the legitimate export channels for offensive cyber tools, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Exploit Generation Platform Development | Accelerates vulnerability discovery and exploit coding, reducing development cycles for state actors. |
| Secure Supply Chain for Zero-Day Exploits | Ensures continuous access to critical offensive capabilities for national security clients. |
| Cyber-Physical Systems Expertise Acquisition | Expands targeting capabilities into critical infrastructure, enhancing strategic disruption options. |
| Wassenaar Arrangement Compliance Program Establishment | Navigates complex international export controls, enabling legitimate sales to allied governments. |
| Elite Talent Development and Retention Programs | Addresses the scarcity of skilled personnel, maintaining a competitive edge in advanced cyber warfare. |
Research Approach
Direct dialogue with cyber warfare strategists, offensive security engineers, government procurement officers, and intelligence analysts informed primary insights. This qualitative data combined with extensive secondary research, including government defense spending reports and national cybersecurity strategies, provided a comprehensive view. Academic vulnerability research papers and technology patent databases further validated market dynamics. Bottom-up data aggregation and top-down market sizing triangulated volume and value outputs.
Quantitative models produced market volume and value projections across the analysis window. Segmentation dimensions modeled included type, deployment, application, end-user, and geographic demand. Compound annual growth rates were derived through regression analysis on historical data and projected future investment trends. Geopolitical tension levels and national cybersecurity budget allocations served as key industry-specific forecast inputs.
Revisions become necessary when major international cyber arms control treaties or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions regarding geopolitical stability and national security priorities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Railway Cyber Security Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Defence Cybersecurity Market