
 Global C4I Systems Market | 2026-2036
Global C4I Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global C4I Systems Market Analysis
ISO 9001 certification for defense contractors is bifurcating the vendor landscape into qualified system integrators and excluded component suppliers. Lockheed Martin leverages its vertically integrated command-center production to sustain sole-source positions on major NATO programs. BAE Systems anchors European demand through its UK-Germany industrial footprint, while Elbit Systems competes aggressively in tactical-communications upgrades across Eastern European militaries.
C4I systems fuse command, control, communications, computers, and intelligence functions into networked architectures operating at latency thresholds below 50 milliseconds for real-time battlefield coordination. These systems process multi-source sensor feeds into common operating pictures for joint-force commanders. Communication Equipment generates the deepest margin pools due to encrypted waveform refresh cycles, while AI Integration represents the fastest-expanding technology segment as militaries deploy predictive analytics for threat prioritization. Surveillance Solutions remain mature with stable replacement demand across coastal and border monitoring programs.
FDA oversight applies where C4I platforms interface with medical-logistics modules, while FCC spectrum allocations govern tactical radio frequency bands in US deployments. NATO STANAG interoperability standards and the EU AI Act jointly determine which vendors qualify for transatlantic joint-command programs. Stakeholders must monitor evolving certification requirements for sovereign-cloud data residency as alliance members tighten supply-chain security screening.
Market Dynamics
Defense procurement offices are consolidating vendor lists around AI-readiness certifications, compressing qualification timelines from 18 months to under 9 months for NATO STANAG-compliant platforms.
Growth Catalysts
- EU AI Act compliance mandates:Article 6 requirements for high-risk AI systems are forcing defense ministries to prioritize vendors with pre-certified algorithmic audit trails.
- Joint-force interoperability:US-Germany-Australia trilateral exercises are generating demand for common operating picture architectures that fuse multi-domain sensor feeds.
- Tactical edge computing:Processing latency requirements below 50 milliseconds are pulling ruggedized GPU modules into forward-deployed command nodes.
Market Restraints
- GaN semiconductor supply concentration:Taiwan-based foundries control 78% of defense-grade gallium nitride wafer output, exposing radio frequency component supply to single-point fragility.
- Sovereign-cloud data residency:Germany's IT-SiG 2.0 and Australia's DISP framework impose conflicting encryption key custody rules that fragment cross-border program architectures.
- Legacy system integration debt:Existing command platforms running 1990s-era messaging protocols require middleware layers that consume 40% of program engineering budgets.
Strategic Opportunities
- Poland's eastern flank modernization:The Territorial Defence Forces are fielding mobile command posts with open-architecture standards that bypass incumbent vendor lock-in.
- Predictive maintenance AI:Machine learning models trained on vibration and thermal signatures are reducing mean-time-to-repair for satellite ground stations by 60%.
- Swarm-drone command interfaces:Human-machine teaming protocols for controlling 50+ autonomous assets simultaneously are creating new software-only procurement categories.
Industry Challenges
- Cleared workforce scarcity:NATO Secret-level software engineers with embedded systems expertise command 3.5x civilian-market salaries, constraining program staffing.
- Cross-domain solution certification:Connecting air-gapped classified networks to unclassified tactical nets requires 14-22 month NSA or EUCC evaluation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global C4I Systems Market |
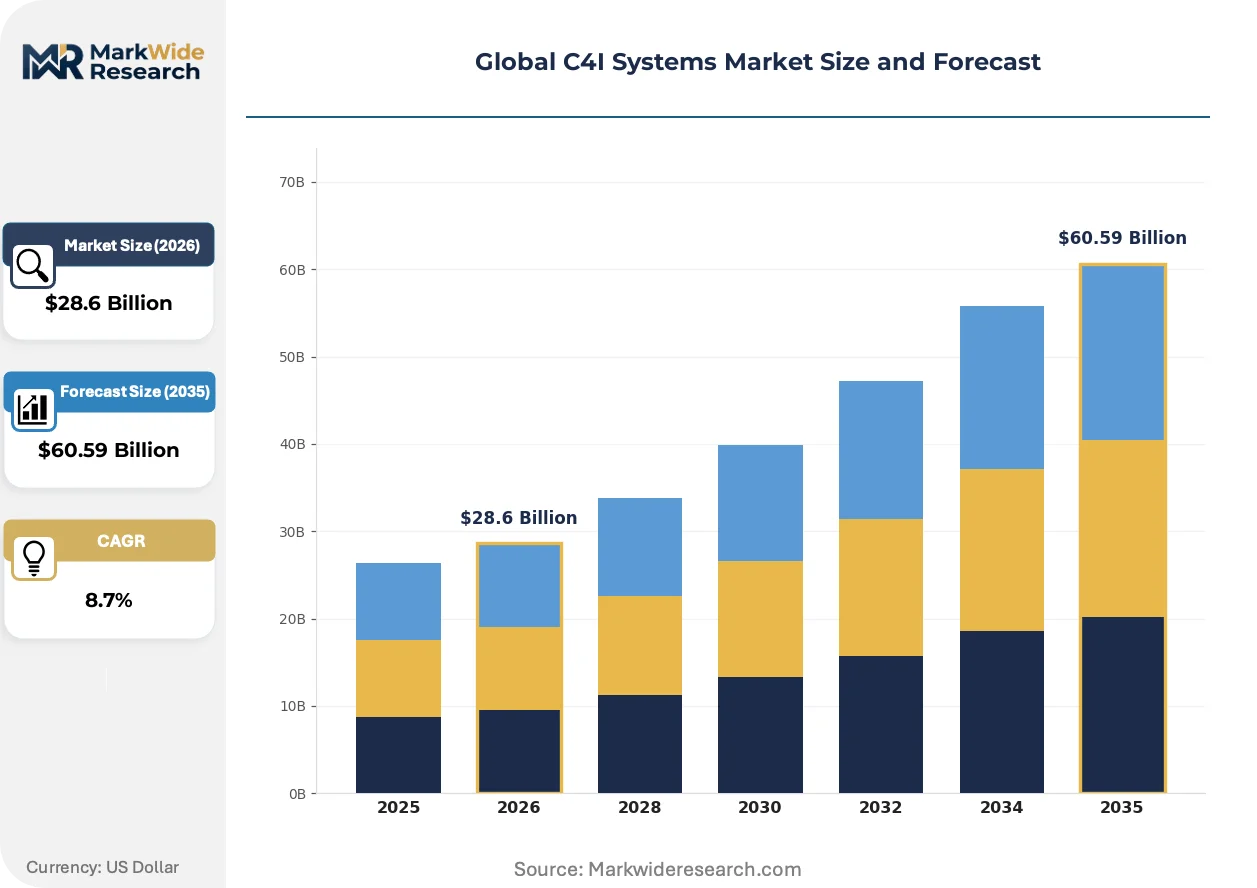
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Command Centers, Communication Equipment, Data Processing Systems, Surveillance Solutions Technology: AI Integration, Cloud Computing, Network Security, IoT Solutions End User: Military, Government, Law Enforcement, Civilian Agencies Application: Border Security, Disaster Management, Intelligence Gathering, Tactical Operations |
| Companies Covered | Leonardo, SAAB, General Dynamics, Northrop Grumman, Lockheed Martin, Elbit Systems, Rheinmetall, BAE Systems, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global C4I Systems Market Emerging Trajectories
Command architecture design is pivoting from centralized hub-and-spoke models to meshed edge networks where decision authority distributes across forward nodes.
Software-defined radio chipsets are miniaturizing. These reconfigurable transceivers enable single hardware units to switch between Link-16, UHF SATCOM, and proprietary waveforms through firmware updates. Special operations units in Australia and Germany are fielding man-portable variants that previously required vehicle mounting. This compression is miniaturizing the physical footprint of tactical command posts from shelter-sized to backpack-portable, enabling dismounted operations in contested electromagnetic environments.
REACH authorization requirements for persistent organic pollutants are restricting halogenated flame retardants in printed circuit board substrates. Defense contractors must reformulate laminate materials or source exemptions for military-critical applications. European prime contractors are most affected, with BAE Systems and Rheinmetall accelerating qualification of phosphorus-based alternatives for naval command consoles.
Budget authorities are unbundling hardware procurement from software sustainment. Australian Defence Force contracts now separate platform acquisition from algorithm update subscriptions, creating recurring revenue pools for predictive analytics modules. This shift is most visible in intelligence-fusion contracts, where three-year software licenses now exceed initial sensor hardware costs by factors of two to four.
Global C4I Systems Market Segmentation
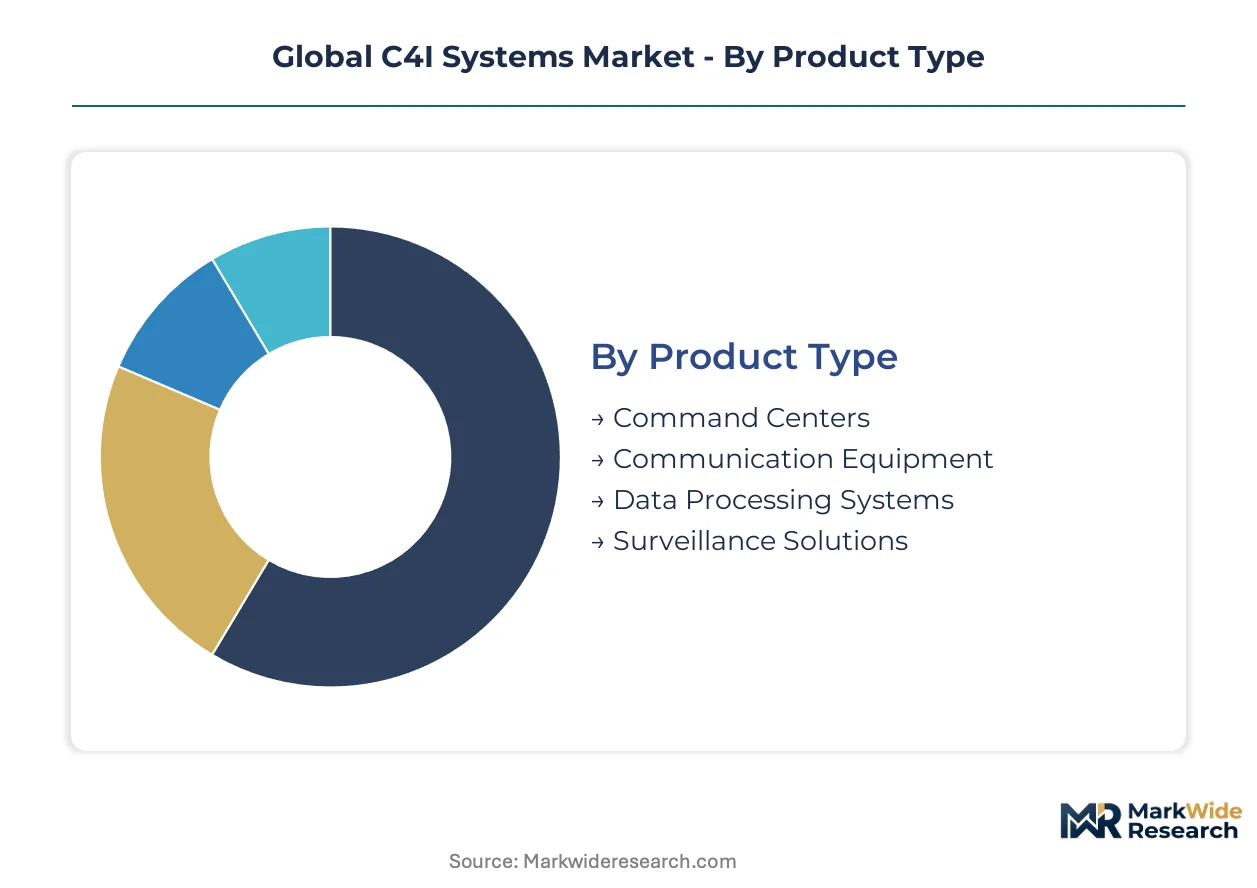
C4I procurement channels diverge sharply by segment maturity. Hardware platforms move through defense prime contractors with multi-year qualification cycles, while software modules increasingly route through direct government contracting vehicles with compressed vendor timelines.
Product Type:
Command centers and communication equipment flow through integrated prime contractors with NATO STANAG certification, whereas surveillance solutions and data processing systems increasingly bypass traditional channels via software-only procurement frameworks.
- Command Centers:Physically integrated facilities housing multi-console operator positions with sub-50 millisecond latency requirements for real-time coordination. Demand clusters in Germany and Australia as both nations modernize joint-force headquarters under trilateral exercise commitments. These platforms require 14-22 month cross-domain solution certifications that constrain vendor pools.
- Communication Equipment:Encrypted waveform systems generating recurring refresh cycles through software-defined radio architectures. The United States and Eastern European militaries drive procurement as legacy VHF bands face spectrum reallocation under FCC and national regulatory frameworks. GaN semiconductor supply concentration in Taiwan-based foundries exposes this segment to single-point fragility.
- Data Processing Systems:Ruggedized edge computing nodes processing multi-source sensor feeds into common operating pictures.
- Surveillance Solutions:Coastal and border monitoring platforms with stable replacement demand across mature defense programs.
By volume, Communication Equipment leads. By growth pace, Data Processing Systems is ahead.
Technology:
Cost tier stratification separates experimental AI modules from commoditized network security stacks, with cloud computing occupying a mid-tier position as sovereign-cloud data residency requirements fragment deployment architectures.
- AI Integration:Predictive analytics engines for threat prioritization requiring algorithmic audit trails under EU AI Act Article 6 mandates. Procurement offices across NATO member states are compressing qualification timelines from 18 months to under 9 months for pre-certified vendors. Machine learning models trained on vibration and thermal signatures are reducing satellite ground station repair intervals.
- Cloud Computing:Distributed command architectures with conflicting encryption key custody rules between Germany's IT-SiG 2.0 and Australia's DISP framework. These sovereign-cloud requirements fragment cross-border program architectures despite standardization efforts.
- Network Security:Cross-domain solutions connecting air-gapped classified networks to unclassified tactical nets.
- IoT Solutions:Sensor mesh networks for forward-deployed command nodes with meshed edge network topologies.
By deployment scale, Network Security leads. By expansion trajectory, AI Integration is climbing the fastest.
End User:
Application intensity varies by mission criticality, with military end-users demanding 99.999% availability thresholds while civilian agencies accept 99.95% tiers at substantially lower unit costs.
- Military:Joint-force command architectures requiring NATO STANAG interoperability and real-time multi-domain sensor fusion. The United States, Germany, and Australia anchor demand through trilateral exercise programs generating common operating picture requirements. Poland's Territorial Defence Forces are fielding mobile command posts with open-architecture standards.
- Government:National-level emergency response coordination with sovereign data residency mandates.
- Law Enforcement:Tactical communications for counter-terrorism and critical infrastructure protection.
- Civilian Agencies:Disaster response coordination with lower availability thresholds and compressed procurement cycles.
By contract value, Military leads. By procurement velocity, Civilian Agencies is gaining share fastest.
Application:
Geographic deployment patterns concentrate border security and tactical operations in Eastern European theaters, while disaster management and intelligence gathering distribute across alliance member territories with varying data residency constraints.
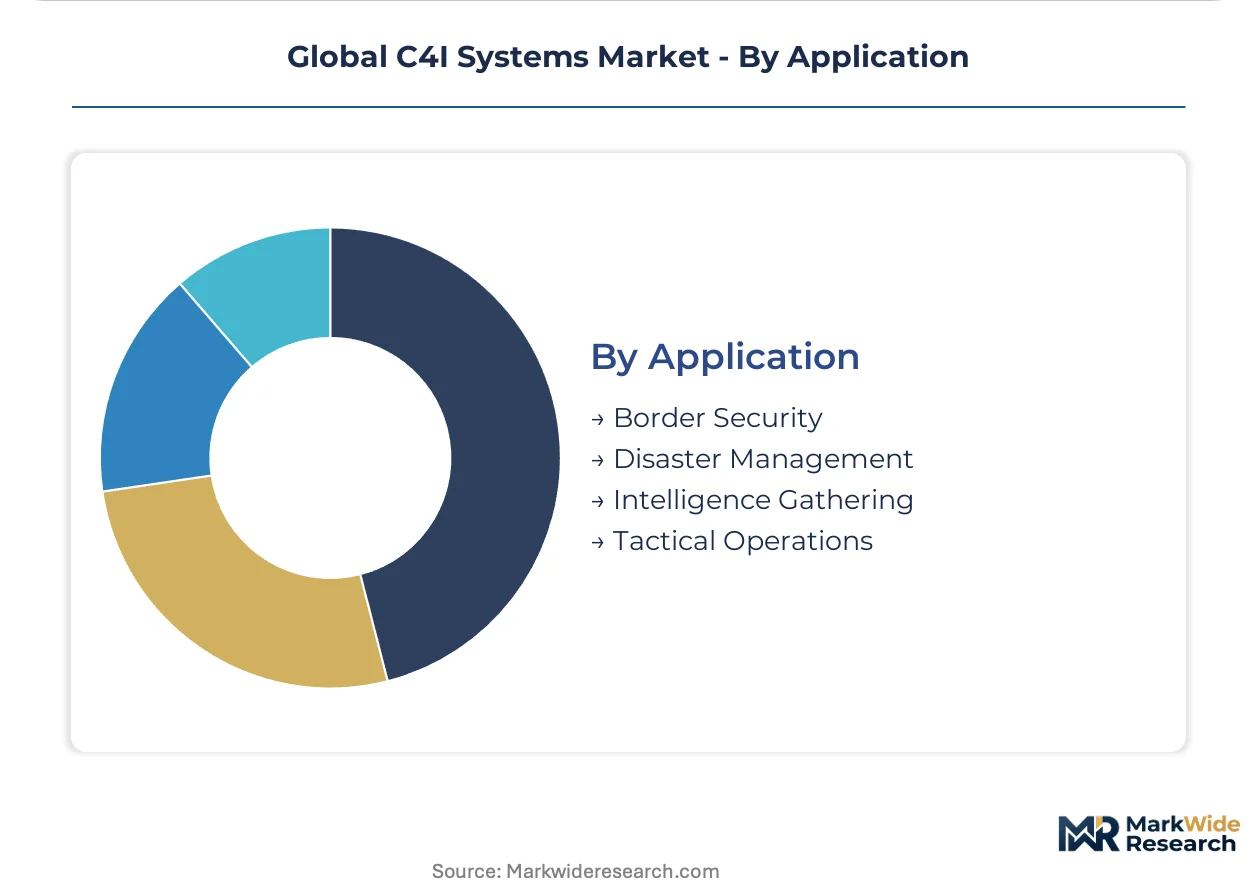
- Border Security:Coastal and land frontier monitoring with stable replacement demand across NATO's eastern flank. Surveillance Solutions product lines serve this application with mature technology refresh cycles.
- Tactical Operations:Forward-deployed command nodes requiring sub-50 millisecond latency for swarm-drone human-machine teaming protocols. Special operations units in Australia and Germany are fielding man-portable software-defined radio variants previously requiring vehicle mounting.
- Disaster Management:Civilian-military coordination for humanitarian assistance and emergency response.
- Intelligence Gathering:Multi-source sensor fusion into common operating pictures with three-year software licenses now exceeding initial hardware costs.
By installed base, Border Security leads. By technology refresh intensity, Tactical Operations is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in the United States, Germany, and Australia concentrate the largest contract awards for integrated command platforms. These three nations anchor trilateral exercise programs that generate demand for common operating picture architectures with sub-50 millisecond latency requirements.
United States
The Pentagon's Joint All-Domain Command and Control (JADC2) initiative drives procurement of meshed edge networks for multi-domain operations. FCC spectrum allocations govern tactical radio frequency bands, while NSA cross-domain solution certifications filter vendor pools. Defense contractors cluster around Washington DC's Beltway corridor and Huntsville, Alabama, where Army Futures Command accelerates software-defined radio fielding.
Germany
Bundeswehr modernization programs prioritize NATO STANAG-compliant platforms for joint-force headquarters integration. IT-SiG 2.0 sovereign-cloud mandates impose encryption key custody rules that reshape cross-border program architectures. Industrial concentration spans Munich's defense electronics cluster and Düsseldorf's systems integration hubs, where Rheinmetall anchors European supply chains.
Australia
The Australian Defence Force unbundles hardware procurement from algorithm update subscriptions under Project Land 17 command post modernization. DISP framework data residency requirements conflict with allied encryption standards. Sydney and Melbourne host prime contractor engineering centers supporting trilateral exercise commitments with US and German forces.
Poland
Territorial Defence Forces field mobile command posts with open-architecture standards that bypass incumbent vendor lock-in on NATO's eastern flank. National procurement directives prioritize EU AI Act Article 6 pre-certified vendors for threat prioritization analytics. Warsaw and Krakow emerging as regional integration hubs for Eastern European interoperability programs.
Israel
Israel Defense Forces deploy predictive maintenance AI and swarm-drone command interfaces that reduce satellite ground station repair intervals. Israeli software modules increasingly route through direct government contracting vehicles with compressed vendor timelines. Tel Aviv's defense technology cluster specializes in tactical edge computing for contested electromagnetic environments.
Global C4I Systems Market Vendor Landscape
Player mix skews toward vertically integrated prime contractors with NATO STANAG certification and sole-source positions on major programs. Market structure concentrates around defense ministries' consolidated vendor lists, compressing qualification timelines for AI-ready platforms. Three archetypes dominate: integrated system houses with command-center production, communications specialists with software-defined radio architectures, and AI module vendors with algorithmic audit trails. Competitive moves center on M&A for GaN semiconductor supply security and strategic partnerships for sovereign-cloud compliance.
Among US-based integrated primes, Lockheed Martin and Northrop Grumman occupy positions sustained by vertically integrated production and cross-domain solution certifications. European system integration anchors through BAE Systems and Rheinmetall, representing the UK-Germany industrial footprint required for EU defense procurement. Elbit Systems exemplifies the specialist archetype competing in tactical communications upgrades across Eastern European militaries with compressed procurement cycles.
| Leading Market Players |
|---|
| Leonardo |
| SAAB |
| General Dynamics |
| Northrop Grumman |
| Lockheed Martin |
| Elbit Systems |
| Rheinmetall |
| BAE Systems |
| Thales |
| Others |
Supply Flow & Price Mechanics
Eighteen-month qualification cycles for NATO STANAG-compliant platforms compress to under nine months for AI-ready vendors, concentrating pricing power with pre-certified system integrators while fragmenting margin pools for component suppliers excluded from consolidated vendor lists.
Pricing Analysis
Cost-plus contracts with labor-hour indexation dominate prime contractor engagements, while software sustainment unbundles into three-year algorithm update subscriptions that exceed initial hardware costs. Price differentiation rests on EU AI Act Article 6 certification tiers and sovereign-cloud compliance levels. Cost compression in tactical radio components intensifies due to GaN semiconductor supply bottlenecks. Civilian agencies exhibit highest price sensitivity; military joint-force programs accept premium pricing for sub-50 millisecond latency guarantees.
Supply Chain Analysis
Taiwan and South Korea anchor defense-grade gallium nitride wafer fabrication, while Germany and the United States concentrate systems integration and cross-domain solution certification. Raw material dependencies span rare earth substrates for magnetics, halogen-free laminates for REACH-compliant circuit boards, and ruggedized GPU modules for edge computing nodes. Single-source vulnerability in Taiwan-based foundries exposes radio frequency component supply. Distribution runs through defense prime contractors with NATO STANAG certification for hardware platforms, while software modules increasingly route through direct government contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
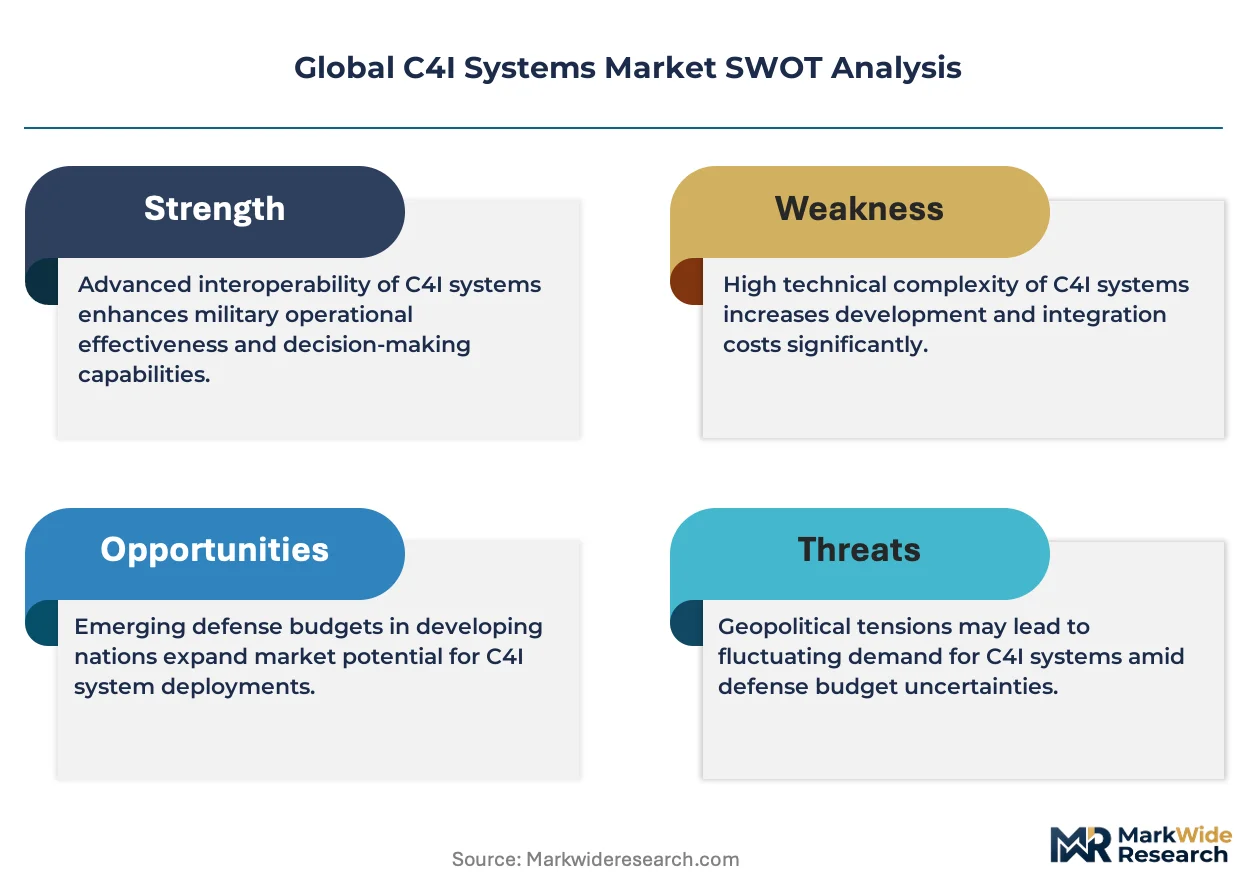
Fragmentation opportunity emerges as defense procurement offices bifurcate vendor lists around AI-readiness certifications, creating niches for algorithmic audit trail specialists alongside incumbent system integrators.
For Market Incumbents: Secure GaN semiconductor supply through strategic foundry partnerships or captive wafer allocation agreements to mitigate Taiwan concentration risk. Invest in sovereign-cloud compliance engineering for Germany's IT-SiG 2.0 and Australia's DISP framework to defend cross-border program eligibility against emerging regional specialists. For New Entrants and Emerging Players: Differentiate on open-architecture mobile command posts for Poland's Territorial Defence Forces, bypassing incumbent vendor lock-in through NATO STANAG-compliant modular designs. Target predictive maintenance AI for satellite ground stations, deploying machine learning models on vibration and thermal signatures with compressed procurement cycles via direct government contracting vehicles. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate defense electronics divisions lacking AI integration capabilities or sovereign-cloud compliance infrastructure. Long-term viability hinges on algorithmic audit trail certification and cross-domain solution clearance pipelines. Watch for EU AI Act enforcement actions as inflection indicators for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Certification Investment | EU AI Act Article 6 pre-certification compresses NATO vendor qualification timelines from 18 to 9 months. |
| GaN Supply Security Partnership | Taiwan foundry allocation agreements mitigate single-point fragility in defense-grade radio frequency components. |
| Sovereign-Cloud Compliance Engineering | Germany's IT-SiG 2.0 and Australia's DISP framework encryption rules determine cross-border program eligibility. |
| Open-Architecture Mobile Command Post Development | Poland's Territorial Defence Forces procurement bypasses incumbent lock-in through modular NATO STANAG standards. |
| Predictive Maintenance AI Licensing | Australian Defence Force software subscriptions now exceed hardware costs by factors of two to four. |
Methodological Framework
The analysis maps command centers, communication equipment, data processing systems, and surveillance solutions, each validated through program managers at defense ministries, procurement officers at NATO agencies, systems engineers at prime contractors, and regulatory affairs leads navigating EU AI Act compliance. Primary interviews triangulate with secondary sources including NATO STANAG documentation, EU defense procurement directives, FCC spectrum allocation records, and customs data on GaN semiconductor trade flows. Bottom-up segment sizing cross-references against top-down defense budget appropriation analysis.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, technology tier, end-user mission criticality, and application intensity dimensions. CAGRs derive from defense budget trajectory analysis, procurement cycle compression observations, and technology refresh rate assumptions for software-defined radio and AI integration segments.
Material uncertainties — geopolitical semiconductor supply disruptions, EU AI Act enforcement variance, sovereign-cloud rule divergence — sit outside the modeled envelope. Forecasts reflect assumptions on NATO interoperability standard adoption and trilateral exercise program continuity. Recalibration cycles align with material shifts in defense procurement directive revisions and foundry capacity allocation policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Military Computers Market
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Railway Cyber Security Market
Defense Cybersecurity
Electronic Warfare Market