
 Blockchain Technology in Aerospace and Defense Market | 2026-2036
Blockchain Technology in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Technology in Aerospace and Defense Market Outlook
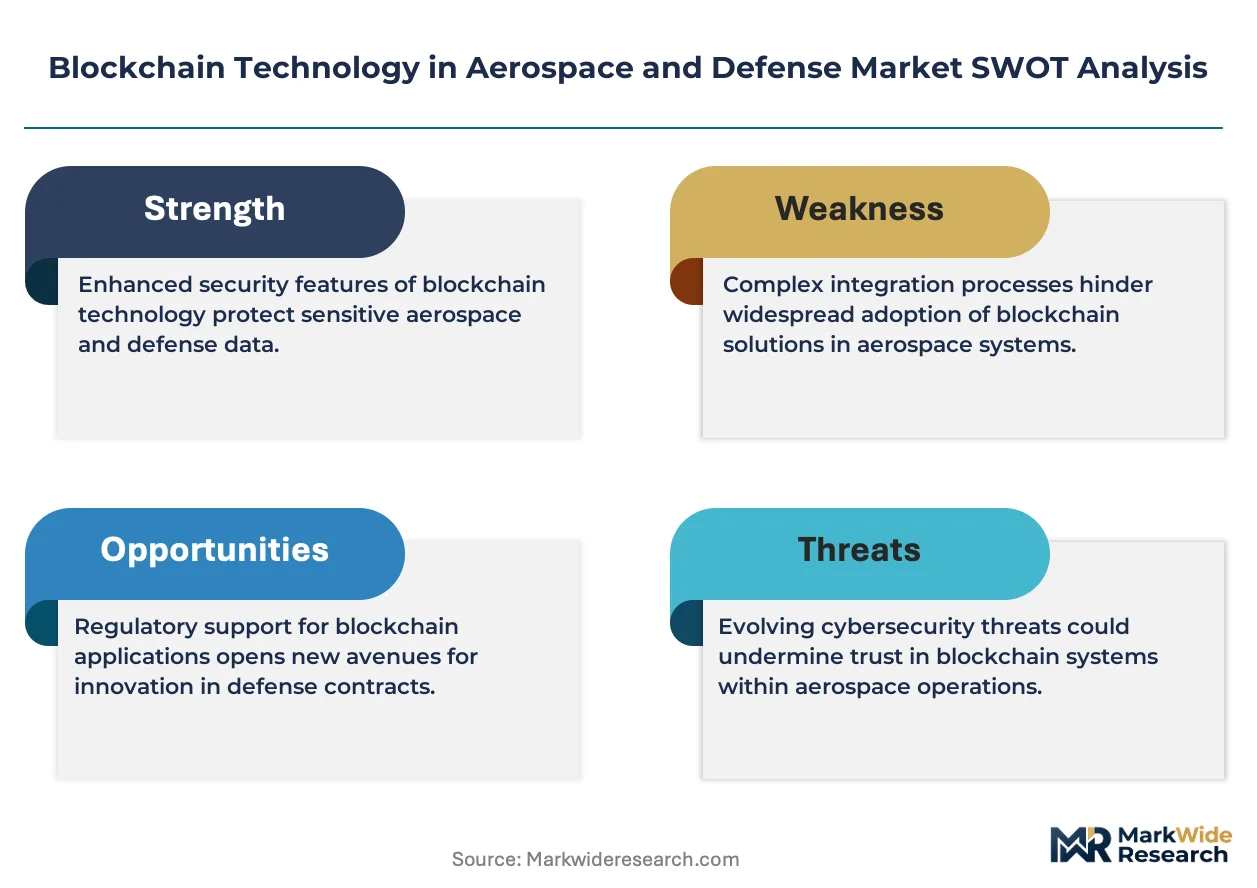
Aftermarket service revenue is rewriting competitive economics for prime contractors. Lockheed Martin leverages its sustainment networks to embed blockchain-verified component histories across F-35 logistics chains. BAE Systems anchors its digital engineering strategy with distributed ledger integration for submarine program documentation. Northrop Grumman differentiates through cryptographic supply chain attestation on classified aerospace platforms.
Blockchain technology in aerospace and defense constitutes a cryptographically secured, distributed ledger architecture employing consensus mechanisms and cryptographic protocols to record transactions across multiple nodes without centralized authority. Its primary industrial purpose centers on creating immutable audit trails for multi-tier supply chains handling ITAR-controlled components and flight-critical materials. Supply chain management applications dominate current deployment value, while smart contracts represent the fastest-expanding segment as primes automate supplier compliance verification. Hybrid blockchain deployments capture growing preference among defense contractors balancing transparency requirements with classified data segregation needs.
The US Department of Defense, through NIST cybersecurity frameworks and DFARS supply chain regulations, mandates enhanced traceability that directly stimulates blockchain procurement across contractor tiers. EASA and EU Cybersecurity Act standards are converging toward distributed ledger requirements for aviation maintenance record integrity across European aerospace manufacturing. Stakeholders must monitor how emerging quantum-resistant cryptographic standards reshape protocol selection and existing deployment roadmaps.
Market Dynamics
Defense procurement agencies now mandate cryptographic supply chain attestation for ITAR-controlled components, forcing prime contractors to re-architect legacy verification systems around distributed ledger infrastructure before contract eligibility expires.
Growth Catalysts
- DFARS Supply Chain Regulations:The US Department of Defense mandates enhanced traceability for critical components, compelling defense contractors to deploy blockchain-verified supplier credentials across multi-tier sourcing networks.
- Smart Contract Automation:Aerospace primes automate supplier compliance verification through self-executing contracts, compressing audit cycles from months to hours for flight-critical material certifications.
- EU Cybersecurity Act Convergence:European aviation maintenance record integrity standards are hardening toward distributed ledger requirements, accelerating compliance investments across EASA-regulated manufacturing clusters.
Market Restraints
- Quantum Vulnerability Exposure:Current elliptic curve cryptographic protocols face obsolescence risk as quantum computing advances, forcing premature protocol migration costs on early deployers.
- Specialized Talent Scarcity:Cryptographic engineering expertise concentrates in finite labor pools, inflating implementation costs for defense contractors competing against fintech and cryptocurrency sectors.
- Interoperability Friction:Proprietary blockchain architectures from competing vendors create data silos that fragment audit trails across joint defense programs and multinational supply chains.
Strategic Opportunities
- NIS2 Directive Compliance Services:European defense contractors face mandatory supply chain risk management obligations, creating advisory and platform revenue streams for blockchain-native verification providers.
- AI-Blockchain Convergence:Machine learning models trained on immutable ledger data enable predictive maintenance analytics for aircraft engine fleets, unlocking outcome-based service contracts.
- Space Supply Chain Expansion:Satellite constellation manufacturing for low-Earth orbit deployments requires component pedigree tracking across dispersed global suppliers, favoring distributed ledger architectures.
Industry Challenges
- ITAR Data Segregation Complexity:Classified aerospace programs require cryptographic isolation of US-controlled technical data from foreign national participants, complicating multi-national blockchain network design.
- Legacy System Integration Burden:ERP and MRO platforms from SAP and Oracle lack native distributed ledger interfaces, necessitating expensive middleware development for maintenance record synchronization.
- Cross-Jurisdictional Evidence Standards:Blockchain records face admissibility disputes across national court systems, creating legal uncertainty for contract enforcement and dispute resolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Technology in Aerospace and Defense Market |
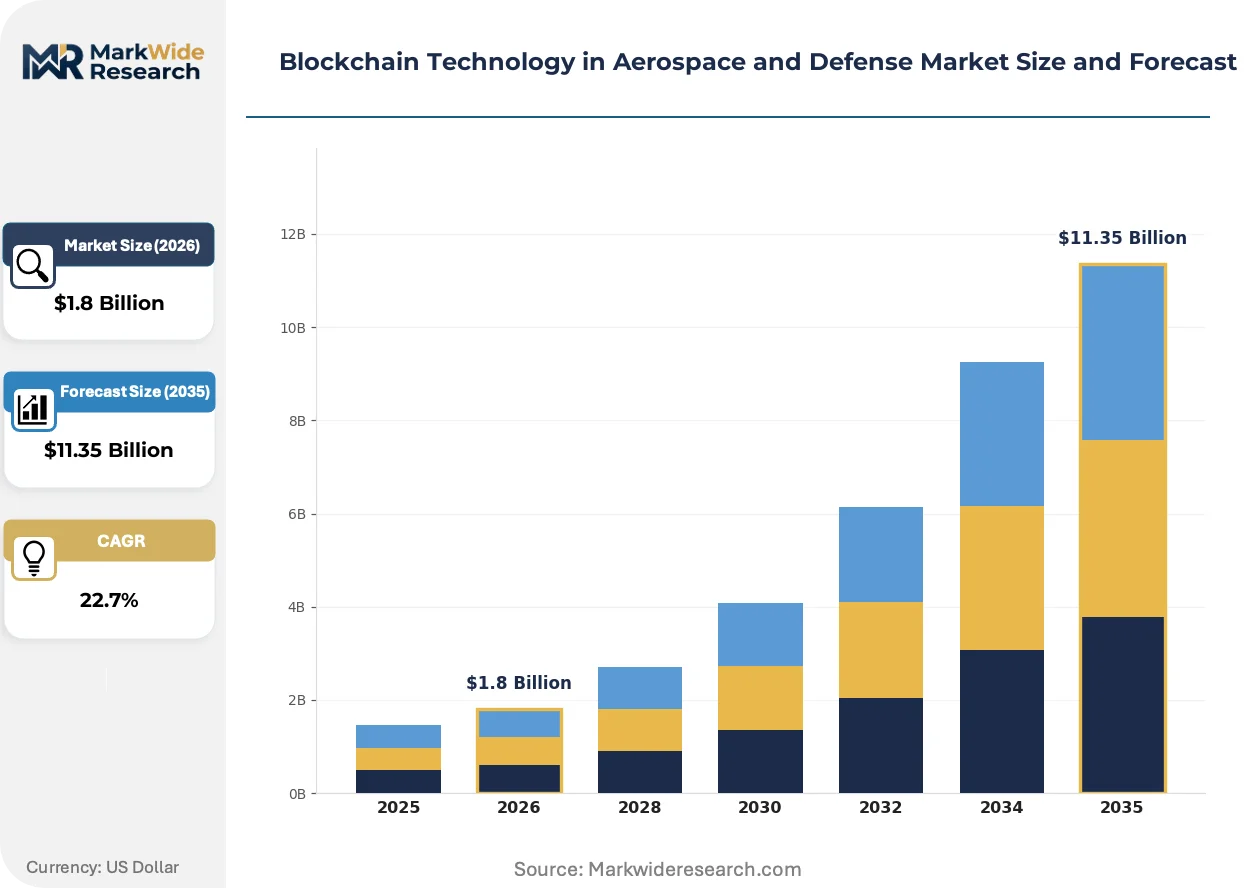
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Management, Data Security, Smart Contracts, Asset Tracking End User: OEMs, Government Agencies, Defense Contractors, Aerospace Companies Deployment: Private Blockchain, Public Blockchain, Hybrid Blockchain, Consortium Blockchain Technology: Cryptographic Protocols, Decentralized Ledger, Consensus Mechanisms, Tokenization |
| Companies Covered | Lockheed Martin, Northrop Grumman, Raytheon Technologies, Boeing, Thales Group, Airbus, General Dynamics, BAE Systems, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Technology in Aerospace and Defense Market Strategic Shifts
Consensus mechanism innovation and cryptographic protocol evolution are compressing the gap between classified security requirements and commercial blockchain scalability, enabling defense-grade deployments without sacrificing transaction throughput.
Hybrid blockchain architecture is hybridizing permissioned and permissionless network layers to satisfy contradictory demands: immutable public audit trails for supplier verification alongside encrypted private channels for classified technical specifications. Aerospace primes including F-35 logistics operators deploy these bifurcated systems to maintain ITAR compliance while achieving multi-party consensus. This architectural pattern is hybridizing competitive positioning by allowing primes to bid on contracts previously restricted to cleared defense integrators with proprietary secure networks.
The EU Cybersecurity Act and NIS2 Directive impose mandatory supply chain risk management obligations on critical infrastructure operators, including defense contractors handling aviation and space systems. These frameworks require documented supplier security postures and incident response capabilities that distributed ledgers automate through cryptographic attestation. European aerospace manufacturing clusters in France, Germany, and Italy are responding by embedding blockchain verification into supplier onboarding workflows ahead of 2024-2025 enforcement deadlines.
Defense procurement officers now demand cryptographic proof of component provenance as a contractual precondition, displacing paper-based certificates of conformance and third-party inspection reports. This verification preference concentrates in US Department of Defense programs for next-generation bomber and unmanned aerial systems, where supply chain integrity directly impacts mission assurance. The behavioral shift is most visible in classified platform development, where primes compete on the depth of their blockchain-integrated supplier networks rather than unit cost alone.
Blockchain Technology in Aerospace and Defense Market Segmentation
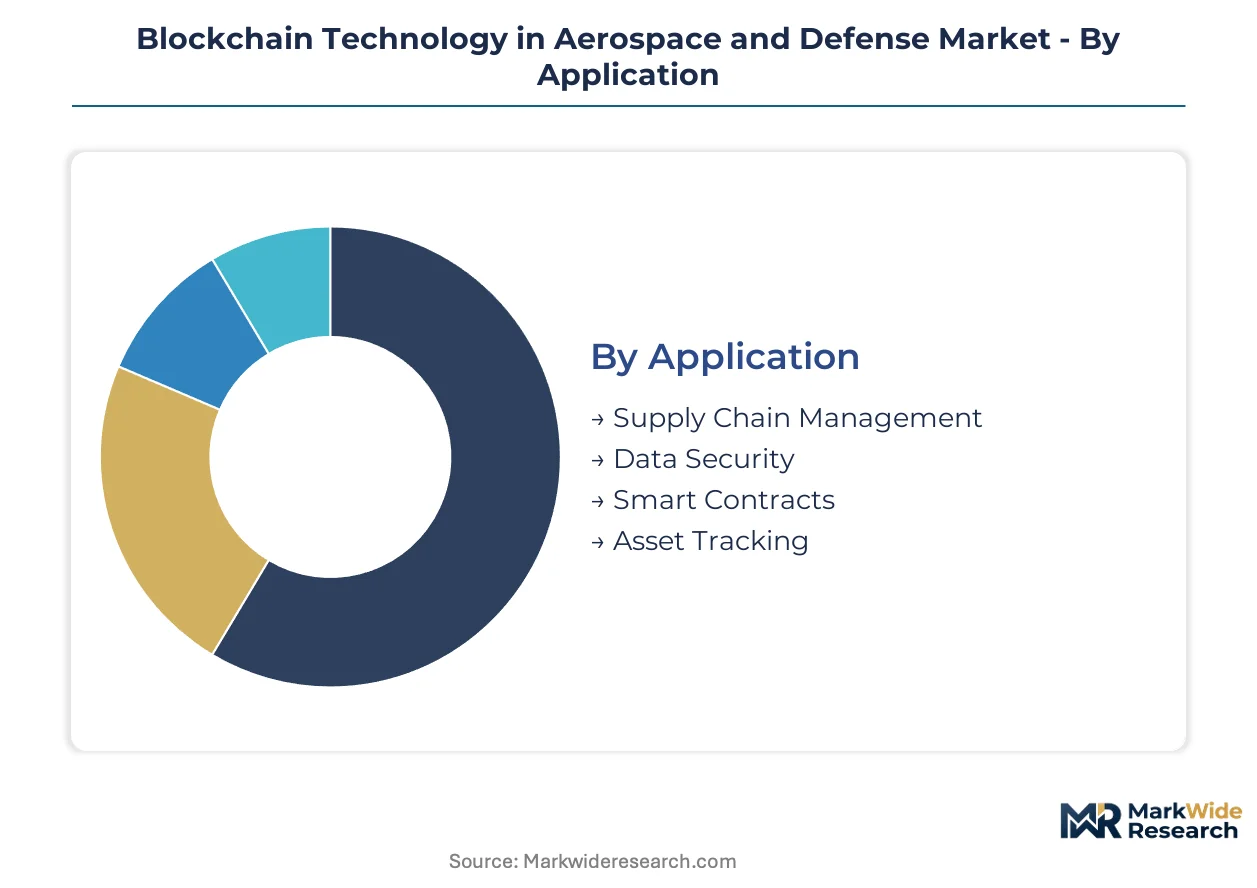
Segmentation in aerospace and defense blockchain markets reveals how procurement complexity and regulatory fragmentation create distinct technology requirements across contractor tiers. Each dimension captures different purchasing behaviors: application segments reflect mission-critical use cases, while deployment modes balance transparency mandates against classified data protection.
Application:
After-sales service intensity varies dramatically across application segments, with maintenance-heavy use cases demanding permanent, queryable records that outlast original equipment warranties.
- Supply Chain Management:Multi-tier supplier verification systems create immutable audit trails for ITAR-controlled components moving through dispersed manufacturing networks. Defense procurement agencies in the United States and European aerospace clusters in France and Germany mandate cryptographic provenance documentation for flight-critical materials, compressing supplier onboarding cycles.
- Smart Contracts:Self-executing compliance protocols automate certification verification between primes and subtier vendors, eliminating manual audit bottlenecks. These contracts gain traction in F-35 logistics chains and submarine program documentation where BAE Systems and Lockheed Martin compress multi-month compliance reviews into hours.
- Data Security:Encrypted distributed storage protects classified technical specifications across cleared defense networks with cryptographic access controls.
- Asset Tracking:Real-time component pedigree monitoring traces high-value aerospace assets through maintenance, repair, and overhaul cycles.
Supply chain management holds the largest share; momentum sits with smart contracts.
End User:
Customer sophistication determines platform requirements, with cleared defense integrators demanding quantum-resistant cryptography while commercial aerospace operators prioritize transaction throughput.
- Defense Contractors:Prime contractors integrate distributed ledgers to satisfy DFARS supply chain regulations and cryptographic attestation mandates for ITAR-controlled programs. These entities anchor procurement volume through classified platform development where multi-tier supplier verification determines contract eligibility.
- Government Agencies:Defense procurement offices in the United States and European defense ministries now embed blockchain requirements directly into RFP specifications. The US Department of Defense and EU defense procurement frameworks treat cryptographic provenance as a contractual precondition for next-generation bomber and unmanned aerial systems.
- OEMs:Original equipment manufacturers deploy ledger infrastructure to synchronize maintenance records across global service networks.
- Aerospace Companies:Commercial aviation operators adopt asset tracking for engine fleet management and predictive maintenance analytics.
Defense contractors dominate current deployment value; government agencies are expanding most quickly as procurement mandates harden.
Deployment:
Architecture selection reflects a tension between audit transparency and information security, with hybrid configurations emerging as the dominant compromise pattern.
- Hybrid Blockchain:Bifurcated permissioned-permissionless architectures satisfy contradictory demands: public audit trails for supplier verification alongside encrypted channels for classified specifications. F-35 logistics operators and European submarine programs deploy these systems to maintain ITAR compliance while achieving multi-party consensus.
- Private Blockchain:Fully permissioned networks isolate sensitive technical data within cleared contractor environments, restricting node participation to US persons and approved foreign nationals.
- Consortium Blockchain:Multi-organization governance structures coordinate joint defense programs across allied nations with shared cryptographic standards.
- Public Blockchain:Open participation models see limited defense adoption due to classification requirements, though some non-sensitive supplier credentialing experiments proceed.
Hybrid blockchain holds the largest share; consortium blockchain is gaining share fastest as multinational defense programs proliferate.
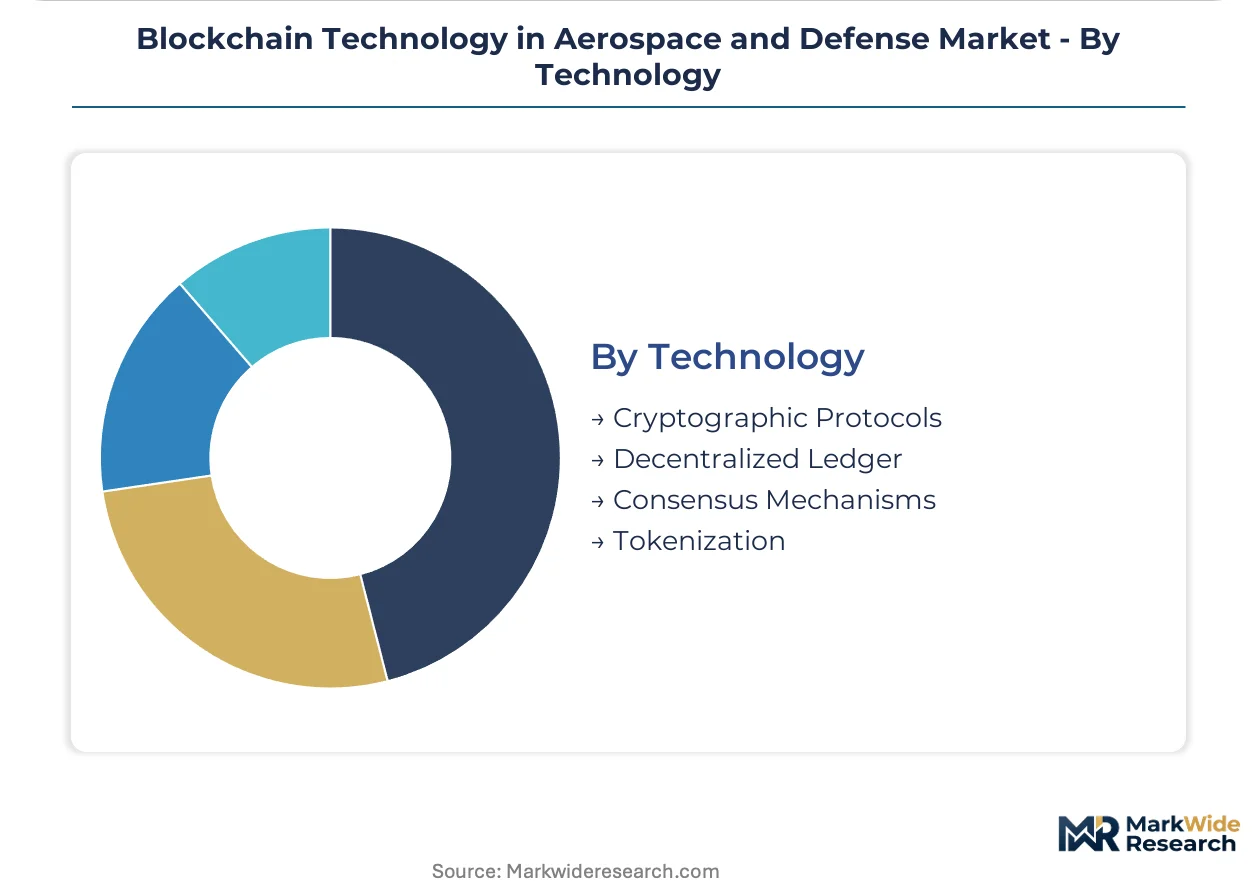
Technology:
Core protocol choices determine long-term security posture, with quantum-resistant algorithm migration becoming a procurement evaluation criterion.
- Cryptographic Protocols:Elliptic curve and hash-based signature schemes currently secure aerospace transactions, though NIST post-quantum standardization drives evaluation of lattice-based alternatives. Defense primes face premature migration costs as quantum computing advances threaten existing deployments.
- Consensus Mechanisms:Byzantine fault-tolerant algorithms achieve agreement across geographically dispersed defense nodes without centralized trust anchors. These protocols enable submarine program documentation and satellite constellation manufacturing where network partitions are routine.
- Decentralized Ledger:Distributed storage architectures eliminate single points of failure for maintenance records that must persist across decades-long platform lifecycles.
- Tokenization:Digital asset representation enables fractional ownership structures and automated settlement for aerospace equipment financing.
Cryptographic protocols anchor current infrastructure; consensus mechanisms show the steepest expansion trajectory as throughput requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies in the United States demonstrate the lowest price elasticity, accepting substantial premiums for cryptographic supply chain verification, while commercial aerospace operators in emerging markets remain highly cost-sensitive to ledger infrastructure investments.
United States
The Department of Defense mandates DFARS-compliant traceability for ITAR-controlled components across F-35 and next-generation bomber programs. NIST cybersecurity frameworks establish cryptographic standards that contractors must satisfy for contract eligibility. The aerospace manufacturing corridor spanning Texas, California, and Virginia anchors deployment volume for hybrid blockchain systems.
France
Dassault Aviation and Safran drive demand for maintenance record integrity across Rafale fighter and Falcon business jet fleets. The EU Cybersecurity Act and NIS2 Directive impose mandatory supplier risk management obligations with enforcement deadlines approaching. The Île-de-France and Occitanie regions concentrate blockchain integration into EASA-regulated manufacturing workflows.
Germany
Airbus Defence and Space and MTU Aero Engines require cryptographic provenance for turbine components and satellite subsystems. The national implementation of NIS2 through the NIS2UmsuCG mandates documented security postures across defense supply chains. Bavaria's aerospace cluster around Munich leads European adoption of consortium blockchain architectures for multinational programs.
United Kingdom
BAE Systems embeds distributed ledgers into submarine program documentation and Typhoon sustainment networks. The UK National Cyber Security Centre publishes guidance aligning with NATO supply chain security standards. The Northwest England and Southwest clusters concentrate smart contract development for defense procurement automation.
Israel
Elbit Systems and Israel Aerospace Industries deploy cryptographic attestation for unmanned aerial systems and missile defense components. The Israel National Cyber Directorate regulates critical infrastructure protection with emphasis on supply chain integrity. The Tel Aviv metropolitan area anchors startup activity in quantum-resistant cryptographic protocols for defense applications.
Blockchain Technology in Aerospace and Defense Market Competitive Environment
Defense prime contractors and technology integrators split the market between mission-critical platform integration and underlying infrastructure provision. The vendor base concentrates around cleared defense integrators with existing security clearances and established supplier networks. Two strategic archetypes dominate: aerospace primes embedding ledger infrastructure into sustainment operations, and enterprise technology vendors supplying cryptographic protocols. Competitive intensity centers on consortium formation for multinational programs and quantum-resistant algorithm migration roadmaps.
Within the prime contractor tier, Lockheed Martin and Northrop Grumman occupy positions exemplifying blockchain-integrated logistics and cryptographic supply chain attestation for classified platforms. BAE Systems represents the European archetype of digital engineering strategy anchored in distributed ledger documentation. These three entities sit within a competitive structure where contract eligibility increasingly depends on verified supplier network depth rather than unit cost positioning.
| Leading Market Players |
|---|
| Lockheed Martin |
| Northrop Grumman |
| Raytheon Technologies |
| Boeing |
| Thales Group |
| Airbus |
| General Dynamics |
| BAE Systems |
| IBM |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in cryptographic engineering talent across the United States and European defense corridors inflates implementation premiums while compressing supplier margins, forcing primes to bundle ledger infrastructure into long-term sustainment contracts rather than standalone software sales.
Pricing Analysis
After-sales service revenue through multi-year sustainment contracts drives lifetime value capture for prime contractors. Pricing stratifies across three tiers: premium deployments for classified platforms with quantum-resistant protocols, standard configurations for ITAR-compliant supply chains, and economy offerings for non-sensitive component tracking. Cost compression in the economy tier is intensifying as commercial blockchain vendors enter adjacent markets. Government agencies demonstrate the lowest price sensitivity, accepting substantial premiums for cryptographic attestation, while commercial aerospace operators in emerging markets resist ledger infrastructure investments without regulatory mandates.
Supply Chain Analysis
Upstream cryptographic hardware and specialized semiconductor components feed from concentrated manufacturing bases in the United States, Taiwan, and Israel. The supply chain draws from quantum-resistant chip foundries, secure enclave manufacturers, and consensus algorithm specialists. Single-source vulnerability runs through NIST-certified cryptographic module providers, where qualification timelines create bottlenecks. Distribution runs through cleared defense integrators with existing security clearances, limiting channel access for unqualified vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards contractors who control scarce cryptographic engineering capacity and maintain cleared supplier networks deep enough to satisfy DFARS and NIS2 mandates without external dependencies.
For Market Incumbents: Build switching-cost moats through embedded ledger infrastructure in multi-decade platform sustainment cycles. Deepen backward integration into quantum-resistant cryptographic protocol development to preempt NIST migration deadlines. Consolidate around consortium blockchain governance for multinational programs before competitors establish alternative standards. For New Entrants and Emerging Players: Build out advisory and compliance automation services targeting European defense contractors facing NIS2 enforcement deadlines. White-space concentration sits with mid-tier suppliers lacking in-house cryptographic expertise. Pursue partnership-led go-to-market strategies with established primes seeking to outsource supplier verification workflows. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among blockchain-native verification providers with multi-year government contracts. Long-term viability hinges on quantum-resistant algorithm roadmaps and clearance-maintained personnel pools. Acquisition targets should demonstrate existing integration into F-35 or submarine program supply chains. Monitor NIST post-quantum standardization announcements as inflection signals for protocol migration spending waves.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Protocol Migration | NIST standardization deadlines force premature cryptographic upgrades across DFARS-compliant contractor networks. |
| Consortium Blockchain Formation | Multi-organization governance structures coordinate joint defense programs across allied nations with shared attestation standards. |
| Smart Contract Platform Integration | Self-executing compliance protocols compress supplier audit cycles from months to hours for flight-critical certifications. |
| Backward Integration into Cryptographic Hardware | In-house secure enclave production reduces dependency on NIST-certified module suppliers with extended qualification timelines. |
| AI-Blockchain Convergence Investment | Machine learning models trained on immutable ledger data enable predictive maintenance analytics for aircraft engine fleets. |
Study Parameters
The analysis maps supply chain management applications, smart contract deployments, data security implementations, and asset tracking solutions, each validated through primary interviews with defense procurement officers, cryptographic engineering leads, prime contractor supply chain executives, and EASA regulatory affairs specialists. Secondary sources include DFARS regulatory filings, NIST cybersecurity framework documentation, EU Cybersecurity Act implementation guidance, and defense contractor SEC disclosures. Bottom-up segment sizing triangulates against top-down procurement budget allocations.
Assumptions hold regulatory enforcement timelines and quantum computing advancement curves within observed trajectories across the analysis window. The forecast framework models deployment mode preferences, application segment growth rates, end-user adoption patterns, and technology protocol evolution. CAGRs derive from segment-level procurement volume projections and technology substitution curves. Industry-specific inputs include DFARS compliance deadline schedules and NIST post-quantum cryptographic standardization milestones.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by hyperscale cloud providers into cleared defense environments would shift outcomes for hybrid blockchain adoption. Cross-checking against Department of Defense budget justification documents and EASA regulatory impact assessments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Military Computers Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Asia-Pacific Missiles and Missile Defense Systems Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Ballistics Targeting Software Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Defensive Cyber Weapons Market