
 Anti-Drone Defense System Market | 2026-2036
Anti-Drone Defense System Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Drone Defense System Market Insights
Modular sensor-fusion packages are pivoting procurement patterns as defense buyers swap monolithic platforms for interoperable, upgradeable subsystems. RTX leverages its radar pedigree to anchor layered detection architectures. Lockheed Martin Corporation sustains competitive pressure through directed-energy integration. Rafael Advanced Defense Systems differentiates with battle-proven kinetic interceptors deployed across Middle Eastern theaters.
Anti-drone defense systems combine radar, electro-optical, infrared, and acoustic detection modalities with jamming, directed energy, or kinetic neutralization mechanisms to identify, track, and defeat unauthorized unmanned aerial vehicles. These systems typically operate across Ku-band through X-band radar frequencies, with electro-optical sensors achieving positive identification at ranges exceeding two kilometers under varied meteorological conditions. Jamming systems currently occupy the largest product-type position due to lower per-unit cost and reversible effects, while directed energy weapons represent the fastest-expanding technology segment as solid-state laser efficiency improves. Military bases command the dominant application share, though airport deployments are accelerating fastest following multiple runway incursion incidents.
The US FAA and DoD jointly shape domestic certification pathways for airport-integrated counter-drone equipment, while the EU Drone Strategy 2.0 mandates standardized detection protocols across member-state critical infrastructure. Israel's Ministry of Defense maintains classified performance benchmarks that effectively filter foreign subsystem vendors. Stakeholders must monitor evolving rules-of-engagement frameworks that determine whether law enforcement or military operators retain neutralization authority in civilian airspace corridors.
Market Dynamics
Defense procurement offices are abandoning single-vendor platform contracts in favor of open-architecture sensor-fusion stacks that let operators mix radar, electro-optical, and electronic-warfare subsystems from competing suppliers. This modularity mandate is compressing vendor margins while accelerating technology refresh cycles.
Growth Catalysts
- EU Drone Strategy 2.0:The framework mandates standardized detection protocols across member-state critical infrastructure, forcing airports and power utilities to deploy certified counter-drone layers.
- Kinetic interceptor refinement:Battle-proven hard-kill systems from Middle Eastern theaters are gaining acceptance among NATO procurement agencies seeking reversible neutralization alternatives.
- Israeli Ministry of Defense benchmarks:Classified performance thresholds filter foreign subsystem vendors, creating captive demand for domestically integrated detection-neutralization packages.
Market Restraints
- Gallium nitride supply concentration:Solid-state radar and directed-energy subsystems depend on GaN foundry capacity concentrated in East Asian semiconductor fabrication facilities.
- FAA certification friction:The US FAA Reauthorization Act creates multi-year approval timelines for airport-integrated counter-drone equipment, delaying revenue recognition for subsystem vendors.
- Jamming system commoditization:Low-cost radio-frequency defeat mechanisms from commercial security suppliers threaten pricing power for defense-grade electronic attack modules.
Strategic Opportunities
- India's critical infrastructure protection:The country's central electricity regulator and airport authority are drafting counter-drone mandates for grid substations and civilian airfields.
- Directed-energy convergence:Solid-state laser efficiency gains above 30% are enabling fiber-combined weapon systems that integrate with existing radar cueing networks.
- Commercial airport channel expansion:System integrators are bypassing prime defense contractors to sell detection-only packages directly to airport operators facing runway incursion liability.
Industry Challenges
- Multi-sensor fusion engineering scarcity:Vendors struggle to hire software architects capable of correlating radar tracks with electro-optical signatures in real-time target classification pipelines.
- Rules-of-engagement ambiguity:Law enforcement and military operators dispute neutralization authority in civilian airspace corridors, delaying deployment decisions.
- Legacy air defense integration:New counter-drone layers must interface with decades-old command-and-control architectures without disrupting existing identification-friend-or-foe protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Drone Defense System Market |
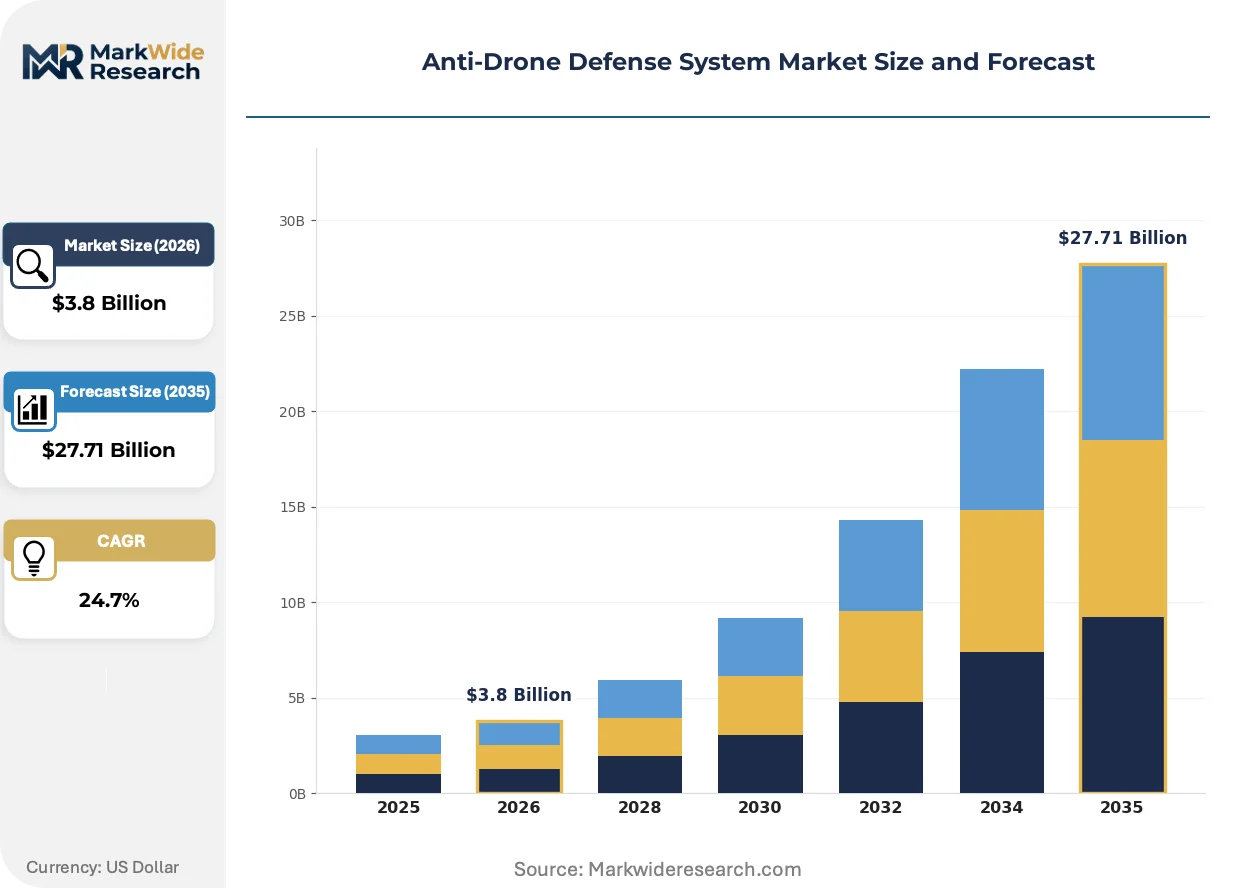
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.71 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jamming Systems, Directed Energy Weapons, Kinetic Interceptors, Radio Frequency Detectors, Optical Sensors Technology: Radar, Laser, Electro-Optical, Infrared, Acoustic, Microwave Application: Critical Infrastructure, Military Bases, Airports, Event Security, Border Surveillance, Maritime Security End User: Defense Agencies, Security Firms, Law Enforcement, Private Corporations, Government Facilities |
| Companies Covered | RTX, Lockheed Martin Corporation, Rafael Advanced Defense Systems, Israel Aerospace Industries, Thales, Leonardo S.p.A., Saab, DroneShield Ltd, Dedrone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Drone Defense System Market Trends and Innovations
Sensor miniaturization and software-defined radio architectures are collapsing the cost curve for detection subsystems, enabling layered deployments that were economically unfeasible five years ago. This democratization is fragmenting vendor hierarchies.
Solid-state directed-energy weapons are overtaking chemical laser predecessors in military procurement evaluations. Fiber-combined laser architectures achieve 50-kilowatt outputs from distributed gain modules. Naval and ground-based air defense programs in the United States and United Kingdom are prioritizing these systems for swarm defeat. The technology is compressing per-shot neutralization costs from thousands of dollars to single-digit electricity consumption.
The FAA Reauthorization Act and DoD joint certification pathway for airport-integrated counter-drone equipment is accelerating dual-use technology transfer. Civilian aviation authorities now reference military environmental testing standards for electromagnetic interference and safety-of-flight qualification. This regulatory convergence benefits subsystem vendors with existing defense contracts seeking commercial revenue diversification.
Buyer concentration among NATO military procurement agencies is fragmenting as national ministries of defense issue separate tenders for interoperable subsystems rather than integrated platforms. Denmark, Norway, and Poland now run independent competitions for radar and electronic attack modules. This pattern compresses contract values while expanding the addressable vendor base for specialized component suppliers.
Anti-Drone Defense System Market Segmentation
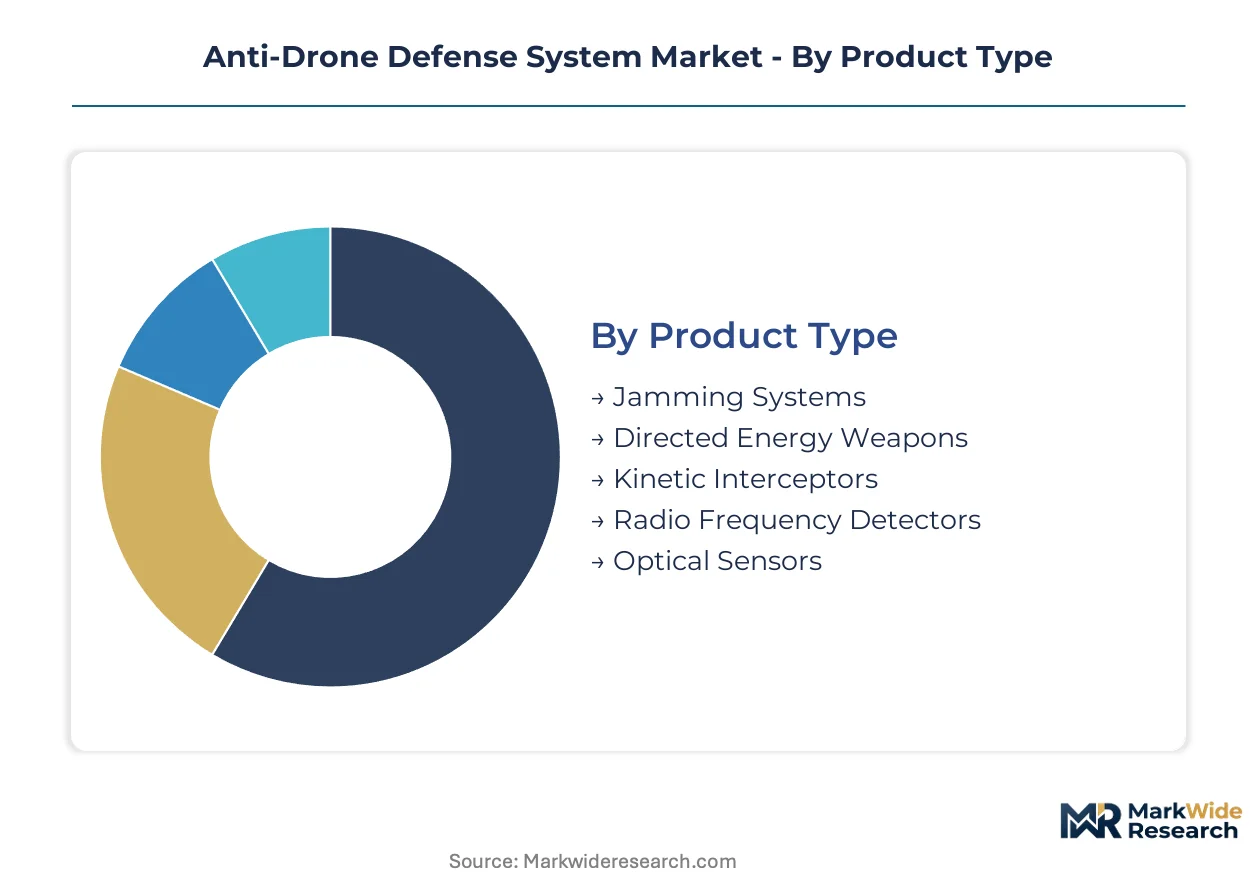
Procurement offices across defense and civilian sectors are segmenting counter-drone investments by neutralization mechanism, sensor modality, and operational environment. Upgrade cycles vary dramatically: jamming hardware refreshes every 3-4 years while directed-energy platforms demand decade-long development timelines.
Product Type:
Replacement cycles diverge sharply between reversible soft-kill mechanisms and permanent hard-kill solutions, with budget constraints favoring modular upgrade paths over platform replacement.
- Jamming Systems:Radio-frequency defeat mechanisms dominate procurement volumes due to sub-$50,000 unit costs and reversible effects that avoid collateral damage liability. Military bases in the United States and airport authorities in the United Kingdom are standardizing on software-defined architectures that permit waveform updates without hardware swap-outs.
- Directed Energy Weapons:Solid-state laser platforms achieving 30%+ wall-plug efficiency are displacing chemical laser predecessors in naval and ground-based programs. The United States Navy and United Kingdom Ministry of Defence are prioritizing fiber-combined architectures for swarm defeat scenarios.
- Kinetic Interceptors:Hard-kill projectiles and net-capture systems from Israeli and Turkish suppliers are gaining NATO evaluation contracts.
- Radio Frequency Detectors:Passive spectrum analyzers provide low-cost detection for commercial airport perimeter security.
- Optical Sensors:Electro-optical and infrared packages achieve positive identification beyond two kilometers under varied meteorological conditions.
Volume placements concentrate in Jamming Systems; the faster expansion belongs to Directed Energy Weapons.
Technology:
Cost tiers separate mature analog subsystems from software-defined architectures that collapse detection economics through commercial component reuse.
- Radar:Active electronically scanned arrays operating across Ku-band through X-band frequencies anchor layered detection architectures. RTX and Saab are supplying GaN-based radar front-ends to Denmark, Norway, and Poland under separate national tenders.
- Laser:Fiber-combined solid-state sources achieving 50-kilowatt outputs are compressing per-shot neutralization costs to single-digit electricity consumption. United States Army and United Kingdom Royal Navy programs are driving procurement evaluations.
- Electro-Optical:Visible-spectrum cameras with automated target recognition algorithms enable positive identification before neutralization authorization.
- Infrared:Thermal imagers detect battery-powered drones through motor heat signatures during night operations.
- Acoustic:Microphone arrays triangulate rotor noise for short-range detection in urban canyons where radar clutter is prohibitive.
- Microwave:High-power microwave burst systems disable electronics through electromagnetic pulse effects without kinetic impact.
Defense procurement is climbing the fastest for Laser technology; commercial airport deployments favor Electro-Optical for its lower electromagnetic interference profile.
Application:
Customer type determines specification stringency: military operators demand all-weather performance while civilian buyers prioritize electromagnetic compatibility with existing aviation systems.
- Critical Infrastructure:Power utilities and telecommunications facilities are deploying perimeter detection layers following EU Drone Strategy 2.0 mandates. India's central electricity regulator is drafting counter-drone requirements for grid substations.
- Military Bases:Layered air defense architectures combining radar cueing with multiple neutralization modalities command the dominant procurement share. United States European Command installations are prioritizing interoperability with NATO identification-friend-or-foe protocols.
- Airports:Runway incursion incidents are accelerating detection-only deployments ahead of full neutralization certification. The FAA Reauthorization Act creates multi-year approval timelines that delay integrated system revenue recognition.
- Event Security:Temporary deployments for sporting venues and political summits favor portable jamming and drone-capture nets.
- Border Surveillance:Fixed-site radar networks along desert and maritime frontiers demand extended-range detection against low-observable targets.
- Maritime Security:Naval vessels and port facilities are evaluating directed-energy weapons for countering explosive-laden boat swarms.
Procurement volumes cluster in Military Bases; steepest expansion trajectory is occurring in Airports as civilian certification pathways mature.
End User:
Geography shapes procurement authority: national defense ministries retain neutralization control while interior ministries and private operators are limited to detection-only capabilities.
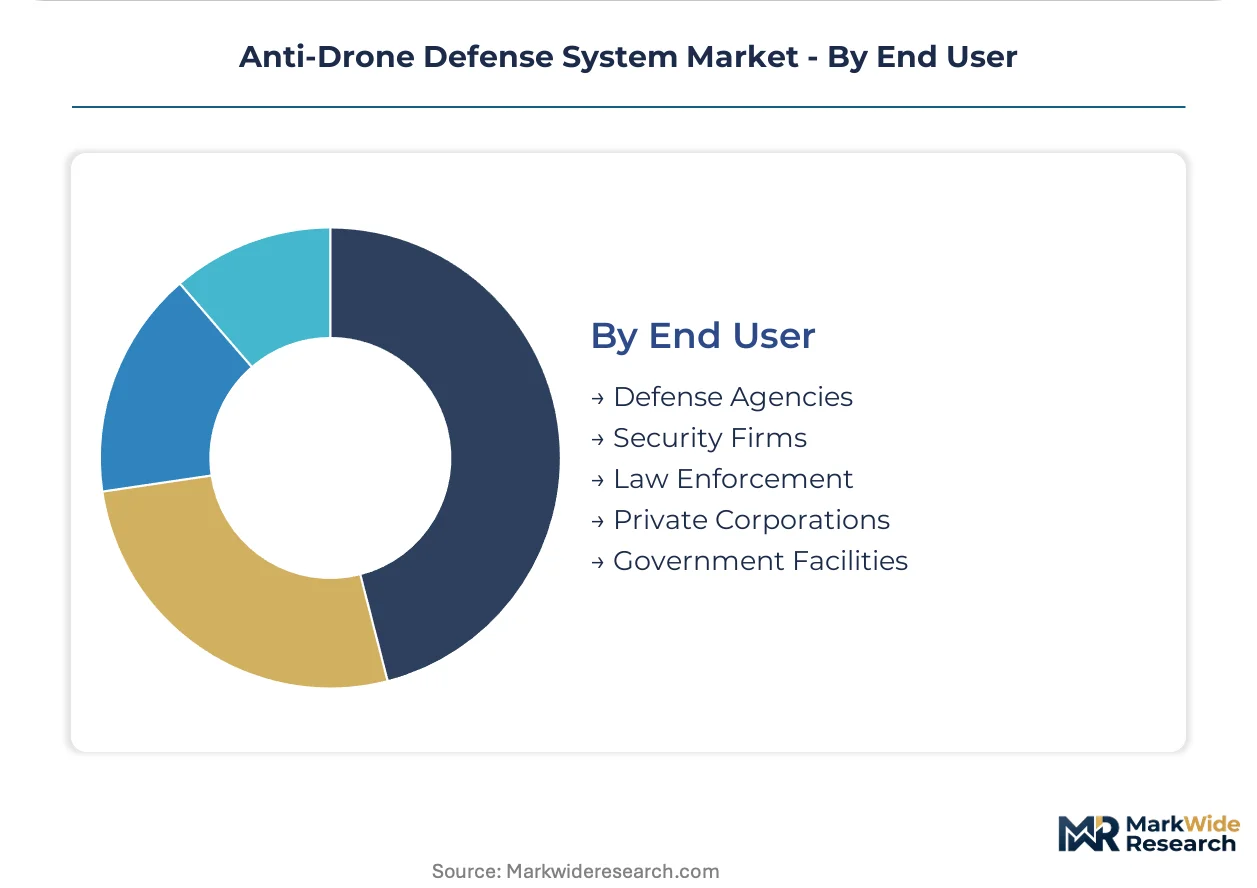
- Defense Agencies:Military procurement offices are abandoning single-vendor platforms for open-architecture sensor-fusion stacks. United States, Israeli, and British defense ministries are running independent competitions for interoperable subsystems.
- Security Firms:Private contractors protecting corporate campuses and entertainment venues are acquiring portable jamming and kinetic capture systems. Israeli and Emirati security providers are exporting operational expertise to African and Asian markets.
- Law Enforcement:Police agencies dispute neutralization authority with military operators in civilian airspace corridors, delaying deployment decisions in the United States and European Union.
- Private Corporations:Energy and logistics firms are purchasing detection-only packages directly from subsystem vendors, bypassing prime defense contractors.
- Government Facilities:Parliament buildings, nuclear sites, and diplomatic compounds are mandating certified counter-drone layers under national critical infrastructure protection regimes.
Contract value concentrates with Defense Agencies; the fastest-growing customer segment is Private Corporations as direct procurement channels open.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense production concentrates in the United States and Israel, while consumption spreads across NATO member states and Gulf Cooperation Council countries seeking layered air defense architectures. Procurement agencies in consuming nations now favor interoperable subsystems over integrated platforms, fragmenting contract awards across multiple national vendors.
United States
The Pentagon and FAA jointly shape certification pathways for airport-integrated counter-drone equipment, creating dual-use demand channels. The US European Command prioritizes NATO identification-friend-or-foe protocol compatibility for base protection layers. RTX and Lockheed Martin anchor radar and directed-energy development in Arizona and Massachusetts defense corridors.
Israel
The Ministry of Defense maintains classified performance benchmarks that filter foreign subsystem vendors, generating captive demand for domestically integrated packages. Rafael Advanced Defense Systems and Israel Aerospace Industries supply battle-proven kinetic interceptors drawn from operational experience in Middle Eastern theaters. Tel Aviv and Haifa host concentrated research clusters for electro-optical and electronic warfare subsystems.
United Kingdom
The Ministry of Defence runs independent competitions for radar and electronic attack modules under open-architecture procurement mandates. Leonardo S.p.A. and Thales supply GaN-based radar front-ends for layered base protection. Farnborough and Bristol defense clusters specialize in directed-energy integration with naval air defense programs.
Germany
The Bundeswehr procurement office prioritizes interoperability with NATO sensor-fusion standards for base and critical infrastructure protection. EU Drone Strategy 2.0 implementation forces standardized detection protocols at airports and power utilities. Munich and Hamburg industrial clusters focus on software-defined radio architectures for jamming subsystems.
India
The central electricity regulator and airport authority are drafting counter-drone mandates for grid substations and civilian airfields under critical infrastructure protection frameworks. Indigenous procurement preferences favor domestic integration of foreign radar and electro-optical subsystems. Bengaluru and Hyderabad defense corridors concentrate on acoustic detection and microwave neutralization technologies.
Anti-Drone Defense System Market Competitive Landscape
The competitive structure tilts toward defense primes with radar pedigrees and directed-energy integration capabilities. Tier-one contractors anchor layered detection architectures while specialized subsystem vendors capture modular upgrade contracts. Three archetypes dominate: radar-centric primes, directed-energy specialists, and battle-proven kinetic intercept suppliers. Consolidation pressure intensifies through strategic partnerships for GaN foundry access and open-architecture software licensing.
Among US-based defense contractors, RTX and Lockheed Martin Corporation exemplify the radar-to-directed-energy integration archetype. Rafael Advanced Defense Systems occupies a distinctive position as an Israeli prime with proven kinetic interceptor deployment. Leonardo S.p.A. and Thales represent European alternatives with concentrated GaN radar and electro-optical capabilities. Saab anchors Nordic procurement through national tender wins in Denmark, Norway, and Poland.
| Leading Market Players |
|---|
| RTX |
| Lockheed Martin Corporation |
| Rafael Advanced Defense Systems |
| Israel Aerospace Industries |
| Thales |
| Leonardo S.p.A. |
| Saab |
| DroneShield Ltd |
| Dedrone |
| Others |
Pricing and Supply Chain Analysis
Defense procurement offices abandoning single-vendor platform contracts for open-architecture sensor-fusion stacks are compressing vendor margins and forcing supply chains to absorb integration costs that primes once internalized.
Pricing Analysis
Cost-down pressure on jamming subsystems accelerates because commercial security suppliers are flooding the market with sub-$50,000 radio-frequency defeat mechanisms. Three-tier pricing structure across defense-grade, dual-use certified, and commercial-grade levels separates NATO-mandated interoperability premiums from airport perimeter detection bundles. Price differentiation hinges on GaN-based radar front-end certification and software-defined waveform update architectures. Airport authorities exhibit highest price sensitivity, while Israeli Ministry of Defense classified benchmarks sustain premium tiers for battle-proven kinetic interceptors.
Supply Chain Analysis
Freight costs for solid-state laser gain modules and GaN semiconductor wafers are climbing as foundry capacity concentrates in Taiwan, South Korea, and Japan. Raw material dependencies center on gallium nitride substrates, fiber-combined laser diodes, and precision electro-optical sensors. Single-source vulnerability in East Asian semiconductor fabrication facilities threatens directed-energy and radar subsystem delivery timelines. Distribution runs through defense prime contractors for military end-users, while commercial airport operators increasingly source detection-only packages directly from subsystem vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around radar-to-directed-energy integration capabilities as open-architecture mandates squeeze pure-play jamming vendors out of prime contractor tiers.
For Market Incumbents: Cement GaN foundry partnerships in Taiwan and South Korea to secure radar front-end supply continuity against export restriction risks. Deepen backward integration into solid-state laser diode manufacturing to capture directed-energy margin expansion as fiber-combined architectures achieve 50-kilowatt outputs. For New Entrants and Emerging Players: Airport system integrators represent the most penetrable channel partner type for detection-only subsystem vendors seeking to bypass prime defense contractors. Target India's central electricity regulator drafting counter-drone mandates for grid substations, where indigenous procurement preferences favor domestic integration of foreign radar and electro-optical subsystems. Lead with electromagnetic interference certification pre-aligned to FAA Reauthorization Act timelines. For Investors and Strategic Acquirers: The window for entry favors GaN radar front-end specialists with existing NATO identification-friend-or-foe protocol compatibility. Long-term viability rests on decade-long directed-energy development timelines rather than 3-4 year jamming hardware refresh cycles. Monitor Israeli Ministry of Defense benchmark declassification as the inflection signal for foreign subsystem vendor market access.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures radar front-end supply against Taiwan Strait logistics disruption. |
| Fiber-Combined Laser Scale-Up | Enables 50-kilowatt directed-energy integration with US Army programs. |
| Airport Direct Channel Expansion | Bypasses prime contractors for detection-only revenue at civilian airfields. |
| EU Drone Strategy 2.0 Certification | Opens standardized detection protocol mandates across member-state airports. |
| India Local Integration Partnership | Navigates indigenous procurement preferences for grid substation deployments. |
Research Methodology
Multi-period observation of defense procurement tender awards, subsystem vendor contract announcements, and regulatory certification timelines anchored the trend analysis, supplemented by interviews with radar subsystem engineering directors, directed-energy program managers at naval research offices, airport authority procurement leads, and GaN semiconductor foundry account executives. Secondary validation drew from US DoD budget justification documents, EU Drone Strategy 2.0 implementation reports, FAA certification docket filings, and Israeli Ministry of Defense procurement bulletins. Bottom-up vendor revenue aggregation triangulated against top-down national defense spending allocations.
Segment-weighting across neutralization mechanism, sensor modality, and operational environment dimensions structured the analytical framework, with product-type splits reflecting divergent replacement cycles between reversible soft-kill and permanent hard-kill solutions. CAGRs were derived from fitted growth curves across the projection horizon, incorporating solid-state laser efficiency improvement trajectories, GaN foundry capacity expansion schedules, and airport certification pathway maturation rates as defense-specific forecast inputs.
Caveats apply where FAA Reauthorization Act certification timeline extensions or Israeli Ministry of Defense benchmark adjustments could materially shift the outlook for subsystem vendor revenue recognition. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Military Computers Market
Defense Cybersecurity
Ballistics Targeting Software Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Railway Cyber Security Market
Defense Cybersecurity
Global C4I Systems Market