
 Mine and IED Detection System Market | 2026-2036
Mine and IED Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Mine and IED Detection System Market Foresight
Israeli defense electronics producers is decoupling from legacy component supply chains, shifting toward indigenous semiconductor sourcing for spectral processing modules. Elbit Systems leverages vertically integrated thermal imaging foundries to control sensor cost curves for handheld detectors. L3Harris Technologies sustains broad government channel access across multiple NATO procurement frameworks. General Dynamics Corporation anchors its position through captive manufacturing of ground-penetrating radar arrays for mounted vehicle programs.
Mine and IED detection systems integrate multi-spectral sensor fusion, ground-penetrating radar, and chemical trace analyzers to locate buried or concealed explosive threats with minimal false-positive rates. These platforms serve military route clearance, humanitarian demining operations, and critical infrastructure perimeter defense where manual probing risks personnel safety. Ground-based systems dominate current procurement volumes due to established military vehicle integration protocols, while robotics segments attract accelerated R&D investment as autonomous platform reliability improves in GPS-denied environments. Infrared technology leads margin pools through high-value thermal differentiation, whereas electromagnetic detection remains the volume workhorse across humanitarian aid applications.
FDA regulatory frameworks for electromagnetic emissions shape product certification requirements for systems deployed near civilian medical infrastructure, while FAA protocols govern unmanned aerial detection platform operations in shared airspace. ISO 17020 and IEC 61508 standards constrain design validation cycles for robotics segments serving ordnance disposal teams. Stakeholders must monitor how evolving national explosive ordnance disposal doctrines recalibrate the balance between autonomous robotics and human-in-the-loop detection protocols.
Market Dynamics
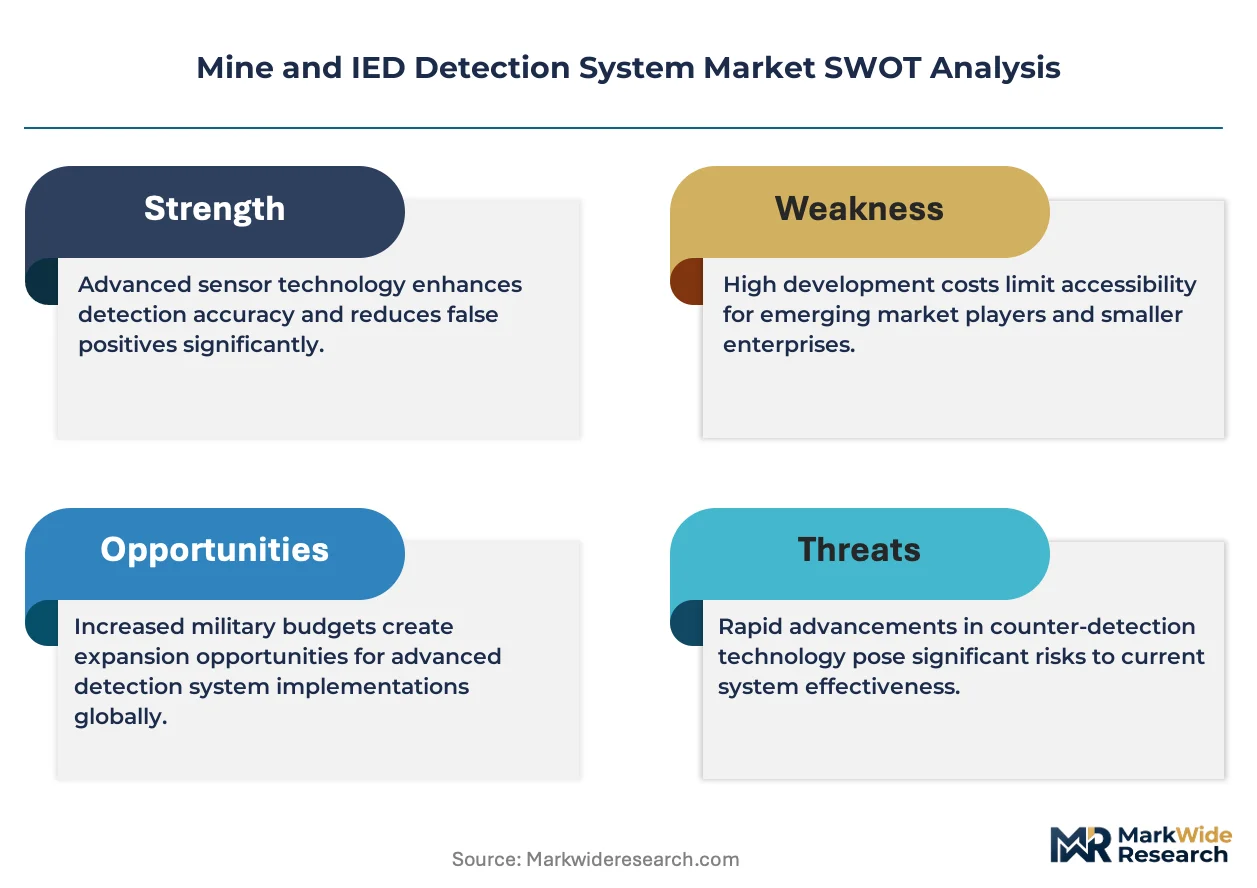
Electromagnetic emission constraints from FDA and FAA are forcing redesign cycles for multi-spectral detection platforms, compressing development timelines while elevating certification costs for dual-use military-civilian systems.
Growth Catalysts
- NATO Explosive Ordnance Disposal Protocols:Tightened standards for route clearance operations mandate robotics integration, accelerating procurement of autonomous ground platforms across member defense ministries.
- Israel:Indigenous semiconductor sourcing for spectral processing modules reduces supply chain vulnerability while lowering unit costs for thermal imaging subsystems.
- Ground-Penetrating Radar:Advances in signal processing algorithms enable deeper soil penetration with reduced false-positive rates, expanding deployment in humanitarian demining corridors.
Market Restraints
- Indium Gallium Arsenide Shortage:Constrained supply of infrared sensor substrate materials creates input cost volatility for thermal detector manufacturers.
- ISO 17020 Validation Cycles:Extended third-party conformity assessment timelines delay robotics platform commercialization by 8-14 months.
- Legacy Metal Detectors:Established humanitarian aid procurement patterns favor low-cost electromagnetic wands, slowing multi-spectral system penetration in price-sensitive segments.
Strategic Opportunities
- United Kingdom:Military modernization budgets prioritize counter-IED capabilities, creating white space for integrated vehicle-mounted detection suites.
- AI-Enhanced Sensor Fusion:Convergence of machine learning with hyperspectral imaging enables real-time threat classification without human-in-the-loop verification.
- United States Infrastructure Protection:Critical perimeter defense applications at transportation hubs and energy facilities drive demand for concealed weapon detection derivatives.
Industry Challenges
- Electromagnetic Compatibility Certification:IEC 61508 functional safety validation for robotics segments requires specialized testing facilities with 6-9 month queue times.
- GPS-Denied Navigation Integration:Autonomous platform reliability in jammed environments demands sensor redundancy that increases unit cost by 22-35 percent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mine and IED Detection System Market |
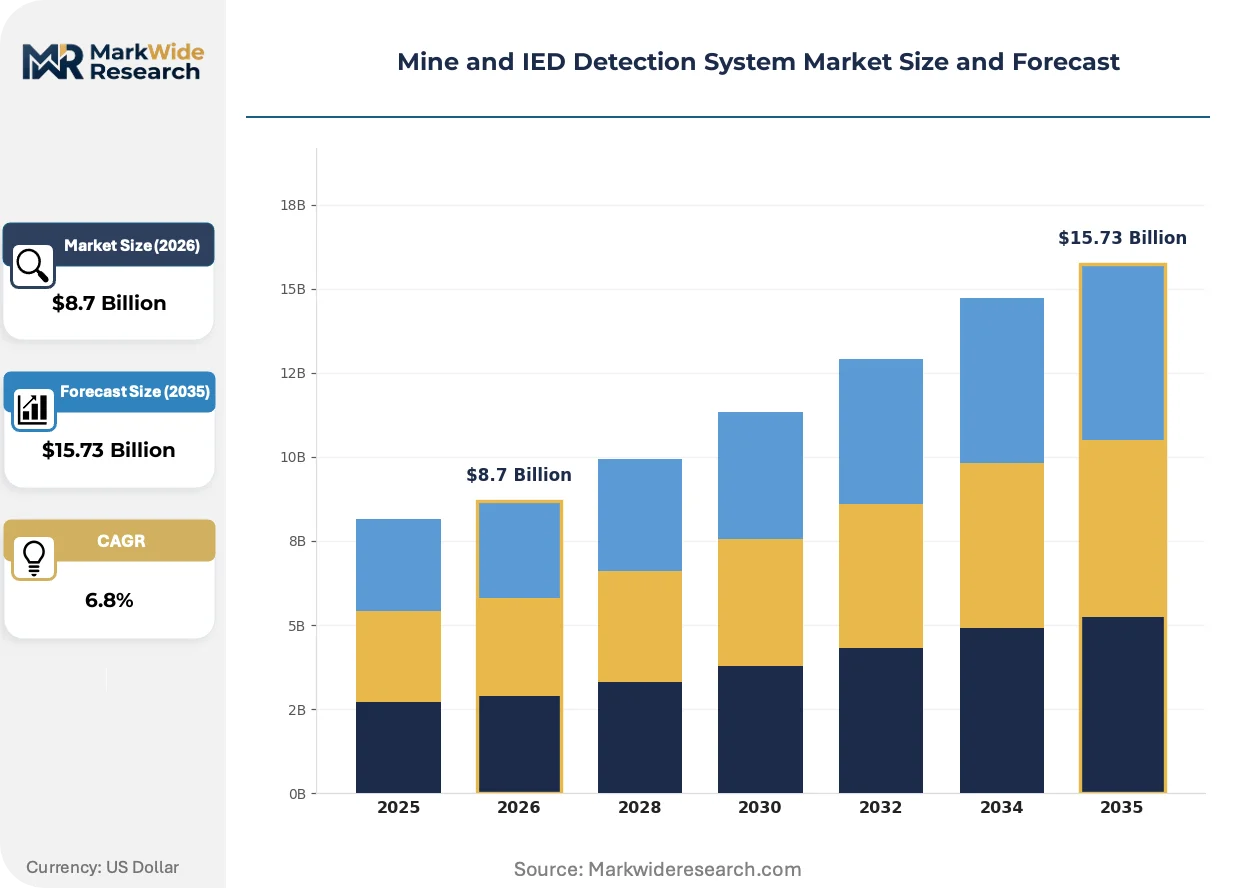
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Detectors, Ground-based Systems, Robotics, Mounted Systems Technology: Magnetic, Acoustic, Electromagnetic, Infrared Application: Military, Humanitarian Aid, Infrastructure Protection, Law Enforcement End User: Government Agencies, NGOs, Defense Contractors, Security Firms |
| Companies Covered | Israel Aerospace Industries, General Dynamics Corporation, BAE Systems, Thales Group, Lockheed Martin Corporation, Raytheon, L3Harris Technologies, Elbit Systems, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mine and IED Detection System Market Shifts & Advancements
Multi-spectral sensor architectures are compressing form factors while expanding threat-detection signatures, enabling platform migration from vehicle-mounted systems to dismounted soldier kits and unmanned aerial payloads.
Hyperspectral imaging is automating buried threat identification by distinguishing explosive chemical signatures from background soil composition. Military ordnance disposal teams in active conflict zones are field-testing handheld units with integrated spectral libraries. This capability is automating the preliminary screening phase that previously required manual soil probing, reducing personnel exposure time by eliminating false excavation events.
EU AI Act risk classification frameworks are imposing conformity assessment obligations on autonomous detection systems with decision-making authority. Robotics manufacturers serving NATO procurement channels must document algorithmic transparency and human oversight protocols. Ground-based autonomous segments face the steepest compliance burden, with several platforms requiring architectural redesign to maintain CE marking eligibility.
Defense ministries are consolidating vendor relationships through multi-year framework agreements that bundle detection hardware with training and maintenance services. Traditional spot procurement through national tenders is contracting as a channel model. This concentration is most visible in United States and Israeli military segments, where sole-source justification thresholds have risen to accommodate integrated system-of-systems awards.
Mine and IED Detection System Market Segmentation
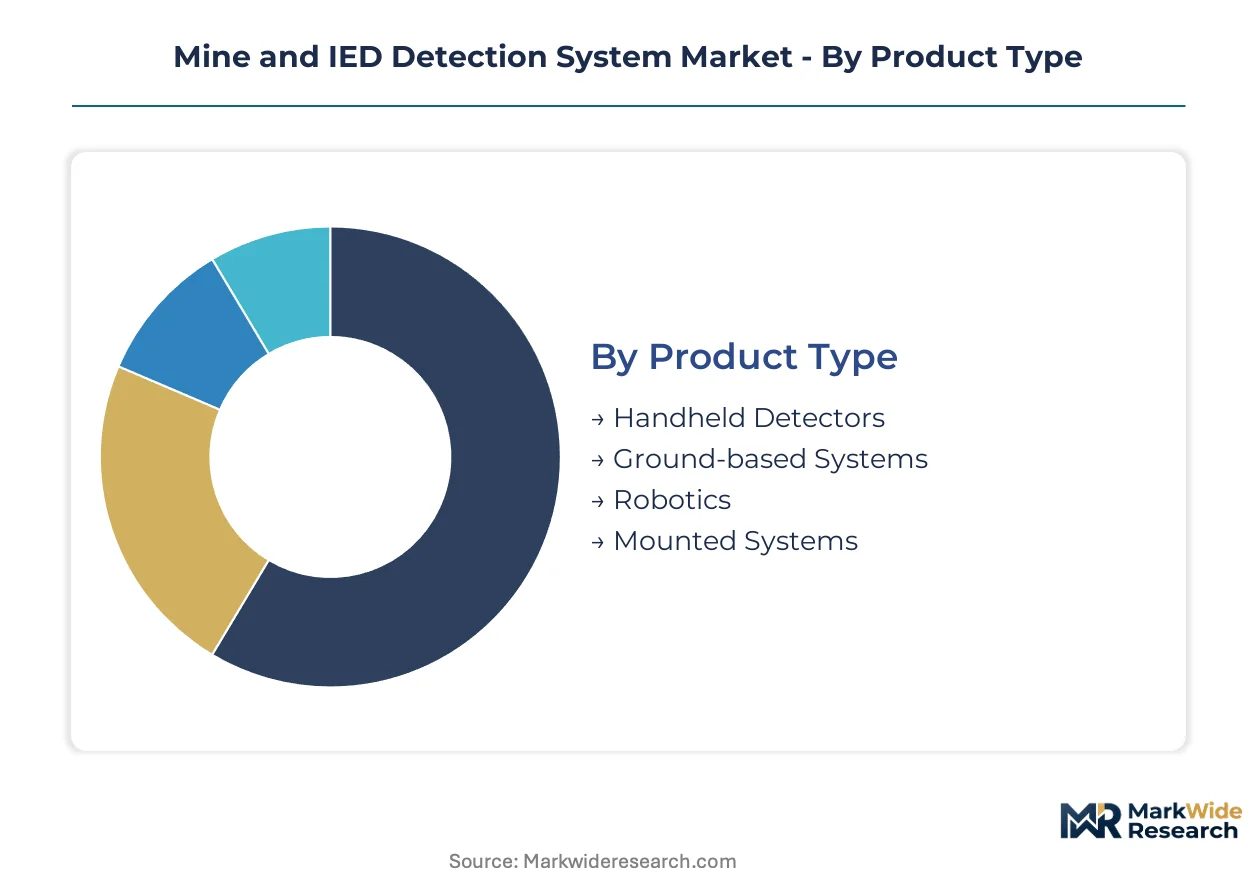
Segmentation in mine and IED detection systems reveals distinct procurement patterns across threat environments, with military route clearance demanding ruggedized vehicle integration while humanitarian operations prioritize portability and cost efficiency. Technology selection varies sharply by soil conditions, explosive composition, and operational tempo, creating specialized vendor ecosystems around each configuration.
Product Type:
Customization intensity spans from standardized handheld units for demining NGOs to fully bespoke mounted arrays integrated into specific armored vehicle chassis, with robotics occupying the middle ground where modular payloads adapt to mission profiles.
- Ground-based Systems:Vehicle-mounted or towed platforms integrate ground-penetrating radar arrays with electromagnetic coils for deep soil penetration. NATO member defense ministries in the United Kingdom and Germany concentrate procurement here, driven by route clearance protocols mandating platform standardization across mechanized units.
- Robotics:Autonomous or teleoperated platforms carry sensor payloads into hazardous zones without human exposure. Israel and the United States channel accelerated R&D investment into GPS-denied navigation capabilities as jamming threats intensify in contested electromagnetic environments.
- Handheld Detectors:Portable electromagnetic wands serve demining technicians in humanitarian corridors.
- Mounted Systems:Permanently integrated detection suites on military vehicles provide continuous route coverage.
Most installed capacity flows through Ground-based Systems. Expansion is steepest in Robotics.
Technology:
Cost tier separation is pronounced, with infrared thermal differentiation commanding premium pricing for specialized military applications while electromagnetic detection dominates volume procurement in price-sensitive humanitarian segments.
- Electromagnetic:Metal detection through eddy current induction remains the foundational technology for broad-area screening. Humanitarian aid procurement in former conflict zones across Southeast Asia and the Balkans relies on this mature, low-cost approach despite higher false-positive rates in mineralized soils.
- Infrared:Thermal imaging detects buried objects through differential heat signatures and soil disturbance patterns. Israeli defense electronics producers leverage indigenous semiconductor foundries to control sensor costs for handheld thermal detectors deployed in arid Middle Eastern terrain.
- Magnetic:Detection of ferrous components in legacy landmines through magnetic anomaly sensing.
- Acoustic:Seismic or sonic probing to identify density variations indicating buried threats.
Electromagnetic technology carries the largest installed base. Infrared platforms are climbing the fastest as spectral processing costs decline.
Application:
Customer maturity varies from established military doctrine with formal technical requirements to emergent infrastructure protection needs where detection specifications remain under development.
- Military:Route clearance, base perimeter defense, and ordnance disposal operations in active conflict zones. The United States and Israeli defense ministries drive specification-setting through multi-year framework agreements that bundle hardware with training and sustainment services.
- Humanitarian Aid:Post-conflict demining operations governed by international standards and donor funding cycles. Procurement concentrates through United Nations Mine Action Service coordination channels, favoring low-cost electromagnetic wands over multi-spectral alternatives.
- Infrastructure Protection:Perimeter security at transportation hubs, energy facilities, and critical installations.
- Law Enforcement:Bomb squad operations and suspicious package screening in urban environments.
Military application absorbs the majority of installed systems. Infrastructure Protection is gaining share fastest as critical facility hardening accelerates.
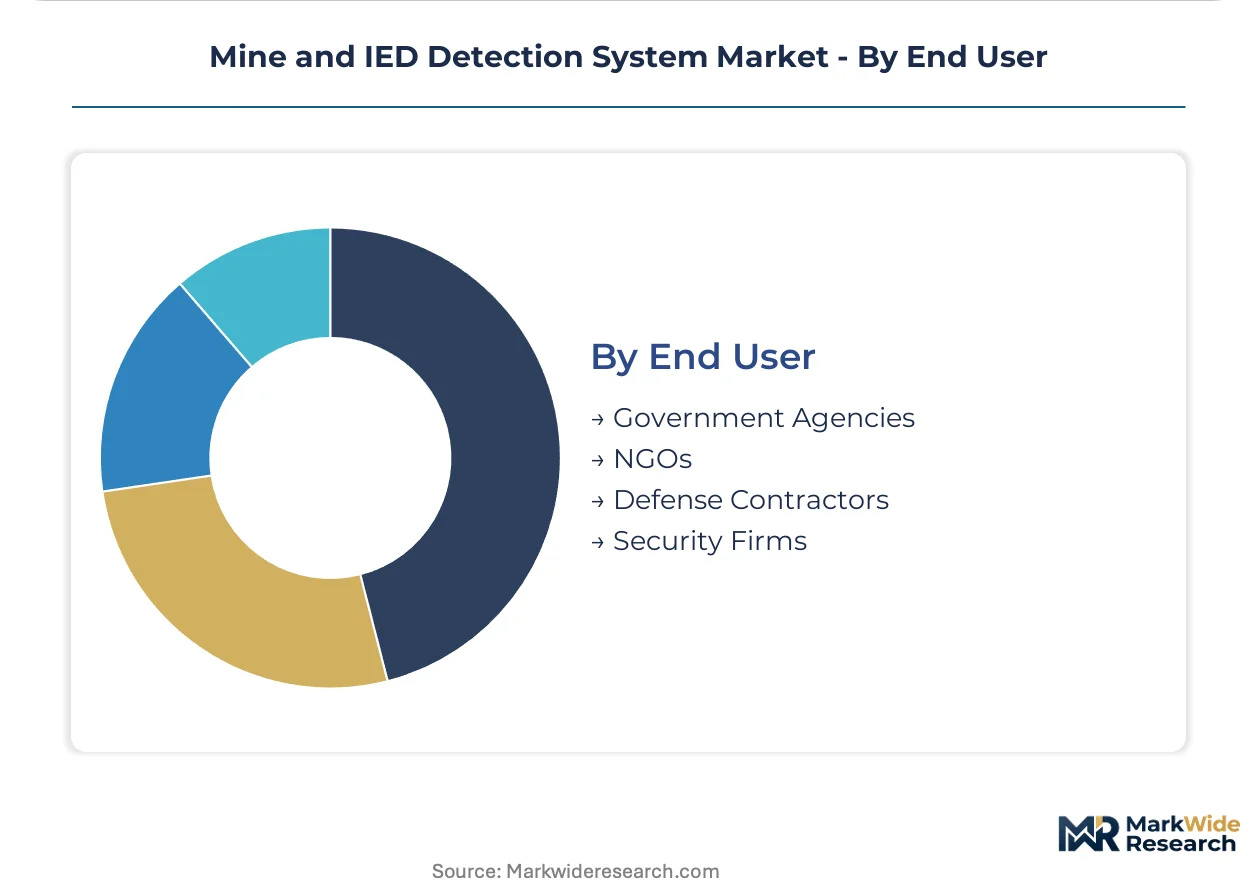
End User:
Supply concentration clusters around defense contractors with captive manufacturing capabilities, while NGO and security firm procurement remains fragmented across spot-market transactions.
- Defense Contractors:Prime system integrators serving national defense ministries with vehicle-mounted and robotics platforms. General Dynamics Corporation and L3Harris Technologies anchor this segment through long-term sole-source relationships with United States and NATO procurement channels.
- Government Agencies:National mine action authorities, border security services, and domestic law enforcement bomb squads. Budget cycles and political prioritization create demand volatility outside established military procurement frameworks.
- NGOs:Humanitarian demining organizations operating under donor grants and international coordination.
- Security Firms:Private sector providers of critical infrastructure protection and event security screening.
Defense Contractors control the largest share of deployed capacity. Government Agencies represent the steepest expansion trajectory as national security budgets diversify beyond traditional military channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with streamlined defense procurement frameworks and established electromagnetic compatibility certification infrastructure. Israel and the United States leverage captive semiconductor foundries to compress thermal sensor cost curves, while European NATO members face extended ISO 17020 validation timelines that elevate program entry costs.
United States
Defense modernization budgets channel counter-IED procurement through multi-year framework agreements bundling hardware with sustainment services. FAA protocols govern unmanned aerial detection platform operations in shared airspace, constraining rapid deployment timelines. Greater Boston and the Southwest defense corridor concentrate prime system integrators serving Pentagon ordnance disposal programs.
Israel
Indigenous semiconductor sourcing for spectral processing modules reduces supply chain vulnerability while lowering unit costs for thermal imaging subsystems. The country's national defense regulator mandates stringent electromagnetic emission standards for systems deployed near civilian medical infrastructure. Tel Aviv and Haifa anchor vertically integrated defense electronics clusters producing handheld detectors for arid terrain operations.
United Kingdom
Military modernization budgets prioritize vehicle-mounted detection suites for mechanized route clearance units. CE marking requirements under EU AI Act risk classification frameworks impose conformity assessment obligations on autonomous platforms with decision-making authority. The Midlands defense manufacturing belt hosts integration facilities for ground-penetrating radar arrays.
Germany
NATO explosive ordnance disposal protocols drive standardization requirements across mechanized units, favoring established vehicle-mounted platform suppliers. IEC 61508 functional safety validation for robotics segments requires specialized testing facilities with extended queue times. Bavaria and Baden-Württemberg concentrate precision sensor manufacturers serving dual-use military-civilian applications.
India
National security budgets diversify beyond traditional military channels toward critical infrastructure perimeter defense applications. The Bureau of Indian Standards constrains electromagnetic emission certification for systems deployed near civilian medical facilities. Bengaluru and Hyderabad emerge as robotics R&D hubs addressing GPS-denied navigation challenges for contested electromagnetic environments.
Mine and IED Detection System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue autonomous robotics and AI-enhanced sensor fusion architectures. The vendor base stratifies across three tiers: prime system integrators with sole-source government relationships, mid-tier specialists in thermal imaging and ground-penetrating radar subsystems, and component suppliers of electromagnetic coils and spectral processing modules. Dominant competitive moves include backward integration into captive semiconductor foundries and multi-year framework agreements bundling hardware with training and maintenance services.
Among Israel-based defense electronics producers, Elbit Systems exemplifies the vertically integrated archetype controlling thermal sensor cost curves through in-house foundry operations. General Dynamics Corporation anchors the prime system integrator tier through long-term relationships with United States and NATO procurement channels. L3Harris Technologies occupies a position spanning multiple government access points across allied defense frameworks.
| Leading Market Players |
|---|
| Israel Aerospace Industries |
| General Dynamics Corporation |
| BAE Systems |
| Thales Group |
| Lockheed Martin Corporation |
| Raytheon |
| L3Harris Technologies |
| Elbit Systems |
| Northrop Grumman Corporation |
| Others |
Supply & Pricing Matrix
Indium gallium arsenide substrate costs cascade from specialty foundries in Taiwan and Japan through tiered detector manufacturing, compressing margins for thermal imaging producers while electromagnetic coil suppliers in China maintain volume pricing leverage over humanitarian procurement channels.
Pricing Analysis
Distributor margins for ground-penetrating radar arrays absorb 12-18 percent of final system cost before reaching defense ministry procurement officers. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified vehicle platforms from commercial-grade handheld units and donor-funded humanitarian wands. Pricing pressure stems from indium gallium arsenide supply constraints as infrared sensor substrate availability tightens. Humanitarian aid organizations exhibit highest price sensitivity, while Israeli and United States defense ministries prioritize performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Tel Aviv, Boston, and Stuttgart coordinate hub-and-spoke patterns for classified military hardware, with civilian-facing components flowing through commercial logistics networks. Manufacturing concentrates in Israel, the United States, and Germany for spectral processing modules, electromagnetic coils, and ground-penetrating radar arrays. The supply chain rests on indium gallium arsenide substrates, precision optical components, and radiation-hardened semiconductors. Single-source vulnerability in infrared sensor materials creates exposure to export control restrictions. Distribution runs through sole-source framework agreements for defense contractors and spot procurement for humanitarian organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in thermal imaging subsystems as indigenous semiconductor sourcing compresses sensor cost curves and premium-tier robotics displace legacy vehicle-mounted platforms.
For Market Incumbents: Deepen captive foundry control over spectral processing modules to offset indium gallium arsenide price volatility. Anchor sole-source relationships with United States and NATO procurement channels through multi-year framework agreements bundling hardware with training and sustainment services. For New Entrants and Emerging Players: AI-enhanced sensor fusion architectures offer entry points into GPS-denied navigation segments where autonomous platform reliability commands premium pricing. Target infrastructure protection applications at transportation hubs and energy facilities where detection specifications remain under development and vendor relationships are unconsolidated. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 17020 validation timelines and IEC 61508 certification requirements create barriers to robotics platform commercialization. Mid-tier thermal imaging specialists with indigenous semiconductor capabilities represent attractive acquisition targets. Watch for EU AI Act conformity assessment obligations as inflection indicators for platform redesign cycles and vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Indigenous Semiconductor Foundry Investment | Elbit Systems controls thermal sensor cost curves through vertically integrated production in Tel Aviv and Haifa. |
| Multi-Year Framework Agreement Expansion | General Dynamics and L3Harris anchor Pentagon procurement through bundled hardware-sustainment contracts. |
| AI-Enhanced Sensor Fusion Development | Machine learning integration with hyperspectral imaging enables real-time threat classification without human verification. |
| GPS-Denied Navigation Capability Investment | Autonomous platform reliability in jammed environments demands sensor redundancy that increases unit premiums. |
| Humanitarian Certification Pathway | ISO 17020 and IEC 61508 compliance opens access to United Nations Mine Action Service coordination channels. |
Research Methodology
Coverage spans the United States, Israel, the United Kingdom, Germany, and India, with primary inputs from each defense procurement ecosystem. The approach combines primary interviews with ordnance disposal program officers, defense electronics procurement leads, humanitarian demining coordinators, and robotics platform engineers with secondary validation. Secondary sources include NATO explosive ordnance disposal protocol documentation, FDA electromagnetic emission filings, FAA unmanned aerial system certifications, and defense ministry budget appropriations records. Bottom-up unit economics and top-down budget allocation triangulation anchor market sizing.
Granularity-level modeling operates at the intersection of product type, technology, application, and end-user segments across national procurement frameworks. CAGRs derive from defense modernization budget trajectories, humanitarian aid donor cycles, and infrastructure protection spending patterns. Industry-specific forecast inputs include electromagnetic compatibility certification queue times, indium gallium arsenide substrate supply forecasts, and evolving national explosive ordnance disposal doctrines.
The model holds under sustained NATO procurement standardization and continued Israeli semiconductor self-sufficiency; deviation in export control regimes or humanitarian funding cycles would shift volume assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Railway Cyber Security Market
Defense Cybersecurity
Aviation Cyber Security Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Asia-Pacific Missiles and Missile Defense Systems Market