
 North America Commercial Aircraft Market | 2026-2036
North America Commercial Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Aircraft Market Analytics
Next-generation fuel efficiency specifications is collapsing the competitive gap between established OEMs and specialized challengers. The Boeing Company leverages its Everett and Charleston production complexes to sustain wide-body output dominance. Bombardier differentiates through regional jet specialization serving thin-route operators. Embraer anchors the sub-150-seat segment with advanced turbofan configurations purpose-built for North American feeder markets.
North America commercial aircraft encompass fixed-wing transport platforms with maximum takeoff weights exceeding 5,700 kilograms, engineered primarily from aluminum alloys, carbon-fiber composites, and titanium structural elements to achieve specific range-payload profiles for passenger and freight carriage. Narrow-body configurations command the largest production volumes due to route density economics on domestic and near-international sectors, while composite material adoption advances fastest as airframers pursue weight reduction targets. Wide-body platforms concentrate margin pools in premium cabin configurations and long-haul engine aftermarket services.
FAA Part 25 airworthiness standards and EPA aircraft engine emission regulations shape product development cycles and fleet retirement timelines across United States operators. Transport Canada certification requirements and ICAO carbon offset mechanisms further constrain design choices for manufacturers serving cross-border routes. Stakeholders must monitor sustainable aviation fuel infrastructure buildout and potential NOx stringency revisions as determinants of next-generation platform competitiveness.
Market Dynamics
FAA Part 25 certification cycles and EPA aircraft engine emission standards are compressing OEM development timelines while simultaneously accelerating fleet retirement decisions among United States carriers. The regulatory dual pressure is restructuring procurement patterns across narrow-body and wide-body segments alike.
Growth Catalysts
- Sustainable Aviation Fuel Infrastructure:United States federal tax incentives under the Inflation Reduction Act are stimulating airport fueling system upgrades. Low-cost carriers are embedding SAF compatibility requirements into new narrow-body orders.
- Ultra-Low-Cost Carrier Expansion:Thin-route operators across the United States and Canada are driving demand for sub-150-seat configurations. These carriers prioritize acquisition cost per seat-mile over maximum range capability.
- Next-Generation Engine Technology:Geared turbofan architectures and open-rotor prototypes are delivering double-digit fuel efficiency gains. Pratt & Whitney and CFM International are fielding powerplants that meet ICAO carbon offset thresholds.
Market Restraints
- Titanium and Composite Input Volatility:Aerospace-grade titanium sponge pricing fluctuates with Russian export restrictions. Carbon-fiber prepreg supply concentrates among Japanese and United States chemical conglomerates.
- Single-Source Supplier Risk:Critical avionics and landing gear subsystems rely on concentrated United States and European tier-one bases. Geographic concentration amplifies disruption vulnerability from trade policy shifts.
- Certification Timeline Friction:FAA type certification for novel airframe architectures averages four to six years. Extended validation periods strain OEM cash conversion cycles and deter radical design departures.
Strategic Opportunities
- Mexico Manufacturing Expansion:Querétaro and Baja California aerospace clusters offer labor cost arbitrage and proximity to United States final assembly lines. Bombardier and tier suppliers have established captive machining operations.
- Urban Air Mobility Convergence:Electric vertical takeoff and landing platforms are creating new certification pathways through FAA Part 23 reform. Commercial aircraft OEMs are acquiring eVTOL startups to secure urban feeder route positioning.
- Maintenance, Repair, and Overhaul Digitization:Predictive analytics and digital twin platforms are unbundling traditional engine service contracts. Independent MRO providers in the United States are capturing aftermarket margin pools previously held by OEMs.
Industry Challenges
- Aerospace Engineering Talent Scarcity:United States universities produce insufficient composite stress analysts and propulsion thermodynamicists. OEMs and tier suppliers compete for the same limited pool of FAA-designated engineering representatives.
- Legacy Fleet Integration Complexity:New avionics suites and connectivity retrofits must interface with 1980s-era cockpit architectures. Certification of mixed-generation systems consumes disproportionate FAA engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Aircraft Market |
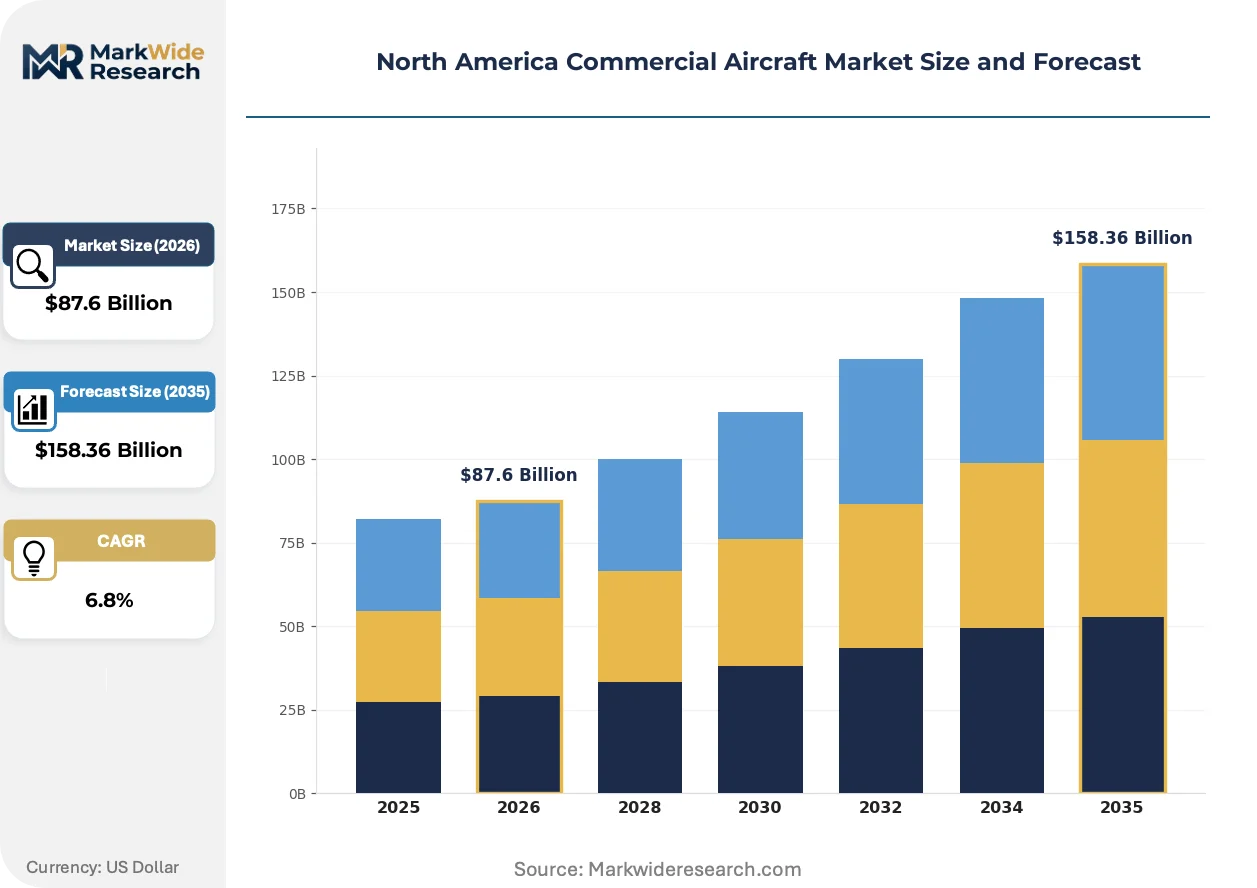
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Narrow-body, Wide-body, Regional Jet, Cargo Aircraft End User: Commercial Airlines, Charter Services, Cargo Operators, Governments Material Type: Aluminum, Composite, Titanium, Steel Engine Technology: Turbofan, Turbojet, Turboprop, Hybrid |
| Companies Covered | De Havilland Aircraft of Canada Ltd, ATR, The Boeing Company, Lockheed Martin, Textron Aviation, Airbus SE, Bombardier, United Aircraft Corporation, Embraer, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Aircraft Market Evolving Landscape
Propulsion-airframe integration and digital manufacturing methods are converging to redefine production economics across North American commercial aviation. These shifts are compressing development cycles while expanding the feasible design space for next-generation platforms.
Additive manufacturing is fragmenting traditional subtractive machining supply chains for titanium and nickel superalloy engine components. GE Aviation and Pratt & Whitney are qualifying 3D-printed fuel nozzles and compressor stators for LEAP and GTF powerplants. The technology is fragmenting procurement patterns by enabling point-of-use production and reducing minimum efficient scale thresholds for complex geometries.
EPA aircraft engine emission regulations and ICAO carbon offset reduction schemes are mandating NOx and particulate matter reductions across thrust classes. United States carriers face compliance deadlines that accelerate retirement of pre-2000 engine architectures. Wide-body operators serving trans-Pacific routes are most exposed, driving demand for re-engining programs and new-generation twin-aisle acquisitions.
Ultra-low-cost carriers are unbundling fleet acquisition from full-service maintenance contracts. Spirit Airlines and Frontier Airlines are negotiating power-by-the-hour alternatives with independent MRO networks. The United States domestic market exhibits the most pronounced shift, with narrow-body operators prioritizing operational flexibility over OEM-captive service arrangements.
North America Commercial Aircraft Market Segmentation
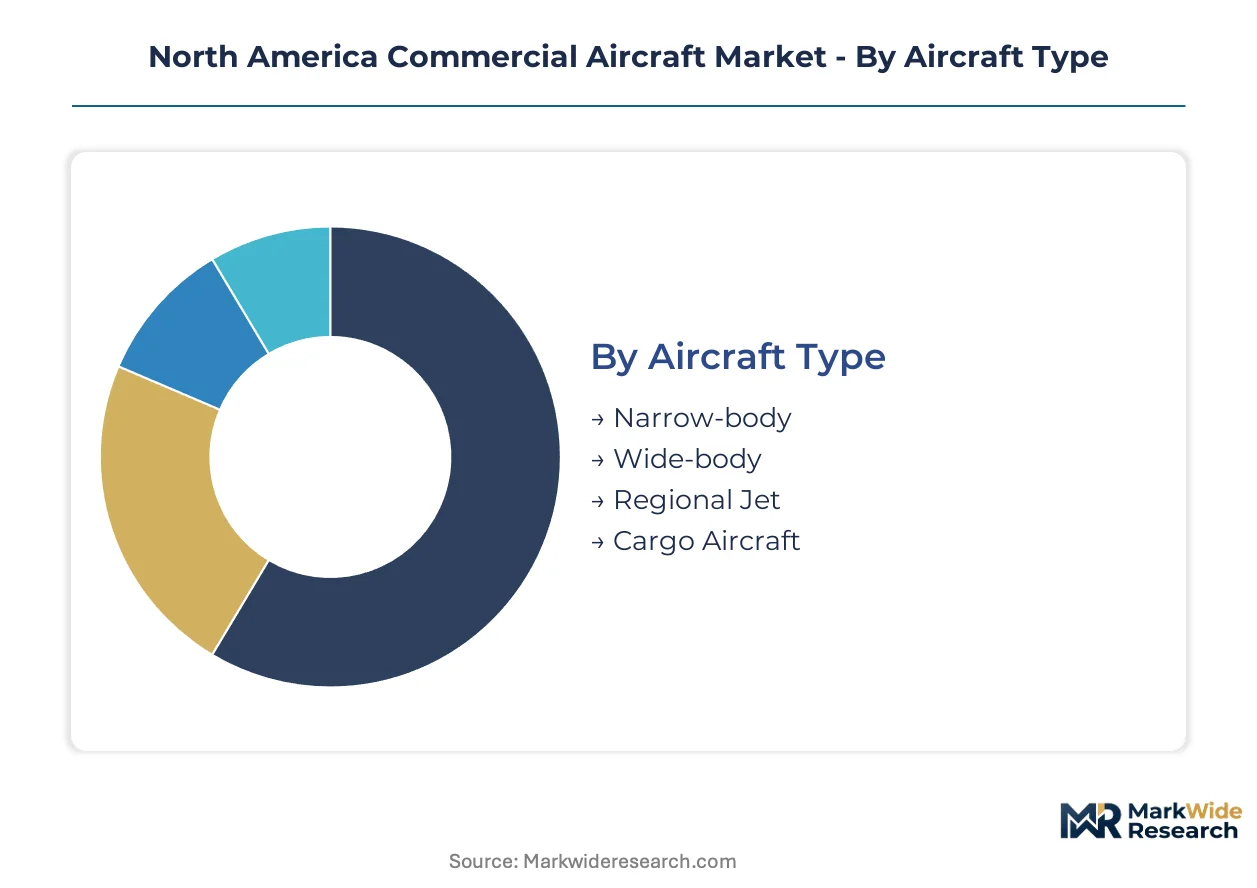
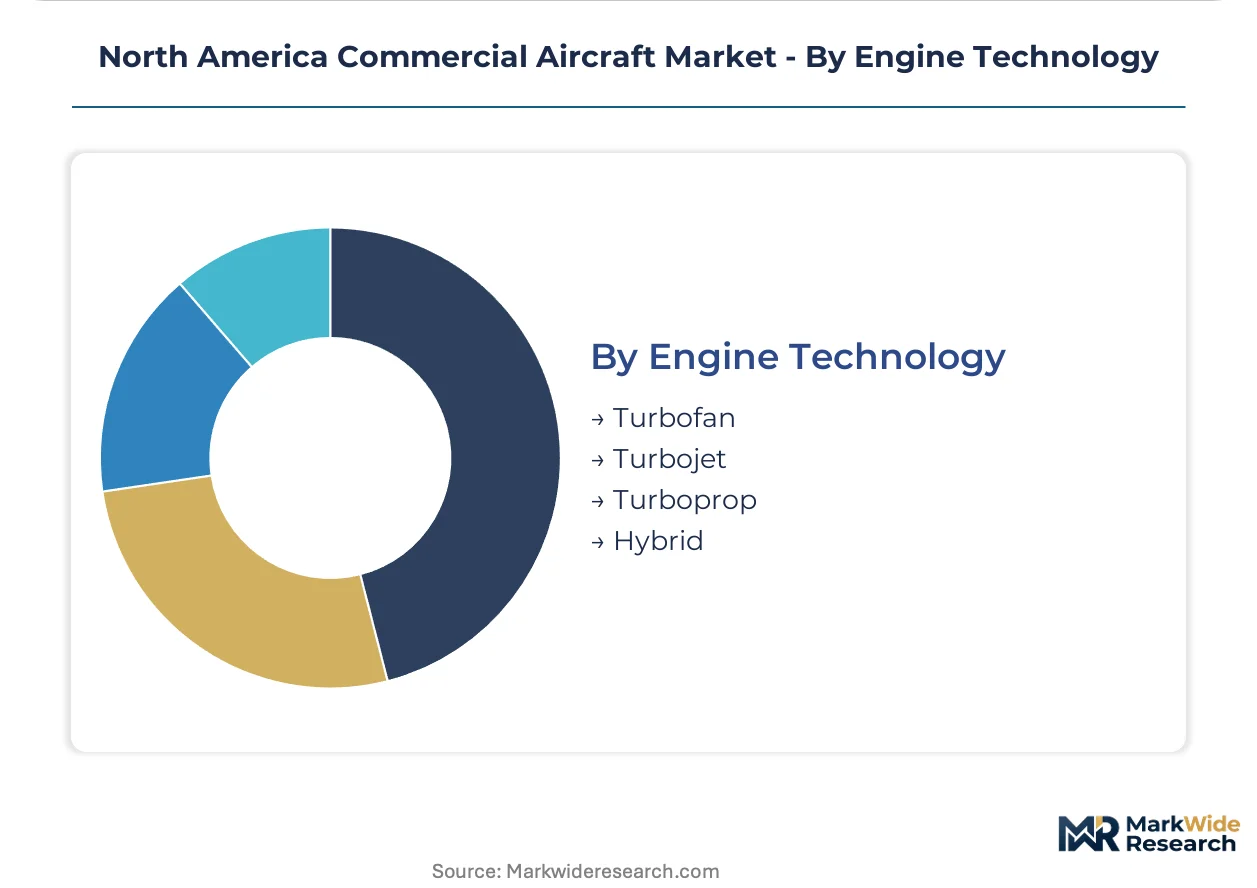
Segmentation reveals how procurement patterns diverge across North American operators. FAA certification pathways and route economics create distinct demand clusters that reshape manufacturing priorities and aftermarket service requirements.
Aircraft Type:
Domestic United States carriers drive narrow-body volume, while export-led wide-body demand concentrates in long-haul international gateways. Canadian operators and Mexican charter services anchor regional jet procurement.
- Narrow-body:Single-aisle configurations dominate United States domestic route networks with aluminum-intensive fuselage construction optimized for high-cycle operations. Ultra-low-cost carriers in Dallas, Denver, and Las Vegas anchor fleet renewal programs targeting fuel efficiency gains on sub-3,000 nautical mile sectors.
- Wide-body:Twin-aisle platforms serve trans-Pacific and trans-Atlantic corridors from Seattle, Los Angeles, and Toronto Pearson with composite wing structures and premium cabin density. United Airlines and Air Canada prioritize these acquisitions for international hub expansion despite higher unit acquisition costs.
- Regional Jet:Sub-100-seat turbofan aircraft connect secondary United States cities to major hubs; Bombardier and Embraer production lines in Montreal and São Paulo feed this segment.
- Cargo Aircraft:Converted wide-body freighters and purpose-built express haulers serve Memphis, Louisville, and Anchorage logistics hubs; e-commerce volume growth drives Amazon Air and UPS fleet expansion.
Narrow-body holds the largest share; momentum sits with regional jets as thin-route economics improve.
End User:
Cost tier segmentation separates capital-intensive scheduled operators from asset-light charter and government purchasers.
- Commercial Airlines:Scheduled carriers operate under FAA Part 121 certificates with standardized maintenance programs and unionized flight crews; network carriers in Atlanta, Chicago, and Dallas-Fort Worth concentrate wide-body orders while low-cost operators prioritize narrow-body fleet commonality.
- Cargo Operators:Express integrators and dedicated freighter airlines acquire converted passenger aircraft and factory-built cargo variants; FedEx Express in Memphis and Atlas Air in Purchase, New York dominate dedicated freighter procurement with overnight network requirements.
- Charter Services:Part 135 operators provide on-demand capacity without fixed route obligations; NetJets and Flexjet in Columbus, Ohio leverage fractional ownership models.
- Governments:Federal, state, and provincial agencies acquire VIP transport, surveillance, and multi-mission platforms; United States Air Force C-40 and Coast Guard HC-144 programs exemplify this segment.
Commercial airlines command procurement volume; cargo operators are expanding most quickly on e-commerce logistics demand.
Material Type:
Supply concentration determines cost structure and fabrication lead times across airframe manufacturing.
- Composite:Carbon-fiber reinforced polymers constitute wing skins, control surfaces, and pressure bulkheads on next-generation narrow-body and wide-body platforms. Boeing Charleston and Airbus Mobile facilities drive demand for Toray and Hexcel prepreg supply.
- Aluminum:2000 and 7000 series alloys remain dominant for fuselage skins and floor beams due to damage tolerance and repairability; Alcoa Tennessee and Arconic supply primary airframe extrusions.
- Titanium:Mill products and forgings concentrate in engine nacelles, landing gear, and high-temperature exhaust fairings; VSMPO-AVISMA restrictions redirect United States sourcing toward ATI and RTI International Metals.
- Steel:High-strength alloys and superalloys constrain landing gear and actuator applications; Carpenter Technology and Universal Stainless supply aerospace-grade bar and forgings.
Aluminum retains installed base dominance; composite applications show steepest expansion trajectory on weight reduction mandates.
Engine Technology:
Customer type segmentation separates high-utilization airline operators from intermittent-use government and charter fleets.
- Turbofan:High-bypass ratio powerplants from Pratt & Whitney and CFM International propel narrow-body and wide-body platforms with geared architectures delivering double-digit fuel efficiency improvements. United, Delta, and American Airlines anchor LEAP and GTF adoption through fleet renewal programs.
- Turboprop:Gas turbine engines driving propeller systems serve regional routes below 500 nautical miles with superior short-field performance; ATR and De Havilland Canada aircraft operate from Boston Harbor and Vancouver Island airports.
- Turbojet:Pure jet propulsion survives in legacy military derivatives and small business aircraft; limited civil applications constrain production scale.
- Hybrid:Turboelectric and parallel-hybrid architectures remain in demonstration phase with NASA and FAA Sustainable Flight National Partnership funding; no commercial certification timeline is established.
Turbofan technology commands the installed base; hybrid architectures are gaining share fastest on decarbonization investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airframe assembly and engine manufacturing concentrate in three national jurisdictions. FAA certification authority, Transport Canada design standards, and Mexican aerospace cluster development create differentiated production footprints across the continent.
United States
Ultra-low-cost carriers in Dallas, Denver, and Las Vegas drive narrow-body fleet renewal with SAF-compatible specifications. FAA Part 25 certification timelines and EPA engine emission standards compress procurement cycles for domestic operators. Boeing's Everett and Charleston complexes anchor wide-body final assembly, while Pratt & Whitney's East Hartford facility produces geared turbofan powerplants for United and Delta.
Canada
Regional jet demand from Air Canada Express and thin-route operators sustains sub-150-seat procurement. Transport Canada certification requirements align with ICAO carbon offset mechanisms for cross-border fleet operations. Bombardier's Montreal production lines and De Havilland's Downsview facility concentrate turboprop and regional jet manufacturing for North American feeder markets.
Mexico
Querétaro and Baja California aerospace clusters supply machined components and subassemblies to United States final assembly lines. Mexican federal manufacturing incentives and USMCA rules of origin provisions attract tier-one supplier investment. Bombardier's Querétaro captive machining operations produce wing components and control surfaces for regional jet programs.
North America Commercial Aircraft Market Competitive Landscape
Concentration sits with integrated airframers possessing captive certification expertise and multi-decade operator relationships. The competitive structure divides between full-line manufacturers covering narrow-body through wide-body segments and specialized regional jet producers serving thin-route economics. Strategic archetypes include platform-scale integrators, sub-150-seat specialists, and government-mission derivatives. Dominant competitive moves involve production site diversification into lower-cost jurisdictions and vertical integration into engine aftermarket services.
Among integrated airframers, The Boeing Company and Airbus SE occupy positions spanning the full product spectrum from single-aisle to twin-aisle platforms. Bombardier and Embraer exemplify the specialist archetype with concentrated regional jet portfolios. De Havilland Aircraft of Canada Ltd represents the turboprop-focused tier serving short-field and thin-density route requirements.
| Leading Market Players |
|---|
| De Havilland Aircraft of Canada Ltd |
| ATR |
| The Boeing Company |
| Lockheed Martin |
| Textron Aviation |
| Airbus SE |
| Bombardier |
| United Aircraft Corporation |
| Embraer |
| Others |
Value Network & Pricing Analysis
Everett and Charleston production line utilization rates above eighty percent concentrate pricing power with Boeing and tier-one suppliers. This scale concentration compresses unit economics for narrow-body platforms while elevating price floors for wide-body configurations serving trans-Pacific routes.
Pricing Analysis
FAA Part 25 certification tiers dictate the pricing structure across North American commercial aviation. Three-tier pricing stratifies across premium long-haul configurations, standard domestic narrow-bodies, and economy regional jet platforms. Price differentiation centers on engine aftermarket bundling and airframe customization levels. Pricing pressure stems from ultra-low-cost carriers unbundling maintenance contracts and negotiating power-by-the-hour alternatives. Charter operators under Part 135 certificates exhibit highest price sensitivity; network carriers with hub-and-spoke operations show lowest sensitivity due to route density economics.
Supply Chain Analysis
Titanium sponge export restrictions through VSMPO-AVISMA chokepoints redirect United States sourcing toward ATI and RTI International Metals. Aerospace-grade carbon-fiber prepreg concentrates in Japanese and United States chemical conglomerates; aluminum extrusions feed from Alcoa Tennessee and Arconic. Supply chain risk rests on single-source avionics and landing gear subsystems concentrated in United States and European tier-one bases. Distribution runs through Boeing's integrated supplier network and Airbus Mobile's regional assembly hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American commercial aircraft markets generate substantial service-attach economics as predictive maintenance platforms and digital twin technologies expand faster than airframe deliveries. Engine aftermarket contracts and MRO digitization layers now command margin premiums exceeding hardware procurement cycles.
For Market Incumbents: Fortify captive engine service networks against independent MRO encroachment through long-term power-by-the-hour contracts with United and Delta. Deepen backward integration into titanium machining capacity at Querétaro to offset Russian supply disruption. Prioritize FAA Part 25 certification investment for sustainable aviation fuel compatibility as EPA emission standards tighten. For New Entrants and Emerging Players: Lead with electric vertical takeoff and landing platforms targeting urban feeder routes from Dallas-Fort Worth and Denver hubs. Exploit white-space in sub-150-seat regional jet aftermarket services where Bombardier and Embraer coverage gaps persist. Pursue FAA Part 23 reform pathways for novel airframe architectures bypassing traditional type certification timelines. For Investors and Strategic Acquirers: Specialized avionics suppliers with FAA-designated engineering representative credentials offer consolidation targets as aerospace engineering talent scarcity intensifies. Long-term viability centers on service revenue predictability rather than cyclical airframe deliveries. Monitor sustainable aviation fuel infrastructure buildout at Memphis, Louisville, and Anchorage as inflection indicator for fleet renewal acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Production Site Diversification | Querétaro and Baja California clusters reduce labor cost exposure for tier suppliers. |
| Engine Aftermarket Integration | Pratt & Whitney's East Hartford facility captures long-haul service margins from United. |
| Sustainable Aviation Fuel Certification | FAA Part 25 SAF compatibility requirements reshape procurement criteria for Delta. |
| Digital Twin Platform Deployment | Predictive analytics unbundle traditional engine contracts at independent MRO networks. |
| Regional Jet Specialization | Embraer's sub-150-seat configurations anchor thin-route economics for Frontier. |
Research Methodology
A spread of perspectives from fleet planning executives at United and Delta, procurement directors at tier-one suppliers, FAA certification engineers, and MRO operations managers converged on the working assumptions. Secondary validation drew from FAA type certification databases, EPA engine emission filings, Transport Canada design standard records, and customs data tracking titanium and carbon-fiber imports. Bottom-up aircraft delivery forecasts triangulated against top-down route density economics across domestic and trans-Pacific corridors.
Segmentation dimensions modeled include aircraft type, end user category, material composition, and engine technology architecture across the projection horizon. CAGRs derived from production line capacity constraints, fleet retirement timelines driven by EPA standards, and ultra-low-cost carrier expansion trajectories. Industry-specific inputs incorporated fuel efficiency specifications, ICAO carbon offset thresholds, and sustainable aviation fuel infrastructure deployment schedules.
Forecasts assume regulatory continuity in FAA Part 25, EPA aircraft engine emission standards, and Transport Canada certification requirements; material policy shifts would require re-modeling of fleet retirement timelines and procurement cycles. Practitioners should keep alternative scenarios live as sustainable aviation fuel tax incentive structures and titanium supply chain reconfigurations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Attack Helicopter Market
Aircraft
Airship Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
General Aviation Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Afterburner Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Aircraft Wheels Market
Aircraft
Europe Aviation Market
Aircraft
America Attack Helicopter Market