
 Tactical Communications Market | 2026-2036
Tactical Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical Communications Market Analysis
Defense end-use demand is hardening as military forces prioritize resilient, jam-resistant links for contested electromagnetic environments. L3Harris Technologies leverages decades of radio-frequency expertise to anchor its position in man-portable and vehicular platforms. Thales Group competes across European NATO markets with integrated soldier systems that extend beyond voice to full situational-awareness suites. Elbit Systems dominates Israeli and allied defense procurement through vertically integrated offerings spanning radios, terminals, and network management software.
Tactical communications encompass encrypted voice, data, and video transmission equipment engineered to operate in spectrum-contested, GPS-denied, and physically harsh conditions, typically conforming to military standards such as MIL-STD-188 for interoperability and security. Radio products sustain the largest revenue pool given their ubiquity across dismounted soldier, vehicle, and airborne platforms, though network equipment represents the fastest-expanding segment as forces transition from point-to-point links to self-healing mesh architectures. Satellite communication technology captures premium margins for beyond-line-of-sight requirements, while radio frequency segments face pricing pressure from software-defined alternatives that reprogram waveforms without hardware swaps.
The U.S. Department of Defense, NATO Standardization Office, and the European Union's Radio Spectrum Committee each impose distinct certification and interoperability mandates that shape procurement timelines and vendor qualification barriers. FCC regulations in the United States and CE marking requirements in Europe further constrain civilian-adjacent product configurations, forcing dual-track development for military-exclusive and dual-use variants. Stakeholders must monitor spectrum reallocation decisions and emerging quantum-resistant encryption standards, as these will determine which incumbent platforms retain relevance and which suppliers face obsolescence risk.
Market Dynamics
Software-defined radio architectures are collapsing the traditional hardware refresh cycle, forcing incumbents to abandon fixed-waveform equipment in favor of reprogrammable platforms that adapt to spectrum reallocation without physical swaps.
Growth Catalysts
- Defense Modernization Mandates:NATO Standardization Office interoperability requirements are compelling member states to retire legacy analog systems and procure encrypted IP-based networks.
- Contested Spectrum Operations:Military end-users demand anti-jam waveforms for GPS-denied environments, accelerating procurement of frequency-hopping and cognitive radio technologies.
- Mesh Networking Protocols:Self-healing network architectures eliminate single points of failure, driving replacement of hub-and-spoke command structures in dismounted soldier programs.
Market Restraints
- Semiconductor Supply Concentration:Advanced RF component fabrication concentrates in East Asian foundries, exposing procurement timelines to geopolitical disruption risks.
- Dual-Use Export Controls:U.S. International Traffic in Arms Regulations and EU dual-use regulations impose multi-year qualification barriers on cross-border technology transfer.
- Legacy System Interoperability:Fielded analog radios lack backward compatibility with digital waveforms, forcing expensive gateway equipment or complete fleet replacement.
Strategic Opportunities
- Quantum-Resistant Encryption:NIST post-quantum cryptographic standards will mandate hardware refreshes across classified communication tiers, creating replacement demand.
- Commercial Spectrum Sharing:Dynamic spectrum access technologies enable military use of civilian bands during emergencies, opening dual-use revenue streams.
- Integrated Soldier Systems:Convergence of radio, navigation, and biometric monitoring into single wearable platforms expands addressable equipment value per warfighter.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized microwave and antenna design expertise pools thinly across defense contractors and commercial telecom, inflating compensation costs.
- Multi-Domain Certification Timelines:Simultaneous airworthiness, maritime, and ground vehicle qualification for single radio models extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical Communications Market |
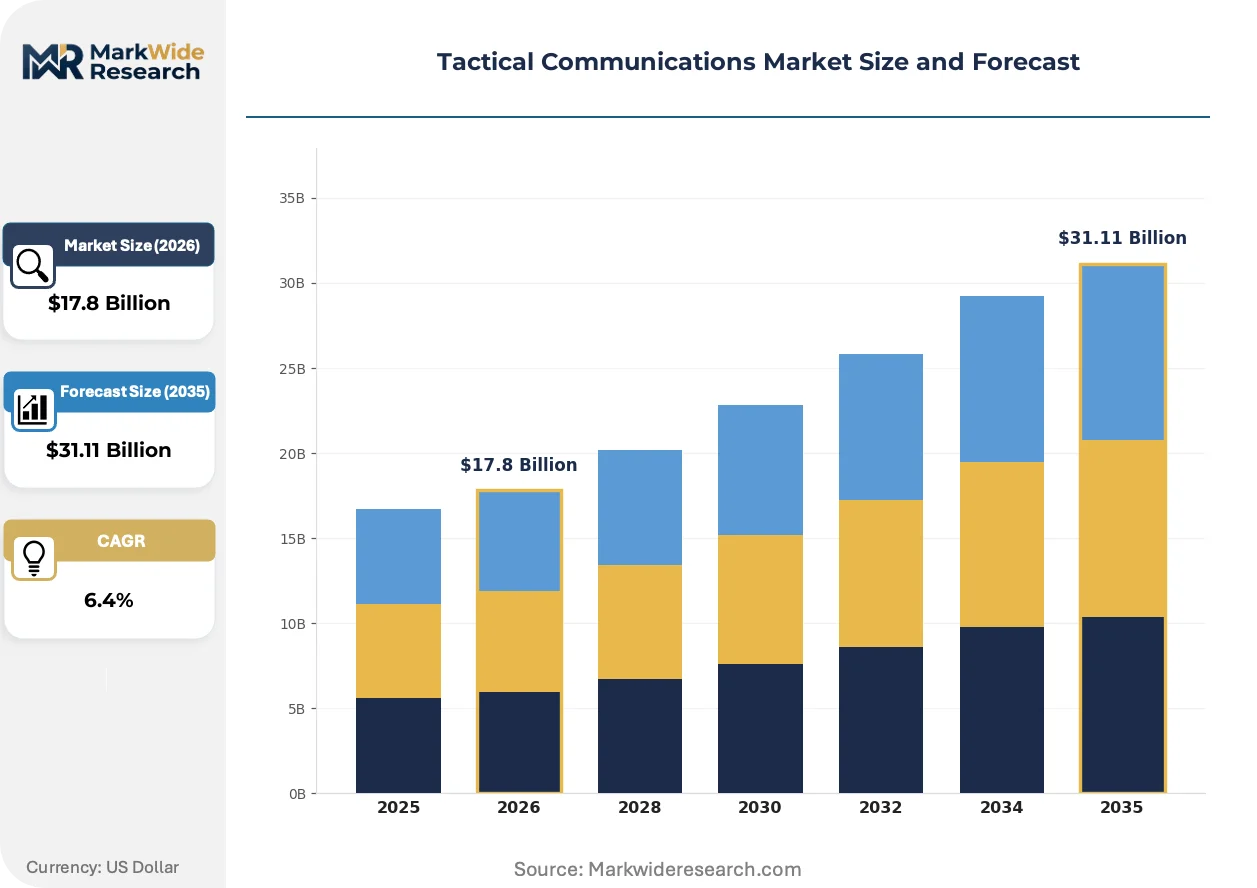
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radios, Intercoms, Network Equipment, Antennas End User: Military, Law Enforcement, Emergency Services, Security Firms Technology: Satellite Communication, Radio Frequency, Wireless Networks, Fiber Optics Application: Field Operations, Command Centers, Disaster Response, Training Exercises |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, L3Harris Technologies, Elbit Systems, BAE Systems, Thales Group, General Dynamics Corporation, Collins Aerospace, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical Communications Market Emerging Trajectories
Three converging forces are restructuring how tactical networks are architected, procured, and fielded: waveform virtualization, cryptographic standard evolution, and consolidated platform integration.
Cognitive radio systems with artificial intelligence-enabled spectrum sensing are decentralizing frequency management authority from centralized command nodes to individual radio units. Dismounted infantry units in urban warfare training exercises adopt these systems fastest, as autonomous interference avoidance proves decisive in dense electromagnetic clutter. Equipment procurement specifications now explicitly reward decentralized spectrum coordination capabilities over raw transmit power.
The European Union's Radio Spectrum Committee and U.S. National Telecommunications and Information Administration are accelerating millimeter-wave band reallocation for defense use. This regulatory convergence compresses available spectrum for legacy VHF/UHF equipment while mandating faster adoption of higher-frequency alternatives. NATO procurement offices have responded by inserting waveform-flexibility requirements into all new radio solicitations.
Defense ministries are consolidating previously separate radio, satellite terminal, and network management procurements into single-vendor platform awards. System integrators now capture multi-year service contracts spanning hardware, waveform software, and network operations, displacing discrete equipment purchases. This bundling pattern appears most pronounced in U.S. Army and British Army vehicle modernization programs.
Tactical Communications Market Segmentation
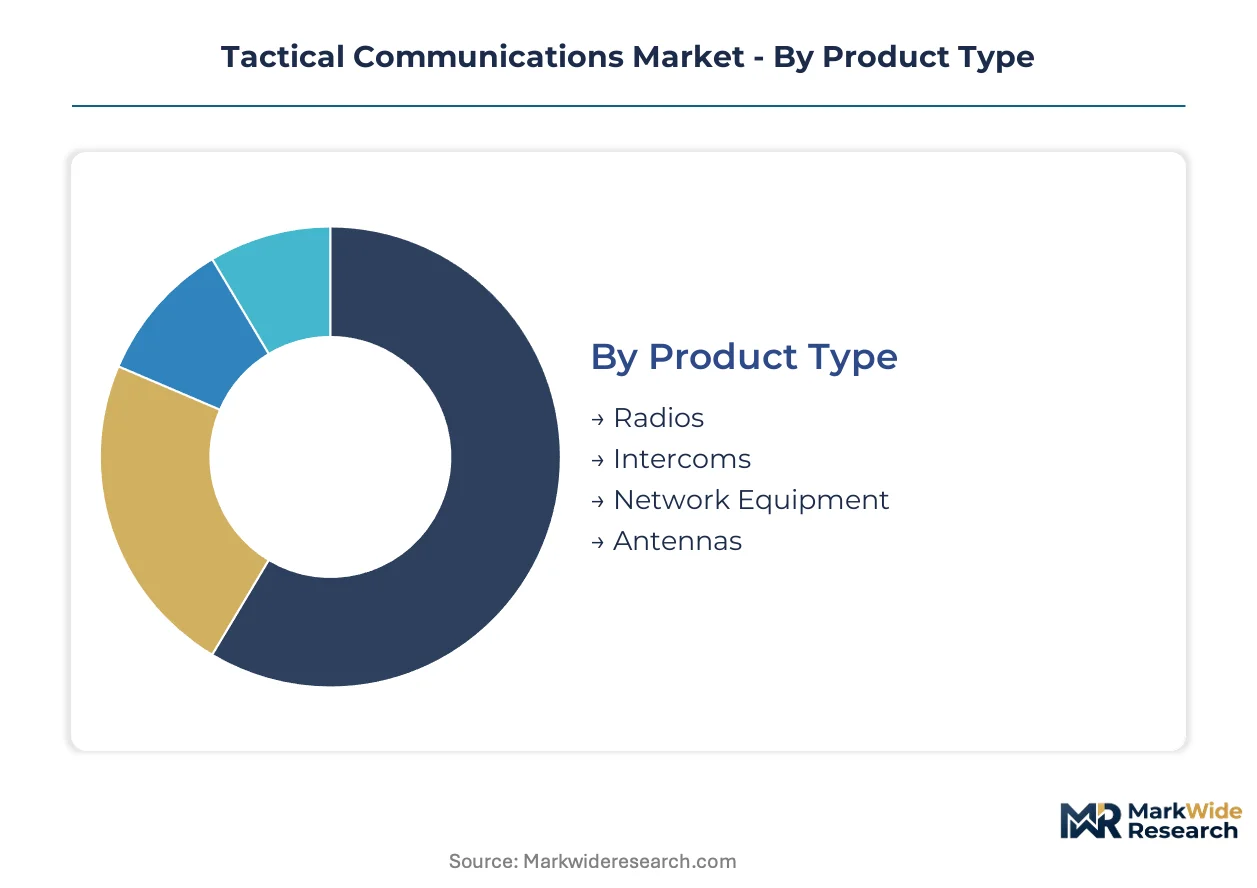
Tactical communications procurement splits across equipment categories, user communities, and transmission technologies. Each axis reveals distinct specification requirements, certification barriers, and replacement cycles that shape vendor positioning.
Product Type:
Equipment differentiation tracks platform mobility and environmental hardening requirements.
- Radios:Software-defined architectures now dominate man-portable and vehicular procurement, with waveform reprogrammability replacing fixed-frequency hardware. Demand concentrates in U.S. Army dismounted soldier programs and NATO vehicle modernization, driven by contested spectrum mandates requiring frequency-hopping agility.
- Network Equipment:Mesh-enabled routers and gateways form the backbone of self-healing command networks, eliminating single points of failure in distributed operations. Procurement is accelerating in British Army and Australian Defence Force vehicle platforms, compelled by interoperability requirements for coalition network integration.
- Intercoms:Vehicle-integrated audio distribution systems with noise cancellation for armored platforms.
- Antennas:Multi-band conformal arrays for low-observable mounting on aircraft and maritime vessels.
Mature deployment sits with radios. Newer deployment is concentrated in network equipment.
End User:
Customer segmentation reflects threat environment severity and procurement budget scale.
- Military:Dominates absolute spending volume, with classified encryption tiers and anti-jam specifications inaccessible to other segments. Procurement timelines stretch across multi-year programs in the United States, United Kingdom, and Germany, constrained by MIL-STD-188 interoperability certification and NIST cryptographic validation.
- Law Enforcement:Swat and tactical response units drive encrypted narrowband voice demand, with lighter environmental specifications than military equivalents. Adoption clusters in U.S. metropolitan police departments and French Gendarmerie units, pressured by encrypted interoperability mandates with federal emergency response networks.
- Emergency Services:Fire and medical first responders require push-to-talk reliability in structural collapse and wildfire conditions.
- Security Firms:Private sector guarding and critical infrastructure protection operates on commercial spectrum with less stringent hardening.
Volume leadership rests with military end users. Fastest expansion is occurring in law enforcement.
Technology:
Transmission modality selection depends on range requirements, spectrum availability, and physical concealment needs.
- Satellite Communication:Beyond-line-of-sight terminals for dismounted units in denied-area operations command premium pricing due to proprietary waveform development and space segment leasing costs. Demand is hardening in U.S. Special Operations Command and Israeli Defense Forces procurement, driven by GPS-denied navigation requirements and anti-jam link resilience.
- Radio Frequency:VHF and UHF bands remain ubiquitous for line-of-sight tactical links, though millimeter-wave migration is compressing available spectrum for legacy equipment. Deployment concentrates in NATO ground maneuver formations and Japanese Ground Self-Defense Force units, facing regulatory pressure from civilian spectrum reallocation.
- Wireless Networks:Mobile ad-hoc networking protocols enable data-intensive situational awareness without fixed infrastructure.
- Fiber Optics:Secure fixed-site and vehicle-vehicle tethered links for electromagnetic pulse-hardened command posts.
Radio frequency maintains installed base dominance. Steepest expansion trajectory belongs to satellite communication.
Application:
Use case segmentation determines mobility, power, and network architecture specifications.
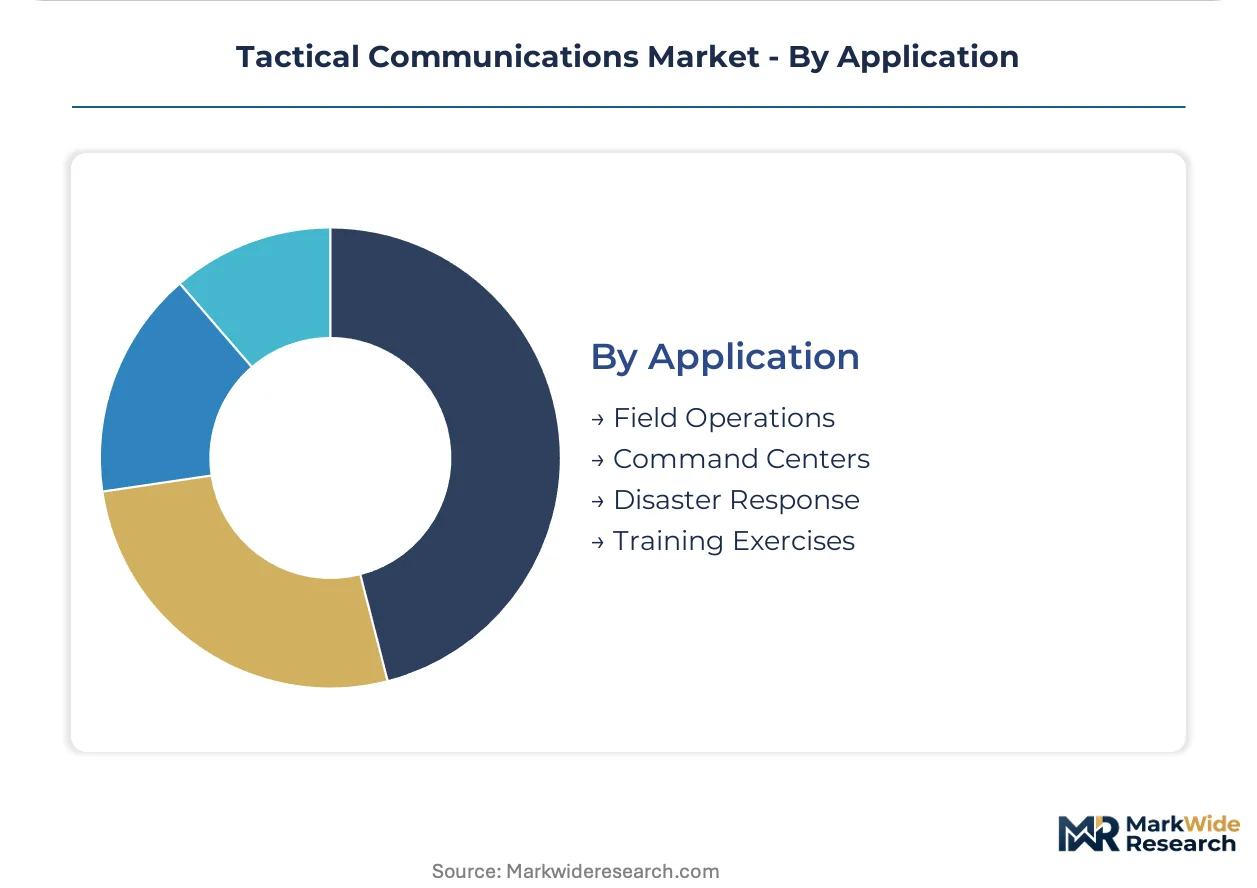
- Field Operations:Dismounted soldier and vehicle-mounted communications in active combat zones demand the most severe environmental hardening and lowest probability of intercept. Procurement prioritization sits with U.S. Marine Corps expeditionary units and Polish Territorial Defence Forces, responding to forward-deployment doctrines requiring austere infrastructure independence.
- Command Centers:Fixed and semi-fixed headquarters integration emphasizes network management software and multi-source data fusion. Investment is concentrating in Pentagon Joint Staff facilities and NATO Supreme Headquarters, driven by multi-domain operations coordination requirements spanning air, maritime, space, and cyber.
- Disaster Response:Interoperable cross-agency communications for hurricane, earthquake, and pandemic scenarios.
- Training Exercises:Instrumented ranges with after-action review data capture and simulated electronic warfare environments.
Established deployment centers on field operations. Emerging investment flows to command centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of tactical communications hardware concentrates in defense industrial bases with mature RF engineering ecosystems, while consumption patterns track military procurement budgets and alliance interoperability mandates. The United States anchors both supply and demand through Pentagon modernization programs. European NATO members import core technologies but field substantial integration capabilities.
United States
Pentagon spending on resilient command-and-control infrastructure outpaces other national markets, driven by contested spectrum operations in the Indo-Pacific. FCC regulations and NIST cryptographic standards shape procurement timelines for encrypted networks. Defense contractors cluster around Washington DC metro, Huntsville, and San Diego, where software-defined radio development accelerates.
Germany
Bundeswehr vehicle modernization programs propel demand for mesh-enabled vehicular platforms and soldier systems. KBA and BAAINBw procurement offices enforce Bundeswehr Technical Delivery Terms that mandate interoperability with NATO allies. Industrial activity concentrates in Bavaria and Baden-Württemberg, where system integrators adapt commercial automotive RF expertise for military applications.
United Kingdom
British Army vehicle platform awards consolidate radio, satellite terminal, and network management into single-vendor contracts. Ministry of Defence procurement specifications align with NATO Standardization Office interoperability mandates. Defense electronics engineering clusters in Bristol, Portsmouth, and Farnborough support integrated soldier system development.
Israel
Israel Defense Forces procurement prioritizes anti-jam waveforms and GPS-denied navigation for denied-area operations. Israeli Ministry of Defense dual-use export regulations govern technology transfer to allied militaries. Tel Aviv and Haifa host vertically integrated suppliers spanning radios, terminals, and network management software.
Australia
Australian Defence Force vehicle platforms accelerate procurement of coalition-interoperable mesh networks for Indo-Pacific expeditionary requirements. Defence Trade Controls Act regulations constrain cross-border technology flows with AUKUS partners. Melbourne and Adelaide defense precincts concentrate integration activity for regional satellite communication terminals.
Tactical Communications Market Vendor Landscape
Top-tier vendors anchor prime contractor positions on multi-year platform awards, while mid-tier specialists capture subsystem and waveform software niches. The vendor base stratifies across integrated system houses, RF component specialists, and software-defined waveform developers. Two dominant competitive moves define current positioning: consolidation of previously separate radio and network equipment procurements into bundled platform awards, and backward integration into captive semiconductor fabrication for security-critical components.
Within the integrated system house tier, L3Harris Technologies and Thales Group exemplify vendors capturing multi-year service contracts spanning hardware, waveform software, and network operations. Elbit Systems occupies a position representing vertically integrated suppliers with in-house production across the full communications stack. These three anchors illustrate how defense procurement consolidation favors vendors with breadth across radios, terminals, and network management rather than discrete equipment specialists.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Elbit Systems |
| BAE Systems |
| Thales Group |
| General Dynamics Corporation |
| Collins Aerospace |
| RTX Corporation |
| Others |
Supply Flow & Price Mechanics
Pentagon program offices and NATO procurement agencies concentrate buying power through multi-year platform awards, anchoring contract-based long-term offtake as the dominant pricing structure across software-defined radio and network equipment categories.
Pricing Analysis
Margin tightening in military-grade hardware reflects semiconductor foundry concentration in East Asian supply zones and multi-year certification timelines that lock in cost structures. Three-tier pricing structure across strategic-tier, tactical-tier, and commercial-adjacent levels separates MIL-STD-188 certified platforms from NATO interoperability-grade systems and dual-use variants. Cost-down pressure on radio frequency components accelerates as software-defined architectures displace fixed-waveform hardware. Law enforcement agencies exhibit highest price sensitivity due to municipal budget constraints, while U.S. Special Operations Command procurement shows lowest sensitivity given mission-critical reliability requirements.
Supply Chain Analysis
RF engineering talent pools thinly across Huntsville, San Diego, and Tel Aviv defense clusters, constraining capacity expansion for microwave and antenna design functions. Advanced RF component fabrication draws from Taiwan, South Korea, and select U.S. foundries, with gallium nitride substrates and millimeter-wave semiconductors feeding from specialized East Asian suppliers. Single-source vulnerability concentrates in space-segment leasing for beyond-line-of-sight satellite terminals. Distribution runs through prime contractor direct sales to defense ministries, supplemented by system integrator channel partners for allied nation procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized microwave engineering expertise functions as the binding capacity constraint, propping pricing power for vendors with captive RF design talent.
For Market Incumbents: Hedge against software-defined commoditization by deepening in-house production of security-critical semiconductors and capturing multi-year service contracts spanning waveform software updates. Threat substitution from commercial telecom entrants with cognitive radio expertise demands accelerated NIST post-quantum cryptographic certification investment to maintain qualification barriers. For New Entrants and Emerging Players: Allied nation vehicle modernization programs represent the most penetrable buyer archetype, as British Army and Australian Defence Force procurement explicitly rewards coalition-interoperable mesh networking capabilities over incumbent brand recognition. Target law enforcement encrypted narrowband voice segments through lighter environmental specifications and faster certification timelines than military-grade alternatives. Go-to-market execution should anchor on channel partnerships with regional system integrators holding existing defense ministry relationships. For Investors and Strategic Acquirers: The window for entry favors waveform software specialists with NIST cryptographic validation and NATO Standardization Office interoperability credentials. Long-term viability hinges on quantum-resistant encryption transition mandates and dynamic spectrum access technology maturation. Signal to monitor: FCC and EU Radio Spectrum Committee millimeter-wave reallocation decisions that compress legacy VHF/UHF equipment addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Waveform Software Acquisition | Captures recurring revenue streams from Pentagon software-defined radio modernization programs. |
| RF Component Foundry Investment | Secures gallium nitride supply chain against Taiwan Strait geopolitical disruption scenarios. |
| NIST Post-Quantum Certification | Positions hardware refresh capture as quantum-resistant encryption mandates activate. |
| Coalition Interoperability Partnership | Unlocks British Army and Australian Defence Force vehicle platform bundling opportunities. |
| Dynamic Spectrum Access Development | Enables military-civilian band sharing revenue under FCC emergency spectrum provisions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across program managers at Pentagon acquisition offices, RF engineering directors at prime contractors, NATO Standardization Office interoperability specialists, and procurement leads at Bundeswehr and British Army. Defense contract award databases, FCC equipment authorization filings, NIST cryptographic validation records, and EU dual-use export control registries supplied quantitative foundations. Bottom-up equipment shipment analysis and top-down defense budget allocation modeling cross-validated volume estimates.
Segment-level granularity modeled product type across radios, network equipment, intercoms, and antennas; end user across military, law enforcement, emergency services, and security firms; technology across satellite communication, radio frequency, wireless networks, and fiber optics; and application across field operations, command centers, disaster response, and training exercises. CAGRs derived from regression analysis against defense modernization spending trajectories and spectrum reallocation timelines. Forecast inputs incorporated software-defined radio adoption curves and quantum-resistant encryption hardware replacement cycles.
Revisions become necessary when semiconductor supply concentration triggers materialize, NATO interoperability mandates shift, or quantum-resistant encryption standards accelerate. Forecasts reflect documented assumptions regarding defense budget continuity and regulatory certification timelines. Material deviation in Pentagon program delays, East Asian foundry disruption, or NIST cryptographic standard finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market