
 Asia-Pacific Defense Market | 2026-2036
Asia-Pacific Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Defense Market Outlook
Buyer concentration across Asia-Pacific defense procurement is broadening as middle-power militaries fragment historically dominant national budgets. Lockheed Martin leverages its F-35 regional partnership network to sustain long-term maintenance revenue across multiple air forces. Mitsubishi Heavy Industries anchors Japan's fighter jet development pipeline while competing for naval export contracts in Southeast Asia. Bharat Dynamics Limited specializes in tactical missile systems and occupies India's growing indigenous procurement channel.
Asia-Pacific defense encompasses integrated military capability spanning kinetic platforms, electronic warfare architectures, and cyber-physical security systems designed for territorial deterrence and power projection across maritime and littoral environments. Airborne systems command the largest current allocation as fifth-generation fighter programs absorb multi-year development budgets across Japan, South Korea, and Australia. AI Systems within the technology dimension represent the fastest-expanding segment, with autonomous targeting and predictive maintenance applications reshaping operational tempo requirements. Cybersecurity Solutions sit at the margin-intensive intersection of civilian critical infrastructure and military command networks, creating dual-use pricing power for specialized vendors.
Japan's Ministry of Economy, Trade and Industry (METI) coordinates defense industrial base policy alongside export control frameworks that restrict sensitive technology transfer. Australia's Defense Trade Controls Act intersects with AUKUS governance mechanisms, creating layered compliance obligations for contractors operating across three national jurisdictions. India's Defence Acquisition Procedure under the Ministry of Defence mandates progressive indigenization thresholds that redirect foreign OEMs toward joint venture structures. Stakeholders must monitor how overlapping technology security regimes reshape supplier eligibility and contract award criteria without explicit harmonization timelines.
Market Dynamics
Naval modernization programs across Southeast Asian fleets are fragmenting procurement authority from traditional single-source national budgets toward distributed acquisition frameworks that accelerate submarine and frigate deployment timelines.
Growth Catalysts
- Indigenous Manufacturing Mandates:India's Defence Acquisition Procedure mandates progressive indigenization thresholds that redirect foreign OEMs toward joint venture structures with domestic partners.
- Submarine Technology Transfer:Australia's AUKUS partnership with the United States and United Kingdom is reshaping nuclear propulsion governance rules and creating new maintenance revenue pools across three national jurisdictions.
- AI Systems Integration:Autonomous targeting and predictive maintenance applications within military platforms are compressing operational tempo requirements and expanding addressable system budgets.
Market Restraints
- Export Control Layering:Australia's Defense Trade Controls Act intersects with AUKUS governance mechanisms, creating compliance cost inflation for contractors operating across multiple regulatory jurisdictions.
- Technology Security Fragmentation:Overlapping national technology security regimes across Japan, Australia, and India reshape supplier eligibility without explicit harmonization timelines, extending contract award cycles.
- Specialized Component Scarcity:Nuclear propulsion system components face concentrated supply from limited qualified vendors, creating bottleneck risk for submarine construction programs.
Strategic Opportunities
- Missile System Localization:India's defense manufacturing corridor stretching from Hyderabad to Pune offers joint venture entry points for tactical missile system production with rising capital allocation absorption.
- Naval Export Contracts:Mitsubishi Heavy Industries anchors Japan's fighter development pipeline while competing for frigate and submarine export opportunities across Indonesia, Vietnam, and the Philippines.
- Cyber-Physical Convergence:Dual-use pricing power emerges at the intersection of civilian critical infrastructure and military command networks for specialized cybersecurity vendors serving both domains.
Industry Challenges
- Multi-Jurisdictional Compliance Architecture:Contractors must maintain parallel certification pathways across Japan's METI export frameworks, Australia's Defense Trade Controls Act, and India's Defence Acquisition Procedure without unified standards.
- Nuclear Propulsion Workforce Gap:AUKUS submarine programs require specialized reactor technicians and engineers that current training pipelines cannot supply at required scale or velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Defense Market |
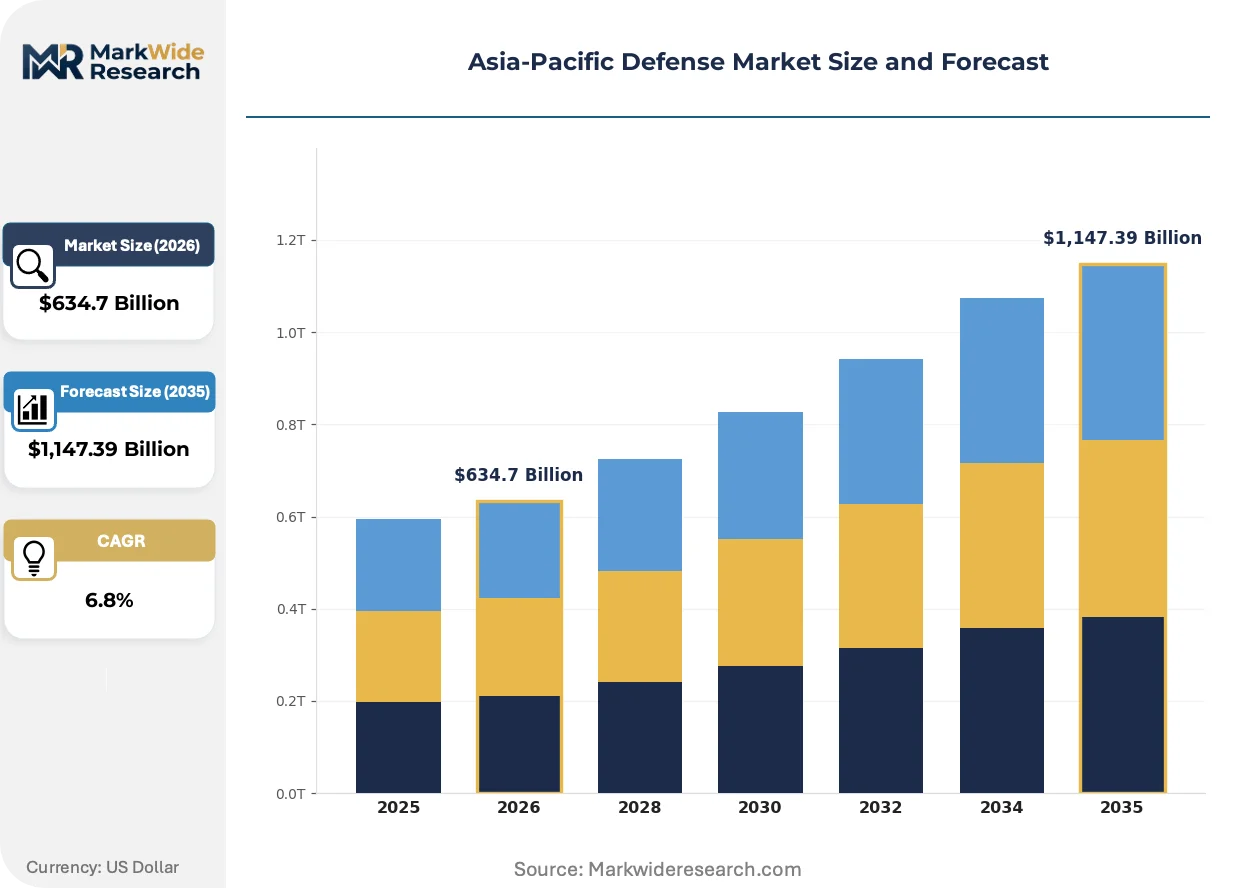
| Market Size in 2026 | $634.7 Billion |
| Market Size in 2035 | $1,147.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Systems, Airborne Systems, Naval Systems, Cybersecurity Solutions Application: National Security, Border Protection, Counter-terrorism, Disaster Relief End User: Government Agencies, Defense Contractors, Armed Forces, Private Security Firms Technology: AI Systems, Drones, Simulation Tools, Communication Tech |
| Companies Covered | The Boeing Company, LIG Nex1, Lockheed Martin, L3Harris Technologies, Bharat Dynamics Limited, RTX Corporation, Mitsubishi Heavy Industries Ltd., MBDA, Northrop Grumman, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Defense Market Strategic Shifts
Electronic warfare architectures are converging with autonomous platform networks to create distributed kill chains that compress sensor-to-shooter timelines across maritime theaters.
Hypersonic glide vehicle technology is unifying ballistic and cruise missile trajectories into maneuverable delivery systems that defeat traditional interceptor geometries. Japan's Ministry of Defense accelerates testing schedules for counter-hypersonic interceptors. Regional air forces are reallocating procurement budgets toward integrated air-and-missile defense architectures that absorb these unified threat profiles.
Japan's METI coordinates defense industrial base policy alongside export control frameworks that restrict sensitive technology transfer to approved partner nations. This regulatory architecture forces foreign suppliers into joint development structures with Japanese primes rather than direct sales. Southeast Asian navies face extended delivery timelines as they navigate these layered approval mechanisms for submarine combat systems.
Fifth-generation fighter maintenance contracts are unbundling from original platform procurement, creating standalone revenue streams that Lockheed Martin leverages across multiple regional air forces. Royal Australian Air Force F-35 sustainment agreements establish template pricing that Republic of Korea Air Force and Japan Air Self-Defense Force programs reference. Long-term availability-based contracts displace traditional spare-part transactional purchasing in fleet management.
Asia-Pacific Defense Market Segmentation
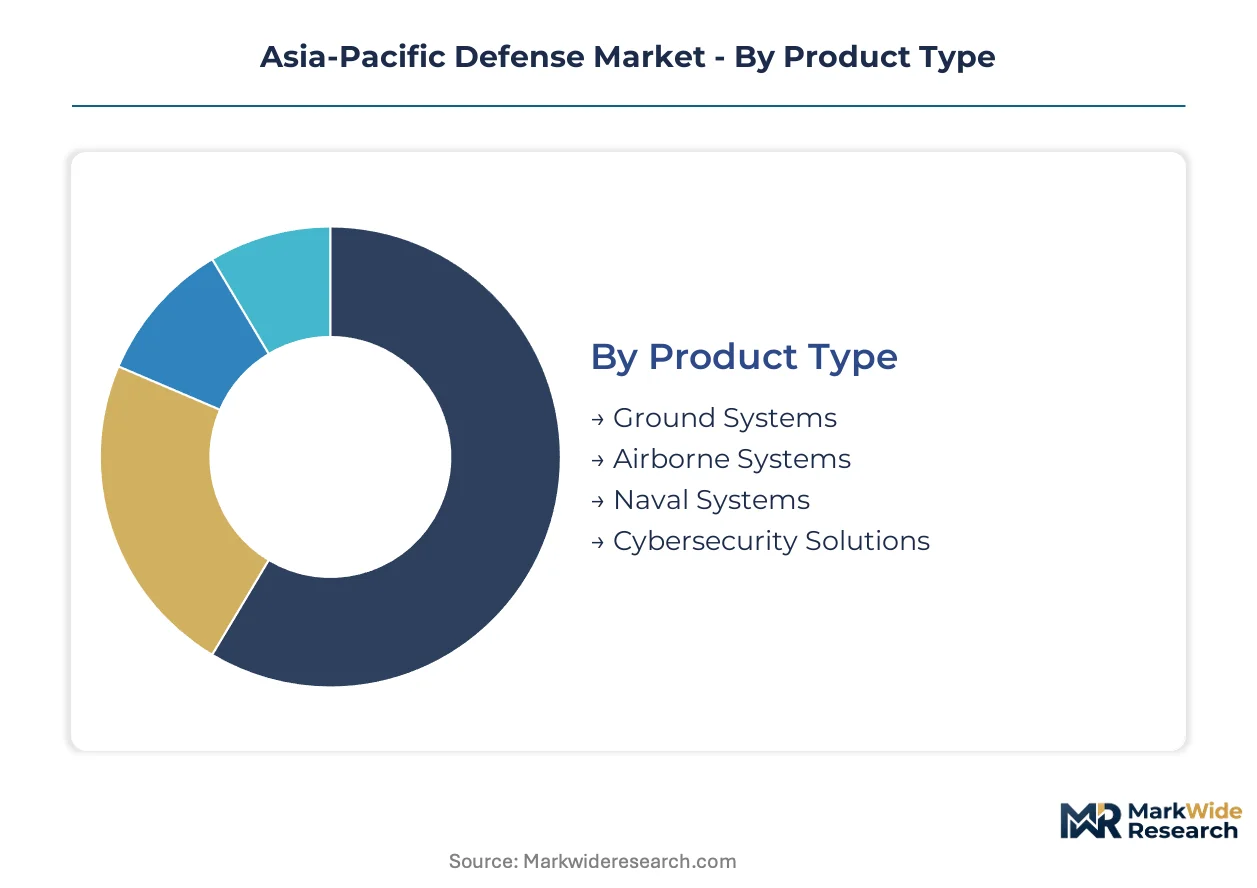
Defense procurement across Asia-Pacific fragments along capability tiers rather than uniform specifications, with each segment demanding distinct compliance architectures and partnership structures. Customization depth determines contract profitability, as indigenous manufacturing mandates reshape supplier eligibility from Australia to India.
Product Type:
Standardization dominates export-ready platforms while domestic programs absorb heavy engineering customization across this spectrum.
- Airborne Systems:Fifth-generation fighter platforms and integrated air-and-missile defense architectures absorb multi-year development budgets across Japan, South Korea, and Australia. Royal Australian Air Force F-35 sustainment agreements establish template pricing that regional air forces reference for long-term availability contracts.
- Naval Systems:Submarine combat systems and surface combatants face extended delivery timelines as Southeast Asian navies navigate layered Japanese METI approval mechanisms. Australia's AUKUS partnership creates trilateral nuclear propulsion governance that fragments traditional single-source procurement authority.
- Ground Systems:Armored vehicle modernization programs concentrate in India's indigenous manufacturing corridor from Hyderabad to Pune.
- Cybersecurity Solutions:Dual-use platforms serving civilian critical infrastructure and military command networks generate margin-intensive pricing power for specialized vendors.
Leading the category by volume: Airborne Systems. Expanding most quickly: Cybersecurity Solutions.
Application:
Cost tier stratification separates sovereign capability investments from coalition-funded interoperability programs.
- National Security:Territorial deterrence and power projection capabilities command priority capital allocation across maritime and littoral environments. India's Defence Acquisition Procedure mandates progressive indigenization thresholds that redirect foreign OEMs toward joint venture structures.
- Border Protection:Sensor networks and unmanned surveillance platforms absorb rising procurement budgets along contested maritime boundaries.
- Counter-terrorism:Special operations equipment and intelligence fusion systems face fragmented demand across multiple national procurement frameworks.
- Disaster Relief:Dual-use airlift and naval logistics vessels create procurement efficiencies through shared civilian-military utilization models.
Highest budget concentration: National Security. Steepest expansion trajectory: Border Protection.
End User:
Customer type determines contract structure, with government direct procurement favoring local content while contractor channels enable technology transfer.
- Armed Forces:Operational tempo requirements drive predictive maintenance applications and autonomous targeting system integration across regional militaries. Long-term availability-based contracts displace traditional spare-part transactional purchasing in fleet management.
- Government Agencies:Defense industrial base policy coordination through Japan's METI restricts sensitive technology transfer to approved partner nations.
- Defense Contractors:Multi-jurisdictional compliance obligations span Australia's Defense Trade Controls Act, Japanese export frameworks, and Indian procurement procedures.
- Private Security Firms:Peripheral demand concentrates in maritime protection and critical infrastructure guarding services.
Dominant procurement volume: Armed Forces. Gaining share fastest: Defense Contractors.
Technology:
Maturity gradient separates field-proven platforms from experimental systems requiring extensive certification pathways.
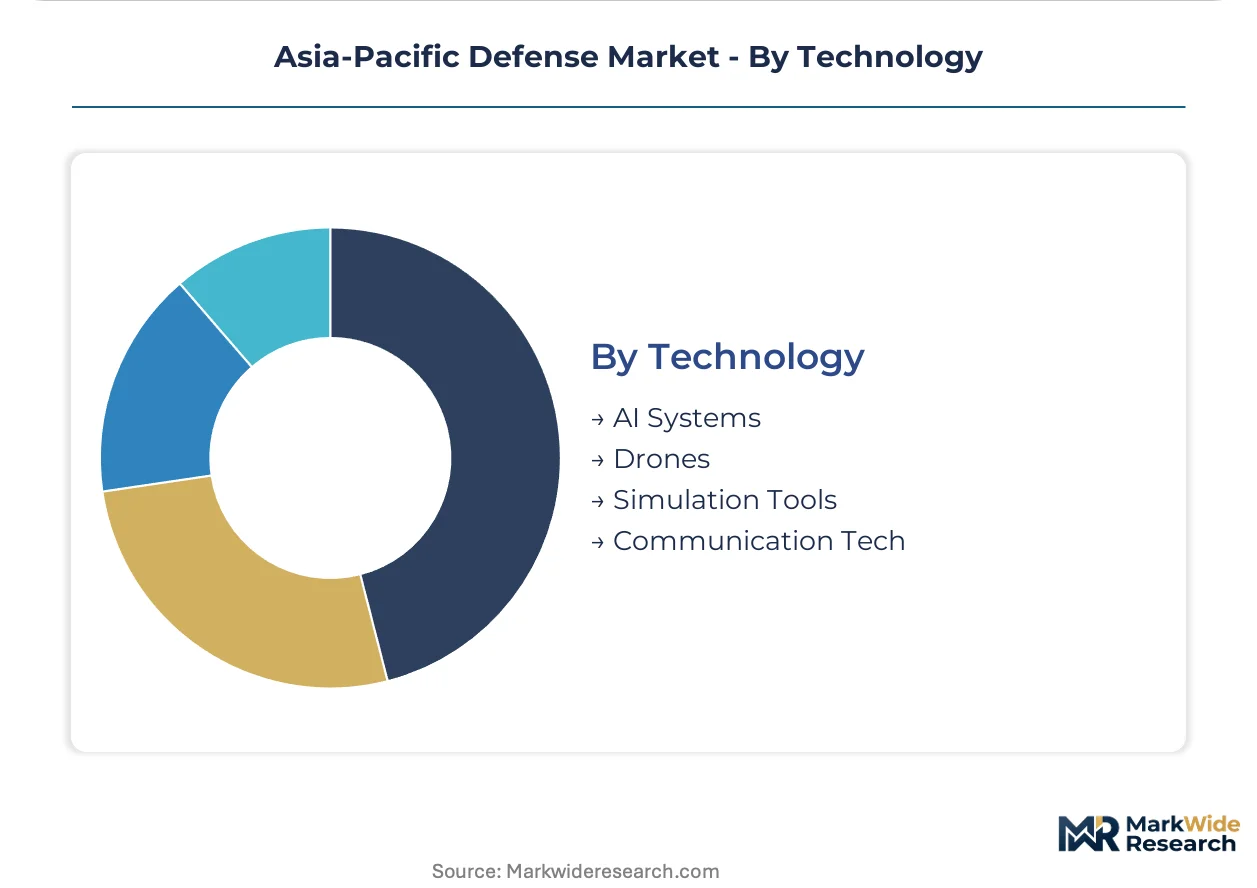
- AI Systems:Autonomous targeting and predictive maintenance applications compress operational tempo requirements while expanding addressable system budgets. This segment climbs the fastest as military platforms integrate machine learning for sensor-to-shooter timeline reduction.
- Drones:Unmanned platforms span tactical reconnaissance through loyal wingman fighter concepts across regional development programs.
- Communication Tech:Secure network architectures face supply concentration from qualified vendors meeting trilateral AUKUS interoperability standards.
- Simulation Tools:Training system procurement lags platform acquisition cycles, creating deferred revenue recognition for specialized providers.
Widest deployment base: Communication Tech. Steepest technology investment slope: AI Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing facilities in Jiangxi Province and Inner Mongolia supply critical magnet materials for precision-guided munitions and radar systems across regional defense supply chains.
Australia
The AUKUS nuclear submarine program drives specialized workforce development and reactor technician training pipelines. Australia's Defense Trade Controls Act intersects with trilateral governance mechanisms, creating layered compliance frameworks for contractors. Western Australia's HMAS Stirling naval base anchors submarine maintenance infrastructure expansion.
Japan
Counter-hypersonic interceptor development absorbs priority funding within integrated air-and-missile defense modernization. Japan's METI coordinates defense industrial base policy alongside export control frameworks that restrict sensitive technology transfer. Mitsubishi Heavy Industries in Nagoya anchors fighter jet development while competing for Southeast Asian naval export contracts.
India
Indigenous missile system production concentrates capital allocation within the Hyderabad-Pune manufacturing corridor. India's Defence Acquisition Procedure mandates progressive indigenization thresholds that redirect foreign OEMs toward joint venture structures. Bharat Dynamics Limited specializes in tactical missile platforms within this domestic procurement channel.
South Korea
Fifth-generation fighter development programs and loyal wingman unmanned concepts absorb multi-year R&D budgets. The Defense Acquisition Program Administration coordinates procurement frameworks that balance indigenous capability with technology transfer agreements. Seoul's defense industrial cluster houses KF-21 development facilities and associated subsystem suppliers.
Vietnam
Submarine combat system procurement from Russian and European sources diversifies fleet capabilities amid South China Sea tensions. The Ministry of National Defense navigates layered approval mechanisms for sensitive technology imports. Cam Ranh Bay anchors naval modernization infrastructure supporting Kilo-class submarine operations.
Asia-Pacific Defense Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue autonomous systems and cyber-physical convergence opportunities. The market structures around three distinct player categories: integrated primes with multi-domain portfolios, national champions serving domestic procurement mandates, and specialized subsystem vendors. Competitive positioning hinges on technology licensing agreements and joint venture formations rather than pure export sales. M&A activity concentrates on cybersecurity and AI-enabled targeting capabilities; strategic partnerships dominate platform development programs.
Among American defense primes, Lockheed Martin and L3Harris Technologies exemplify contrasting archetypes within the regional ecosystem. Lockheed Martin represents the integrated platform model through F-35 sustainment networks that generate recurring revenue across multiple regional air forces. L3Harris Technologies occupies a position emphasizing electronic warfare and communications architectures that bridge civilian and military applications. Mitsubishi Heavy Industries anchors the national champion category, balancing domestic fighter development with selective naval export pursuit. Bharat Dynamics Limited exemplifies the indigenous manufacturing mandate model, operating within India's joint venture structures for tactical missile production.
| Leading Market Players |
|---|
| The Boeing Company |
| LIG Nex1 |
| Lockheed Martin |
| L3Harris Technologies |
| Bharat Dynamics Limited |
| RTX Corporation |
| Mitsubishi Heavy Industries Ltd. |
| MBDA |
| Northrop Grumman |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet materials from Jiangxi Province and Inner Mongolia flow downstream through three distinct pricing tiers determined by end-use certification levels and indigenous content thresholds. India's Defence Acquisition Procedure mandates reshape procurement economics by forcing foreign OEMs into joint venture structures that absorb margin compression through technology transfer obligations.
Pricing Analysis
Warranty and long-term availability contracts unbundle from original platform procurement across regional air forces, creating standalone sustainment revenue streams that Lockheed Martin leverages through F-35 maintenance networks. Three-tier pricing structure across premium, standard, and economy levels separates nuclear propulsion system components from conventional submarine combat suites and dual-use cybersecurity platforms. Cost compression in Southeast Asian naval programs intensifies because layered Japanese METI approval mechanisms extend delivery timelines without corresponding budget expansion. Defense contractors operating across multiple regulatory jurisdictions face highest price sensitivity, while sovereign capability investments in India and Australia absorb premium pricing for indigenized production.
Supply Chain Analysis
India's progressive indigenization thresholds redirect component sourcing toward domestic joint venture structures, fragmenting traditional single-source procurement channels. Rare earth processing concentrates in China, precision guidance system manufacturing anchors in Japan, and submarine combat system integration centers in South Korea. Critical inputs span high-grade samarium-cobalt magnets, gallium nitride semiconductors, and specialized reactor-grade steel alloys. Single-source vulnerability concentrates in nuclear propulsion components supplied by limited qualified vendors. Distribution runs through government direct procurement channels that favor local content, with contractor-mediated technology transfer enabling alternative pathways for specialized subsystem vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into upstream rare earth processing and downstream maintenance infrastructure represents the decisive competitive lever across Asia-Pacific defense procurement. Players securing captive magnet supply and long-term availability contract templates will capture margin pools unavailable to transactional competitors.
For Market Incumbents: Hedge against technology security fragmentation by maintaining parallel certification pathways across Japanese METI export frameworks, Australian Defense Trade Controls Act compliance architectures, and Indian Defence Acquisition Procedure mandates. Pursue backward integration into AI-enabled targeting subsystems to defend margin position against emerging autonomous platform specialists. Lockheed Martin's F-35 sustainment network model offers template for recurring revenue capture across multiple regional air forces. For New Entrants and Emerging Players: Begin with cyber-physical convergence opportunities at the intersection of civilian critical infrastructure and military command networks, where dual-use pricing power remains underexploited by established primes. India's Hyderabad-Pune defense manufacturing corridor offers most penetrable geography for tactical missile system joint ventures under indigenous procurement mandates. Go-to-market positioning should emphasize rapid certification pathway navigation rather than platform scale. For Investors and Strategic Acquirers: AUKUS submarine program workforce development announcements are the leading indicator that nuclear propulsion maintenance infrastructure will consolidate around specialized technical training pipelines. Long-term viability over the coming decade rests on exposure to trilateral governance mechanisms rather than bilateral defense trade relationships. Acquisition targets should display proven navigation of multi-jurisdictional compliance obligations. Watch for India's Defence Acquisition Procedure threshold adjustments as signal for joint venture structure preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Localization | India's Defence Acquisition Procedure mandates redirect foreign OEMs toward domestic partnership structures for missile production. |
| Long-Term Availability Contracting | Royal Australian Air Force F-35 sustainment agreements establish template pricing referenced by Japan and South Korea. |
| AI Systems Integration | Autonomous targeting applications compress sensor-to-shooter timelines across maritime theaters for regional militaries. |
| Multi-Jurisdictional Compliance Architecture | Contractors operating across AUKUS governance mechanisms absorb layered certification costs unavailable to single-market competitors. |
| Cyber-Physical Convergence Development | Dual-use platforms serving civilian critical infrastructure generate margin-intensive pricing power for specialized vendors. |
Study Parameters
Document review covered defense procurement databases, national budget appropriations records, and technology transfer agreement filings, complemented by interviews with program managers at India's Defence Research and Development Organisation, procurement officers within Japan's Ministry of Defense, submarine reactor engineers at Australian naval facilities, and compliance directors navigating AUKUS governance frameworks. Secondary validation drew from parliamentary defense committee reports, national export control registry disclosures, and submarine construction milestone announcements. Bottom-up platform deployment tallies and top-down defense expenditure aggregates were triangulated against joint venture formation records.
Segment-level value outputs were derived through capability-tier stratification across airborne, naval, ground, and cyber system categories, with technology maturity gradients separating field-proven platforms from experimental architectures requiring extensive certification pathways. CAGRs were computed from deployment timeline compressions and indigenous manufacturing mandate acceleration effects. Industry-specific forecast inputs incorporated AUKUS nuclear propulsion workforce pipeline development rates and India's progressive indigenization threshold implementation schedules across the analysis window.
Underlying measurement precision varies by segment; airborne system procurement with established F-35 sustainment templates carries tighter precision than experimental counter-hypersonic interceptor development programs. Forecasts reflect assumptions regarding technology security regime stability and trilateral governance mechanism durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Ballistics Targeting Software Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
Military Computers Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Vehicle Cybersecurity Market