
 Asia-Pacific Missiles and Missile Defense Systems Market | 2026-2036
Asia-Pacific Missiles and Missile Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Missiles and Missile Defense Systems Market Outlook
Multi-source contracting for propulsion subsystems and seeker arrays is hardening across prime contractors in the Asia-Pacific. China Aerospace Science and Industry Corporation leverages state-backed vertical integration to dominate domestic supply chains for solid-fuel motors. Mitsubishi Heavy Industries anchors Japan's layered defense architecture through concentrated R&D on interceptor kill vehicles. LIG Nex1 competes aggressively in export-oriented tactical missile segments, particularly precision strike systems for Southeast Asian buyers.
Missiles and missile defense systems encompass guided and unguided weapon platforms, interceptor batteries, and integrated launch infrastructure designed for kinetic engagement or area denial at ranges from several kilometers to intercontinental arcs; propulsion typically relies on solid or liquid rocket motors, with terminal guidance employing radar, infrared, or electro-optical seekers calibrated for precision engagement against maneuvering or ballistic threats. Air defense systems and cruise missiles capture disproportionate investment flows as regional navies and air forces prioritize layered area denial and standoff strike capability. Interceptor systems within the technology dimension are attracting concentrated engineering talent as hypersonic glide vehicles compress engagement timelines. Military end users remain the dominant demand pool, though defense contractors absorb escalating subsystem integration complexity under government offset programs.
Australia's Defence Trade Controls Act, Japan's Three Principles on Transfer of Defense Equipment, and South Korea's Defense Acquisition Program Administration procurement guidelines collectively shape technology transfer boundaries and co-development eligibility across the region. China's SAMR and MIIT standards for dual-use components, combined with India's offset mandates under DPP guidelines, restrict foreign subsystem penetration while accelerating indigenization timelines. Stakeholders must monitor evolving AUKUS technology-sharing protocols and their cascading effects on supply chain eligibility for non-treaty partners.
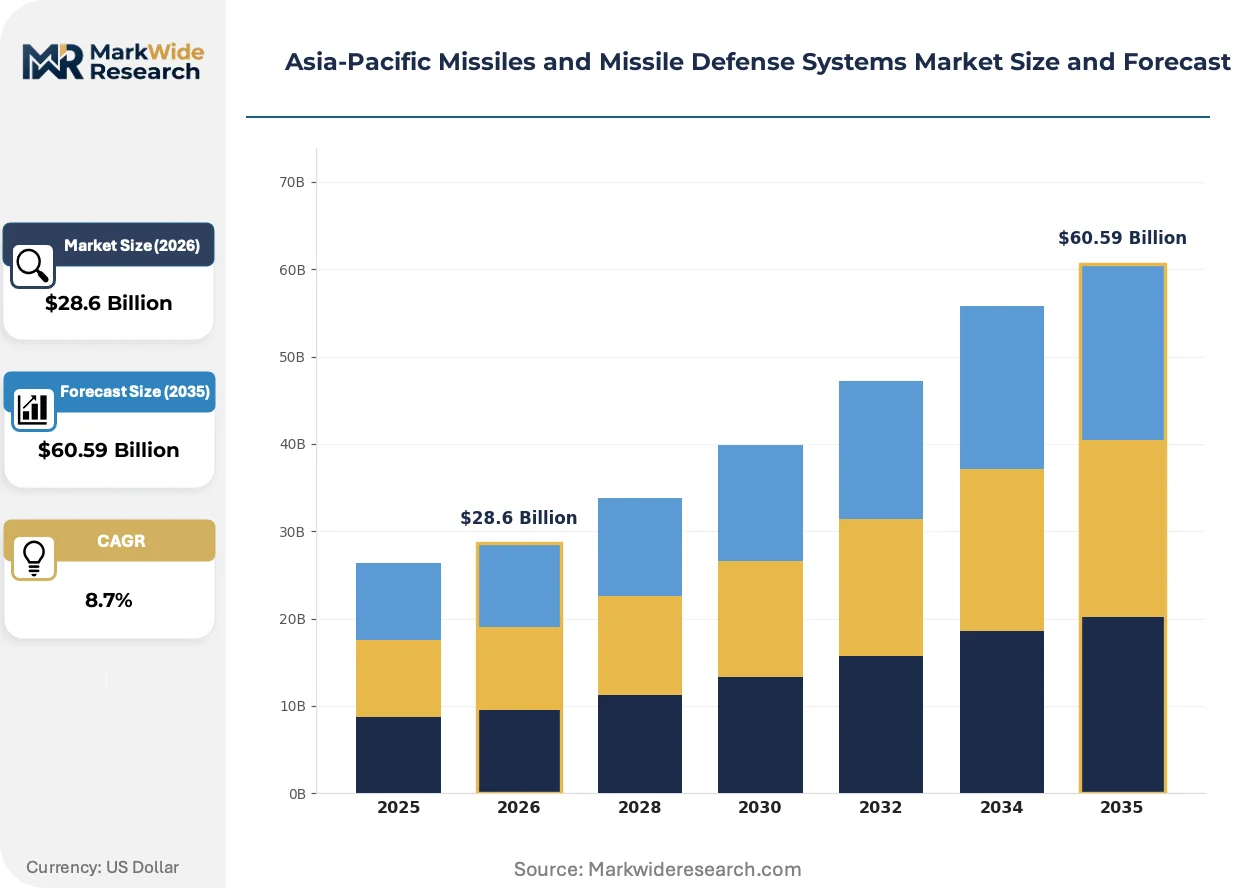
Market Dynamics
Hypersonic glide vehicles are compressing engagement timelines across the Asia-Pacific, forcing defense ministries to reconfigure interceptor architectures and accelerate kill vehicle refresh cycles.
Growth Catalysts
- Japan's Three Principles on Transfer of Defense Equipment:Relaxed export restrictions enable co-development partnerships with Australia and the United Kingdom, expanding addressable markets for Japanese prime contractors.
- Directed-energy countermeasures:South Korea's Defense Acquisition Program Administration channels funding into laser-based point defense systems for naval fleet protection against saturation attacks.
- Southeast Asian layered procurement:Vietnam, Indonesia, and the Philippines accelerate naval modernization programs, creating sustained demand for medium-range air defense batteries.
Market Restraints
- Rare earth magnet supply concentration:China's dominance in neodymium processing creates vulnerability in guided munitions actuator production.
- India's offset mandates under DPP guidelines:Foreign contractors face mandatory technology transfer requirements that dilute proprietary control over seeker algorithms.
- Solid-fuel motor casing shortages:Limited regional capacity for filament-wound composite production constrains tactical missile output.
Strategic Opportunities
- AUKUS technology-sharing protocols:Expanded information exchange creates eligibility pathways for Australian subcontractors in US and UK supply chains.
- Hypersonic interceptor integration:Convergence of scramjet propulsion and advanced seeker fusion enables next-generation area defense architectures.
- Digital engineering workflows:Model-based systems engineering reduces development timelines for South Korean precision strike programs.
Industry Challenges
- Systems engineering talent scarcity:Shortage of specialists in guidance, navigation, and control integration complicates kill vehicle development.
- Multi-level security certification:Australia's Defence Trade Controls Act creates protracted compliance timelines for foreign subsystem suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Missiles and Missile Defense Systems Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Missiles, Cruise Missiles, Air Defense Systems, Anti-Tank Missiles Technology: Guided Missiles, Unguided Missiles, Interceptor Systems, Launch Platforms End User: Military, Defense Contractors, Government, Law Enforcement Deployment: Onshore, Offshore, Mobile Units, Fixed Installations |
| Companies Covered | Defence Research and Development Organisation (DRDO), China Aerospace Science and Industry Corporation, Mitsubishi Heavy Industries, Bharat Dynamics Limited, LIG Nex1, Israel Aerospace Industries, RTX Corporation, Lockheed Martin Corporation, MBDA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Missiles and Missile Defense Systems Market Strategic Shifts
Autonomous targeting loops and software-defined seeker architectures are displacing hardware-centric designs across interceptor development programs.
Artificial intelligence-enabled threat classification is automating engagement authorization protocols in layered defense batteries. Japan's Air Self-Defense Force deploys these systems across southwestern island chain installations. The compression of operator-in-the-loop delays is automating response timelines against maneuvering cruise missiles.
Australia's Defence Trade Controls Act amendments expand technology-sharing eligibility for AUKUS partners while restricting third-country access. The regulatory shift enables deeper subsystem integration between Australian, UK, and US contractors. Japanese and South Korean suppliers face exclusion from certain information tiers, redirecting their partnership strategies toward ASEAN markets.
Defense ministries across the region unbundle platform procurement from sustainment contracts, creating discrete competitive arenas for lifecycle service providers. Original equipment manufacturers confront margin pressure as state-owned maintenance entities capture depot-level overhaul work. This pattern concentrates in Australia's long-range strike programs and South Korea's indigenous fighter-integrated missile initiatives.
Asia-Pacific Missiles and Missile Defense Systems Market Segmentation
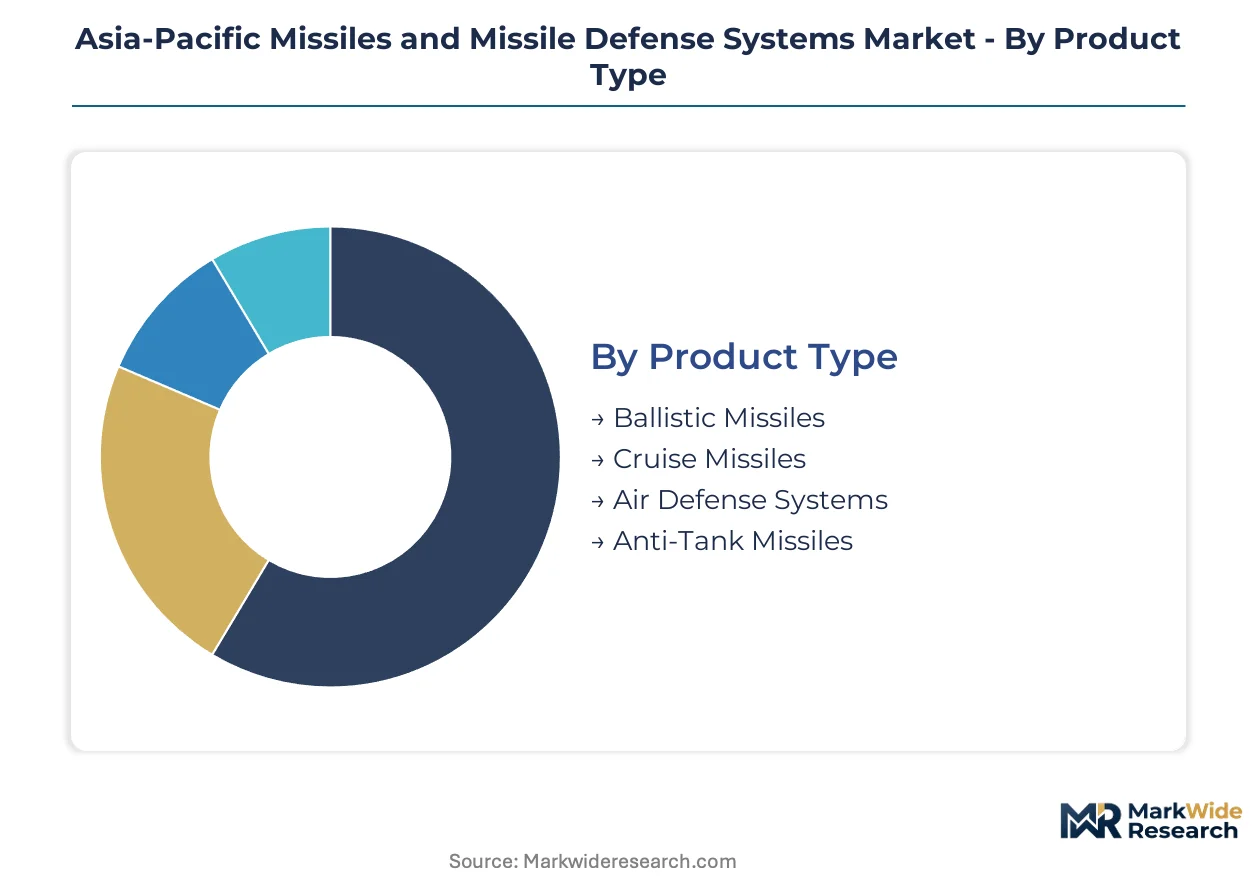
Missile and missile defense procurement in the Asia-Pacific fragments across four distinct dimensions. Each category reflects divergent supply chain configurations, technology transfer barriers, and end-use concentration patterns that shape competitive positioning for prime contractors and subsystem suppliers.
Product Type:
Supply concentration in propulsion subsystems and seeker arrays varies sharply across product categories, with solid-fuel motor production anchoring regional capability clusters.
- Ballistic Missiles:Solid and liquid rocket motor platforms deliver payload across theater and intercontinental ranges. India's DRDO and South Korea's defense innovation ecosystem channel investment into indigenous boosters for nuclear delivery and conventional strike roles, constrained by rare earth magnet supply bottlenecks.
- Cruise Missiles:Turbofan or turbojet propulsion enables terrain-hugging flight profiles with precision terminal guidance. Australia's AUKUS-aligned long-range strike programs concentrate procurement here, while Japan's southwestern island chain deployments prioritize anti-ship variants for area denial.
- Air Defense Systems:Layered interceptor batteries integrate radar cueing with command-and-control networks. Southeast Asian naval fleets accelerate procurement of medium-range systems for fleet protection against saturation attacks.
- Anti-Tank Missiles:Man-portable or vehicle-launched platforms employ tandem warheads against reactive armor. LIG Nex1 competes aggressively in export-oriented precision strike segments for regional ground forces.
Today's leader: Air Defense Systems. Tomorrow's challenger: Cruise Missiles.
Technology:
Cost tier differentiation separates legacy hardware architectures from software-defined systems requiring advanced systems engineering talent pools.
- Guided Missiles:Terminal guidance employs radar, infrared, or electro-optical seekers calibrated for precision engagement. Japan's Air Self-Defense Force deploys autonomous targeting loops across southwestern installations, compressing operator-in-the-loop delays.
- Interceptor Systems:Kill vehicle architectures integrate kinetic or directed-energy effectors against maneuvering threats. South Korea's Defense Acquisition Program Administration channels funding into laser-based point defense for naval fleet protection.
- Unguided Missiles:Rocket artillery platforms rely on ballistic trajectories with area-effect warheads. Regional stockpiles concentrate in legacy systems requiring modernization rather than replacement.
- Launch Platforms:Integrated infrastructure spans vertical launch systems, rail launchers, and airframe hardpoints. Australia's long-range strike programs drive demand for multi-domain launch compatibility.
Interceptor Systems command premium pricing tiers. Guided Missiles scale fastest across procurement volumes.
End User:
Customer type determines contracting structure, with military end users dominating direct procurement while defense contractors absorb subsystem integration complexity under offset mandates.
- Military:Defense ministries across the Asia-Pacific unbundle platform procurement from sustainment contracts. State-owned maintenance entities capture depot-level overhaul work, pressuring original equipment manufacturer margins.
- Defense Contractors:Prime contractors manage multi-source contracting for propulsion subsystems and seeker arrays. China's SAMR and MIIT standards for dual-use components restrict foreign subsystem penetration while accelerating indigenization timelines.
- Government:Civil defense and strategic stockpile agencies acquire reserve inventories and training systems. Procurement follows distinct budget cycles with lower technology transfer requirements.
- Law Enforcement:Specialized tactical units employ reduced-range precision systems for critical incident response. Addressable market remains constrained by export control classifications.
Military end users anchor volume concentration. Defense Contractors capture value-added integration share.
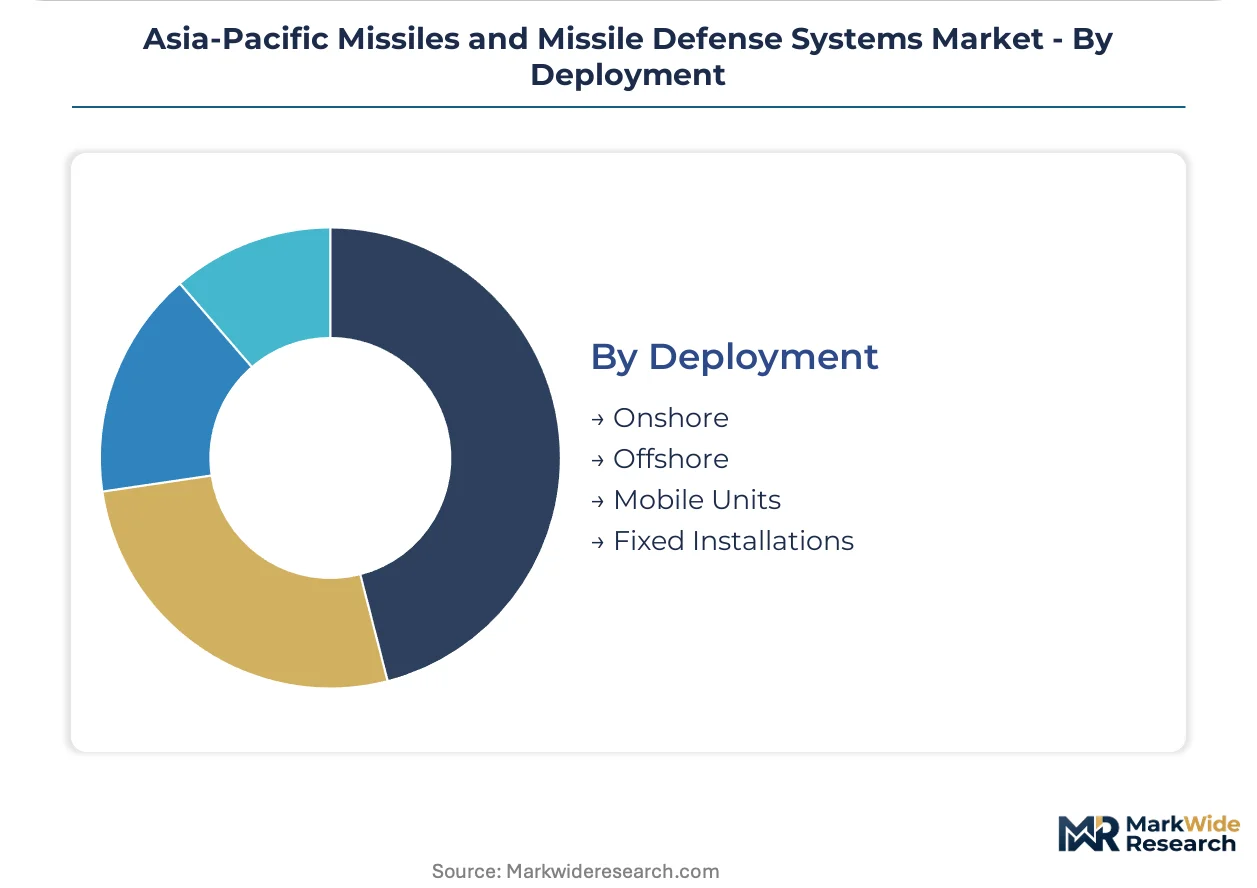
Deployment:
Application context shapes platform specifications, with mobile units demanding hardened electronics and rapid redeployment capability.
- Mobile Units:Road-mobile or naval platforms require stabilized launch systems and survivable command links. Australia's AUKUS technology-sharing protocols create eligibility pathways for Australian subcontractors in mobile system supply chains.
- Fixed Installations:Hardened silos and coastal defense batteries prioritize magazine depth and sensor integration. Japan's southwestern island chain missile deployments exemplify this architecture.
- Onshore:Land-based systems integrate with national air defense networks and territorial defense postures. India's offset mandates under DPP guidelines apply most stringently here.
- Offshore:Naval fleet integration demands corrosion-resistant materials and vertical launch compatibility. Vietnam, Indonesia, and the Philippines accelerate naval modernization programs in this segment.
Mobile Units attract engineering investment priority. Fixed Installations sustain replacement cycle demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense industrial policy across the Asia-Pacific creates uneven compliance burdens that redirect component sourcing toward jurisdictions with streamlined export certification. Prime contractors calibrate subsystem procurement to exploit these regulatory gaps.
China
State-directed vertical integration in solid-fuel motor production dominates domestic supply chains for theater-range systems. SAMR and MIIT standards for dual-use components restrict foreign subsystem penetration while accelerating indigenization timelines. The Beijing-Tianjin-Hebei cluster anchors concentrated rare earth magnet processing for guided munitions actuators.
Japan
Relaxed Three Principles on Transfer of Defense Equipment enable co-development partnerships with Australia and the United Kingdom. METI oversight shapes technology transfer boundaries for interceptor kill vehicle exports. The Nagoya-Chubu corridor concentrates Mitsubishi Heavy Industries R&D on layered defense architectures.
India
DRDO channels investment into indigenous hypersonic interceptors and directed-energy countermeasures under offset mandates. DPP guidelines impose mandatory technology transfer requirements that dilute proprietary control over seeker algorithms. The Hyderabad-Bengaluru corridor hosts concentrated defense electronics integration capacity.
South Korea
Defense Acquisition Program Administration procurement guidelines direct funding into laser-based point defense systems for naval fleet protection. LIG Nex1 competes aggressively in export-oriented tactical missile segments for Southeast Asian buyers. The Seoul Capital Area anchors precision strike program development.
Australia
AUKUS-aligned long-range strike programs concentrate procurement in cruise missile and multi-domain launch systems. Defence Trade Controls Act amendments expand technology-sharing eligibility for treaty partners while restricting third-country access. The Adelaide-Edinburgh defense precinct hosts submarine-launched missile integration facilities.
Asia-Pacific Missiles and Missile Defense Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue indigenous interceptor development through state-backed research institutions. Market structure consolidates around state-owned enterprises with captive supply chains and defense primes managing multi-source subsystem contracting. Two strategic archetypes dominate: vertically integrated national champions leveraging domestic rare earth processing, and export-oriented specialists capturing precision strike niches. Competitive moves center on scramjet propulsion partnerships and directed-energy licensing arrangements.
Within the national champion tier, China Aerospace Science and Industry Corporation and Defence Research and Development Organisation exemplify state-directed integration models. Mitsubishi Heavy Industries occupies a position among defense primes anchoring layered architectures through concentrated kill vehicle development. LIG Nex1 represents the export-specialist archetype competing in tactical missile segments for regional ground forces.
| Leading Market Players |
|---|
| Defence Research and Development Organisation (DRDO) |
| China Aerospace Science and Industry Corporation |
| Mitsubishi Heavy Industries |
| Bharat Dynamics Limited |
| LIG Nex1 |
| Israel Aerospace Industries |
| RTX Corporation |
| Lockheed Martin Corporation |
| MBDA |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of solid-fuel motor casings and seeker arrays across Chinese state-owned enterprises anchors both supply security and pricing power for domestic contractors, while foreign primes absorb margin compression from offset mandates and technology transfer requirements.
Pricing Analysis
Direct-to-defense ministry contracting eliminates distributor margins but imposes heavy compliance cost burdens on foreign subsystem suppliers. Three-tier pricing structure across developmental prototypes, limited production runs, and full-rate manufacturing separates cost tiers by technical maturity and volume scale. Cost compression in tactical missile segments is intensifying because Southeast Asian buyers consolidate procurement under multi-year frameworks. State-owned defense contractors exhibit lowest price sensitivity; export-oriented precision strike specialists face acute margin pressure.
Supply Chain Analysis
Specialized workforce pools for guidance navigation and control integration concentrate in Japan's Nagoya-Chubu corridor, South Korea's Seoul Capital Area, and India's Hyderabad-Bengaluru belt. Rare earth magnet processing draws from China's Beijing-Tianjin-Hebei cluster; filament-wound composite casing production rests on limited regional capacity in Japan and South Korea. Single-source vulnerability in neodymium supply creates chokepoint exposure for guided munitions actuator production. Distribution runs through government-to-government foreign military sales channels and offset-structured co-development agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific missiles and missile defense systems market represents a late-cycle quality story as defense ministries shift procurement toward hypersonic interceptors and directed-energy countermeasures demanding premium engineering specifications.
For Market Incumbents: Extend kill vehicle refresh cycles through digital engineering workflows that compress development timelines against emerging South Korean precision strike programs. Deepen backward integration into rare earth magnet processing to neutralize China's supply chokepoint leverage. Prioritize certification investment under Australia's Defence Trade Controls Act amendments to secure AUKUS technology-sharing eligibility.
For New Entrants and Emerging Players: Enter via naval fleet protection subsystems for Vietnam, Indonesia, and Philippines modernization programs where incumbent presence remains thin. Target medium-range air defense batteries as the most penetrable segment given Southeast Asian layered procurement acceleration. Pursue co-development partnerships with South Korea's Defense Acquisition Program Administration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for precision strike subsystem specialists because defense ministry unbundling of platform and sustainment contracts fragments vendor relationships across the region. Long-term viability centers on scramjet propulsion and directed-energy licensing positions. Monitor AUKUS technology-sharing protocol expansions as the critical inflection signal for supply chain eligibility reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hypersonic Interceptor Development Partnership | DRDO and South Korean defense innovation ecosystem channel investment into indigenous scramjet kill vehicle architectures. |
| Directed-Energy Licensing Agreement | LIG Nex1 and Mitsubishi Heavy Industries pursue laser-based point defense technology transfer for naval fleet protection. |
| Multi-Source Propulsion Subsystem Contracting | Prime contractors diversify solid-fuel motor sourcing beyond China's state-backed vertical integration dominance. |
| AUKUS Supply Chain Integration | Australian subcontractors gain eligibility pathways in US and UK layered defense architecture programs. |
| Southeast Asian Naval Modernization Joint Venture | Export-oriented specialists capture precision strike demand from Vietnam, Indonesia, and Philippines fleet upgrades. |
Study Parameters
Bottom-up defense ministry procurement modeling reconciled against top-down prime contractor production tracking forms the analytical core of this study. Primary interviews with missile program executives, defense acquisition officers, subsystem engineering directors, and export compliance specialists combined with secondary validation from customs filings, SAMR and MIIT dual-use component registrations, DPP offset disclosure documents, and AUKUS technology-sharing protocol amendments. Triangulation across these sources yields volume and value estimates segmented by product type, technology tier, end-user category, and deployment mode.
Input-output matrices map propulsion subsystem demand to solid-fuel motor capacity, seeker array orders to rare earth magnet supply, and interceptor battery deployments to radar integration lead times across the projection horizon. CAGRs derive from regression against historical procurement cycles, defense budget trajectory analysis, and technology refresh rate assumptions. Hypersonic glide vehicle threat compression timelines and directed-energy countermeasure funding flows constitute key forecast inputs.
Inputs from defense ministry budget appropriations and prime contractor backlog disclosures were available through the study window; gaps in classified kill vehicle performance specifications introduce uncertainty bands around interceptor system penetration assumptions. Forecasts reflect documented assumptions regarding AUKUS protocol expansion pace and Southeast Asian naval modernization commitment durability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Electronic Countermeasures Market
Defense Cybersecurity
Railway Cyber Security Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Defensive Cyber Weapons Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Aviation Cyber Security Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Mine and IED Detection System Market