
 Global Handheld Counter IED Market | 2026-2036
Global Handheld Counter IED Market Size, Share, and Industry Trends Forecast 2026-2036
Global Handheld Counter IED Market Foresight
Aftermarket calibration and refurbishment revenue is fragmenting across regional service networks as prime contractors surrender direct control. L3Harris Technologies leverages its domestic depot network to sustain recurring service income. Smiths Detection anchors European maintenance contracts through certified field engineering teams. Elbit Systems competes on integrated training and logistics packages in Middle Eastern markets.
A handheld counter IED device comprises a portable electronics suite weighing under ten kilograms, integrating radio frequency transmitters, magnetic anomaly detectors, and thermal imaging modules to locate and identify improvised explosive devices at standoff distances. The primary purpose centers on protecting dismounted personnel during route clearance, perimeter security, and targeted search operations. Combined sensors command premium positioning due to multi-spectral threat detection capabilities, while machine learning-enabled units represent the fastest-expanding technology tier as operators prioritize reduced false-alarm rates. Bomb disposal units and border control applications absorb disproportionate procurement share among end-use categories.
The U.S. Department of Defense mandates Joint Test and Evaluation protocols through DOT&E, while NATO STANAG 4778 defines interoperability benchmarks for allied force equipment exchange. The EU Green Deal's restricted substance schedules increasingly affect battery and circuit board sourcing decisions for European-deployable units. Stakeholders must weigh dual-use export control alignment against accelerated foreign military sales timelines.
Market Dynamics
Machine learning integration into threat classification algorithms is compressing development cycles and forcing established suppliers to retrain field personnel on algorithmic interpretation protocols.
Growth Catalysts
- NATO STANAG 4778 interoperability mandates:Allied force equipment exchange requirements compel manufacturers to standardize communication protocols, expanding addressable procurement pools across member militaries.
- Route clearance operations:Persistent asymmetric conflict patterns sustain demand for dismounted detection capabilities in contested urban environments.
- Dual-use export control alignment:Harmonized U.S. State Department and EU dual-use regulations accelerate foreign military sales timelines for qualified platforms.
Market Restraints
- Lithium-ion battery supply concentration:Processing capacity bottlenecks in raw material refining create input volatility for portable power systems.
- EU Green Deal restricted substance schedules:RoHS and REACH compliance requirements constrain circuit board and battery chemistry sourcing flexibility for European-deployable units.
- Standoff distance limitations:Current radio frequency transmitter architectures face physics-bound detection range ceilings against shielded device configurations.
Strategic Opportunities
- Border control modernization:Israel and Saudi Arabia are expanding perimeter security procurement beyond traditional military end-uses.
- Integrated training and logistics packages:Comprehensive operator certification and maintenance bundling creates recurring revenue streams distinct from hardware margins.
- Machine learning-enabled thermal fusion:Convergence of multi-spectral imaging with adaptive algorithms opens premium positioning for false-alarm reduction capabilities.
Industry Challenges
- DOT&E Joint Test and Evaluation protocols:U.S. Department of Defense validation timelines extend product qualification cycles, compressing effective contract windows.
- Algorithmic threat signature maintenance:Continuous model retraining demands specialized data science talent scarce within traditional defense electronics workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Handheld Counter IED Market |
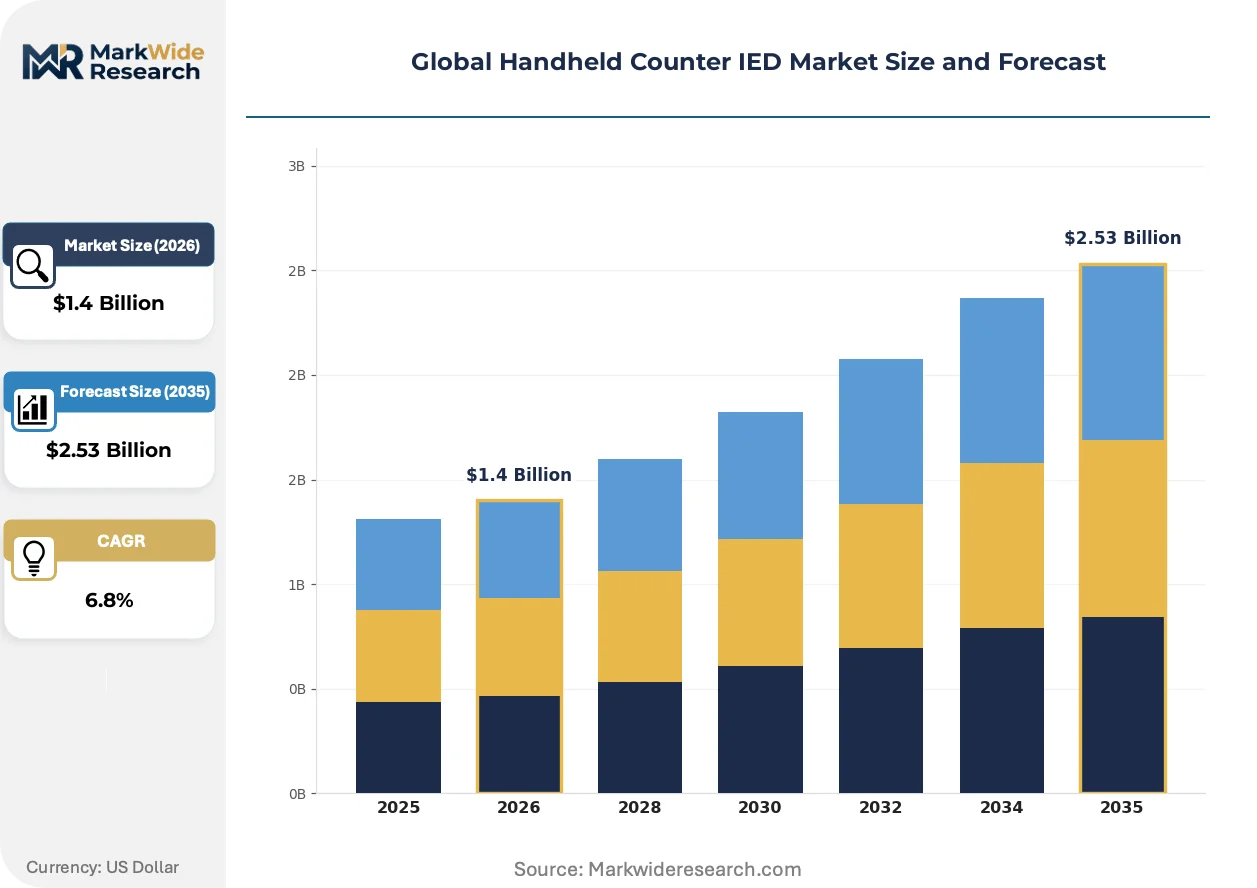
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar-Based Detectors, Magnetic Sensors, Infrared Sensors, Combined Sensors, Acoustic Sensors Technology: Signal Processing, Image Recognition, Spectrum Analysis, Magnetic Field Detection, Machine Learning Application: Military Operations, Bomb Disposal Units, Law Enforcement, Security Screening, Border Control End User: Defense Forces, Counterterrorism Units, Public Safety Agencies, Private Security Firms, Emergency Responders |
| Companies Covered | Northrop Grumman Corporation, BAE Systems PLC, L3Harris Technologies, Inc., Thales Group, Smiths Detection, Chemring Group PLC, Raytheon Technologies, Elbit Systems Ltd., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Handheld Counter IED Market Shifts & Advancements
Computational detection architectures are displacing hardware-centric platforms, shifting value capture toward software and data services while compressing equipment replacement cycles.
Multi-spectral sensor fusion is digitizing threat identification workflows by combining magnetic anomaly, thermal, and radio frequency signatures into unified classification outputs. Bomb disposal units in the United States and United Kingdom are fielding these platforms at accelerated procurement tempos. This convergence is digitizing maintenance protocols, as field calibration shifts from hardware adjustment to algorithmic parameter updates.
EU Green Deal battery sourcing requirements are reshaping European-deployable unit specifications, mandating recycled content thresholds and restricted substance documentation. Manufacturers serving NATO allied forces must maintain parallel supply chains: one compliant with EU environmental schedules, another optimized for U.S. foreign military sales timelines. Israeli and Australian defense procurement offices are observing these compliance patterns to inform their own sustainability mandates.
Aftermarket service unbundling is fragmenting traditional prime contractor revenue models as regional depot networks assume direct calibration and refurbishment relationships. L3Harris Technologies sustains recurring income through domestic service infrastructure, while Smiths Detection anchors European maintenance through certified field engineering deployments. This disaggregation is most visible in Middle Eastern markets, where integrated training and logistics packages now determine contract awards more than equipment specifications alone.
Global Handheld Counter IED Market Segmentation
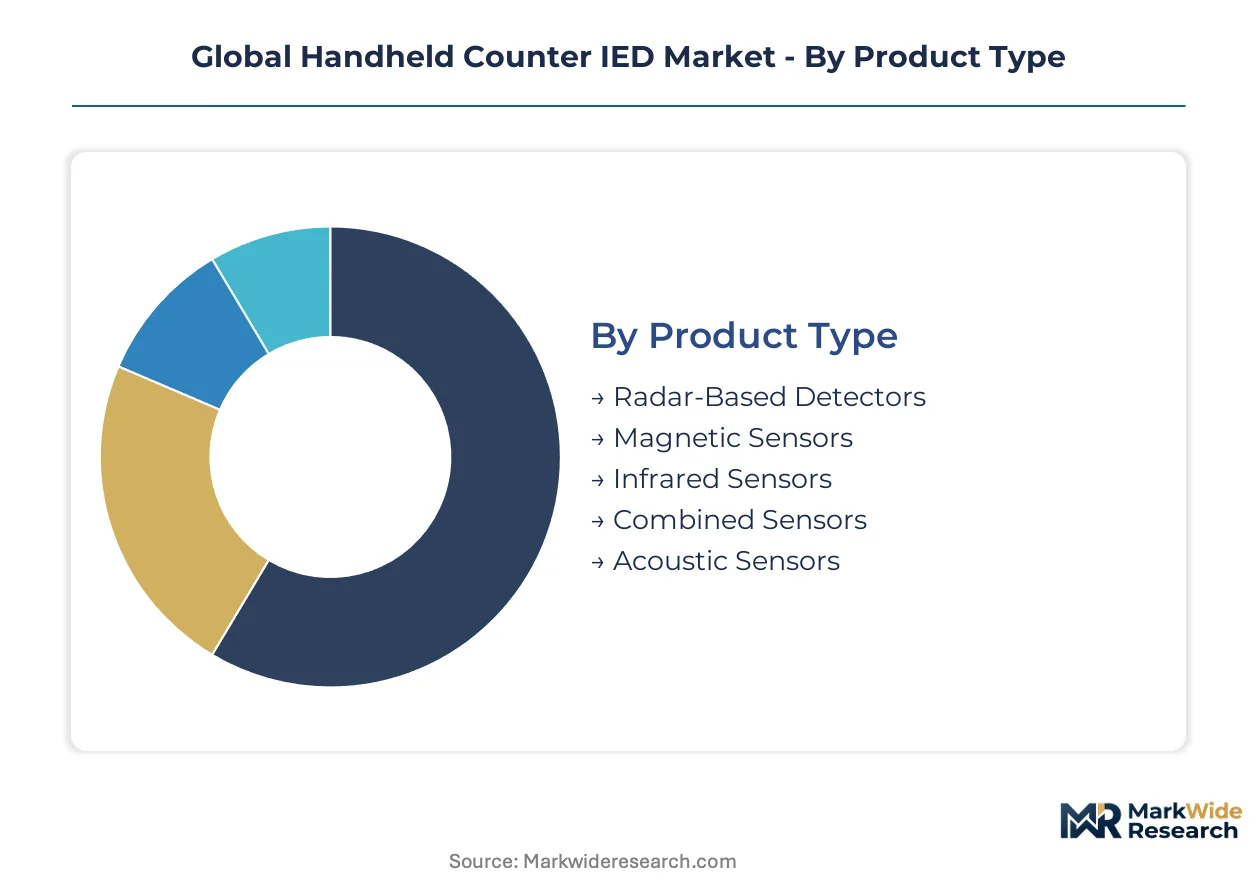
Segmentation in the Global Handheld Counter IED Market reveals divergent service intensity profiles across product tiers. Combined sensors and machine learning-enabled platforms demand continuous algorithmic updates and recalibration protocols, while legacy magnetic and acoustic systems require simpler hardware maintenance cycles.
Product Type:
After-sales-service intensity varies sharply across detection modalities, with multi-sensor platforms requiring integrated maintenance networks and single-technology units amenable to regional depot servicing.
- Combined Sensors:Integrated radio frequency, magnetic anomaly, and thermal imaging modules enable multi-spectral threat detection at standoff distances. Bomb disposal units in the United States and United Kingdom absorb disproportionate procurement volumes as operators prioritize false-alarm reduction in urban route clearance scenarios. These platforms command premium positioning and recurring calibration revenue streams.
- Radar-Based Detectors:Ground-penetrating and forward-looking radar architectures detect metallic and non-metallic anomalies through electromagnetic pulse analysis. Israeli Defense Forces and Saudi border security agencies drive procurement for perimeter applications where subsurface detection dominates operational requirements. Physics-bound range limitations against shielded devices constrain deployment flexibility.
- Magnetic Sensors:Fluxgate and gradiometer technologies identify ferromagnetic disturbances from triggering mechanisms and power sources.
- Infrared Sensors:Thermal imaging modules detect heat signatures from electronic components and battery assemblies.
- Acoustic Sensors:Vibration and ultrasonic detection systems identify hollow cavities and anomalous material densities.
Combined sensors hold the largest share; momentum sits with radar-based detectors as standoff range requirements intensify.
Technology:
Cost tier stratification separates legacy signal processing architectures from premium machine learning implementations, with mid-tier spectrum analysis and image recognition occupying transitional positioning.
- Machine Learning:Adaptive algorithms compress threat classification timelines and reduce operator cognitive load through automated signature recognition. NATO STANAG 4778 interoperability mandates accelerate procurement across allied defense forces seeking algorithmic standardization. Continuous model retraining demands scarce data science talent within traditional defense electronics workforces.
- Signal Processing:Digital filtering and spectral analysis techniques form the foundational layer of radio frequency detection architectures. Legacy military procurement programs in the United States sustain volume demand despite longer development cycles compared to adaptive systems. Established supplier relationships and proven field reliability maintain contract continuity.
- Image Recognition:Computer vision algorithms process thermal and visual feeds for device component identification.
- Spectrum Analysis:Wideband radio frequency scanning identifies anomalous transmission signatures from remote triggering systems.
- Magnetic Field Detection:Analog and digital magnetometer signal processing enables ferrous object localization.
Signal processing retains dominant installed base; machine learning is gaining share fastest through false-alarm reduction contracting priorities.
Application:
Volume concentration clusters in military end-uses, though border control and law enforcement applications are expanding procurement pools beyond traditional defense budgets.
- Military Operations:Dismounted route clearance, convoy protection, and tactical site exploitation absorb the majority of platform deployment. United States, United Kingdom, and Israeli defense budgets sustain modernization cycles with multi-year procurement frameworks. DOT&E Joint Test and Evaluation protocols extend qualification timelines, compressing effective contract windows.
- Bomb Disposal Units:Specialized explosive ordnance disposal teams require portable, high-confidence detection for deliberate approach scenarios. Urban counterterrorism operations in European metropolitan areas drive demand for reduced-form-factor platforms with integrated disposal tool interfaces. Operator certification requirements create attached training revenue opportunities.
- Law Enforcement:Domestic security agencies deploy handheld units for suspicious package response and critical infrastructure protection.
- Security Screening:Event venues and transportation hubs utilize detection platforms for access point monitoring.
- Border Control:Perimeter security agencies in Israel and Saudi Arabia are expanding procurement beyond traditional military end-uses.
Military operations command the largest procurement volume; border control shows the steepest expansion trajectory as perimeter modernization accelerates.
End User:
Customer type determines procurement channel structure, with defense forces utilizing foreign military sales frameworks and public safety agencies operating through domestic acquisition mechanisms.
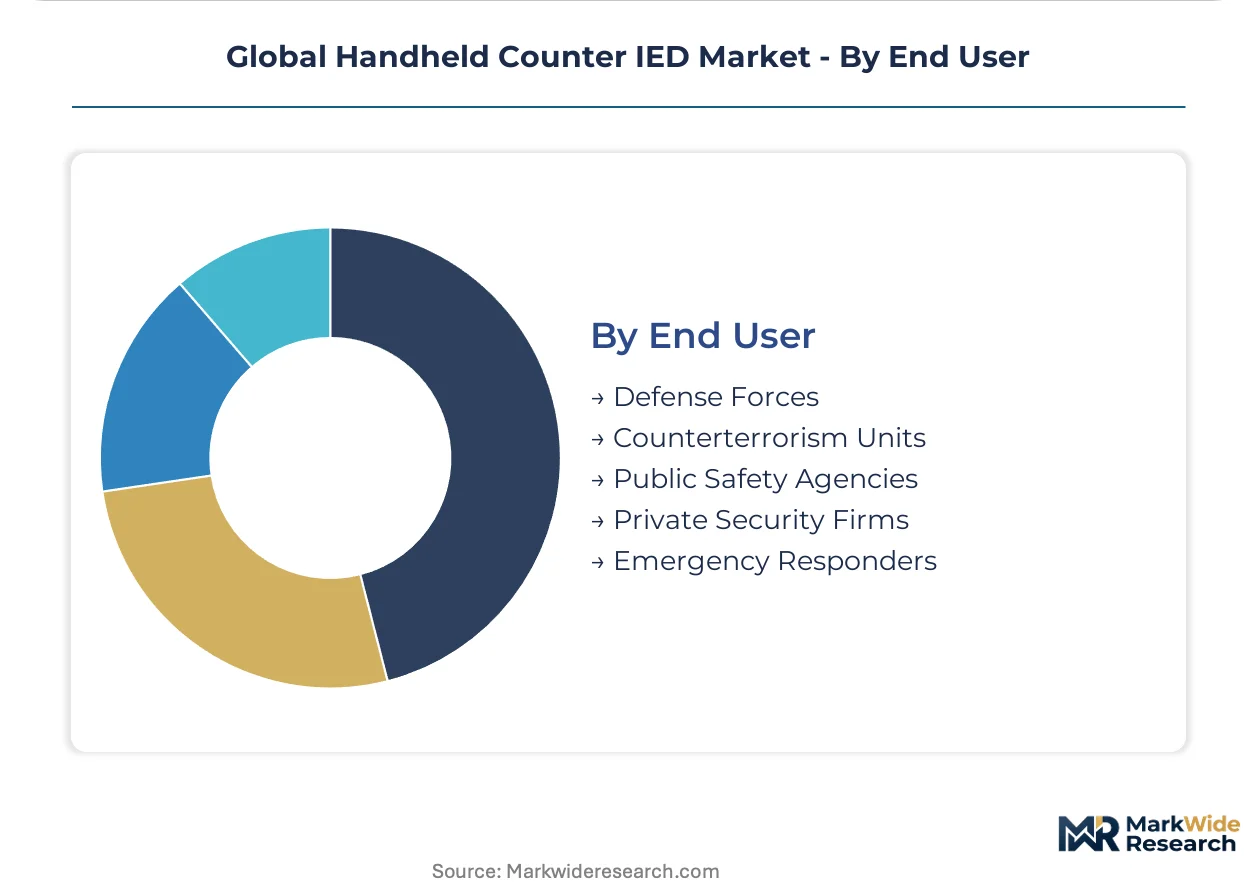
- Defense Forces:National military establishments procure through centralized defense procurement offices with multi-year program budgeting. NATO interoperability requirements and U.S. foreign military sales timelines shape equipment standardization across allied forces. Dual-use export control alignment accelerates qualified platform deliveries.
- Counterterrorism Units:Specialized federal and state-level tactical teams require rapid deployment capabilities and classified threat signature databases. Intelligence-sharing protocols between United States, United Kingdom, and Israeli units drive common platform specifications. Integrated training and logistics packages determine contract awards more than equipment specifications alone.
- Public Safety Agencies:Municipal police and emergency management departments acquire through domestic security grants and intergovernmental purchasing agreements.
- Private Security Firms:Commercial contractors serving critical infrastructure and corporate clients operate outside classified procurement channels.
- Emergency Responders:Fire departments and hazardous materials teams require cross-trained detection capabilities for secondary device response.
Defense forces represent the dominant customer category; counterterrorism units are climbing fastest as domestic security budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across geographies. Israeli and Saudi buyers prioritize capability premiums over unit cost, while European NATO members face tighter budget constraints that compress vendor margins.
United States
DOT&E Joint Test and Evaluation protocols extend qualification timelines for dismounted detection platforms, compressing effective contract windows for suppliers. The U.S. Department of Defense mandates interoperability benchmarks through foreign military sales frameworks. Defense electronics clusters in Virginia and Massachusetts concentrate algorithm development and systems integration work for next-generation threat classification units.
United Kingdom
Bomb disposal units in urban metropolitan areas absorb disproportionate procurement volumes as operators prioritize reduced-form-factor platforms. UK Ministry of Defence procurement offices align equipment specifications with NATO STANAG 4778 interoperability requirements. Industrial activity clusters around Farnborough and the Southeast, where certified field engineering teams anchor European maintenance contract networks.
Israel
Perimeter security agencies expand procurement beyond traditional military end-uses into border control modernization programs. Israeli Defense Forces drive demand for subsurface detection capabilities where physics-bound range requirements dominate operational specifications. Tel Aviv-area defense electronics corridors concentrate multi-spectral sensor fusion development and integrated training package design.
Germany
EU Green Deal restricted substance schedules constrain battery chemistry and circuit board sourcing flexibility for deployable units. ECHA REACH compliance documentation requirements extend supplier qualification timelines for European-deployable platforms. Industrial concentration in Bavaria and Baden-Württemberg sustains precision manufacturing capabilities for magnetic anomaly detector components.
Saudi Arabia
Border security agencies accelerate perimeter modernization procurement with integrated logistics and training package requirements. Dual-use export control alignment with U.S. State Department regulations accelerates qualified platform deliveries through foreign military sales channels. Riyadh-based procurement offices coordinate regional depot network development for aftermarket calibration services.
Global Handheld Counter IED Market Competitive Landscape
Capability concentration sits with specialized sensor integrators; scale advantage sits with diversified defense primes with established depot networks. The vendor base organizes around three strategic archetypes: multi-domain platform houses with service infrastructure, sensor specialists with algorithmic IP positions, and regional integrators with training bundling capabilities. Dominant competitive moves include aftermarket service unbundling to regional depot networks and machine learning-enabled product tier differentiation.
Among U.S.-based defense electronics primes, Northrop Grumman Corporation and L3Harris Technologies, Inc. exemplify the platform-house archetype with integrated domestic service infrastructure. Thales Group represents the European multi-domain specialist position with certified field engineering deployments across NATO member states. These three occupy positions where recurring calibration revenue and algorithm update subscriptions increasingly determine contract profitability.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| BAE Systems PLC |
| L3Harris Technologies, Inc. |
| Thales Group |
| Smiths Detection |
| Chemring Group PLC |
| Raytheon Technologies |
| Elbit Systems Ltd. |
| Lockheed Martin Corporation |
| Others |
Supply & Pricing Matrix
The Trans-Suez freight corridor's rate volatility feeds directly into landed cost differentials for lithium-ion battery cells and rare-earth magnet assemblies, compressing margins for European-deployable units while amplifying price spreads between premium multi-sensor platforms and single-technology alternatives. Defense procurement offices in Germany and Saudi Arabia absorb these logistics premiums differently, with the former prioritizing EU Green Deal compliance documentation and the latter accepting integrated logistics bundling to offset unit cost premiums.
Pricing Analysis
After-sales calibration contracts and algorithm update subscriptions drive lifetime value capture, with recurring service revenue now matching hardware margins for machine learning-enabled platforms. Three-tier pricing structure across premium multi-sensor, standard dual-technology, and economy single-modality levels reflects certification grade differentiation and NATO STANAG 4778 interoperability compliance. Cost compression in standard tiers is intensifying because lithium-ion supply bottlenecks constrain battery chemistry sourcing flexibility. Bomb disposal units in the United Kingdom and Israel demonstrate least price sensitivity, prioritizing false-alarm reduction capabilities over unit acquisition cost.
Supply Chain Analysis
Contract manufacturing capacity for RF transmitter modules and thermal imaging cores concentrates in South Korean and Taiwanese electronics foundries, with Israeli sensor fusion specialists maintaining captive assembly lines for classified threat signature processing. Critical inputs draw from Chinese rare-earth processing facilities for magnetic anomaly detector components, Japanese precision optics for infrared modules, and German semiconductor packaging for signal processing architectures. Single-source vulnerability in lithium refining creates input volatility for portable power systems. Distribution runs through prime contractor depot networks and certified field engineering deployments rather than open channel wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
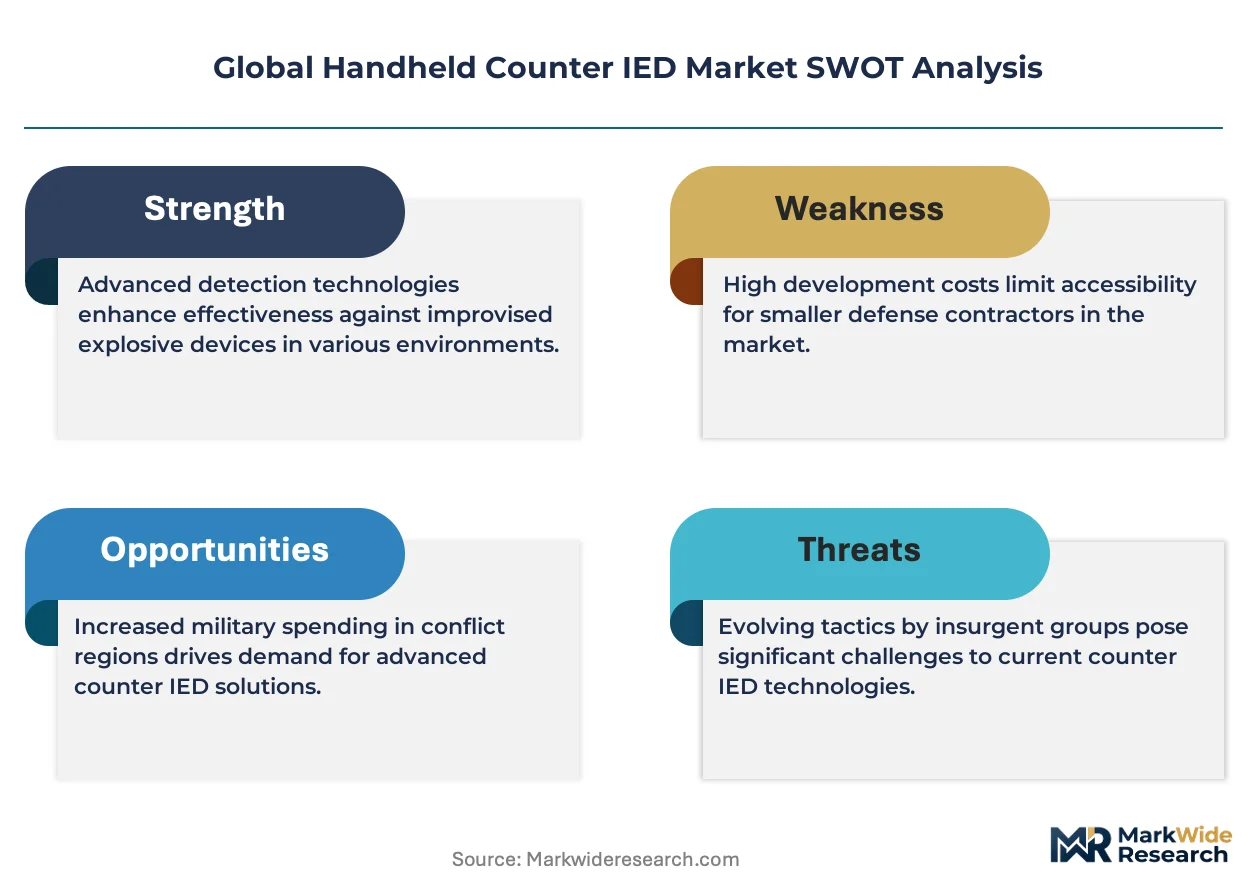
This market functions as a regulatory-entrenchment defensive moat, where DOT&E Joint Test and Evaluation protocols and NATO STANAG 4778 interoperability mandates create multi-year qualification barriers that insulate validated suppliers from rapid competitive displacement.
For Market Incumbents: Build switching-cost moats through embedded algorithm update subscriptions and captive depot network infrastructure. Consolidate position by acquiring specialized sensor fusion IP holders in Tel Aviv-area defense electronics corridors. Counter emerging algorithmic-native entrants by accelerating machine learning-enabled thermal fusion roadmaps ahead of foreign military sales qualification timelines. For New Entrants and Emerging Players: Build out white-space positions in border control modernization programs across Saudi Arabia and Israel, where perimeter security procurement operates outside traditional defense budget cycles with reduced DOT&E validation requirements. Target law enforcement and public safety agencies in European metropolitan areas seeking reduced-form-factor platforms with integrated disposal tool interfaces. Pursue go-to-market angles through certified training bundling rather than hardware specification competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense primes seeking to divest non-core detection electronics divisions lacking integrated service infrastructure. Long-term viability hinges on algorithmic IP ownership and recurring revenue attachment rates rather than hardware shipment volumes. Monitor foreign military sales pipeline conversion rates as the primary inflection indicator for contract profitability compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Update Subscription Model | Transforms one-time hardware transactions into recurring revenue streams with NATO interoperability mandates. |
| Certified Field Engineering Network Expansion | Captures aftermarket calibration revenue previously surrendered to regional depot unbundling trends. |
| Dual-Use Export Control Pre-Qualification | Accelerates foreign military sales timelines through harmonized U.S. State Department and EU regulatory alignment. |
| Machine Learning-Enabled Thermal Fusion Development | Opens premium positioning for false-alarm reduction capabilities in urban route clearance scenarios. |
| Integrated Training and Logistics Package Design | Determines Middle Eastern contract awards more than equipment specifications alone. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of defense procurement databases, NATO standardization documents, and dual-use export control filings. Primary interviews encompassed program managers at U.S. Department of Defense procurement offices, explosive ordnance disposal team leads in United Kingdom metropolitan police units, and field engineering directors at European maintenance contract networks. Secondary validation drew from DOT&E test evaluation reports, EU Green Deal restricted substance schedules, and foreign military sales disclosure filings. Bottom-up demand modeling across end-use categories was triangulated against top-down defense budget allocation analysis.
Forecast inputs include algorithm adoption curves across threat classification technology tiers, lithium-ion battery supply elasticity assumptions, and NATO member state procurement cycle phasing. Segmentation dimensions modeled encompass product type, technology tier, application category, end-user type, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement volumes against defense modernization budget trajectories. Industry-specific inputs include DOT&E qualification timeline compression effects and EU REACH compliance documentation burden estimates.
Stress conditions across lithium raw material price bands, dual-use export control harmonization failure scenarios, and algorithmic threat signature maintenance talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO STANAG 4778 adoption velocity and foreign military sales pipeline conversion efficiency. Quarterly review of defense procurement office RFP issuance rates and algorithm update subscription renewal ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Asia-Pacific Defense Market
Defense Cybersecurity
Electronic Warfare Market
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Ballistics Targeting Software Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Maritime Cybersecurity Market
Defense Cybersecurity
Defence Cybersecurity Market
Defense Cybersecurity
Cyber Weapons Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Automotive Cyber Security Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Blockchain Technology in Aerospace and Defense Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Defensive Cyber Weapons Market