
 Asia-Pacific Semiconductor Market | 2026-2036
Asia-Pacific Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor Market Insights
JIS Q 9001 certification is collapsing the supplier base for automotive-grade chips in Japan, forcing foundries to rebuild quality systems or exit tier-one supply chains. TSMC leverages its N3E process leadership to dominate advanced-node contracts for AI accelerators and smartphone SoCs. Samsung Electronics anchors memory supply through vertical control over HBM3E stack architecture and in-house packaging. SK Hynix competes aggressively in high-bandwidth memory through specialized yield engineering at its Icheon complex.
Asia-Pacific semiconductors are solid-state electronic devices fabricated on silicon, gallium nitride, or silicon-on-insulator substrates, engineered to switch, amplify, or store electrical signals with nanometer-scale precision; they power computing, communication, sensing, and power conversion across every industrial system. CMOS logic nodes below 7nm now capture the bulk of foundry margin pools as digital product categories absorb disproportionate capex allocation. GaN-on-silicon technology for power electronics is expanding fastest within the technology segment, driven by EV onboard chargers and datacenter power supplies. Mixed-signal products maintain defensive profitability in industrial and automotive end-user channels where qualification cycles extend to 36 months.
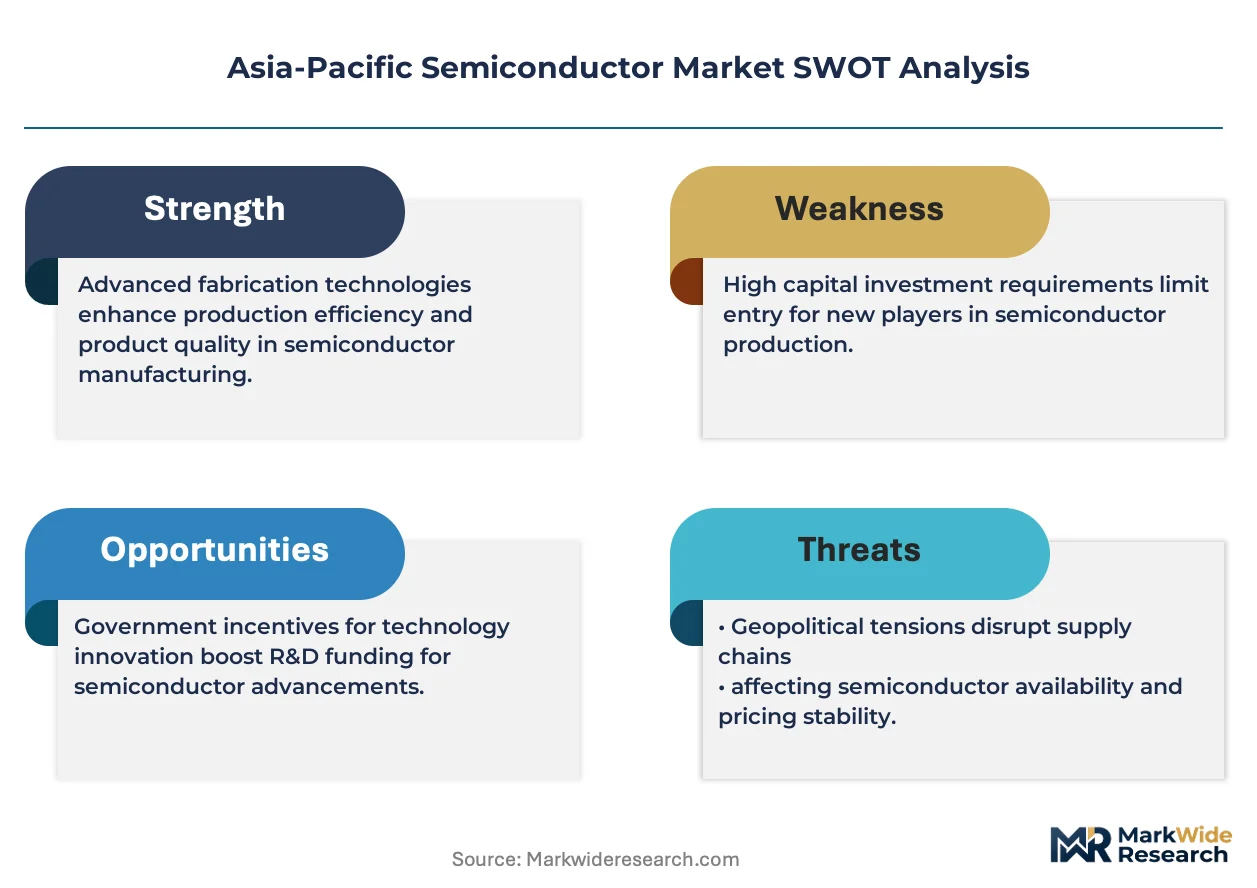
Japan's METI directs domestic reshoring through the Semiconductor Emergency Measures Act, while South Korea's K-Chips Act structures tax credits for facility investment. China's MIIT enforces GB standards for domestic IC procurement, fragmenting market access rules across the region. Stakeholders must monitor which regulatory jurisdiction governs their customers' qualification requirements before committing to multi-billion dollar fab capacity.
Market Dynamics
Automotive electrification is compressing qualification timelines while foundries race to secure JIS Q 9001 certification for tier-one automotive supply chains across Japan, Taiwan, and South Korea.
Growth Catalysts
- Japan's METI Semiconductor Emergency Measures Act:Domestic reshoring subsidies are redirecting capital toward foundry expansion in Kyushu and Tohoku, creating captive supply for automotive OEMs.
- GaN-on-silicon power devices:EV onboard chargers and datacenter power supplies are pulling capacity from silicon carbide alternatives, with foundries in Taiwan and South Korea expanding dedicated lines.
- China's MIIT domestic procurement mandates:GB standards enforcement is fragmenting market access rules, creating parallel qualification tracks that favor local design houses.
Market Restraints
- Advanced-node equipment concentration:EUV lithography systems from a single Dutch supplier create chokepoints for sub-7nm production ramps.
- Neon and specialty gas supply:Ukrainian-sourced neon purification capacity remains constrained, forcing Japanese and South Korean fabs to rebuild buffer inventories at 40% cost premiums.
- JIS Q 9001 certification backlog:Automotive-grade qualification cycles extending to 36 months are freezing out second-tier foundries from tier-one supply chains.
Strategic Opportunities
- Vietnam and Malaysia backend assembly:Underpenetrated test and packaging capacity is attracting OSAT investments as China-plus-one strategies mature.
- Chiplets and 3D packaging convergence:Hybrid bonding and through-silicon via integration are opening new architectural paths for AI accelerators beyond monolithic dies.
- South Korea's K-Chips Act tax credits:Facility investment incentives are structuring 15-year depreciation schedules that improve project IRRs for memory and logic expansions.
Industry Challenges
- Process engineering talent scarcity:Advanced-node yield optimization requires PhD-level expertise in atomic-layer deposition that universities in Taiwan and South Korea cannot supply at scale.
- Legacy 200mm equipment sourcing:Automotive and industrial chip demand is colliding with decommissioned 200mm fab capacity, forcing foundries to pay 300% premiums for refurbished tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor Market |
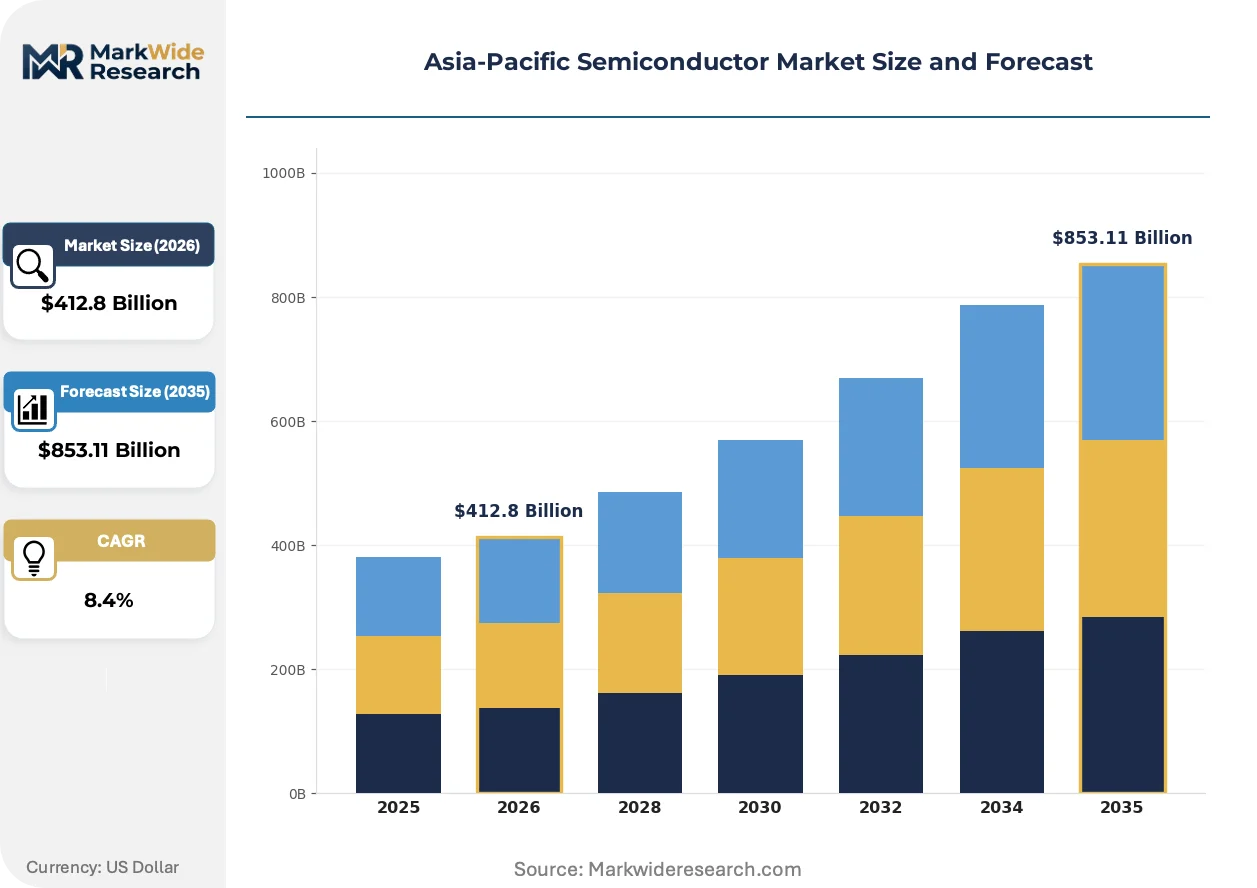
| Market Size in 2026 | $412.8 Billion |
| Market Size in 2035 | $853.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Mixed-Signal, Microcontrollers Technology: CMOS, BiCMOS, GaN, SOI End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Computing, Networking, IoT, Smart Appliances |
| Companies Covered | Tokyo Electron, Powerchip Semiconductor Manufacturing Corporation (PSMC), Taiwan Semiconductor Manufacturing Company (TSMC), ASE Technology Holding, MediaTek, Samsung Electronics, United Microelectronics Corporation (UMC), Tokyo Ohka Kogyo Co., Ltd., SK Hynix, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor Market Trends and Innovations
Process-node bifurcation is splitting investment flows between bleeding-edge EUV nodes and trailing-edge specialty processes, with packaging innovation emerging as the third competitive axis.
Gate-all-around transistor architecture is fragmenting the foundry landscape as TSMC, Samsung, and Intel pursue divergent nanosheet implementations for 2nm-class production. Automotive SoC designers are adopting GAA for power efficiency gains in ADAS compute, while smartphone OEMs prioritize density scaling. This technology divergence is fragmenting IP ecosystem development and EDA tool standardization across the region.
Japan's METI export controls on 23 categories of semiconductor manufacturing equipment, mirrored by Dutch and US coordination, are restructuring equipment procurement channels. South Korean memory makers are accelerating domestic etch and deposition tool qualification to reduce ASML and Tokyo Electron dependency. Chinese fabs are responding with aggressive reverse engineering of legacy tool architectures, compressing technology transfer timelines.
Consolidated procurement by hyperscale cloud operators is displacing fragmented OEM purchasing for AI training chips. Amazon Web Services, Microsoft Azure, and Alibaba Cloud are negotiating direct foundry relationships for custom silicon, bypassing traditional semiconductor distributors. This buyer concentration is most visible in Taiwan's Hsinchu corridor, where dedicated capacity allocation agreements now span five-year horizons.
Asia-Pacific Semiconductor Market Segmentation
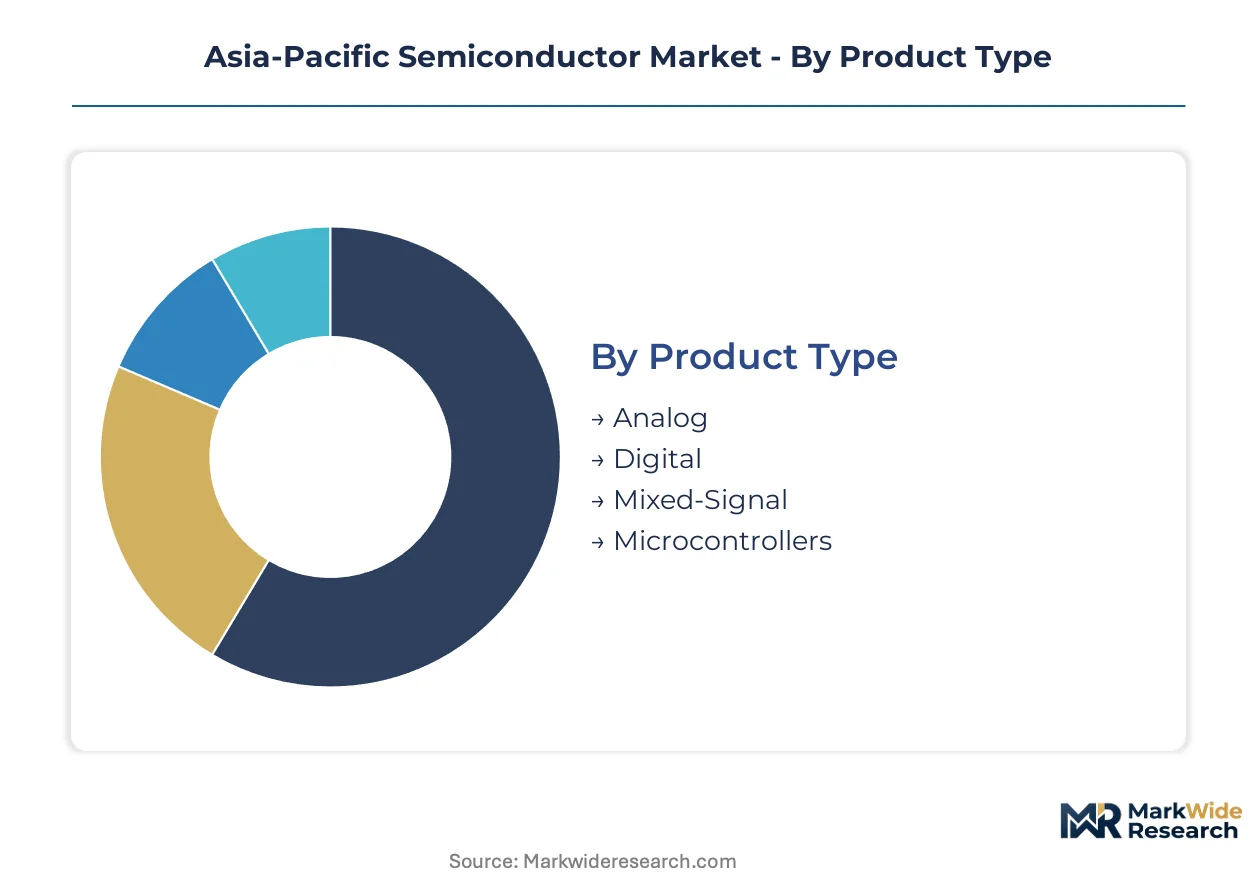
Segmentation in the Asia-Pacific semiconductor market reveals how margin pools concentrate across process nodes, end-use qualification tiers, and technology maturity curves. Foundries and IDMs allocate capacity based on these boundaries, with automotive-grade and advanced-node segments commanding disproportionate pricing power.
Product Type:
Margin pools concentrate in automotive-qualified and precision analog products where 36-month qualification cycles create supply scarcity.
- Analog:Power management ICs and signal conditioning devices fabricated on mature nodes dominate industrial and automotive supply chains. Demand concentrates in Japan's tier-one automotive OEMs where JIS Q 9001 certification creates 40% price premiums over commercial-grade equivalents.
- Digital:Logic devices at 7nm and below capture the majority of foundry capex allocation as AI accelerators and smartphone SoCs absorb leading-edge capacity. Taiwan's Hsinchu corridor anchors production where TSMC's N3E process locks in multi-year supply agreements with hyperscale cloud operators.
- Mixed-Signal:Data converters and sensor interface ICs bridge analog sensing with digital processing for industrial automation systems.
- Microcontrollers:Embedded control units for automotive body electronics and motor drives run on 40nm-90nm nodes with extended lifecycle commitments.
Analog holds installed capacity. Digital is rotating up the share rankings.
Technology:
Process differentiation separates cost-optimized legacy production from premium advanced-node manufacturing.
- CMOS:Complementary metal-oxide-semiconductor logic underpins 90% of digital IC production from 350nm legacy nodes to 3nm EUV-class manufacturing. South Korea's Samsung and SK Hynix deploy CMOS for memory and logic foundry services across DRAM, NAND, and SoC categories.
- GaN:Gallium nitride-on-silicon power devices enable 650V switching for EV onboard chargers and datacenter power supplies. Taiwan and South Korea foundries are expanding dedicated GaN lines as silicon carbide alternatives face substrate supply constraints.
- BiCMOS:Bipolar-CMOS integration serves precision analog and RF applications in telecommunications infrastructure.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for RF front-end modules and low-power IoT edge devices.
CMOS holds installed capacity. GaN is climbing the fastest.
End User:
Customer concentration patterns determine pricing leverage and contract structure across the region.
- Automotive:Electrification and ADAS compute are compressing qualification timelines while pulling capacity from consumer allocations. Japan's METI subsidies target domestic foundry expansion in Kyushu to secure captive automotive supply.
- Consumer Electronics:Smartphone and PC OEMs negotiate annual volume commitments with foundries, prioritizing density scaling and cost-per-transistor metrics over absolute performance.
- Telecommunications:5G baseband and RF infrastructure demand mixed-signal expertise with extended temperature range specifications.
- Industrial:Factory automation and power conversion systems require 10-15 year supply continuity that only established IDMs can guarantee.
Consumer Electronics holds installed capacity. Automotive is gaining share fastest.
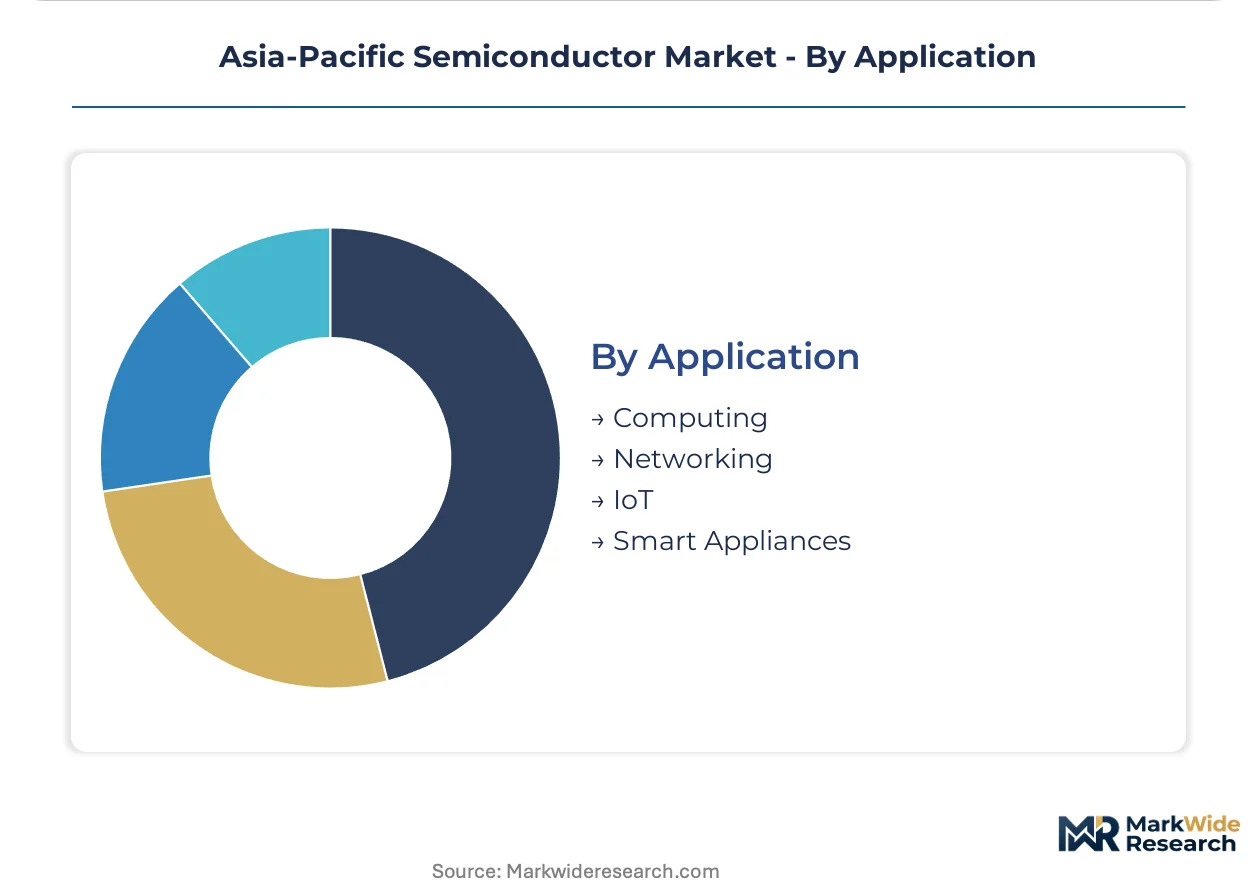
Application:
System architecture requirements dictate process selection and packaging technology.
- Computing:AI training and inference accelerators drive leading-edge node adoption with chiplet-based designs emerging as an architectural alternative to monolithic dies. Hyperscale operators in Taiwan's Hsinchu corridor negotiate direct foundry relationships bypassing traditional distribution.
- Networking:Datacenter switching and routing ASICs require high-speed SerDes integration at 7nm and 5nm nodes with advanced packaging for thermal management.
- IoT:Edge sensing and connectivity modules prioritize ultra-low power consumption over performance, favoring 22nm and older nodes with extended voltage ranges.
- Smart Appliances:Motor control and touch interface ICs for white goods and HVAC systems run on established 90nm-180nm processes with minimal mask layer counts.
Computing holds installed capacity. IoT is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators in Taiwan's Hsinchu corridor negotiate multi-year capacity agreements directly with foundries, bypassing traditional semiconductor distributors. Automotive OEMs in Japan and South Korea compress qualification timelines as electrification pulls capacity from consumer allocations. China's domestic procurement mandates fragment market access rules across the region.
Taiwan
AI accelerator and smartphone SoC demand concentrates in the Hsinchu Science Park cluster where advanced-node production anchors foundry margins. The National Development Council structures tax incentives for semiconductor R&D facilities in Taichung and Tainan. TSMC's N3E process leadership locks in dedicated capacity agreements with hyperscale operators spanning five-year horizons.
South Korea
High-bandwidth memory for AI training clusters drives capacity expansion at the Icheon and Pyeongtaek semiconductor complexes. The K-Chips Act structures 15-year depreciation schedules and facility investment tax credits that improve project IRRs for memory and logic expansions. Samsung Electronics anchors HBM3E supply through in-house packaging control while SK Hynix competes via specialized yield engineering.
Japan
Automotive-grade chip demand from tier-one OEMs redirects capital toward domestic foundry expansion in Kyushu and Tohoku. METI's Semiconductor Emergency Measures Act subsidizes reshoring investments to secure captive supply for electrification platforms. Tokyo Electron supplies process equipment from its base in Tokyo while domestic foundries rebuild quality systems for JIS Q 9001 certification.
China
Domestic IC procurement mandates under MIIT enforcement fragment qualification tracks and favor local design houses. GB standards for semiconductor procurement create parallel certification requirements that foreign suppliers must navigate. The Yangtze River Delta cluster around Shanghai maintains the highest concentration of legacy node capacity for industrial and automotive applications.
Vietnam
Backend assembly and test capacity expansion accelerates as China-plus-one strategies mature among OSAT investors. The Ministry of Planning and Investment offers land lease incentives for semiconductor packaging facilities in Bac Ninh and Ho Chi Minh City. Underpenetrated test infrastructure attracts capital from regional players seeking geographic diversification of supply chain risk.
Asia-Pacific Semiconductor Market Competitive Landscape
Player mix skews toward integrated device manufacturers and pure-play foundries with divergent capital allocation strategies. Memory specialists compete through vertical control over HBM stack architecture while logic foundries race for gate-all-around transistor leadership at 2nm-class nodes. Two strategic archetypes dominate: scale-driven capex leaders pursuing process-node leadership, and specialty analog players defending margin pools through extended qualification cycles. Competitive moves concentrate on capacity expansion and strategic partnerships for advanced packaging integration.
Within the foundry tier, Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation anchor logic production capacity. Samsung Electronics occupies a position exemplifying the integrated memory-logic model. SK Hynix represents the specialized high-bandwidth memory archetype competing through yield engineering rather than scale alone.
| Leading Market Players |
|---|
| Tokyo Electron |
| Powerchip Semiconductor Manufacturing Corporation (PSMC) |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| ASE Technology Holding |
| MediaTek |
| Samsung Electronics |
| United Microelectronics Corporation (UMC) |
| Tokyo Ohka Kogyo Co., Ltd. |
| SK Hynix |
| Others |
Pricing and Supply Chain Analysis
TSMC's 85% utilization rates at its N3E node establish price floors that second-tier foundries cannot match without bleeding cash. This scale concentration forces automotive chip buyers into cost-plus contracts indexed to neon gas and silicon wafer spot markets, while foundries extract premiums for JIS Q 9001-certified capacity.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate foundry pricing for automotive and industrial segments. Three-tier pricing structure across JIS Q 9001-certified, automotive-grade, and commercial-grade tiers separates tier-one OEM supply from secondary channels. Pricing pressure stems from legacy 200mm equipment scarcity forcing 300% premiums on refurbished tools. Consumer electronics OEMs exhibit highest price sensitivity, while automotive electrification platforms accept cost premiums for qualification-certain supply.
Supply Chain Analysis
Strategic stockpiling of Ukrainian-sourced neon and specialty gases has displaced just-in-time inventory norms across Japanese and South Korean fabs. Supply concentrates in Taiwan's Hsinchu corridor, South Korea's Icheon complex, and Japan's Kyushu cluster. Raw material dependencies center on silicon wafers, EUV photoresists, and high-purity neon. Single-source vulnerability to ASML's EUV lithography systems creates chokepoints for sub-7nm production ramps. Distribution runs through direct foundry relationships with hyperscale cloud operators, bypassing traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific semiconductors sit in early-cycle expansion as automotive electrification and AI accelerator demand outpace installed foundry capacity. Penetration tailwinds from GaN-on-silicon power devices and chiplet-based architectures create whitespace for differentiated entrants.
For Market Incumbents: Compound defensive moats through backward integration into specialty gas purification and captive 200mm equipment refurbishment. TSMC's N3E process leadership threatens Samsung's foundry ambitions, making yield engineering investment in gate-all-around transistors the critical lever for logic incumbents. Memory specialists must defend HBM3E stack architecture control against SK Hynix's yield-optimization challenge. For New Entrants and Emerging Players: Backend assembly service gaps in Vietnam's Bac Ninh corridor offer white-space entry points where incumbents under-serve OSAT demand. Malaysia's test infrastructure underpenetration provides the most penetrable geography for China-plus-one strategies. Foundry-less design houses targeting automotive-grade mixed-signal products can exploit 36-month qualification backlogs that freeze tier-two competitors from tier-one supply chains. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty analog players with JIS Q 9001 certification and 10-15 year supply continuity contracts. Long-term viability favors foundries with secured EUV equipment slots and domestic subsidy alignment. Acquisition targets should display process-node diversification across trailing-edge automotive and leading-edge AI accelerators. Watch ASML's order backlog as the inflection signal for advanced-node capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Expansion | METI subsidies in Japan's Kyushu region secure captive automotive supply for tier-one OEMs. |
| Advanced Packaging Integration | Hybrid bonding and TSV capabilities at ASE Technology unlock AI accelerator architectures beyond monolithic dies. |
| Backward Integration into Equipment | Tokyo Electron's domestic etch tool qualification reduces ASML dependency for South Korean memory makers. |
| Geographic Diversification | Vietnam and Malaysia backend capacity attracts OSAT investment under China-plus-one supply chain strategies. |
| Certification Investment | JIS Q 9001 quality system rebuilds enable Japanese foundries to re-enter tier-one automotive supply chains. |
Research Methodology
Operator-level perspectives from foundry operations directors, automotive Tier 1 procurement managers, OSAT facility planners, and METI policy officials anchored the qualitative base. Secondary validation drew from SEMI equipment spending reports, customs wafer import data, SEC filings from capital equipment suppliers, and JIS certification registry updates. Bottom-up capacity modeling triangulated against top-down end-use demand forecasts across the analysis window.
Sensitivity analysis tested forecast robustness against EUV equipment delivery delays, neon supply disruption scenarios, and automotive electrification penetration variance. Segmentation dimensions modeled include process node tier, end-use qualification level, substrate technology, and regional regulatory jurisdiction. CAGRs derived from equipment spending trajectories and foundry utilization trends, with explicit inputs from hyperscaler capex disclosure patterns and automotive platform electrification roadmaps.
Underlying assumptions cover sustained subsidy enforcement by METI and K-Chips Act administrators, with deviation risk concentrated in export control coordination between Japan, Netherlands, and US regulators. Forecasts reflect these conditions holding stable. Revision becomes warranted when EUV lithography system delivery backlogs exceed 24 months or when Chinese domestic procurement mandates expand beyond current GB standard enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Resistive RAM Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Gaas Wafer Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Discrete Semiconductor Market