
 High Reliability Semiconductor Market | 2026-2036
High Reliability Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
High Reliability Semiconductor Market Foresight
The gap between commercial-grade and radiation-hardened process nodes is narrowing, forcing suppliers to recalibrate design-for-reliability methodologies across the stack. Infineon Technologies AG leverages its automotive-qualified SiC fabrication expertise to extend into aerospace power management segments. Texas Instruments Incorporated anchors its position through proprietary BCD process technology that sustains extended temperature ranges for industrial control systems. Microchip Technology Inc. specializes in antifuse-based FPGA architectures that dominate mission-critical payload applications where configuration immunity matters.
High reliability semiconductors are electronic components engineered to operate across extreme temperature ranges, radiation environments, and mechanical stress conditions, typically manufactured on dedicated process flows with enhanced screening protocols such as burn-in testing and hermetic packaging. These devices serve sectors where failure carries catastrophic consequences, including orbital platforms, implantable medical equipment, and weapons systems. Power semiconductors built on silicon carbide substrates command premium positioning due to thermal performance advantages in electric aircraft propulsion and grid-scale inverters. Mixed-signal semiconductor demand is accelerating fastest in defense systems where analog front-ends must interface with digital signal processors under severe electromagnetic interference. MEMS-based inertial sensors remain a mature margin pool, with established suppliers capturing recurring revenue from platform lifecycle extensions in legacy aerospace programs.
The U.S. Department of Defense's Trusted Foundry Program and the Defense Federal Acquisition Regulation Supplement shape vendor eligibility for sensitive programs, effectively segmenting the supply base between cleared and non-cleared producers. Europe's CE marking requirements under the Radio Equipment Directive, alongside ESA's European Preferred Parts List, impose additional qualification burdens that filter out commodity-tier competitors. Japan's METI coordinates national production capacity for strategic components through designated critical technology partnerships. Stakeholders must monitor how evolving export control classifications around wide-bandgap substrates redraw competitive boundaries between allied and non-allied supplier networks.
Market Dynamics
Radiation-hardened process nodes now lag commercial CMOS by only two generations, collapsing the traditional reliability-versus-performance tradeoff that once protected incumbent suppliers from mainstream competition.
Growth Catalysts
- Satellite Constellation Deployment:NATO defense procurement agencies mandate radiation-hardened components for low-Earth orbit platforms, creating sustained demand for qualified foundry capacity.
- Federal Semiconductor Subsidies:The U.S. CHIPS Act directs capital toward domestic high-reliability fabrication, accelerating reshoring of trusted supply chains for sensitive applications.
- Silicon Carbide Substrate Maturation:Automotive-qualified SiC wafer supply chains now extend into aerospace power management, reducing qualification timelines for electric aircraft propulsion systems.
Market Restraints
- Qualified Foundry Concentration:Trusted fabrication for radiation-hardened devices concentrates among three U.S.-based facilities, creating single-source vulnerability for defense programs.
- Hermetic Packaging Cost Structure:Ceramic package substrates and gold wire bonding consume 40-60% of finished device cost, limiting price elasticity in cost-sensitive industrial segments.
- Export Control Friction:U.S. Commerce Department Entity List restrictions on wide-bandgap substrate technology fragment allied supplier networks, complicating multinational program participation.
Strategic Opportunities
- European Preferred Parts List Expansion:ESA qualification pathways for commercial-off-the-shelf high-reliability devices open procurement to non-traditional suppliers in member state programs.
- Medical Implant Convergence:Neurostimulation and cardiac device manufacturers seek automotive-grade reliability methodologies adapted to biocompatible packaging requirements.
- Digital Twin Qualification:Physics-based reliability simulation reduces empirical test cycles, compressing time-to-qualification for fabless entrants targeting aerospace derivative markets.
Industry Challenges
- Radiation Effects Engineering Talent Scarcity:Single-event upset modeling and total ionizing dose characterization expertise concentrates among retiring specialists at national laboratories.
- Dual-Use Certification Complexity:Simultaneous satisfaction of MIL-STD-883 and AEC-Q100 requirements demands redundant test flows that extend development timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Reliability Semiconductor Market |
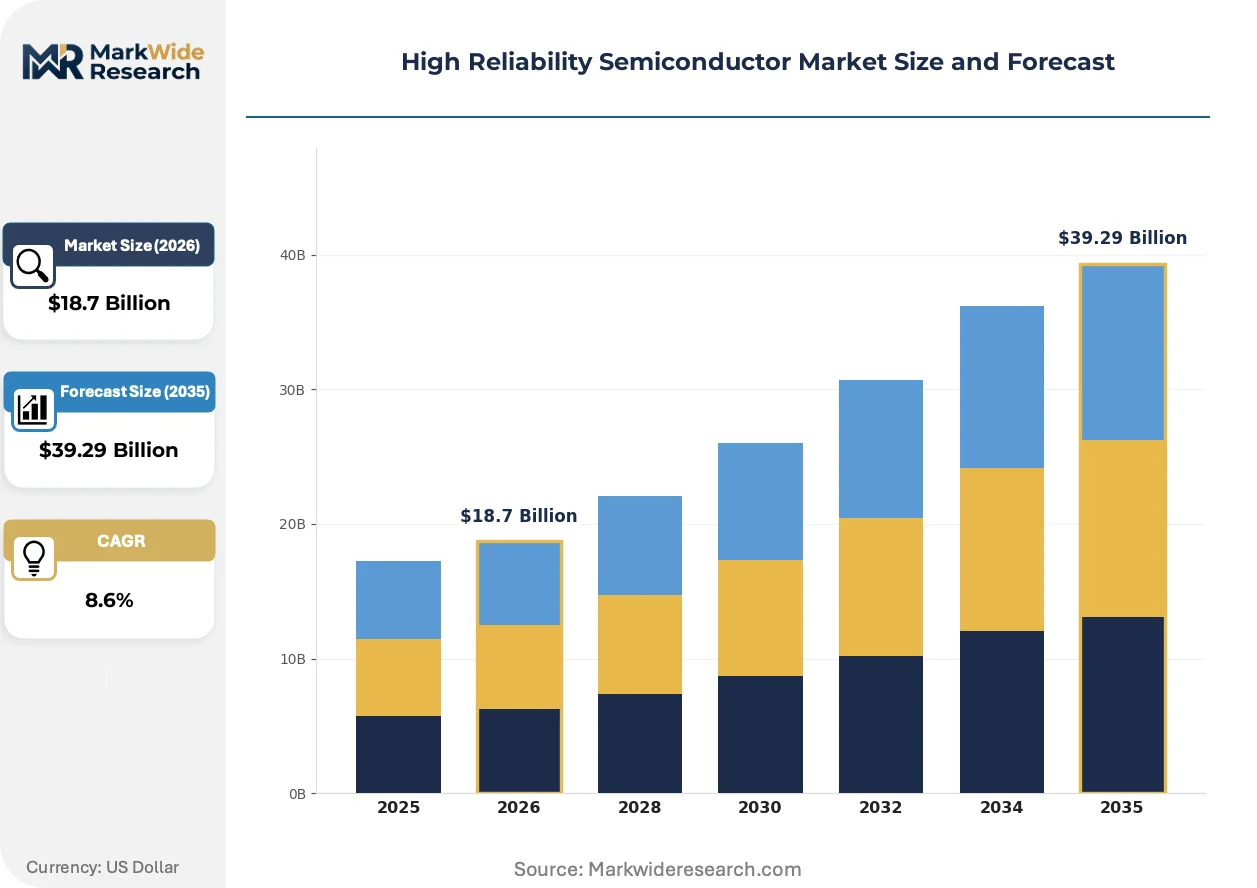
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Semiconductor, Digital Semiconductor, Mixed-Signal Semiconductor, Power Semiconductor Technology: Silicon, Gallium Nitride, Silicon Carbide, MEMS End User: Aerospace, Automotive, Industrial, Telecommunications Application: Defense Systems, Medical Devices, Space Applications, Renewable Energy Systems |
| Companies Covered | Infineon Technologies AG, Microchip Technology Inc., Texas Instruments Incorporated, Analog Devices, Inc., NXP Semiconductors N.V., Intel Corporation, Advanced Micro Devices, Inc. (AMD), GlobalFoundries Inc., L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Reliability Semiconductor Market Shifts & Advancements
Process convergence between commercial and radiation-hardened nodes is forcing architectural innovation at the system level rather than the transistor level, privileging design-for-reliability methodologies over brute-force hardening.
Antifuse-based FPGA architectures are hybridizing with SRAM-based reconfigurable logic to deliver configuration immunity for mission-critical payloads while retaining in-orbit reprogrammability for algorithm updates. Satellite operators at NASA and ESA now specify these hybrid architectures for earth observation platforms. The approach compresses supplier margins on pure antifuse products while expanding addressable market for mixed-technology vendors.
CE marking requirements under the EU Radio Equipment Directive now mandate electromagnetic compatibility testing that overlaps substantially with MIL-STD-461 specifications, creating pathway efficiencies for dual-qualified components. European prime contractors leverage this overlap to reduce qualification burden on commercial-off-the-shelf derivatives. The directive most affects mixed-signal suppliers targeting industrial automation and defense crossover applications.
Defense procurement agencies now unbundle long-term sustainment contracts from initial hardware awards, forcing component suppliers to price separately for lifecycle support and obsolescence management. Prime contractors at Lockheed Martin and Northrop Grumman negotiate these terms aggressively. The unbundling is most visible in U.S. Department of Defense programs where Weapons System Sustainment accounts now exceed procurement budgets.
High Reliability Semiconductor Market Segmentation
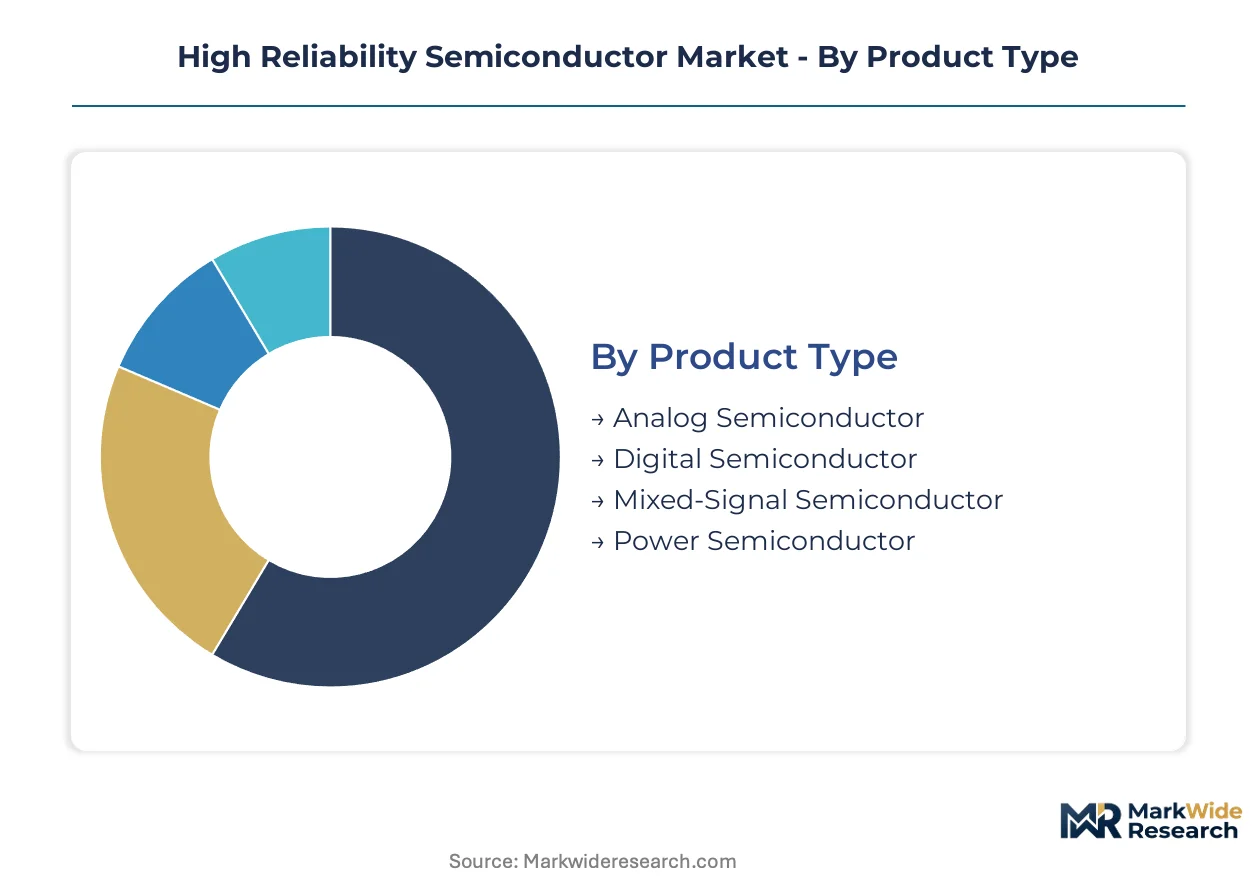
Segmentation in high reliability semiconductors reveals distinct qualification burdens and lifecycle economics across each dimension. Product type determines screening intensity. Technology choice dictates foundry access. End user and application shape certification pathways and sustainment contract structures.
Product Type:
After-sales-service intensity varies sharply across product categories, with analog and power devices demanding decades-long obsolescence management while digital components face faster refresh cycles.
- Power Semiconductor:Silicon carbide and gallium nitride devices operate at junction temperatures exceeding 175°C, enabling electric aircraft propulsion and grid-scale inverters. NATO satellite programs and U.S. Navy shipboard power systems drive procurement of radiation-hardened variants with hermetic ceramic packaging.
- Mixed-Signal Semiconductor:Data converters and interface ICs bridge analog sensor front-ends to digital processors under severe electromagnetic interference. Defense systems in NATO member states concentrate procurement where MIL-STD-461 compliance overlaps with CE marking requirements.
- Analog Semiconductor:Precision voltage references and operational amplifiers serve implantable medical equipment with biocompatible packaging mandates.
- Digital Semiconductor:Microcontrollers and logic devices face compressed qualification timelines as radiation-hardened nodes converge toward commercial CMOS generations.
By volume, Power Semiconductor leads. By growth pace, Mixed-Signal Semiconductor is ahead.
Technology:
Substrate material selection governs thermal performance ceilings and foundry qualification availability, with wide-bandgap technologies commanding premium positioning in aerospace power management.
- Silicon Carbide:Wide-bandgap substrates deliver breakdown voltages above 1200V with switching losses 70% below silicon equivalents. Automotive-qualified wafer supply chains now extend into electric aircraft propulsion at NASA and ESA, compressing traditional aerospace qualification timelines.
- MEMS:Micromachined inertial sensors and pressure transducers operate across military temperature ranges with established screening protocols. Legacy aerospace programs at Boeing and Lockheed Martin generate recurring sustainment revenue through platform lifecycle extensions.
- Silicon:Mature CMOS and bipolar processes anchor rad-hard digital and analog functions with proven total ionizing dose characterization.
- Gallium Nitride:High electron mobility transistors enable RF power amplification at millimeter-wave frequencies for satellite communications payloads.
Silicon retains volume dominance. Silicon Carbide posts the steepest expansion trajectory.
End User:
Customer type determines certification burden severity, with aerospace and defense programs imposing multi-year qualification timelines that filter out commodity-tier competitors.
- Aerospace:Commercial and military aviation platforms require DO-254 and DO-178C compliance for hardware and software. FAA certification pathways for electric aircraft propulsion systems are accelerating SiC power module adoption at Pratt & Whitney and GE Aviation.
- Automotive:AEC-Q100 qualification provides a pathway for medical implant suppliers seeking reliability methodologies without full aerospace screening. Cardiac device manufacturers at Medtronic and Boston Scientific leverage automotive-grade processes for biocompatible packaging derivatives.
- Industrial:Extended temperature range requirements for factory automation and grid infrastructure drive demand for BCD process technology.
- Telecommunications:Base station and satellite ground equipment require electromagnetic compatibility under EU Radio Equipment Directive mandates.
Aerospace commands the highest average selling prices. Automotive is expanding most quickly.
Application:
Application context dictates radiation tolerance requirements and configuration immunity needs, with space and defense programs specifying antifuse-based architectures for mission-critical functions.
- Defense Systems:Weapons platforms and electronic warfare systems mandate Trusted Foundry Program compliance with configuration-immune FPGA architectures. U.S. Department of Defense procurement now unbundles sustainment contracts from initial hardware awards, forcing separate pricing for lifecycle support.
- Space Applications:Low-Earth orbit constellations at NASA and ESA specify hybrid antifuse-SRAM FPGA architectures delivering immunity for mission-critical payloads with in-orbit reprogrammability for algorithm updates.
- Medical Devices:Implantable neurostimulation and cardiac equipment require biocompatible hermetic packaging with automotive-derived reliability screening.
- Renewable Energy Systems:Grid-scale inverters and offshore wind converters demand SiC power modules with extended temperature cycling endurance.
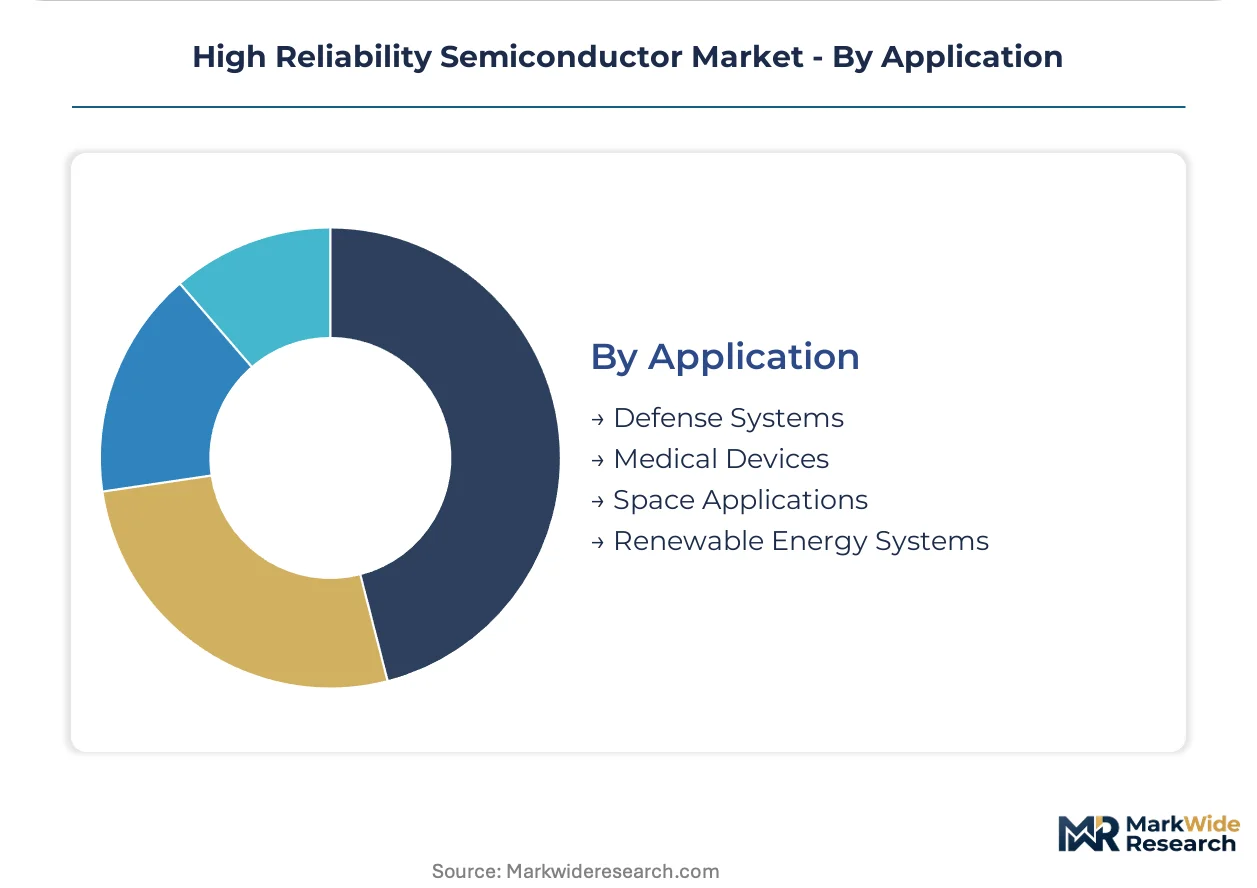
Defense Systems dominates procurement value. Space Applications is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies and federal subsidy programs concentrate demand among allied nations with trusted fabrication infrastructure. Radiation-hardened component qualification pathways now determine supplier eligibility across national security programs. Geographic expansion follows Trusted Foundry Program compliance and CHIPS Act capital deployment.
United States
The Department of Defense's Trusted Foundry Program and CHIPS Act subsidies anchor domestic high-reliability fabrication. Weapons System Sustainment accounts now exceed procurement budgets, forcing component suppliers to price lifecycle support separately. Arizona and Texas host expanding foundry capacity serving NASA satellite constellations and Navy shipboard power systems.
Germany
Automotive-qualified silicon carbide expertise extends into aerospace power management through ESA's European Preferred Parts List pathways. CE marking requirements under the Radio Equipment Directive overlap with MIL-STD-461 specifications, reducing qualification burdens for dual-use components. Bavaria's industrial corridor hosts suppliers targeting electric aircraft propulsion at Airbus Defence and Space.
Japan
METI coordinates national production capacity for strategic components through designated critical technology partnerships. Domestic suppliers leverage MEMS inertial sensor maturity for legacy aerospace platform sustainment. The Kyushu region maintains specialized screening facilities for hermetic packaging used in implantable medical equipment.
United Kingdom
Defense procurement agencies mandate radiation-hardened components for low-Earth orbit platforms under NATO interoperability standards. The UK Space Agency accelerates qualification timelines for commercial-off-the-shelf devices meeting ESA specifications. Harwell Space Cluster concentrates payload integration expertise serving earth observation programs.
France
ANSM biocompatibility requirements intersect with aerospace reliability methodologies for neurostimulation device manufacturers. ESA qualification pathways at CNES facilities enable non-traditional suppliers to access member state programs. Toulouse's aerospace corridor hosts prime contractors negotiating unbundled sustainment contracts for satellite platforms.
High Reliability Semiconductor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered qualification barriers that filter commodity-tier entrants. Trusted fabrication access concentrates among cleared producers serving defense programs, while fabless designers target commercial-off-the-shelf derivatives. Three archetypes dominate: vertically integrated foundry operators, mixed-signal specialists with proprietary process technology, and antifuse-based FPGA architects. Competitive moves center on strategic partnerships for qualification pathway access and portfolio diversification into adjacent reliability tiers.
Among European-based diversified suppliers, Infineon Technologies AG and NXP Semiconductors N.V. occupy positions bridging automotive and aerospace qualification methodologies. Microchip Technology Inc. represents the configuration-immune architecture specialist tier. These three exemplify how geographic origin and company structure correlate with trusted supply chain access across NATO defense programs.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Microchip Technology Inc. |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| NXP Semiconductors N.V. |
| Intel Corporation |
| Advanced Micro Devices, Inc. (AMD) |
| GlobalFoundries Inc. |
| L3Harris Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Underutilization at U.S.-based trusted foundries is compressing pricing power for radiation-hardened components while accelerating contract renegotiations toward cost-plus structures indexed to gold and ceramic substrate costs.
Pricing Analysis
Cost-plus contracts with gold-price indexation dominate procurement for defense programs, separating pricing across Trusted Foundry Program tiers, hermetic packaging grades, and unbundled sustainment terms. Price differentiation rests on certification burden and volume scale, with NATO satellite programs showing lowest sensitivity and industrial automation buyers facing acute pressure. Cost compression in ceramic packaging tiers is intensifying because automotive SiC supply chains are extending into aerospace. Medical implant manufacturers exhibit highest price sensitivity due to biocompatibility screening requirements.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities now anchor procurement relationships, with prime contractors at Lockheed Martin and Northrop Grumman pushing 90-120 day cycles onto component vendors. Geographic supply concentration centers on the United States, Germany, and Japan for trusted fabrication and hermetic packaging. Raw material dependencies draw from silicon carbide substrates, gold wire bonding, and ceramic package materials. Single-source vulnerability at three U.S. radiation-hardened foundries constitutes the dominant structural risk. Distribution runs through prime contractor integration channels rather than open market sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Weapons System Sustainment accounts now exceed procurement budgets, making lifecycle support and obsolescence management the fastest-expanding revenue layer for qualified suppliers.
For Market Incumbents: Harden antifuse FPGA margins by accelerating hybrid architecture roadmaps that blend configuration immunity with SRAM-based reprogrammability, directly countering fabless entrants targeting ESA commercial-off-the-shelf pathways. Deepen backward integration into hermetic ceramic packaging to capture the 40-60% cost concentration that currently flows to specialized substrate vendors.
For New Entrants and Emerging Players: ESA qualification pathways for commercial-off-the-shelf high-reliability devices represent the most penetrable entry point for non-cleared suppliers seeking access to European member state satellite programs. Medical implant convergence offers secondary white-space, where automotive AEC-Q100 methodologies adapt to biocompatible packaging without full aerospace screening. Go-to-market execution should anchor on digital twin qualification partnerships that compress empirical test cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon carbide substrate qualification for aerospace power management, favoring asset-light fabless designers over captive fabrication plays. Long-term viability over the next decade hinges on Trusted Foundry Program access or equivalent European clearance. The signal to watch is CHIPS Act capital deployment velocity at Arizona and Texas facilities, which indicates foundry capacity inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Program Certification | U.S. Department of Defense mandates create exclusive supplier pools for sensitive programs. |
| Silicon Carbide Qualification Pathway | Automotive wafer supply chains at Infineon accelerate aerospace power module timelines. |
| Digital Twin Reliability Simulation | Physics-based modeling reduces empirical test cycles for fabless entrants targeting derivatives. |
| Hybrid FPGA Architecture Development | Antifuse-SRAM blends satisfy NASA and ESA requirements for immunity plus reprogrammability. |
| Unbundled Sustainment Contract Pricing | Separate lifecycle support terms capture Weapons System Sustainment budget expansion. |
Research Methodology
Initial hypotheses were tested against primary input from radiation effects engineers at national laboratories, procurement officers at NATO defense agencies, foundry operations directors, and satellite payload integrators, then refined through secondary validation against SEC 10-K filings, ESA European Preferred Parts List databases, U.S. Department of Defense budget justification materials, and customs trade records for wide-bandgap substrate movements. Bottom-up and top-down triangulation cross-validated segment-level demand against aggregate federal subsidy deployment.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation modeled by product type, technology substrate, end user certification tier, and application radiation tolerance requirement. CAGRs were derived from capacity deployment schedules and procurement budget trajectories. Industry-specific forecast inputs incorporated Trusted Foundry Program qualification timelines and CHIPS Act capital allocation patterns.
Practitioners should monitor export control classification revisions and allied supplier network fragmentation for early signals of competitive boundary shifts. Forecasts reflect documented assumptions regarding federal subsidy continuity and defense procurement velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Organic Electronics Market
Semiconductors
Semiconductor IP Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Semiconductor Market
Semiconductors
Analog Semiconductor Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Smartphone Battery Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
India Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Europe Semiconductor Diode Market