
 ASEAN Semiconductor Market | 2026-2036
ASEAN Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Semiconductor Market Analysis
Vietnam's northern industrial zones is tilting toward memory module assembly and testing capacity. Micron Technology leverages its existing Bac Ninh footprint for DRAM packaging operations. Intel sustains its Ho Chi Minh City chip assembly plant as a strategic export node. ASE Technology Holding anchors backend services across multiple ASEAN locations.
Semiconductors are electronic materials, typically silicon or compound substrates like gallium arsenide, engineered with precise dopant concentrations to control conductivity between insulators and conductors; they form the basis of diodes, transistors, and integrated circuits that process, store, and transmit information across all electronic systems. Integrated circuits command the largest value share due to their complexity and silicon real estate requirements, while sensors represent the fastest-expanding category as automotive and industrial OEMs embed more environmental and positional awareness into their systems. Discrete semiconductors remain a mature, margin-compressed segment where cost-efficient Asian producers compete on scale.
Malaysia's Ministry of International Trade and Industry administers tax holidays and customs exemptions that directly shape where packaging and test houses locate capacity. Thailand's Board of Investment coordinates with the country's industrial estate authority to zone semiconductor activities away from flood-prone eastern corridors. Vietnam's Ministry of Planning and Investment negotiates land-lease terms that determine which foreign fabs establish backend operations. Stakeholders must weigh political risk premiums against incentive durability when committing to greenfield capacity in emerging ASEAN nodes.
Market Dynamics
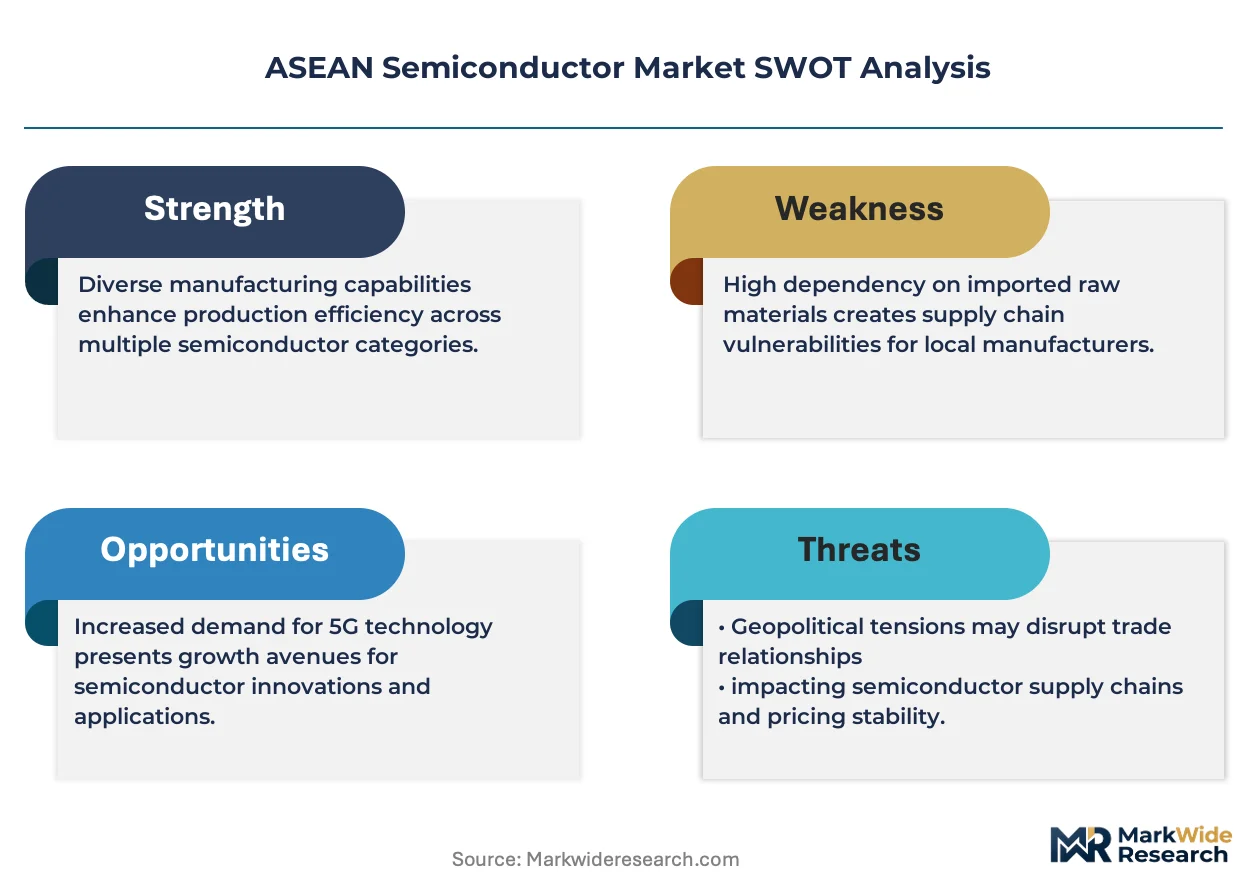
Backend packaging capacity is consolidating into ASEAN industrial corridors as geopolitical fragmentation fragments wafer fabrication across multiple jurisdictions, creating urgent demand for neutral-ground assembly and test services.
Growth Catalysts
- Thailand's EV manufacturing incentives:The Board of Investment grants eight-year corporate tax exemptions to electric vehicle component producers, pulling automotive-grade chip packaging demand into the Eastern Economic Corridor.
- Advanced packaging technologies:Fan-out wafer-level packaging and 2.5D/3D integration processes are penetrating high-performance computing and smartphone applications, requiring specialized ASEAN-based capacity.
- Vietnam's land-lease negotiations:The Ministry of Planning and Investment offers 50-year industrial zone leases with streamlined customs procedures, attracting memory module assembly investments from multinational semiconductor firms.
Market Restraints
- Silicon substrate cost volatility:Raw silicon wafer prices fluctuate with polysilicon feedstock availability from Chinese smelters, compressing margins for ASEAN-based discrete component foundries.
- Concentrated equipment supply:Lithography and deposition tools originate from a narrow base of Dutch and Japanese vendors, exposing ASEAN packaging houses to 12-18 month delivery lead times.
- Technical limitation in EUV proximity:No ASEAN facility currently operates extreme ultraviolet lithography, restricting the region to mature-node backend processes while front-end fabrication migrates elsewhere.
Strategic Opportunities
- Underpenetrated Philippines corridor:Subic Bay and Clark freeport zones offer unused industrial land with deepwater port access for importing bare wafers and exporting finished memory modules.
- Automotive functional safety certification:ISO 26262 compliance capabilities remain scarce across ASEAN, creating first-mover advantage for packaging houses that invest in automotive-qualified production lines.
- Silicon carbide power module assembly:Electric vehicle traction inverters require wide-bandgap semiconductor packaging expertise that legacy silicon houses have not yet developed.
Industry Challenges
- Cleanroom technician scarcity:Malaysia's Penang corridor competes with Singapore fabs for experienced contamination-control specialists, inflating wage premiums for Class 1000 environment operators.
- Legacy equipment integration:Brownfield packaging facilities in Johor struggle to retrofit 200mm toolsets for advanced copper-pillar bumping processes without complete line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Semiconductor Market |
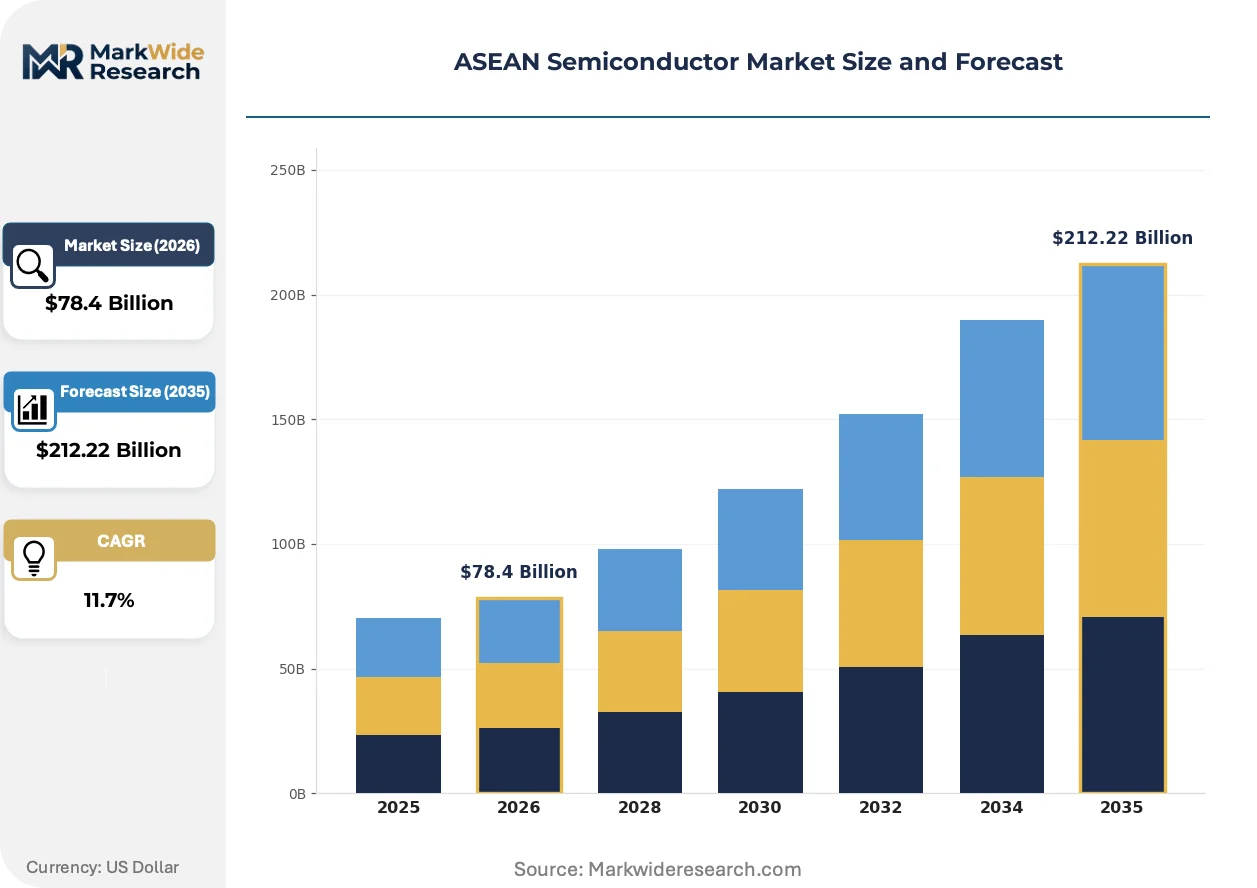
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $212.22 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete Semiconductors, Integrated Circuits, Optoelectronics, Sensors Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications Technology: Analog, Digital, Mixed-Signal, RF End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators |
| Companies Covered | Micron Technology, Inc., GlobalFoundries, Intel Corporation, STMicroelectronics, Texas Instruments, ASE Technology Holding Co., Ltd., Infineon Technologies AG, TSMC, Amkor Technology, Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Semiconductor Market Emerging Trajectories
Virtualization of semiconductor manufacturing workflows is collapsing traditional boundaries between design, fabrication, and test operations across Southeast Asian production networks.
Digital twin technology is virtualizing physical packaging and test floor operations, allowing ASE Technology Holding and peer vendors to simulate thermal stress profiles before committing actual die to bond wire assemblies. Automotive OEMs in Thailand's Eastern Economic Corridor now require virtual process qualification data prior to vendor selection, compressing traditional 18-month approval cycles. This virtualization is compressing capital deployment risk for greenfield ASEAN facilities by enabling remote commissioning of equipment prior to site readiness.
Malaysia's Ministry of International Trade and Industry revised its Pioneer Status incentive framework to require minimum 40% local engineering employment for tax holiday eligibility, directly altering hiring practices across Penang and Johor packaging clusters. The policy compresses the timeline for technology transfer from foreign parent entities to Malaysian subsidiaries. Packaging houses are responding by establishing dedicated training academies in partnership with Universiti Sains Malaysia to satisfy the mandate while maintaining process integrity.
Consolidated procurement of outsourced semiconductor assembly and test services is displacing fragmented multi-vendor arrangements among fabless design houses. Mid-tier integrated circuit developers in Singapore and Taiwan now negotiate single-source backend contracts covering wafer probe through final test, collapsing previous tiered supplier hierarchies. This concentration is most visible in Vietnam's Bac Ninh province, where memory module assemblers have absorbed functions previously performed by separate substrate vendors and logistics providers.
ASEAN Semiconductor Market Segmentation
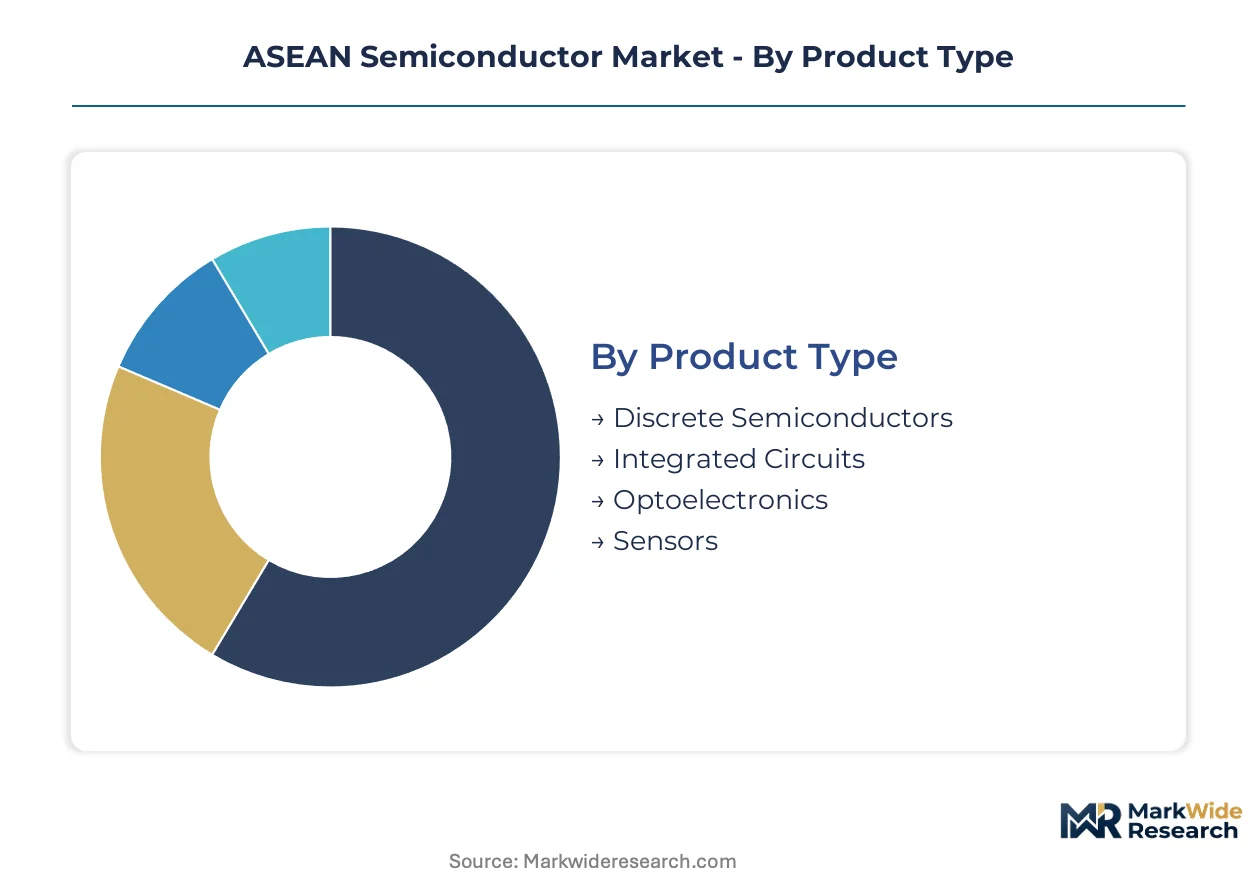
ASEAN's semiconductor landscape fragments across four critical dimensions that determine where packaging houses invest capital and how governments calibrate incentive structures. Product type distinctions separate mature-margin commodity production from advanced-node assembly services. Application verticals dictate cleanroom certification requirements and automotive qualification protocols.
Product Type:
Mature commodity segments coexist with emerging high-value categories across ASEAN backend facilities, creating divergent margin profiles and capital intensity requirements.
- Discrete Semiconductors:Individual diodes, transistors, and thyristors fabricated on silicon or silicon carbide substrates serve power management and switching functions. Malaysia's Johor corridor hosts volume assembly of standard discretes for industrial motor drives, though polysilicon feedstock volatility compresses foundry margins.
- Integrated Circuits:Complex arrays of transistors, resistors, and capacitors fabricated on single silicon dies demand the most sophisticated packaging real estate across ASEAN. Vietnam's Bac Ninh province concentrates DRAM module assembly and logic device packaging, driven by memory-hungry data center deployments across Asia-Pacific.
- Optoelectronics:Light-emitting diodes, laser diodes, and photodetectors convert electrical signals to optical output for communications infrastructure.
- Sensors:Microelectromechanical systems and environmental detectors capture motion, pressure, and chemical data for automotive and industrial systems.
Integrated circuits retain volume leadership across ASEAN packaging floors; sensors hold the steepest expansion curve as Thailand's EV manufacturers embed more positional and environmental awareness into vehicle platforms.
Application:
End-use concentration determines which ASEAN industrial zones attract packaging investment, with automotive qualification requirements filtering out legacy assembly houses.
- Consumer Electronics:Smartphones, tablets, and wearables drive high-volume, short-lifecycle chip demand. Thailand's Eastern Economic Corridor packages power management ICs for regional electronics brands, with fan-out wafer-level penetration accelerating for slim-form-factor devices.
- Automotive Electronics:Engine control units, advanced driver-assistance systems, and battery management modules require ISO 26262-compliant production lines. Penang's packaging clusters are racing to certify cleanrooms for functional safety as Thai EV incentives pull automotive-grade demand into ASEAN.
- Industrial Automation:Programmable logic controllers, robotics controllers, and motor drives operate in harsh environments requiring extended temperature-range packaging.
- Telecommunications:Baseband processors, RF front-ends, and optical transceivers serve 5G infrastructure deployment across Southeast Asia.
Consumer electronics commands the largest share of ASEAN packaging volume; automotive electronics is climbing the fastest as Thailand's Board of Investment incentives restructure regional demand patterns.
Technology:
Signal processing architecture separates cost-optimized analog production from digital logic requiring advanced interconnect density.
- Analog:Continuous signal processing circuits for power management and audio applications tolerate larger feature sizes and mature-node packaging. Malaysia's Penang corridor dominates analog IC assembly for industrial and automotive voltage regulators.
- Digital:Binary logic circuits for microprocessors and memory devices drive the most aggressive pitch scaling in ASEAN packaging. Vietnam's memory module assemblers handle digital DRAM and NAND flash packaging for export to global data center operators.
- Mixed-Signal:Combined analog-digital circuits for analog-to-digital converters and touch controllers bridge signal domains.
- RF:Radio frequency circuits for wireless communications require specialized substrate materials and electromagnetic shielding.
Digital technology captures the dominant share of ASEAN packaging revenue; mixed-signal is expanding most quickly as IoT edge devices proliferate across industrial and consumer applications.
End User:
Customer type determines contract structure, with OEM direct relationships displacing fragmented tiered supplier hierarchies across ASEAN backend services.
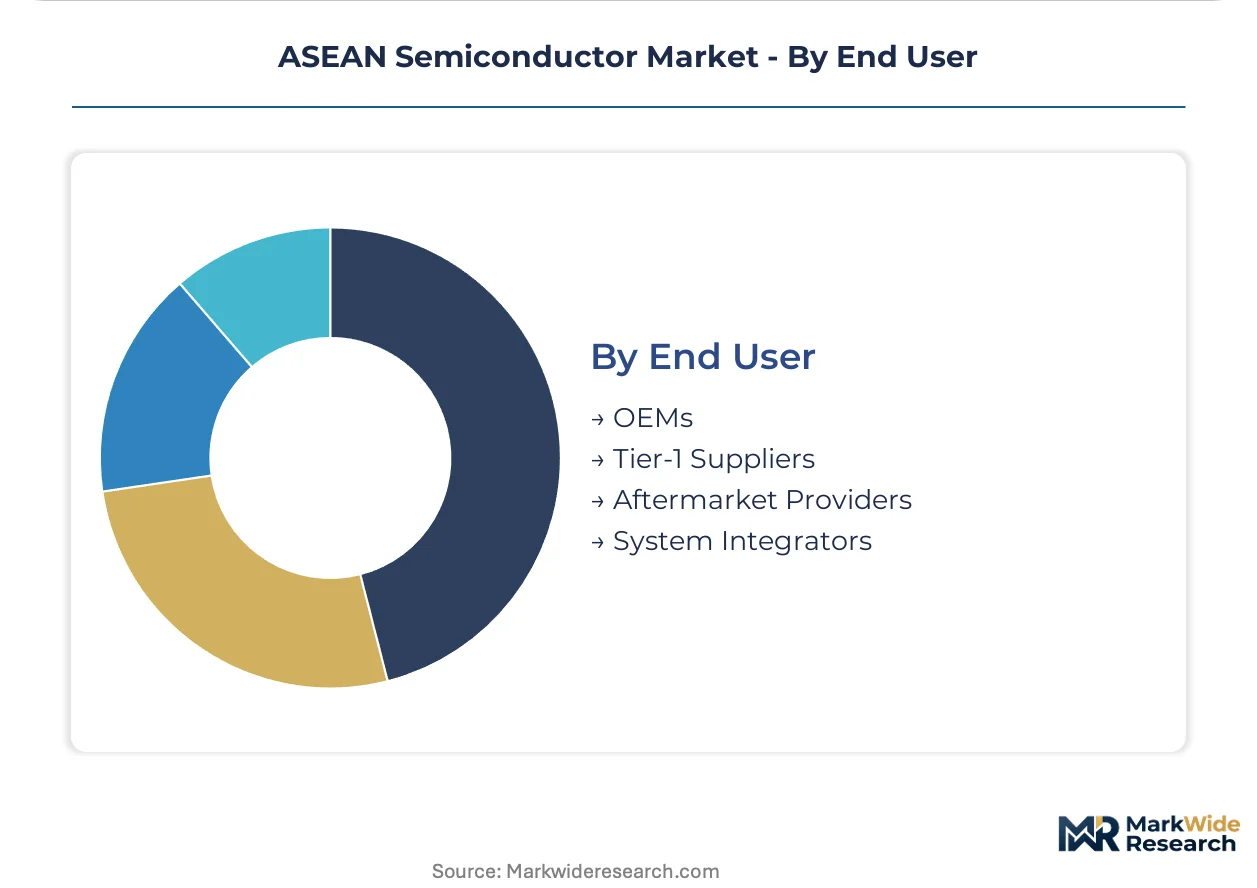
- OEMs:Original equipment manufacturers in consumer electronics and automotive verticals negotiate direct backend contracts covering wafer probe through final test. Vietnam's Bac Ninh province has absorbed substrate and logistics functions previously performed by separate vendors as OEMs consolidate procurement.
- Tier-1 Suppliers:Direct component suppliers to vehicle manufacturers and electronics brands require automotive-qualified packaging lines with traceability documentation. Thailand's Eastern Economic Corridor packaging houses serve tier-1 EV component producers qualifying for Board of Investment tax exemptions.
- Aftermarket Providers:Replacement component distributors and repair service networks source packaged dies for legacy system maintenance.
- System Integrators:Industrial automation and telecommunications infrastructure contractors specify semiconductors for custom equipment builds.
OEMs retain the largest contract value across ASEAN packaging services; tier-1 suppliers are gaining share fastest as automotive electrification concentrates purchasing power among qualified component vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Backend packaging capacity clusters in specific ASEAN industrial corridors as geopolitical fragmentation disperses wafer fabrication across multiple jurisdictions. Malaysia's Penang and Johor corridors anchor mature-node assembly services. Vietnam's northern provinces attract memory module investments through negotiated land-lease terms.
Malaysia
Penang's packaging clusters handle analog IC assembly for industrial voltage regulators while Johor concentrates discrete semiconductor volume for motor drive applications. Malaysia's Ministry of International Trade and Industry administers Pioneer Status tax holidays requiring 40% local engineering employment. Penang's Bayan Lepas Free Industrial Zone houses backend facilities serving automotive-qualified production lines.
Vietnam
Bac Ninh province anchors DRAM module assembly and logic device packaging driven by data center demand across Asia-Pacific. The Ministry of Planning and Investment negotiates 50-year industrial zone leases with streamlined customs procedures. Intel's Ho Chi Minh City chip assembly plant operates as a strategic export node for regional electronics supply chains.
Thailand
The Eastern Economic Corridor packages power management ICs for regional consumer electronics brands and automotive-grade chips for EV traction inverters. Thailand's Board of Investment grants eight-year corporate tax exemptions to electric vehicle component producers. Rayong and Chonburi provinces zone semiconductor activities away from flood-prone eastern corridors.
Singapore
Advanced wafer fabrication and front-end processes concentrate in Singapore's wafer fab parks, though backend services increasingly migrate to lower-cost ASEAN nodes. The Economic Development Board coordinates semiconductor investments through land allocation and research partnerships. Singapore's Pasir Ris and Woodlands industrial estates retain specialty packaging for high-reliability applications.
Philippines
Subic Bay and Clark freeport zones offer unused industrial land with deepwater port access for importing bare wafers and exporting finished memory modules. The Philippine Economic Zone Authority administers fiscal incentives for semiconductor assembly and test operations. Clark Freeport's aviation-linked logistics infrastructure supports just-in-time delivery to Asian electronics manufacturers.
ASEAN Semiconductor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The ASEAN backend packaging sector structures around three tiers: multinational IDMs operating captive assembly facilities, pure-play OSATs contracting with fabless designers, and emerging regional specialists serving discrete component markets. Strategic differentiation centers on automotive qualification capabilities, advanced packaging technology access, and geographic proximity to major electronics manufacturing clusters. Competitive moves concentrate on capacity expansion in Vietnam and Malaysia, plus technology licensing agreements for fan-out wafer-level packaging processes.
Among U.S.-based memory and logic specialists, Micron Technology, Inc. and Intel Corporation exemplify the integrated device manufacturer archetype with established ASEAN backend footprints. ASE Technology Holding Co., Ltd. represents the dominant pure-play OSAT model across multiple Southeast Asian locations. These three companies anchor the competitive landscape through divergent strategic postures: captive vertical integration versus outsourced service aggregation.
| Leading Market Players |
|---|
| Micron Technology, Inc. |
| GlobalFoundries |
| Intel Corporation |
| STMicroelectronics |
| Texas Instruments |
| ASE Technology Holding Co., Ltd. |
| Infineon Technologies AG |
| TSMC |
| Amkor Technology, Inc. |
| Others |
Supply Flow & Price Mechanics
Polysilicon feedstock volatility from Chinese smelters compresses margins for ASEAN-based discrete component foundries while simultaneously widening the spread between automotive-qualified packaging premiums and commodity assembly rates. This single-source dependency on upstream silicon refining shapes both the tiered pricing architecture across Penang and Johor corridors and the geographic configuration of wafer import logistics.
Pricing Analysis
Malaysia's Pioneer Status incentive framework dictates the pricing tier structure by mandating 40% local engineering employment for tax holiday eligibility, forcing packaging houses to internalize training costs that separate premium automotive-certified lines from standard consumer electronics assembly. Price differentiation hinges on ISO 26262 functional safety certification and volume scale, with OEM direct contracts commanding premiums over fragmented tier-1 supplier arrangements. Cost compression in mature discrete segments is intensifying because polysilicon spot volatility passes through to foundry margins. Fabless design houses in Singapore and Taiwan exhibit the highest price sensitivity, while automotive OEMs in Thailand's Eastern Economic Corridor prioritize qualification reliability over unit cost.
Supply Chain Analysis
ASE Technology Holding, Amkor Technology, and Intel's captive facilities concentrate outsourced semiconductor assembly and test capacity across Vietnam, Malaysia, and the Philippines. Raw silicon wafers, organic substrates, and gold bond wire feed from Taiwan, Japan, and South Korean suppliers. Single-source vulnerability in extreme ultraviolet lithography equipment from Dutch and Japanese vendors restricts ASEAN facilities to mature-node backend processes. Distribution runs through just-in-time hub arrangements in Singapore's free trade zones before final delivery to electronics manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN semiconductor backend is approaching a platform-economics inflection as virtualization collapses traditional boundaries between design, fabrication, and test operations, with digital twin interoperability becoming the new competitive moat.
For Market Incumbents: Harden automotive qualification capabilities against emerging pure-play OSAT entrants by accelerating ISO 26262 cleanroom certification in Penang facilities. Capture vertical integration opportunities in silicon carbide power module assembly before legacy silicon houses develop wide-bandgap expertise. Prioritize technology licensing agreements for fan-out wafer-level packaging to maintain process differentiation.
For New Entrants and Emerging Players: The Philippines' Subic Bay and Clark freeport zones offer unused industrial land with deepwater port access for importing bare wafers and exporting finished memory modules. Target automotive functional safety certification gaps across ASEAN, where qualified packaging lines remain scarce relative to Thai EV incentive-driven demand. Establish substrate and logistics integration capabilities to serve OEMs consolidating multi-function backend contracts.
For Investors and Strategic Acquirers: Malaysia's revised Pioneer Status employment mandate reshapes the acquisition landscape by compressing technology transfer timelines and elevating training infrastructure value. Focus on packaging houses with established automotive qualification pipelines and advanced copper-pillar bumping retrofit capabilities. Monitor cleanroom technician wage premiums in Penang as an early signal of capacity constraint inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional Safety Certification | ISO 26262-compliant cleanrooms in Penang capture Thai EV component demand. |
| Silicon Carbide Power Module Assembly | Wide-bandgap packaging expertise addresses electric vehicle traction inverter requirements. |
| Digital Twin Process Virtualization | Remote equipment commissioning collapses capital deployment risk for greenfield ASEAN facilities. |
| Local Engineering Training Academy Partnership | Universiti Sains Malaysia collaborations satisfy Malaysia's 40% employment mandate. |
| Substrate and Logistics Integration | Absorbed functions in Bac Ninh align with OEM consolidated procurement trends. |
Methodological Framework
Operator-level perspectives from packaging house operations directors, cleanroom engineering managers, automotive OEM procurement leads, and Ministry of Planning and Investment officials anchored the qualitative base. Secondary validation drew from Malaysia's Pioneer Status incentive filings, Vietnam's industrial zone lease registries, Thailand's Board of Investment approval records, and ASEAN customs trade data. Bottom-up capacity assessments across Penang, Johor, Bac Ninh, and Ho Chi Minh City facilities triangulated against top-down demand modeling from electronics manufacturing cluster outputs.
Scenario-bracketing around polysilicon feedstock volatility and EUV equipment availability shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type complexity tiers, application vertical certification requirements, technology node maturity, and end-user contract structure. CAGRs derived from installed packaging capacity expansion schedules and electronics manufacturing relocation patterns. Forecast inputs incorporated automotive electrification incentive durability and memory module demand from Asia-Pacific data center deployments.
Practitioners should monitor Malaysian local employment mandate enforcement, Thai EV component qualification timelines, and Vietnam land-lease renegotiation patterns for early signals of capacity relocation or incentive erosion. Quarterly review of cleanroom technician wage indices, polysilicon spot price movements, and automotive OEM backend contract consolidation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Smartphone Battery Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Semiconductor IP Market
Semiconductors
Semiconductor Clock Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Global FD-SOI Wafers Market