
 Semiconductor Bonding Market | 2026-2036
Semiconductor Bonding Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Bonding Market Outlook
Copper wire is pivoting from gold in high-volume packaging lines as substrate costs and thermal performance requirements intensify. Kulicke & Soffa Industries leverages its bonder installed base across memory and logic segments to sustain service revenue streams. BE Semiconductor Industries anchors European automotive packaging demand through precision die-attach systems. ASM Pacific Technology competes on flip-chip throughput metrics in advanced node foundries.
Semiconductor bonding encompasses the mechanical and electrical interconnection of dies to substrates or lead frames through thermosonic, thermocompression, or laser-assisted processes operating at sub-micron placement accuracy and temperatures ranging from 150°C to 450°C depending on material stack. Wire bonding retains the largest equipment installed base across legacy and mainstream nodes, though flip chip bonding captures expanding margin pools in high-performance computing and AI accelerator packaging where bump pitch compression below 40 micrometers demands thermocompression precision. Copper material type segments command volume leadership in cost-sensitive consumer and automotive applications, while gold persists in medical devices and aerospace-qualified reliability tiers where corrosion resistance and ball shear consistency outweigh raw material premiums.
The US EPA and OSHA frameworks govern volatile organic compound emissions and worker exposure limits in bonding wire manufacturing facilities, while China's SAMR enforces GB standards on semiconductor equipment safety and electromagnetic compatibility for domestic production incentives. REACH and RoHS in Europe restrict hazardous substances in packaging materials, compelling material suppliers to certify lead-free and halogen-free wire formulations. Stakeholders must monitor how carbon border adjustment mechanisms and equipment localization mandates in East Asian foundry economies reshape supplier qualification timelines and capital deployment priorities.
Market Dynamics
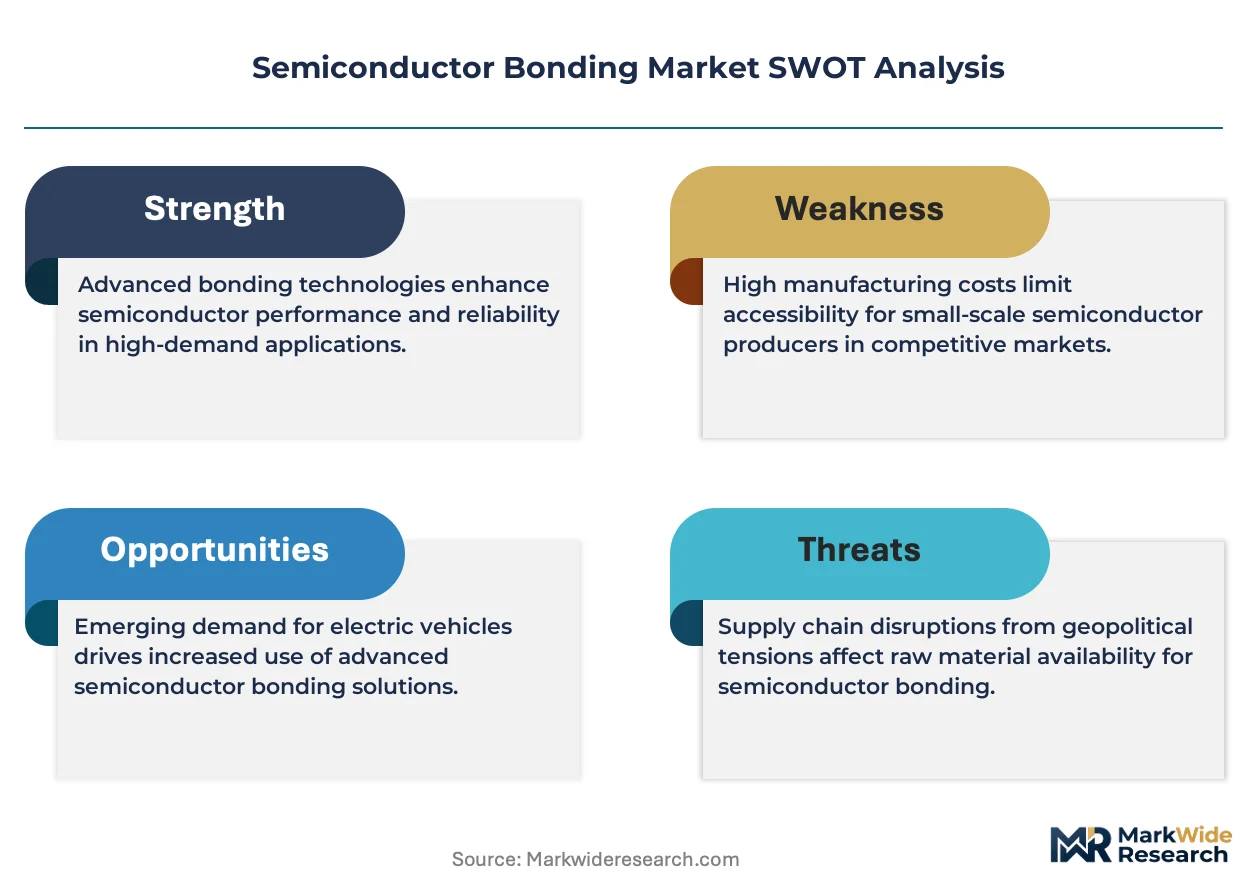
Copper wire substitution is compressing gold bonding volumes as China's MIIT dual carbon mandates and substrate cost pressures force packaging line retrofits across East Asian foundry clusters.
Growth Catalysts
- EV Powertrain Semiconductor Content:Automotive electronics OEMs are expanding wire bonding equipment orders to accommodate rising die counts in electric vehicle inverters and battery management systems.
- MIIT Dual Carbon Framework:China's Ministry of Industry and Information Technology emissions targets are accelerating copper wire qualification timelines in domestic packaging facilities.
- Flip-Chip Throughput Demands:Advanced node foundries are thermocompression bonding equipment to address bump pitch compression below 40 micrometers in AI accelerator packaging.
Market Restraints
- Copper Oxidation Sensitivity:Copper wire bonding requires inert atmosphere handling and specialized capillary designs that elevate process control costs versus gold alternatives.
- East Asian Equipment Concentration:Bonder manufacturing and service infrastructure clusters heavily in Taiwan, South Korea, and mainland China, creating geographic supply vulnerability.
- REACH and RoHS Compliance Burden:European hazardous substance restrictions compel material suppliers to certify lead-free and halogen-free wire formulations, extending qualification cycles.
Strategic Opportunities
- India Semiconductor Mission:The country's PLI scheme and fab incentives are attracting packaging investment that will require localized bonding equipment deployment and technical support infrastructure.
- Medical Device Reliability Tier:Gold wire bonding retains premium positioning in implantable and aerospace-qualified applications where corrosion resistance justifies material cost premiums.
- Thermocompression-Laser Hybrid Systems:Convergence of laser-assisted and thermocompression processes is enabling finer pitch interconnects for high-bandwidth memory stacking applications.
Industry Challenges
- Sub-Micron Placement Expertise Gap:Bonding equipment operation at 150°C to 450°C process windows demands specialized thermosonic process engineers that foundries struggle to recruit.
- Legacy Node Equipment Obsolescence:Wire bonder installed base depreciation schedules conflict with copper retrofit requirements, forcing capital allocation decisions between refurbishment and replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Bonding Market |
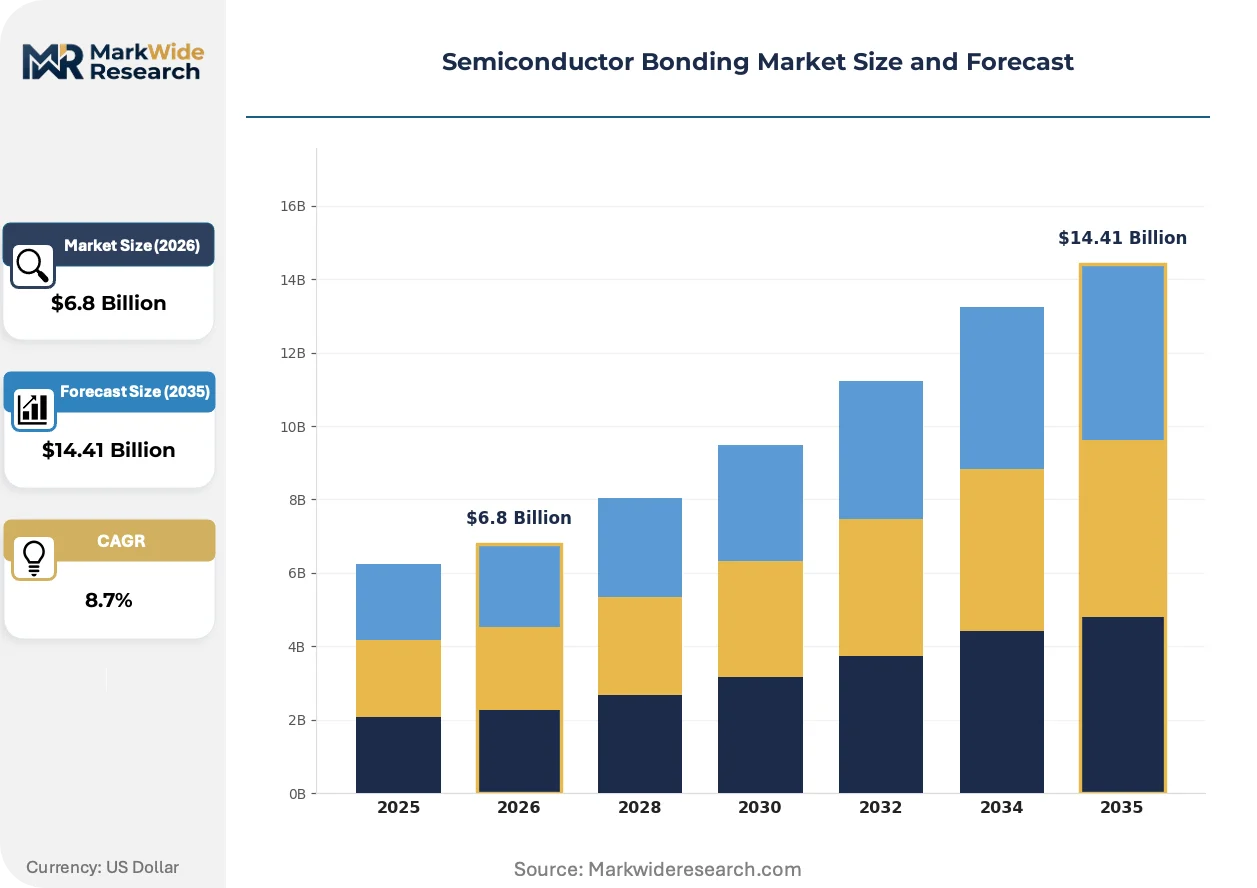
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bonding Technology: Wire Bonding, Flip Chip Bonding, Laser Bonding, Thermocompression Bonding Material Type: Copper, Gold, Aluminum, Silver Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Medical Devices End User: OEMs, Foundries, Electronics Manufacturers, R&D Institutions |
| Companies Covered | Kulicke & Soffa Industries, ASM Pacific Technology, BE Semiconductor Industries, EV Group, Shinkawa Ltd, SUSS MicroTec, Palomar Technologies, Fasford Technology, Shibaura Mechatronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Bonding Market Strategic Shifts
Bonding technology trajectories are diverging between legacy wire interconnects and advanced flip-chip architectures, with regulatory material mandates and thermal performance thresholds dictating equipment selection criteria.
Thermocompression bonding with non-conductive paste is unifying die-attach and underfill processes for high-performance computing packages. Memory and logic foundries in Taiwan and South Korea are adopting these integrated workflows at pilot scale. The structural consequence is unifying capital equipment procurement decisions around multi-function platforms rather than discrete bonder and dispenser purchases.
China's SAMR enforcement of GB standards on semiconductor equipment electromagnetic compatibility is compressing foreign supplier qualification timelines. Domestic packaging facilities must demonstrate compliance to access production incentives under the dual carbon framework. High-volume consumer electronics packaging lines in mainland China are responding by accelerating local equipment vendor partnerships.
Automotive electronics procurement is consolidating bonding equipment vendor relationships around service responsiveness metrics rather than upfront capital cost. Tier-1 automotive semiconductor suppliers are replacing transactional equipment purchases with lifecycle service agreements covering predictive maintenance and process optimization. This behavioral shift is most visible in German and Japanese automotive packaging corridors where zero-defect reliability requirements dominate supplier scorecards.
Semiconductor Bonding Market Segmentation
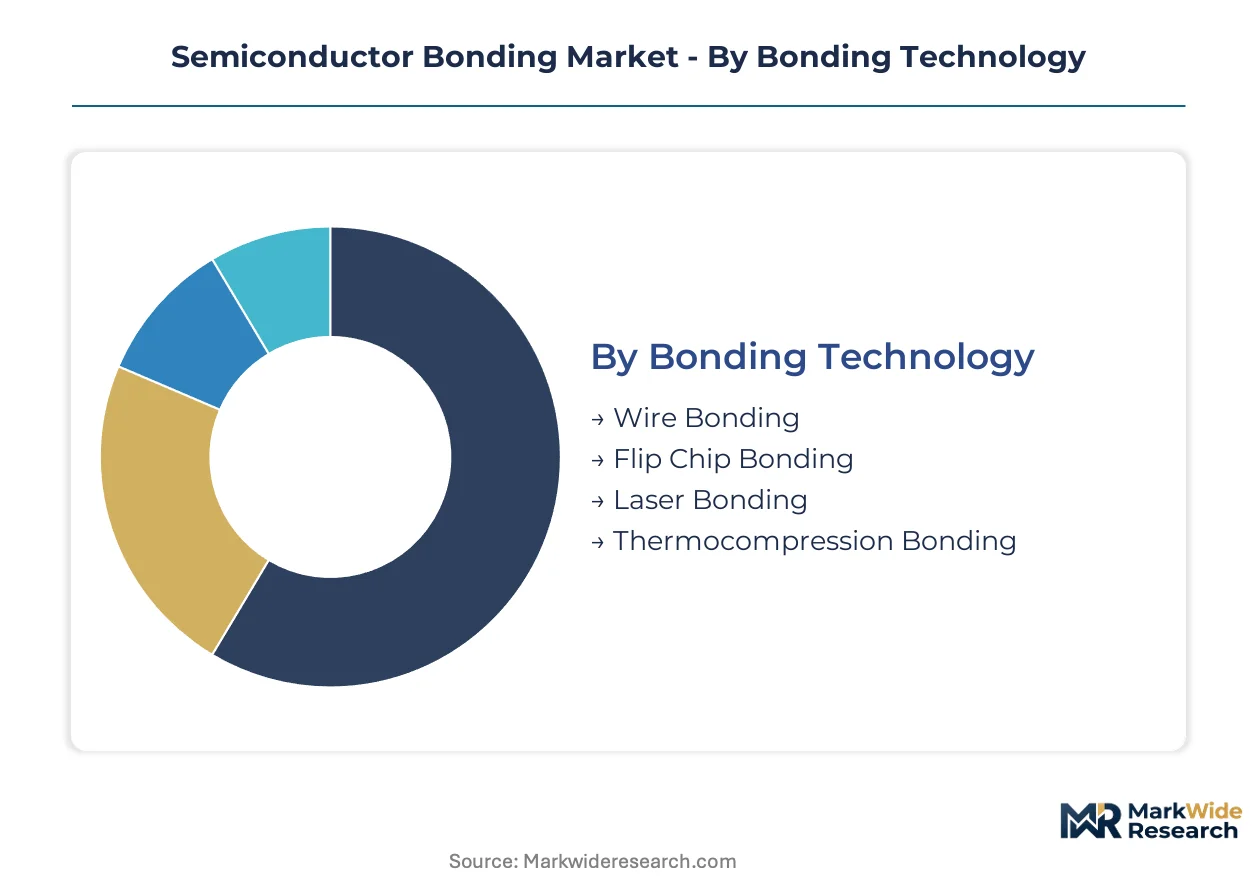
Semiconductor bonding equipment purchasing patterns diverge sharply across technology maturity, material cost structures, and end-use reliability requirements. Equipment vendors must calibrate product portfolios to serve both high-volume consumer packaging lines and precision-driven automotive qualification programs.
Bonding Technology:
Equipment buyers sort by throughput requirements, bump pitch tolerance, and thermal budget constraints rather than capital cost alone.
- Wire Bonding:Thermosonic interconnects using gold or copper wire dominate legacy node packaging and automotive power modules where 25-micron pitch tolerances suffice. Taiwanese memory foundries maintain the largest installed base, though copper retrofits are extending equipment lifecycles amid substrate cost pressures.
- Flip Chip Bonding:Thermocompression and mass reflow processes enable sub-40-micron bump pitches for AI accelerators and high-bandwidth memory stacks. South Korean logic foundries are expanding capacity fastest as advanced node packaging demands precision placement below 10 micrometers.
- Laser Bonding:Non-contact thermal processing for temperature-sensitive substrates and heterogeneous integration applications.
- Thermocompression Bonding:Fine-pitch die-to-wafer and chip-to-chip stacking for 3D-IC architectures requiring sub-5-micron alignment accuracy.
Wire bonding retains volume leadership today; flip chip bonding is climbing the fastest as advanced packaging penetration deepens.
Material Type:
Raw material selection hinges on conductivity requirements, oxidation sensitivity, and regulatory emissions frameworks governing smelter operations.
- Copper:Electrical conductivity exceeds gold by 40% while raw material costs run 80% lower, driving adoption in consumer and automotive volume lines. China's MIIT dual carbon mandates are compressing qualification timelines as domestic packaging facilities retrofit gold lines to access production incentives.
- Gold:Corrosion immunity and ball shear consistency sustain demand in implantable medical devices and aerospace-qualified tiers where failure rates must approach zero. Japanese automotive semiconductor suppliers maintain long-term supply agreements with dedicated wire vendors to ensure lot traceability.
- Aluminum:Cost-effective wedge bonding for power discrete and LED packaging applications.
- Silver:Sintering pastes and die-attach materials for high thermal conductivity power module assembly.
Copper leads volumes today; gold maintains premium positioning in reliability-tier applications.
Application:
End-use reliability specifications and thermal cycling requirements dictate equipment selection and process window validation protocols.
- Consumer Electronics:High-volume smartphone and wearable packaging drives demand for copper wire bonding with 150°C process windows. Mainland China packaging facilities serving Apple and Android OEMs concentrate orders in the Pearl River Delta and Yangtze River Delta corridors.
- Automotive Electronics:EV powertrain inverters and battery management systems require zero-defect wire bonding validated to AEC-Q100 standards. German Tier-1 suppliers are consolidating vendor relationships around service responsiveness metrics rather than upfront equipment pricing.
- Industrial Automation:Motor drive and power supply modules using heavy aluminum wire bonding for high-current applications.
- Medical Devices:Implantable pacemakers and diagnostic equipment mandate gold wire bonding with full lot traceability and FDA-compliant process documentation.
Consumer electronics leads volumes today; automotive electronics is expanding most quickly as EV semiconductor content rises.
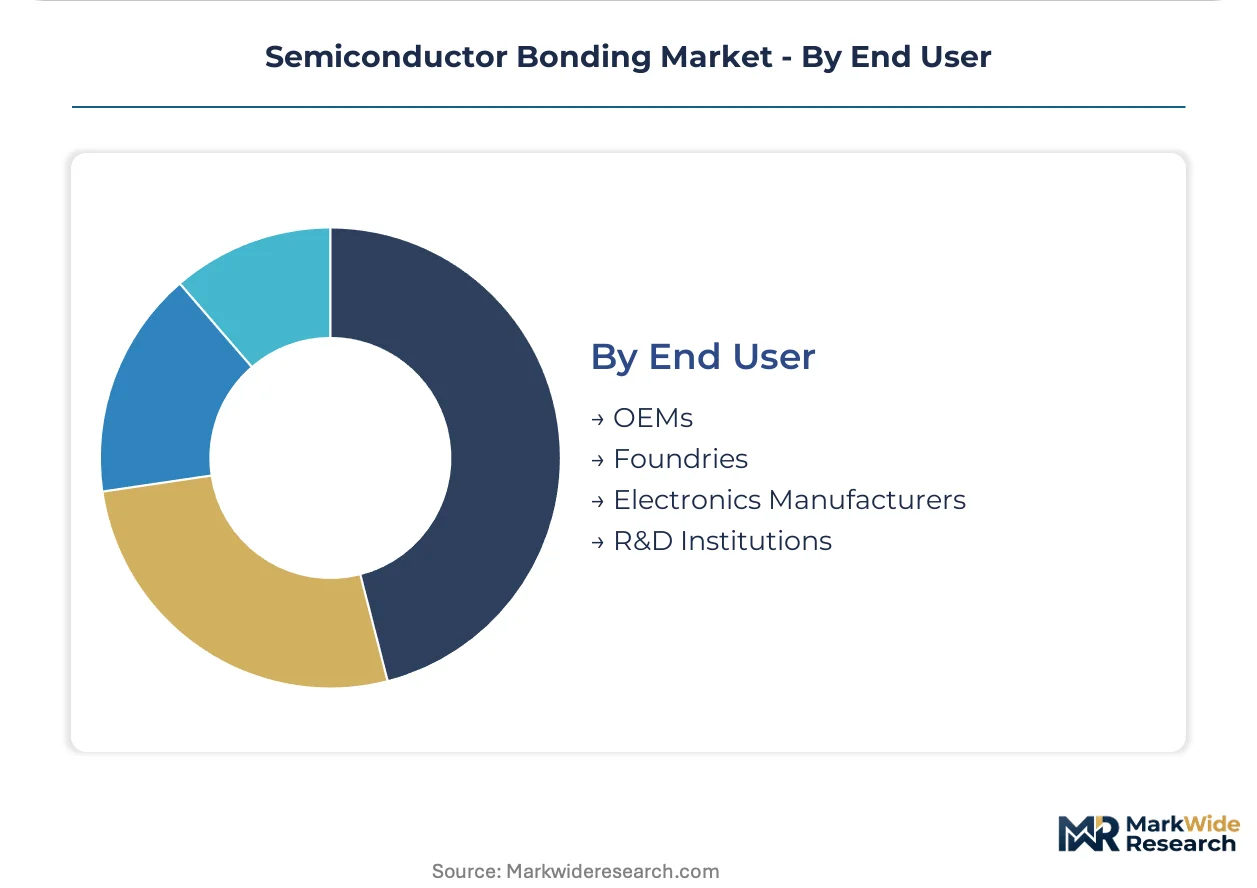
End User:
Procurement authority and technical specification control vary sharply across outsourced packaging and captive manufacturing models.
- OEMs:Automotive and medical device OEMs specify bonding equipment requirements in supplier qualification programs, often mandating specific wire metallurgies and process validation protocols. Tesla and BYD are expanding direct semiconductor packaging investment to secure supply chain control.
- Foundries:Taiwan Semiconductor Manufacturing and Samsung Foundry drive flip chip bonding equipment specifications for advanced node customers. These facilities concentrate thermocompression bonding capacity for CoWoS and similar 2.5D/3D integration schemes.
- Electronics Manufacturers:Contract assemblers and OSATs operating wire bonding lines for mid-range consumer and industrial applications.
- R&D Institutions:University and national laboratory pilot lines for emerging bonding processes and materials qualification.
Foundries lead equipment procurement volumes today; OEMs are gaining share fastest as vertical integration into packaging accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundry clusters in Taiwan, South Korea, and mainland China dominate semiconductor bonding equipment procurement, driven by advanced packaging capacity expansion and copper wire retrofit mandates. Equipment vendors concentrate service infrastructure around Hsinchu, Yongin, and Shanghai metropolitan corridors to support 24-hour fab uptime requirements. Regulatory pressure from China's MIIT dual carbon framework and Taiwan's industrial emissions standards is accelerating material qualification timelines across the region.
China
Mainland packaging facilities are retrofitting gold wire lines to copper as MIIT dual carbon goals compress qualification schedules for domestic production incentives. SAMR enforcement of GB standards on electromagnetic compatibility is forcing foreign equipment vendors to accelerate certification timelines. Yangtze River Delta clusters around Shanghai and Suzhou are absorbing the majority of new thermocompression bonding capacity for high-bandwidth memory applications.
Taiwan
TSMC and domestic OSATs are expanding flip-chip bonding capacity for CoWoS and 3D-IC integration schemes serving AI accelerator demand. The Industrial Development Bureau's emissions regulations are pushing packaging facilities toward copper wire adoption in legacy memory lines. Hsinchu Science Park anchors the densest concentration of wire bonder installed base globally, with equipment vendors maintaining dedicated technical support centers.
South Korea
Samsung Foundry and SK Hynix are driving thermocompression equipment specifications for sub-10-micron placement accuracy in advanced node packaging. METI-aligned industrial standards are shaping equipment qualification protocols for automotive semiconductor exports. Yongin and Pyeongtaek corridors concentrate the fastest-growing flip-chip bonding capacity as high-bandwidth memory stacking requirements intensify.
United States
Automotive electronics OEMs in Michigan and Texas are expanding captive packaging investment to secure EV powertrain semiconductor supply chains. EPA volatile organic compound regulations and OSHA worker exposure limits govern bonding wire manufacturing facility emissions. Phoenix and Austin metro areas are attracting advanced packaging investment as Intel and domestic foundries diversify manufacturing geography.
Germany
Infineon and Bosch are consolidating bonding equipment vendor relationships around zero-defect reliability requirements and service responsiveness metrics. REACH and RoHS restrictions on hazardous substances are compelling material suppliers to certify lead-free wire formulations. Bavaria and Baden-Württemberg automotive packaging corridors are replacing transactional equipment purchases with lifecycle service agreements covering predictive maintenance.
Semiconductor Bonding Market Competitive Environment
Global majors compete with regional champions across equipment technology tiers and service infrastructure density. The vendor landscape stratifies between precision-focused European specialists, high-throughput Asian equipment fabricators, and vertically integrated Japanese conglomerates. Three archetypes dominate: scale-driven throughput leaders serving memory foundries, precision specialists targeting automotive reliability tiers, and hybrid-platform vendors unifying die-attach and underfill processes. Competitive intensity centers on M&A for process technology access and strategic partnerships with materials suppliers to secure qualified wire formulations.
Among precision-focused European equipment specialists, BE Semiconductor Industries occupies a position exemplifying die-attach system integration for automotive packaging corridors. ASM Pacific Technology and Kulicke & Soffa Industries represent the throughput-driven archetype, with the former sitting within advanced node foundry supply chains and the latter anchoring service revenue streams across memory and logic installed bases. These three companies collectively illustrate how vendor positioning diverges between flip-chip precision metrics and wire bonding lifecycle service capture.
| Leading Market Players |
|---|
| Kulicke & Soffa Industries |
| ASM Pacific Technology |
| BE Semiconductor Industries |
| EV Group |
| Shinkawa Ltd |
| SUSS MicroTec |
| Palomar Technologies |
| Fasford Technology |
| Shibaura Mechatronics |
| Others |
Value Chain & Pricing Dynamics
China's MIIT dual carbon mandates gate qualified supply access for copper wire bonding equipment, forcing packaging facilities to complete retrofit certifications before premium-tier pricing privileges unlock under domestic production incentive schemes.
Pricing Analysis
Input-cost pass-through from copper wire feedstock and specialized capillary components shapes equipment pricing tiers. Three-tier pricing structure across premium, standard, and economy levels separates thermocompression precision systems from legacy wire bonders and refurbished units. Price differentiation hinges on bump pitch capability certification and geographic proximity to East Asian service hubs. Pricing pressure stems from copper oxidation handling requirements elevating process control costs. Consumer electronics OSATs exhibit highest price sensitivity; medical device OEMs accept premium positioning for gold wire reliability tiers.
Supply Chain Analysis
Dual-sourcing requirements from automotive Tier-1 suppliers mandate multi-supplier qualification for bonding wire and capillary consumables. Equipment manufacturing concentrates in Taiwan, South Korea, and Japan. Raw material dependencies span high-purity copper cathodes, gold bullion, and precision-machined ceramic capillaries. Single-source vulnerability runs through specialized thermocompression bonding head assemblies. Distribution runs through direct foundry relationships in Hsinchu and Yongin corridors, supplemented by regional service depots in Shanghai and Austin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper wire substitution in high-volume packaging lines compresses input costs while flip-chip precision tiers capture expanding margin pools, positioning the market for sustained margin expansion.
For Market Incumbents: Deploy lifecycle service agreements as the primary retention lever. Automakers in Germany and Japan now score suppliers on predictive maintenance response times rather than capital cost. Incumbents should consolidate channel control over refurbished equipment flows to counter emerging Asian equipment fabricators. Certification investment in MIIT-compliant copper retrofit protocols secures access to Chinese production incentives. For New Entrants and Emerging Players: Thermocompression-laser hybrid process development offers a technology-first wedge into high-bandwidth memory stacking applications. White-space targets include India's Semiconductor Mission packaging corridors and medical device reliability tiers where gold wire traceability requirements deter commodity competition. A equipment-as-a-service go-to-market angle aligns with automotive procurement shifts toward operational expenditure models. For Investors and Strategic Acquirers: Valuations sit cheapest among precision-focused European die-attach specialists with automotive certification depth. Long-term viability centers on exposure to advanced packaging node migration rather than legacy wire bonding depreciation cycles. The signal to watch is Intel and domestic foundry advanced packaging capacity announcements in Phoenix and Austin, which would reconfigure North American equipment demand geography.| Strategic Initiative | Industry Significance |
|---|---|
| Copper Wire Retrofit Certification | MIIT compliance unlocks Chinese production incentive access for packaging facilities. |
| Thermocompression-Laser Hybrid Development | Sub-5-micron alignment capability addresses high-bandwidth memory stacking requirements. |
| Lifecycle Service Agreement Expansion | Predictive maintenance contracts align with German automotive zero-defect procurement criteria. |
| India Semiconductor Mission Localization | Technical support infrastructure deployment captures PLI-scheme packaging investment flows. |
| Medical Device Reliability Tier Positioning | Gold wire traceability protocols secure implantable pacemaker and aerospace-qualified demand. |
Study Parameters
Bottom-up foundry capacity modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with packaging process engineers, OSAT procurement directors, automotive Tier-1 supplier quality managers, and semiconductor equipment service technicians combined with secondary validation from SEC filings, SEMI equipment market data, MIIT production incentive disclosures, and foundry capex announcements. Triangulation between demand-side installation schedules and supply-side manufacturing output ensures cross-verified volume estimates.
Historical trendline analysis of wire bonder and flip-chip equipment shipments established baseline growth patterns across the projection horizon. The analytical framework segments by bonding technology, material type, application, and end-user procurement authority, with additional modeling across regional foundry cluster expansion timelines. CAGRs derive from equipment replacement cycles intersecting with copper retrofit mandates and advanced packaging node penetration curves. Forecast inputs include EV powertrain semiconductor content trajectories and AI accelerator packaging demand from cloud hyperscalers.
The model holds under sustained East Asian foundry concentration and gradual copper qualification timelines; deviation in MIIT enforcement intensity or automotive zero-defect standard revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Smartphone Battery Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Resistive RAM Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
North America Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market