
 X-Ray Lithography Equipment Market | 2026-2036
X-Ray Lithography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Lithography Equipment Market Analytics
Semiconductor manufacturing is consolidating its position as the dominant end-use vertical for x-ray lithography equipment, displacing slower-growing research institution procurement. ASML leverages its established extreme-ultraviolet expertise to anchor adjacent x-ray development programs in Dutch and Taiwanese facilities. SUSS MicroTec specializes in substrate bonding and alignment systems that bridge legacy optical and emerging x-ray process flows. Canon U.S.A. competes through precision optics heritage adapted for next-generation mask imaging requirements.
X-ray lithography equipment employs short-wavelength electromagnetic radiation—typically 0.4 to 5 nanometers—to pattern semiconductor wafers with sub-50nm resolution, bypassing the diffraction limits that constrain deep-ultraviolet systems. The technology serves critical commercial purposes in fabricating advanced memory chips, photonic devices, and MEMS structures where extreme precision outweighs throughput constraints. Maskless lithography configurations command premium positioning due to their elimination of costly reticle sets, while nanoimprint lithography variants attract development funding for high-volume replication of nanoscale features. Full-field lithography systems retain structural importance in pilot-line environments where wafer-scale uniformity validates process transfer.
Japan's METI coordinates national x-ray lithography consortia under semiconductor reindustrialization mandates, while the FDA oversees radiation safety certification for equipment deployed in U.S. biomedical microfabrication facilities. REACH compliance in Europe restricts hazardous material content in vacuum chamber components and x-ray source housings, elevating design costs for non-compliant suppliers. Stakeholders must monitor divergence between Japan's JIS standards and emerging ISO protocols for source stability metrics, as alignment between these frameworks will determine cross-border equipment qualification timelines.
Market Dynamics
East Asian semiconductor manufacturers are redirecting capital toward x-ray lithography architectures as extreme-ultraviolet equipment availability tightens, compressing qualification timelines for alternative patterning technologies.
Growth Catalysts
- Maskless lithography maturation:Elimination of reticle fabrication costs accelerates pilot-line adoption among memory chip producers seeking sub-10nm resolution without EUV dependency.
- Japan's METI semiconductor revival framework:National consortia under METI coordination channel public-private funding into domestic x-ray source development and mask infrastructure.
- Photonics device fabrication:Silicon photonics foundries in Taiwan and South Korea deploy full-field x-ray systems for waveguide patterning where edge placement precision exceeds optical limits.
Market Restraints
- Specialized vacuum component sourcing:REACH compliance in Europe restricts hazardous material content in chamber housings, elevating design costs for non-compliant suppliers.
- Source stability standard divergence:Misalignment between Japan's JIS protocols and emerging ISO metrics prolongs cross-border equipment qualification timelines.
- Throughput limitations:X-ray systems pattern wafers at rates substantially below deep-ultraviolet alternatives, constraining high-volume logic chip deployment.
Strategic Opportunities
- Biomedical microfabrication expansion:FDA radiation safety certification pathways for U.S. facilities open diagnostic sensor and implantable device applications.
- MEMS structure replication:Nanoimprint lithography variants attract development funding for high-volume replication of nanoscale mechanical features in automotive pressure sensors.
- Consolidated foundry procurement:Samsung and SK Hynix in South Korea's foundry corridor are expanding sub-10nm pilot lines with captive x-ray capacity.
Industry Challenges
- Specialized technician scarcity:Vacuum system maintenance and synchrotron source operation require expertise concentrated in national laboratory ecosystems.
- Legacy optical integration friction:Hybrid fabs must bridge alignment systems between established deep-ultraviolet workflows and emerging x-ray process flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Lithography Equipment Market |
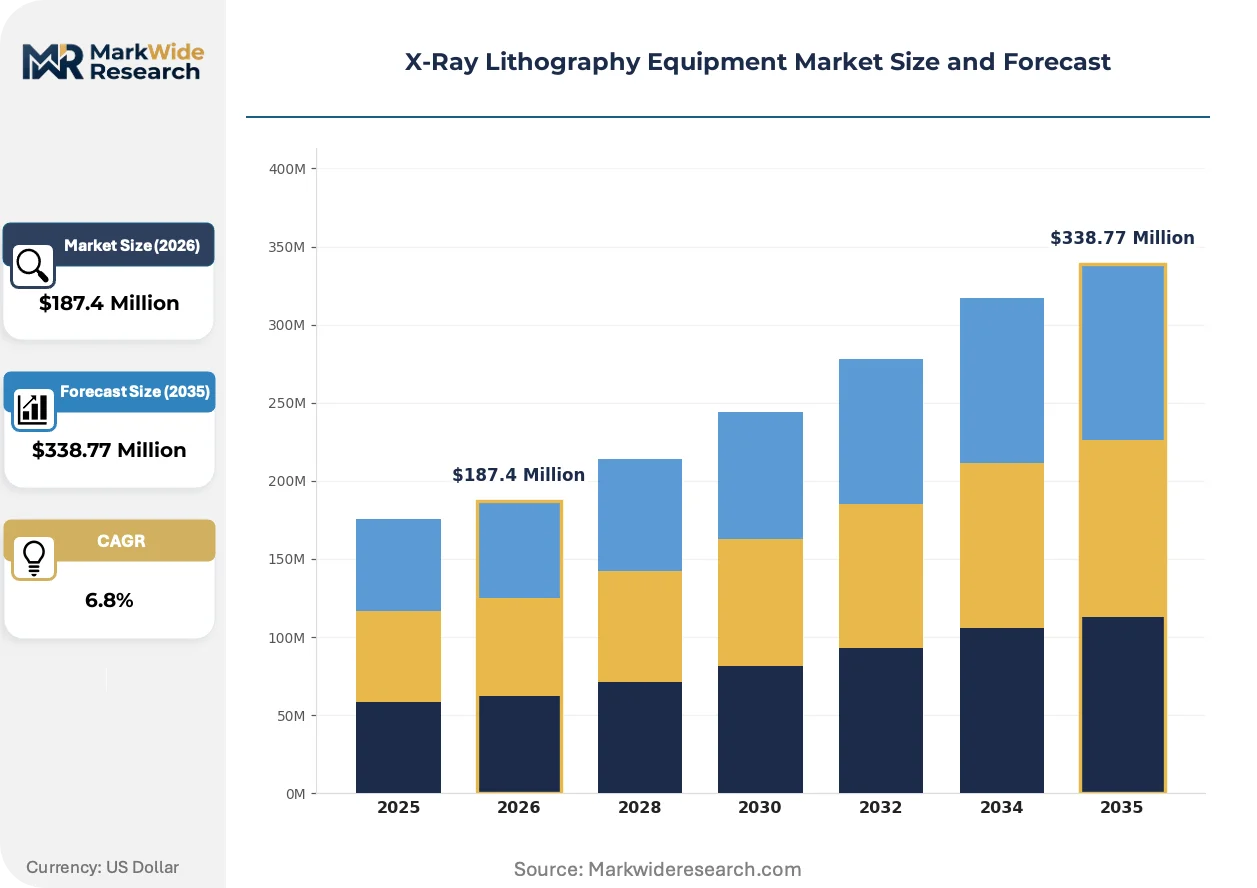
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Sources, Masks, Substrates, Control Systems Technology: Maskless Lithography, e-Beam Lithography, Full-Field Lithography, Nanoimprint Lithography End User: Semiconductor Manufacturers, Research Institutions, Electronics Companies, Automotive Suppliers Application: Chip Design, Circuit Fabrication, Wafer Testing, Microfabrication |
| Companies Covered | Nabity Lithography, Optnics Precision, ASML, Nanonics Imaging, NIL Technology, SUSS MicroTec, Rolith, Raith GmbH, Canon U.S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Lithography Equipment Market Evolving Landscape
Patterning technology selection is bifurcating between throughput-optimized optical systems and precision-optimized x-ray architectures, with equipment vendors restructuring development roadmaps around this divergence.
Compact synchrotron-based x-ray sources are decentralizing access to high-brightness illumination for semiconductor research facilities previously dependent on shared national laboratory beamlines. Materials science departments at U.S. and Japanese universities are installing laboratory-scale sources for mask characterization and resist development. This diffusion is compressing innovation cycles by eliminating beamtime allocation bottlenecks and enabling iterative process optimization.
REACH restrictions on fluorinated compounds are forcing redesign of vacuum chamber seals and source cooling loops in equipment destined for European fabs. Manufacturers are qualifying perfluoropolyether alternatives and metal-bellows sealing architectures to maintain base pressure specifications. South Korean and Taiwanese export units face parallel compliance verification, extending factory acceptance test durations.
Equipment procurement is consolidating under direct foundry-engineering relationships, displacing traditional distributor channels for x-ray lithography systems. Samsung and TSMC are negotiating source-code access and customization rights as standard contract terms. This disintermediation concentrates vendor accountability while fragmenting aftermarket service ecosystems across East Asian manufacturing clusters.
X-Ray Lithography Equipment Market Segmentation
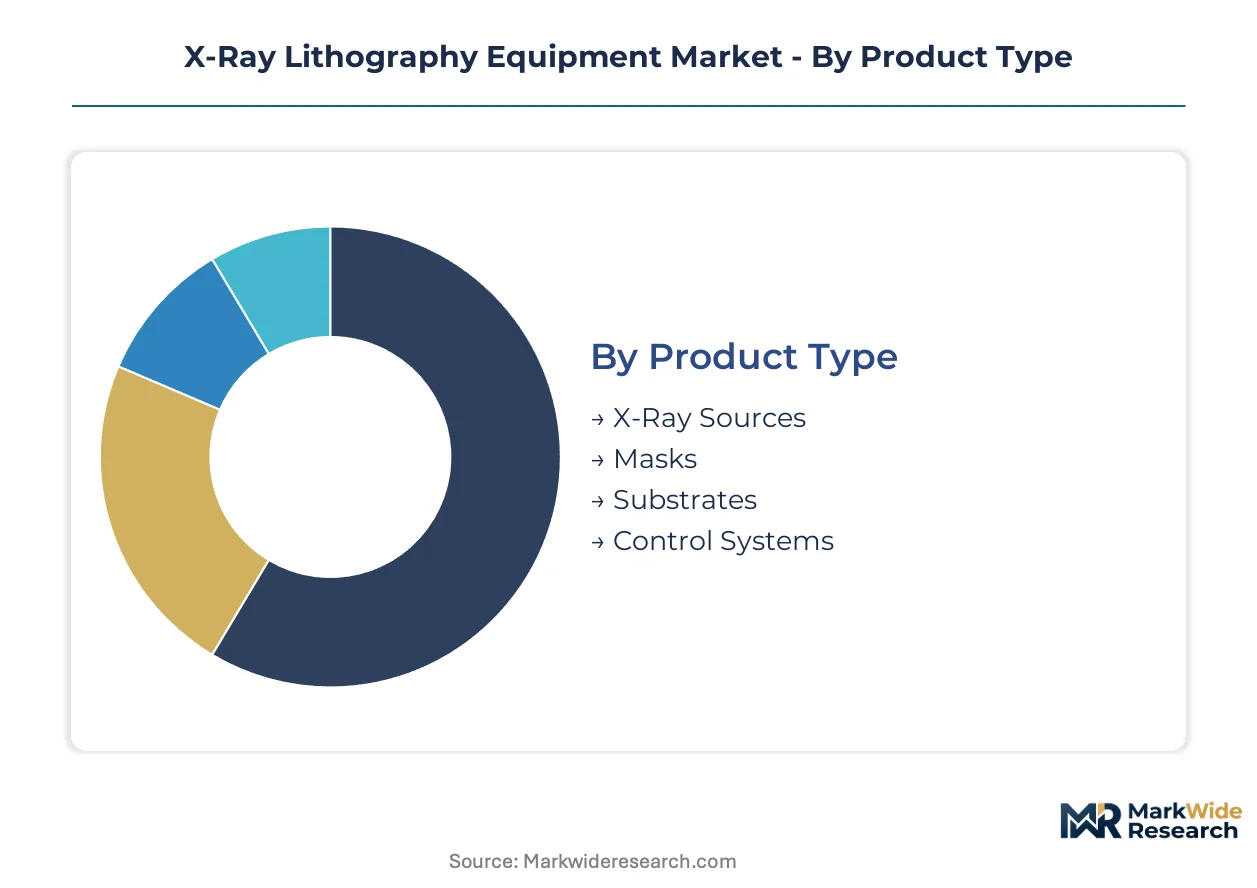
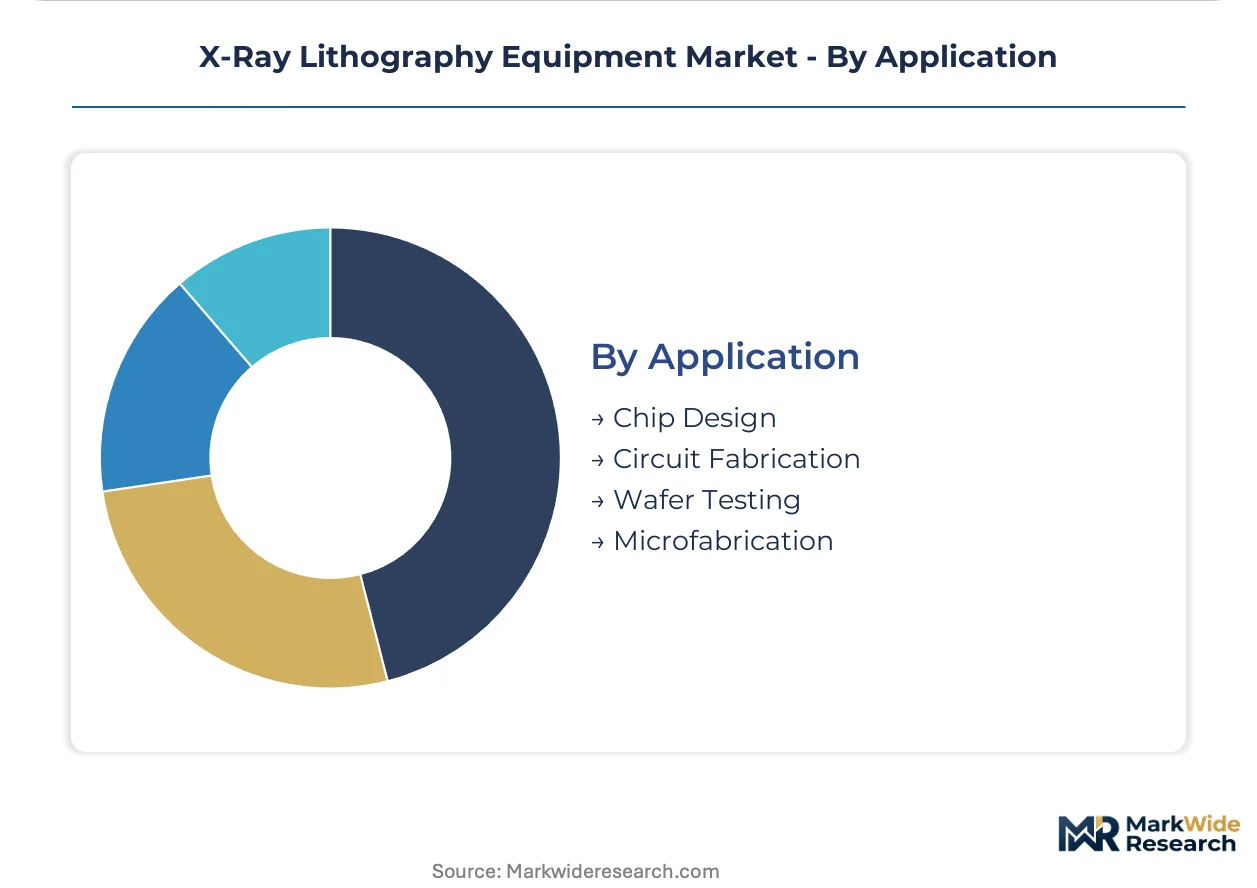
X-ray lithography equipment segmentation reveals how procurement priorities diverge between high-volume memory foundries and precision-focused research installations. Upgrade cycles vary dramatically across technology tiers, with maskless systems requiring more frequent source replacement than full-field alternatives.
Product Type:
Equipment refresh timelines differ substantially across component categories, with vacuum-sealed sources demanding more frequent replacement than static optical elements.
- X-Ray Sources:Compact synchrotron and laser-produced plasma generators supply 0.4-5 nanometer illumination for sub-50nm patterning. South Korean foundries in Samsung's Pyeongtaek cluster prioritize source brightness stability for sub-10nm pilot lines, driving premium procurement of liquid-metal-jet alternatives.
- Masks:Absorber-patterned membranes with tungsten or tantalum features define circuit geometries with edge placement precision below 2 nanometers. Japanese consortia under METI coordination fund domestic mask blank production to reduce reliance on imported reticle substrates.
- Substrates:Silicon wafers with specialized surface preparation for x-ray resist adhesion.
- Control Systems:Real-time alignment and overlay correction electronics bridging source-to-wafer positioning.
X-Ray Sources sits at the top of the volume ranking, with Control Systems climbing the fastest as fabs automate overlay correction.
Technology:
Cost tier stratification separates maskless configurations commanding premium positioning from full-field systems serving pilot-line validation needs.
- Maskless Lithography:Direct-write patterning eliminates reticle fabrication costs entirely through programmable beam steering. Memory chip producers in SK Hynix's Icheon facilities deploy these systems for sub-10nm development, accepting throughput penalties for pattern flexibility.
- e-Beam Lithography:Focused electron beams achieve sub-10nm resolution through electrostatic deflection of charged particles. Research institutions in Japan's Tsukuba science city favor hybrid e-beam/x-ray workflows for resist characterization.
- Full-Field Lithography:Wafer-scale exposure through stationary masks suits process transfer validation.
- Nanoimprint Lithography:Mechanical replication of nanoscale features attracts automotive pressure sensor funding.
Full-Field Lithography dominates installed base volume, though Maskless Lithography expands most quickly among memory foundries.
End User:
Customer type determines procurement scale, with captive semiconductor fabs consolidating multi-system orders against fragmented research institution purchasing.
- Semiconductor Manufacturers:Integrated device foundries and memory houses operate dedicated x-ray pilot lines for technology node migration. Taiwan's Hsinchu corridor fabs negotiate source-code access and customization rights as standard contract terms.
- Research Institutions:National laboratories and university materials science departments install laboratory-scale sources for iterative resist development. U.S. Department of Energy facilities share beamtime allocation for external mask characterization.
- Electronics Companies:Specialized photonics and sensor producers seeking precision without foundry-scale throughput.
- Automotive Suppliers:MEMS pressure sensor fabricators qualifying nanoimprint replication for high-volume mechanical features.
Semiconductor Manufacturers anchor procurement volume, while Automotive Suppliers gain share fastest as MEMS integration accelerates.
Application:
Application maturity varies from established circuit fabrication workflows to emerging microfabrication frontiers in biomedical devices.
- Chip Design:Physical verification and layout optimization using x-ray proximity correction algorithms precedes mask ordering. Samsung's Austin design center validates sub-10nm geometries through simulation-to-hardware correlation.
- Circuit Fabrication:Pattern transfer from mask to wafer through x-ray exposure and subsequent etching defines transistor and interconnect structures. South Korean foundries compress qualification timelines as EUV equipment availability tightens.
- Wafer Testing:Non-destructive inspection of buried structures using x-ray transmission imaging.
- Microfabrication:Biomedical sensor and implantable device patterning under FDA radiation safety protocols.
Circuit Fabrication leads application volume, with Microfabrication ascending fastest through diagnostic sensor demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting x-ray lithography equipment procurement toward jurisdictions with streamlined radiation safety certification pathways and coordinated public-private funding mechanisms. Compliance cost differentials between REACH-regulated European markets and East Asian industrial policy zones are accelerating foundry investment decisions.
South Korea
Samsung Electronics and SK Hynix are expanding captive x-ray pilot lines in Pyeongtaek and Icheon to circumvent EUV equipment bottlenecks. The Ministry of Trade, Industry and Energy channels tax incentives toward domestic source development under the K-Semiconductor Belt initiative. Foundry engineering teams in the Seoul Capital Area negotiate direct source-code access with equipment vendors as standard procurement terms.
Japan
METI coordinates national consortia funding mask blank production and compact synchrotron source development to reduce import dependency. JIS standards for source stability metrics diverge from emerging ISO protocols, complicating cross-border qualification timelines for multinational equipment suppliers. Tsukuba science city research institutions favor hybrid e-beam and x-ray workflows for resist characterization studies.
United States
Department of Energy national laboratories share beamtime allocation with external mask characterization projects, compressing innovation cycles for domestic semiconductor research. FDA radiation safety certification pathways enable biomedical microfabrication applications in diagnostic sensors and implantable devices. Materials science departments at Stanford and MIT are installing laboratory-scale sources previously restricted to shared synchrotron facilities.
Taiwan
TSMC negotiates customization rights and engineering co-development agreements as standard contract terms for x-ray pilot line equipment. The Industrial Technology Research Institute coordinates public-private consortia for photonics device fabrication where waveguide patterning precision exceeds optical lithography limits. Hsinchu corridor fabs are consolidating multi-system orders under direct vendor relationships, displacing traditional distributor channels.
Germany
REACH restrictions on fluorinated compounds are forcing equipment redesigns for vacuum chamber seals and source cooling loops destined for European fabs. The Federal Motor Transport Authority's automotive sensor standards are accelerating MEMS pressure sensor qualification using nanoimprint lithography variants. Fraunhofer Institutes in Dresden and Munich are validating metal-bellows sealing architectures as perfluoropolyether alternatives.
X-Ray Lithography Equipment Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors secure foundry engineering relationships and source-code access agreements. The vendor base clusters around three archetypes: precision optics heritage firms adapting mask imaging systems, substrate bonding specialists bridging optical and x-ray process flows, and direct-write technology developers eliminating reticle costs. Consolidation pressures are intensifying as captive procurement at Samsung and TSMC fragments aftermarket service ecosystems. Technology licensing and geographic expansion represent the two dominant competitive vectors for mid-scale participants seeking scale.
Within the precision optics tier, ASML and Canon U.S.A. occupy positions anchored by established extreme-ultraviolet expertise adapted for adjacent x-ray development. SUSS MicroTec exemplifies the substrate bonding and alignment specialist archetype, bridging legacy optical workflows with emerging x-ray process requirements. Raith GmbH represents the direct-write technology vector, serving research institutions with programmable beam steering configurations that eliminate reticle fabrication costs entirely.
| Leading Market Players |
|---|
| Nabity Lithography |
| Optnics Precision |
| ASML |
| Nanonics Imaging |
| NIL Technology |
| SUSS MicroTec |
| Rolith |
| Raith GmbH |
| Canon U.S.A. |
| Others |
Value Network & Pricing Analysis
Captive source development by South Korean and Japanese foundries anchors both supply security and pricing power for x-ray lithography equipment, compressing margin capture for vendors lacking direct engineering relationships with Samsung or SK Hynix.
Pricing Analysis
Direct-to-OEM discounts dominate equipment procurement as Samsung and TSMC negotiate source-code access and customization rights as standard contract terms. Three-tier pricing structure across premium maskless systems, standard full-field configurations, and economy research-grade units reflects certification grade and after-sales service bundling. Cost compression in research-grade tiers is intensifying because laboratory-scale synchrotron sources are decentralizing access previously restricted to national facilities. Memory foundries exhibit lowest price sensitivity given EUV equipment bottlenecks, while university materials science departments face capital constraint pressure.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers and German precision component manufacturers, with vacuum chamber seals and source cooling loops drawing from Fraunhofer Institute validation networks. Liquid-metal-jet source components, tungsten absorber membranes, and metal-bellows sealing architectures feed from consortia-coordinated domestic production in Japan and South Korea. Single-source vulnerability concentrates in mask blank substrates where METI-funded production lines are reducing import dependency. Distribution runs through direct foundry-engineering relationships displacing traditional distributor channels across East Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in x-ray lithography equipment hinges on maskless lithography maturation eliminating reticle fabrication costs, allowing premium capture for direct-write configurations while full-field systems face commoditization pressure.
For Market Incumbents: Cement engineering co-development agreements with TSMC and Samsung as defensive moats against emerging direct-write technology developers. Lock in source-code access terms and captive service contracts to fragment aftermarket ecosystems before maskless lithography alternatives achieve throughput parity. Prioritize vacuum component qualification under REACH and JIS divergence scenarios to compress cross-border equipment acceptance timelines. For New Entrants and Emerging Players: Automotive MEMS pressure sensor fabricators represent an underserved buyer archetype seeking nanoimprint lithography variants for high-volume mechanical feature replication. Target biomedical microfabrication facilities in the United States requiring FDA radiation safety certification pathways for diagnostic sensor applications. Lead with laboratory-scale compact synchrotron offerings that eliminate beamtime allocation bottlenecks for university materials science departments. For Investors and Strategic Acquirers: Roll-up economics work for substrate bonding and alignment specialists because hybrid fabs require bridge systems between legacy optical and emerging x-ray process flows. Five-to-ten year viability favors vendors with precision optics heritage adapted for mask imaging requirements. Watch for JIS-ISO source stability standard alignment as the inflection indicator determining cross-border equipment qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Maskless Lithography Scale-Up | Eliminates reticle costs for SK Hynix sub-10nm pilot lines. |
| Compact Synchrotron Source Development | Decentralizes beam access for Stanford and MIT materials departments. |
| Domestic Mask Blank Production | Reduces import dependency under Japan METI consortia coordination. |
| REACH-Compliant Vacuum Redesign | Qualifies perfluoropolyether alternatives for European fab acceptance. |
| Direct Foundry Engineering Partnerships | Secures source-code access terms with Samsung Pyeongtaek cluster. |
Research Methodology
Bottom-up semiconductor foundry modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with lithography engineering directors, vacuum system procurement leads, national laboratory beamline managers, and resist development scientists combined with secondary validation from SEC equipment vendor filings, METI policy documentation, FDA radiation safety certification records, and customs trade data. Triangulation across these sources calibrated installed base estimates against public consortium funding disclosures.
Historical trendline analysis of maskless versus full-field system deployment patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology tier, end-user category, application maturity, and regional regulatory cluster. CAGRs derived from equipment refresh cycle analysis and foundry capital expenditure intention surveys. Forecast inputs incorporated EUV equipment availability constraints and JIS-ISO standard divergence scenarios.
Underlying measurement precision varies by segment; maskless lithography and semiconductor manufacturer procurement carry tighter precision than research institution purchasing and nanoimprint variants. Forecasts reflect assumptions regarding METI funding continuity and REACH restriction evolution. Synchrotron source brightness stability breakthroughs and mask blank production yield improvements warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Semiconductor CVD Equipment Market
Semiconductor Equipment
Semiconductor Dielectric Etching Equipment Market
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Global Semiconductor Thermal Evaporators Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market