
 High Voltage Insulator Market | 2026-2036
High Voltage Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Insulator Market Outlook
Renewable energy developers is unwinding traditional utility-centric procurement patterns as offshore wind and solar interconnection projects multiply. NGK Insulators anchors ceramic supply chains through captive raw material sourcing in Japan and sustained investment in ultra-high voltage formulations. Siemens Energy competes on digital monitoring integration, embedding fiber-optic sensors within composite housings for real-time contamination tracking. Hitachi Energy differentiates through GIS-compatible compact designs that reduce substation footprints in dense Asian metropolitan corridors.
High voltage insulators are dielectric structures engineered to mechanically support energized conductors while withstanding electrical stresses exceeding 72.5 kV, manufactured from porcelain, toughened glass, or silicone rubber composite matrices with fiberglass cores. Their primary purpose is preventing flashover and mechanical failure across transmission towers, substation buswork, and switchgear assemblies operating in contaminated or seismic environments. Composite insulators lead product type momentum due to lighter weight and superior hydrophobicity in coastal installations, while porcelain retains dominance in ultra-high voltage corridors above 800 kV where decades of field data validate long-term reliability. Underground installation types command margin concentration given specialized cable termination requirements and shorter replacement cycles than overhead equivalents.
IEC 60383 and ANSI C29 standards govern dimensional and electrical performance benchmarks, while China's GB/T 11030 and India's BIS IS 731 enforce localized testing protocols for pollution severity classes. The EU Green Deal's F-Gas Regulation indirectly pressures composite insulator material selection by restricting fluorinated compounds in ancillary sealing components. Stakeholders must monitor evolving national pollution classification maps and corresponding creepage distance requirements as climate-induced contamination patterns shift established design assumptions.
Market Dynamics
Composite insulator technology is compressing traditional procurement cycles as offshore wind developers demand lighter, hydrophobic alternatives to porcelain for coastal installations. Grid operators in China, Germany, and the United States now specify real-time contamination monitoring as standard, forcing material science and digital sensor convergence.
Growth Catalysts
- EU Green Deal grid mandates:Transmission operators across Germany, Spain, and Poland must modernize legacy corridors to accommodate renewable interconnection, tightening contamination resistance specifications for new insulator deployments.
- Offshore wind buildout:Developers in the North Sea and Baltic regions procure composite designs exclusively, as salt spray degradation accelerates replacement cycles for conventional ceramic strings.
- Silicone rubber hydrophobicity:Polymer surface properties reduce leakage current in high-humidity environments, extending maintenance intervals beyond porcelain benchmarks in tropical and coastal zones.
Market Restraints
- Alumina supply concentration:High-purity ceramic feedstock processing clusters in China's Shandong province, creating exposure to export quota volatility for porcelain manufacturers elsewhere.
- Long-term reliability data gaps:Composite insulators lack four-decade field performance records above 500 kV, causing conservative procurement in ultra-high voltage corridors where porcelain dominates.
- F-Gas Regulation compliance costs:The EU's fluorinated gas restrictions raise sealing component expenses for composite housings, compressing margins on European-bound shipments.
Strategic Opportunities
- India's transmission expansion:State utilities under CEA mandates require 765 kV and 1200 kV installations, opening specification battles between established ceramic suppliers and emerging composite specialists.
- Fiber-optic sensor integration:Real-time contamination and mechanical load monitoring creates recurring revenue streams through sensor-embedded composite designs.
- Retrofit replacement cycles:North American utilities face simultaneous end-of-life for 1960s-1970s porcelain installations, accelerating demand for higher-performance drop-in alternatives.
Industry Challenges
- IEC 60383 certification timelines:Multi-year type-testing protocols for new composite formulations delay product launches and freeze R&D capital.
- Seismic qualification complexity:Japan's METI and California's utilities demand earthquake-resistant mechanical ratings that require specialized test facilities and extended validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Insulator Market |
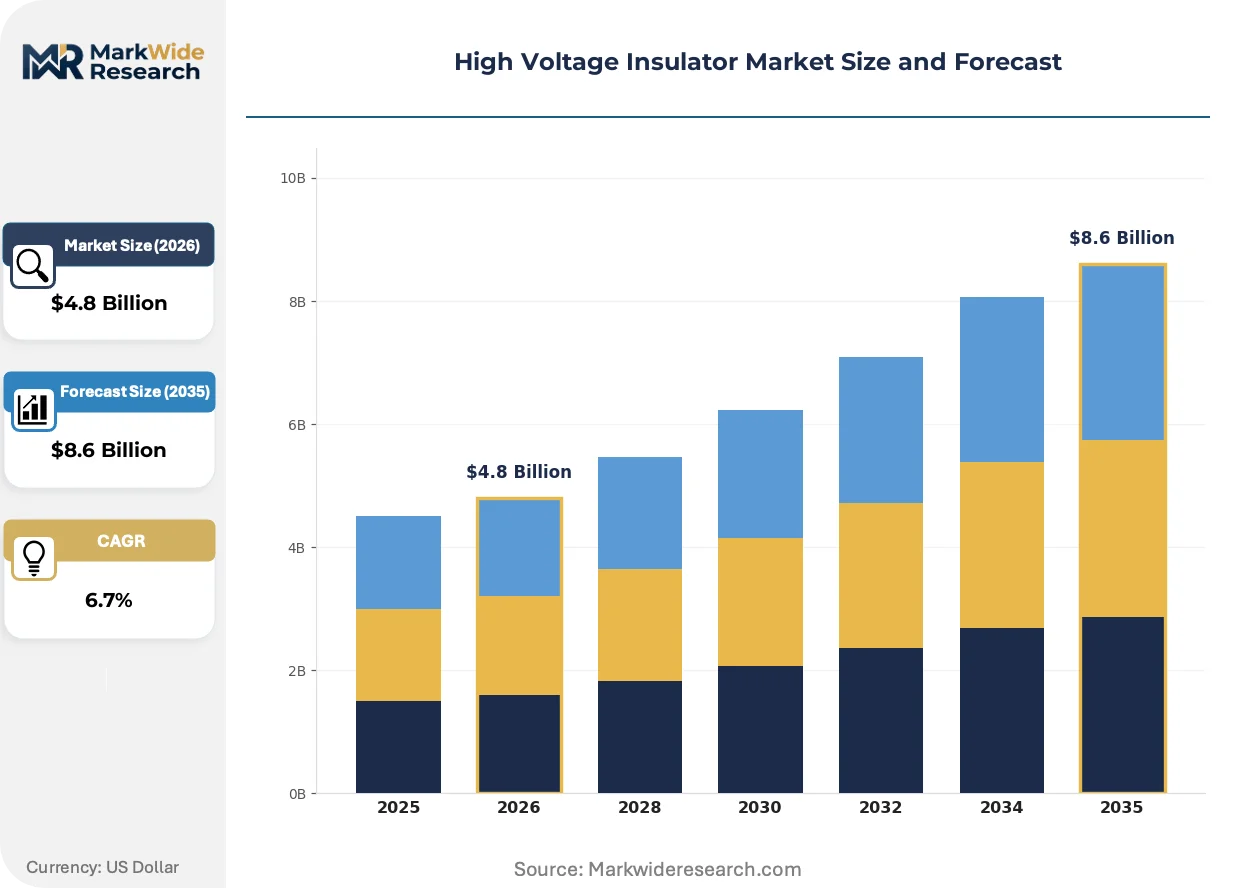
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain Insulators, Composite Insulators, Glass Insulators, Silicone Insulators End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Overhead, Underground, Transmission Lines, Distribution Networks Application: Transmission, Distribution, Power Generation, Substation |
| Companies Covered | NGK Insulators, Aditya Birla Power Composites, Hitachi Energy, TE Connectivity, PFISTERER, Siemens Energy, General Electric Grid Solutions, PPC Insulators, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Insulator Market Strategic Shifts
Material substitution and embedded intelligence are rewriting competitive differentiation as performance validation shifts from decades-old field data to real-time operational telemetry.
Silicone rubber composite housings with fiberglass cores are supplanting traditional porcelain strings in transmission corridors below 800 kV. Offshore wind developers in the North Sea and Baltic markets specify these designs exclusively for new interconnection projects. The transition compresses supplier margins on ceramic production while elevating polymer formulation and precision molding capabilities as core competencies.
REACH and the EU F-Gas Regulation now restrict fluorinated sealing compounds in ancillary composite components. Manufacturers reformulate gasket materials and housing interfaces to maintain IP ratings without regulated substances. German and French transmission operators have accelerated qualification timelines for compliant designs, pressuring suppliers with non-European material chains.
Buyer specifications now bundle insulator supply with predictive maintenance service contracts. European utilities and large-scale renewable developers unbundle hardware procurement from traditional EPC wrap, instead contracting directly with sensor-embedded composite specialists. This pattern concentrates procurement authority among technical buyers in Germany, Denmark, and the Netherlands who prioritize lifecycle cost over upfront capital expenditure.
High Voltage Insulator Market Segmentation
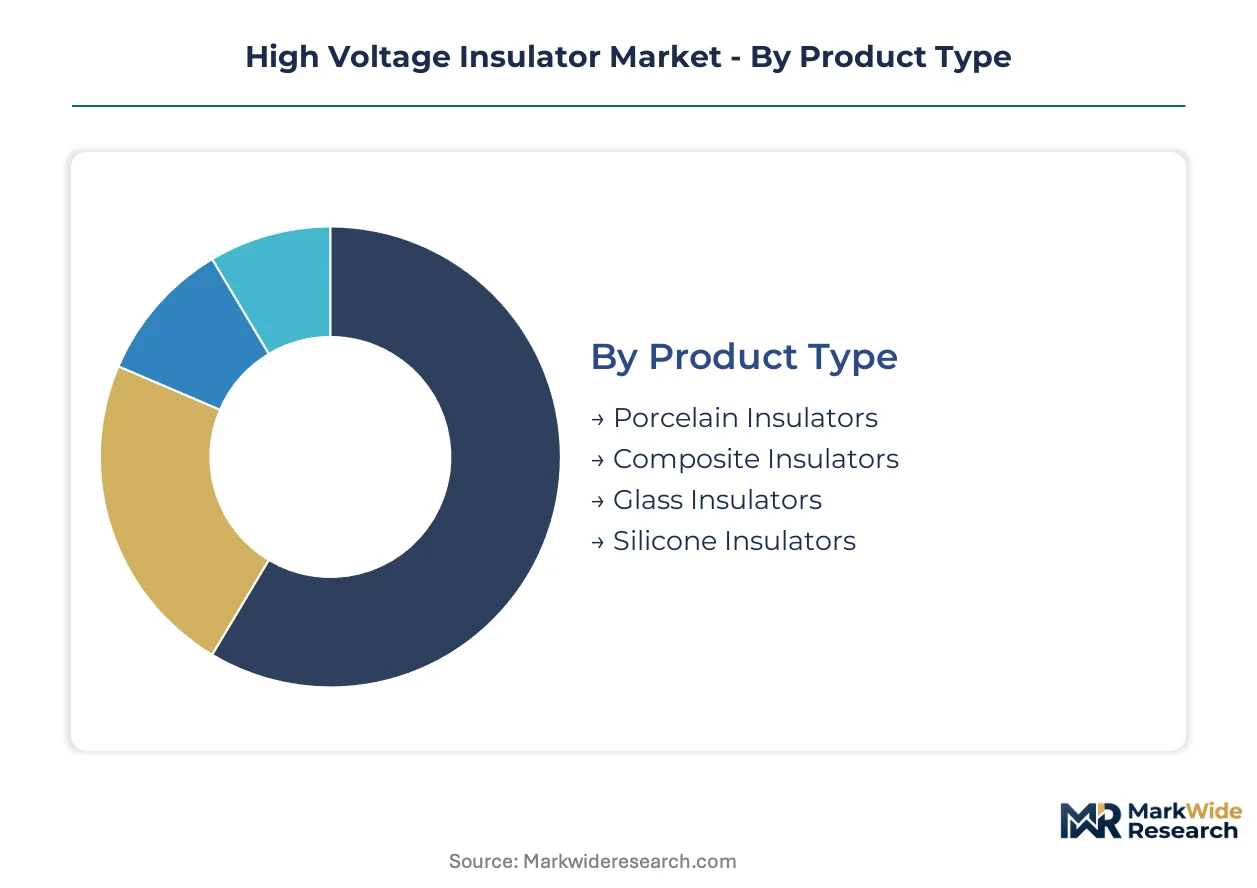
Segmentation in high voltage insulators reveals divergent procurement patterns across voltage classes and environmental exposures. Material selection, installation constraints, and end-use reliability requirements fragment supplier positioning across overlapping technical specifications.
Product Type:
Domestic manufacturing clusters in Japan and Germany anchor porcelain supply chains, while composite formulations concentrate in China and Denmark for export-led renewable interconnection projects.
- Composite Insulators:Silicone rubber housings bonded to fiberglass cores deliver hydrophobic surfaces that resist salt spray accumulation. North Sea offshore wind developers specify these exclusively, as polymer weight advantages reduce tower loading and helicopter installation costs.
- Porcelain Insulators:High-alumina ceramic formulations fired at extreme temperatures provide decades of field-validated performance above 800 kV. Chinese ultra-high voltage corridors and legacy European transmission networks maintain procurement preference for proven dielectric stability.
- Glass Insulators:Toughened borosilicate designs offer visual inspection advantages for surface damage detection. Distribution utilities in France and Italy retain standardized glass string configurations for medium-voltage overhead lines.
- Silicone Insulators:Specialized polymer variants with enhanced tracking resistance serve contaminated industrial environments. Petrochemical facilities along the US Gulf Coast specify these for substation buswork exposed to chemical vapor deposition.
Porcelain holds the largest share; momentum sits with composite designs.
End User:
Procurement authority fragments between centralized state utilities with decade-long qualification cycles and renewable developers demanding compressed delivery timelines.
- Utilities:Grid operators in Germany, China, and the United States dominate volume procurement through multi-year framework agreements. These buyers enforce IEC 60383 and ANSI C29 compliance with extended type-testing protocols that freeze supplier margins.
- Renewable Energy:Offshore wind developers in Denmark and the Netherlands unbundle hardware from EPC contracts, contracting directly with composite specialists for sensor-embedded designs. Real-time contamination monitoring now appears as standard specification.
- Industrial:Heavy manufacturing and petrochemical facilities require specialized contamination resistance for harsh atmospheric exposures. Refinery complexes in Texas and Rotterdam specify elevated creepage distances for coastal humidity.
- Commercial:Data centers and large commercial campuses procure medium-voltage switchgear with compact GIS-compatible insulator configurations. Singapore and Frankfurt financial districts prioritize substation footprint reduction.
Utilities represent the dominant revenue concentration; renewable energy is expanding most quickly.
Installation Type:
Overhead corridors span national transmission backbones while underground installations concentrate in dense metropolitan substations with space constraints.
- Overhead:Suspension and tension strings on lattice towers constitute the bulk of installed base across rural transmission corridors. Chinese 765 kV and 1200 kV projects and US interstate backbones drive specification for extended mechanical load ratings.
- Underground:Cable termination assemblies and GIS bushings serve urban substations where right-of-way constraints eliminate overhead options. Tokyo and London underground networks command premium pricing for specialized sealing and shorter replacement cycles.
- Transmission Lines:Bulk power corridors above 220 kV require contamination-resistant designs for long-distance reliability. Indian CEA-mandated expansion creates specification battles between ceramic incumbents and composite challengers.
- Distribution Networks:Medium-voltage feeders below 72.5 kV serve last-mile connectivity with standardized insulator strings. Brazilian and Indonesian rural electrification programs drive volume procurement of cost-optimized designs.
Overhead maintains the dominant installed base; underground claims the steepest margin expansion.
Application:
Transmission and substation applications concentrate in high-voltage corridors where material science and digital monitoring converge, while distribution serves volume replacement cycles.
- Transmission:Bulk power corridors above 220 kV demand mechanical and electrical performance validation across seismic and contamination extremes. California utilities and Japan's METI enforce earthquake-resistant qualification protocols.
- Substation:GIS-compatible compact designs reduce footprint in dense Asian metropolitan corridors. Hitachi Energy and Siemens Energy compete on integrated sensor deployment for predictive maintenance contracts.
- Distribution:Medium-voltage networks below 72.5 kV drive volume replacement of aging porcelain from the 1960s-1970s. North American utilities face simultaneous end-of-life cycles accelerating demand for drop-in alternatives.
- Power Generation:Generator step-up transformers and switchyard equipment require specialized high-current bushing designs. Combined-cycle plants in the US and Saudi Arabia specify elevated thermal cycling resistance.
Transmission commands the largest project value; substation applications are gaining share fastest through digital integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sino-Singapore Tianjin Eco-City grid interconnection anchors China's transmission upgrade pipeline. Germany's SuedLink DC corridor and India's Green Energy Corridors program frame regional procurement priorities across three continents.
China
State Grid Corporation's 1200 kV ultra-high voltage corridors drive ceramic insulator procurement at unprecedented scale. GB/T 11030 pollution severity classifications now mandate extended creepage distances for western desert installations. Shandong province alumina refineries supply captive feedstock to domestic porcelain manufacturers facing export quota volatility.
Germany
TenneT and 50Hertz transmission operators modernize North Sea offshore wind interconnectors under EU Green Deal mandates. F-Gas Regulation compliance costs reshape composite insulator sealing component supply chains. Siemens Energy and composite specialists in Bavaria deploy fiber-optic sensor integration for real-time contamination monitoring contracts.
United States
Texas ERCOT interconnections and California ISO backbones accelerate 1960s-era porcelain replacement cycles. FERC Order 2023 grid reliability standards tighten mechanical load specifications for seismic corridors. Pacific Northwest utilities specify hydrophobic composite designs for coastal humidity exposure.
India
CEA-mandated 765 kV and 1200 kV transmission expansion creates specification battles between ceramic incumbents and composite challengers. BIS IS 731 localized testing protocols enforce pollution severity validation for tropical contamination patterns. Gujarat and Maharashtra state utilities procure composite strings for coastal renewable interconnection projects.
Japan
Tokyo Electric Power and Chubu Electric reinforce earthquake-resistant grid infrastructure under METI seismic qualification protocols. NGK Insulators anchors ceramic supply chains through captive raw material sourcing in Aichi prefecture. Kanto metropolitan corridor GIS-compatible compact designs reduce substation footprints for dense urban deployment.
High Voltage Insulator Market Competitive Environment
Listed leaders compete with private specialists across technology integration and material science dimensions. The vendor base separates into three tiers: integrated conglomerates with captive utility relationships, mid-scale composite specialists serving renewable developers, and regional ceramic fabricators with legacy certification advantages. Strategic moves concentrate on fiber-optic sensor embedding for predictive maintenance contracts and silicone rubber formulation partnerships to bypass F-Gas Regulation constraints.
Within the integrated conglomerate tier, NGK Insulators, Hitachi Energy, and Siemens Energy exemplify divergent competitive positioning. NGK Insulators occupies the ceramic-centric archetype with decades of ultra-high voltage field validation. Hitachi Energy represents the compact GIS-compatible design specialization for dense Asian metropolitan corridors. Siemens Energy anchors the digital monitoring convergence archetype, embedding intelligence within composite housings for real-time operational telemetry. These three entities illustrate how material science heritage, geographic footprint, and sensor integration capabilities segment competitive advantage across procurement authority centers in Germany, China, and Japan.
| Leading Market Players |
|---|
| NGK Insulators |
| Aditya Birla Power Composites |
| Hitachi Energy |
| TE Connectivity |
| PFISTERER |
| Siemens Energy |
| General Electric Grid Solutions |
| PPC Insulators |
| ABB |
| Others |
Value Chain & Pricing Dynamics
GB/T 11030 and BIS IS 731 certification protocols gate both supplier qualification and price differentiation simultaneously, as multi-year type-testing timelines freeze R&D capital and compress margins for non-compliant entrants while rewarding incumbent ceramic manufacturers with decades of field-validated premium positioning.
Pricing Analysis
Volume-discount tiering structures separate IEC 60383-certified premium suppliers from ANSI C29-standard mid-tier competitors and economy-grade regional fabricators. Price differentiation hinges on certification grade and after-sales service bundling, with sensor-embedded composite designs commanding lifecycle-cost premiums over transactional hardware procurement. Pricing pressure stems from F-Gas Regulation compliance costs compressing European-bound shipment margins. Renewable developers exhibit lowest price sensitivity due to unbundled EPC contracting authority, while distribution utilities in emerging markets drive aggressive standard-tier negotiation.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery for North Sea offshore wind developers demanding compressed installation windows. Supply concentrates in China's Shandong province for high-purity alumina ceramic feedstock, Denmark for silicone rubber composite formulations, and Japan for captive raw material integration. Raw material dependencies rest on fiberglass cores, silicone polymers, and high-alumina clays. Single-source vulnerability in Shandong alumina refining creates exposure to export quota volatility. Distribution runs through transmission operator framework agreements and direct renewable developer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among technical procurement officers at European transmission operators and unbundled renewable developers, fragmenting traditional utility-centric volume concentration and forcing suppliers to compete on lifecycle value rather than capital cost alone.
For Market Incumbents: Secure captive raw material sourcing through backward integration into alumina refining or silicone polymer production to defend against Shandong supply volatility. Anchor premium positioning through accelerated fiber-optic sensor certification for predictive maintenance contracts, as real-time monitoring specifications displace commodity hardware procurement. For New Entrants and Emerging Players: BIS IS 731 fast-track qualification for 765 kV composite designs opens penetration into India's CEA-mandated transmission expansion, where ceramic incumbents lack localized manufacturing presence. Target coastal renewable interconnection projects in Gujarat and Maharashtra with hydrophobic silicone formulations, leveraging direct developer contracting to bypass entrenched utility framework agreements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core insulator divisions lacking sensor integration capabilities or F-Gas-compliant sealing expertise. Long-term viability centers on recurring revenue streams from predictive maintenance contracts rather than transactional hardware cycles. Watch for inflection when European transmission operators mandate real-time contamination monitoring as standard specification across all voltage classes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captive Shandong feedstock supply secures porcelain margin stability against export quota volatility. |
| Fiber-Optic Sensor Certification Investment | IEC 60383-compliant embedded monitoring enables predictive maintenance contract revenue streams. |
| F-Gas Regulation Compliance Reformulation | Fluorinated-free sealing materials maintain European market access under tightened environmental standards. |
| Direct Renewable Developer Contracting | Unbundled procurement from EPC wraps concentrates authority with technical buyers prioritizing lifecycle cost. |
| Seismic Qualification Facility Investment | METI and California utility compliance opens premium positioning in earthquake-resistant corridor specifications. |
Study Parameters
A spread of perspectives from transmission planning engineers, renewable project procurement leads, ceramic plant operations managers, and composite R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation from IEC standard documentation, national pollution classification maps, SEC filings of listed suppliers, and customs trade data for alumina and silicone polymer flows. Bottom-up installation forecasts triangulated against top-down grid investment pipelines across the analysis window.
Segmentation dimensions modeled encompass product type, end user archetype, installation configuration, and application voltage class alongside regional regulatory framework clusters. CAGRs were derived from weighted average of utility capital expenditure projections and renewable interconnection timelines. Industry-specific forecast inputs include contamination severity reclassification trends and seismic qualification protocol adoption rates.
Underlying assumptions cover sustained grid modernization mandate enforcement, with deviation risk concentrated in alumina export policy shifts and composite long-term reliability data accumulation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
Busbar Trunking System Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
US Electric Enclosure Market