
 Programmable LED Drivers Market | 2026-2036
Programmable LED Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable LED Drivers Market Analytics
Distribution through specialized lighting and electronics distributors is reconfiguring as programmable LED driver portfolios expand beyond commodity replacement sales into specification-driven project channels. Texas Instruments leverages its analog semiconductor heritage to anchor high-precision current regulation segments. Signify competes through vertical integration into luminaire manufacturing, capturing margin pools that standalone component vendors cannot access. Macroblock specializes in driver IC architectures for large-format display backlighting, occupying a defensible niche against generalist competitors.
Programmable LED drivers are power conversion and control devices that modulate electrical output to LED arrays through configurable current or voltage parameters, typically operating across input ranges of 90-305 VAC with power factors exceeding 0.9. Their primary commercial purpose centers on enabling precise dimming curves, color temperature tuning, and networked control in solid-state lighting installations. Constant current architectures dominate unit volume in commercial and industrial deployment, while dimmable variants command premium positioning as building automation penetration deepens. Digital control interfaces, particularly those supporting wireless protocols, represent the fastest-expanding technology segment as Bluetooth and Zigbee integration displaces legacy 0-10V analog wiring in retrofit and new construction alike.
The EU Ecodesign Directive and F-Gas Regulation shape product efficiency benchmarks and thermal management requirements for drivers sold in European markets, while the US EPA ENERGY STAR program and DOE lighting standards influence North American procurement specifications. China's GB standards and MIIT circular economy mandates impose domestic efficiency tiers that foreign suppliers must meet for market access. Stakeholders must monitor divergence between regional interoperability standards for wireless control protocols, as fragmentation threatens to segment addressable markets by compliance jurisdiction rather than by technical performance alone.
Market Dynamics
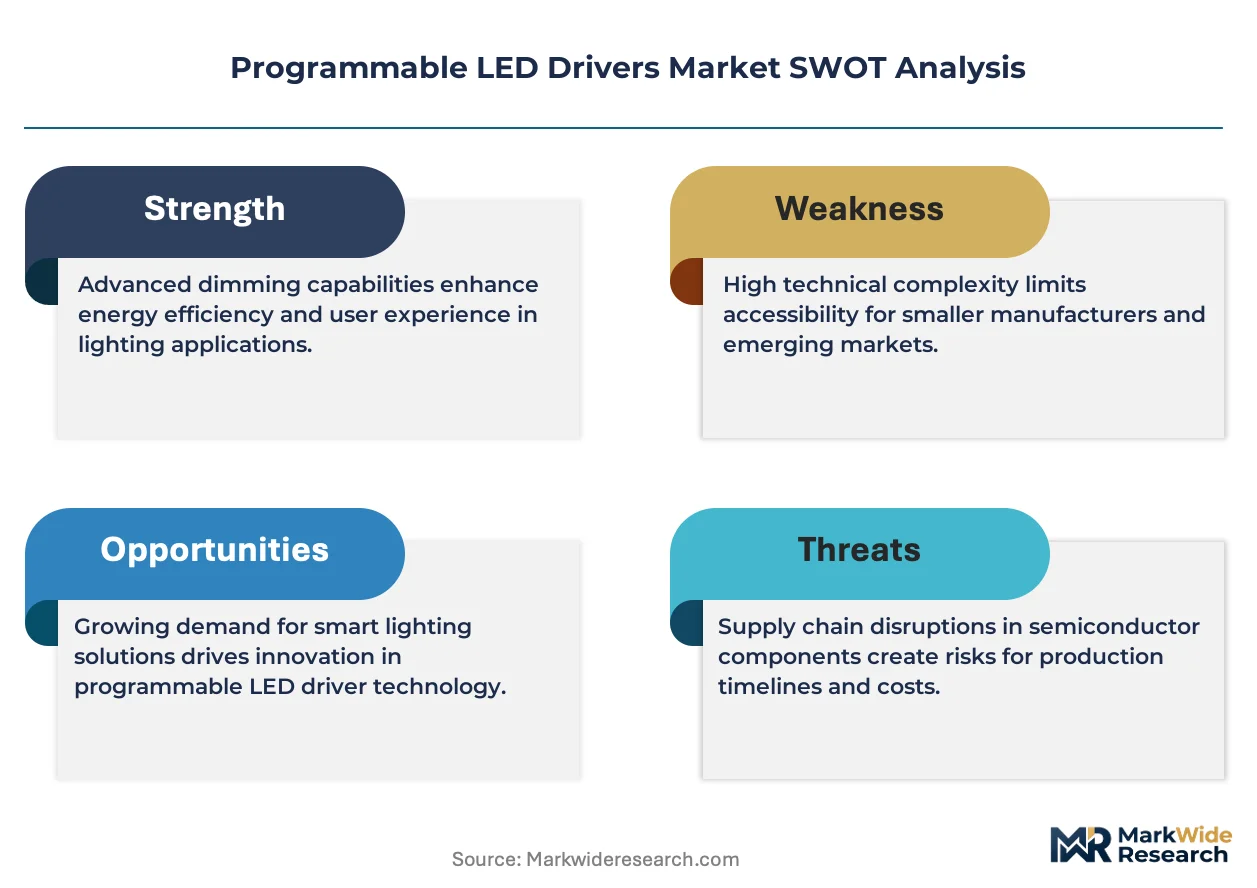
The transition from analog 0-10V dimming to wireless digital control protocols is restructuring procurement specifications across commercial and municipal lighting sectors, forcing driver manufacturers to requalify products for interoperability certification with building automation systems.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency mandates for luminaire components are accelerating replacement cycles in European commercial real estate, creating pull-through demand for programmable drivers with power factors above 0.9.
- Smart city infrastructure:Municipalities in China, Germany, and the United States are deploying connected street lighting networks that require drivers with embedded wireless communication capability and remote configurability.
- Bluetooth Mesh and Zigbee integration:These wireless protocols are eliminating dedicated control wiring in retrofit installations, reducing labor costs and expanding addressable project scale for programmable driver deployment.
Market Restraints
- Semiconductor supply concentration:Driver IC fabrication depends on concentrated capacity at Taiwanese and South Korean foundries, exposing lead times to geopolitical and capacity allocation risks.
- Copper and magnetic component costs:Input volatility in transformer-grade copper and ferrite cores compresses gross margins for manufacturers lacking forward purchasing agreements or alternative sourcing.
- Legacy 0-10V infrastructure persistence:Existing installed base of analog-controlled luminaires in North American commercial buildings slows upgrade cycles despite superior digital performance.
Strategic Opportunities
- Horticultural lighting expansion:Controlled-environment agriculture in the Netherlands and Canada requires spectral-tunable drivers with precise photon flux regulation, commanding premium positioning beyond general illumination.
- India's streetlight national program:Municipal energy efficiency tenders under the country's LED procurement schemes are creating volume demand for programmable drivers with remote monitoring capability.
- Human-centric lighting convergence:Circadian rhythm applications in healthcare and education facilities are integrating tunable white drivers with building management systems, opening specification-driven channels.
Industry Challenges
- Firmware security certification:Wireless-enabled drivers require cybersecurity validation under IEC 62443 and regional variants, extending product development timelines by 6-12 months.
- Interoperability testing fragmentation:Divergent certification requirements across DALI, Zigbee, and proprietary mesh protocols force redundant qualification investments for multi-region product portfolios.
- Thermal management engineering scarcity:Driver miniaturization for slim luminaire form factors demands specialized power electronics expertise that competes with electric vehicle and renewable energy sectors for talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable LED Drivers Market |
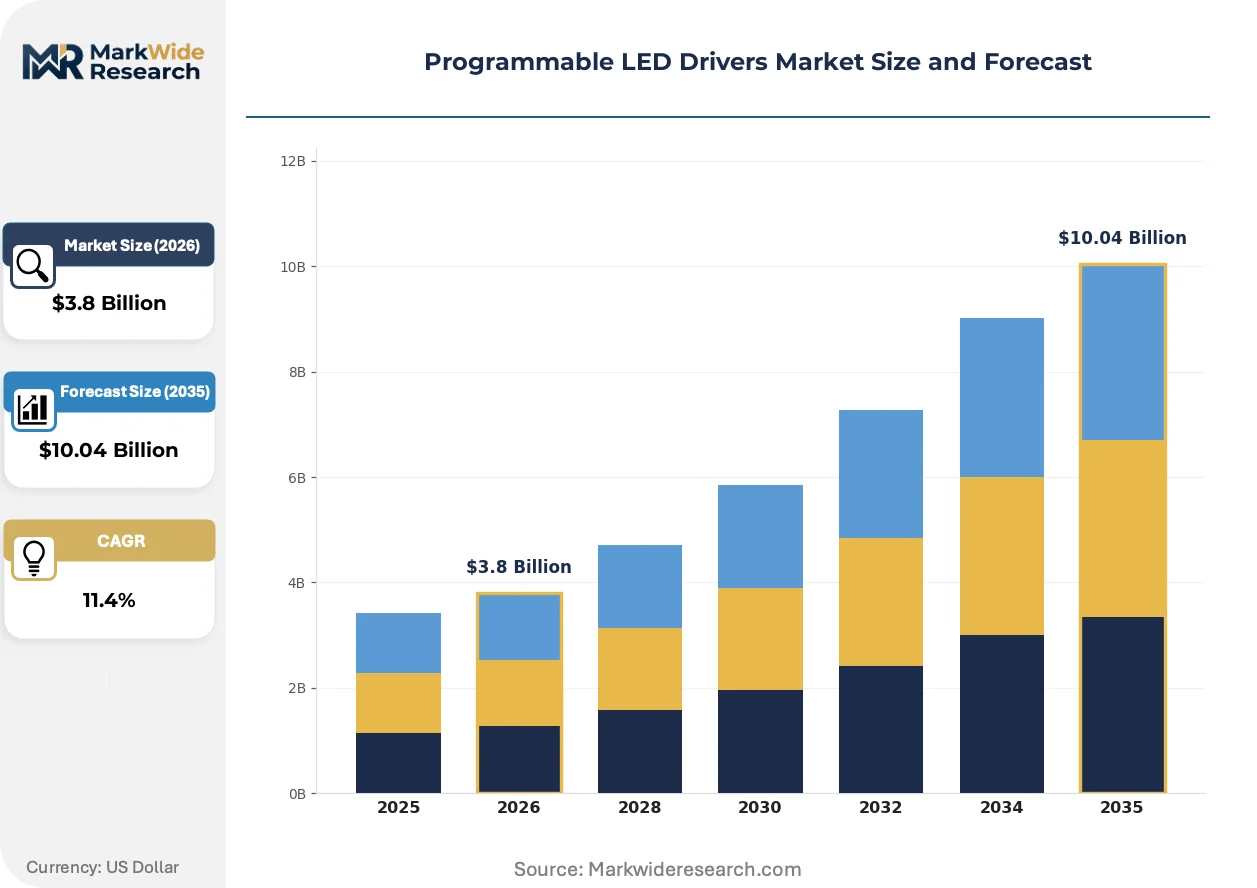
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Current, Constant Voltage, Dimmable, Non-Dimmable Technology: Analog, Digital, Hybrid, PWM End User: Commercial Lighting, Residential Lighting, Industrial Applications, Automotive Lighting Control Interface: Wi-Fi, Bluetooth, Zigbee, 0-10V |
| Companies Covered | Texas Instruments, ams OSRAM, Signify, Maxim Integrated, Macroblock, Tridonic, Inventronics, NXP Semiconductors, Lutron Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable LED Drivers Market Evolving Landscape
Wireless protocol integration is compressing installation labor content and enabling granular fixture-level control that analog architectures cannot support. Three developments are reshaping product roadmaps and competitive positioning.
Power-over-Ethernet (PoE) driver architectures are digitizing low-voltage DC distribution within commercial buildings. Facility managers in Class A office developments are specifying PoE-enabled luminaires to consolidate infrastructure and enable granular energy monitoring. This topology is digitizing the traditional segregation between electrical and IT infrastructure, repositioning driver vendors as network edge device suppliers.
China's MIIT circular economy mandates are tightening domestic efficiency tiers for power electronics, requiring foreign suppliers to requalify products for GB standard compliance. The regulations are compressing market access for non-compliant imports while accelerating local R&D investment. Domestic LED module manufacturers are responding by integrating programmable drivers at the source, capturing value that discrete component suppliers previously accessed.
Specification influence is migrating from electrical contractors to building automation integrators and energy service companies. These buyers prioritize API-accessible driver platforms over standalone hardware, disrupting traditional distributor relationships. The shift is most visible in German and Dutch commercial construction, where performance contracting models require verified operational data from connected luminaires.
Programmable LED Drivers Market Segmentation
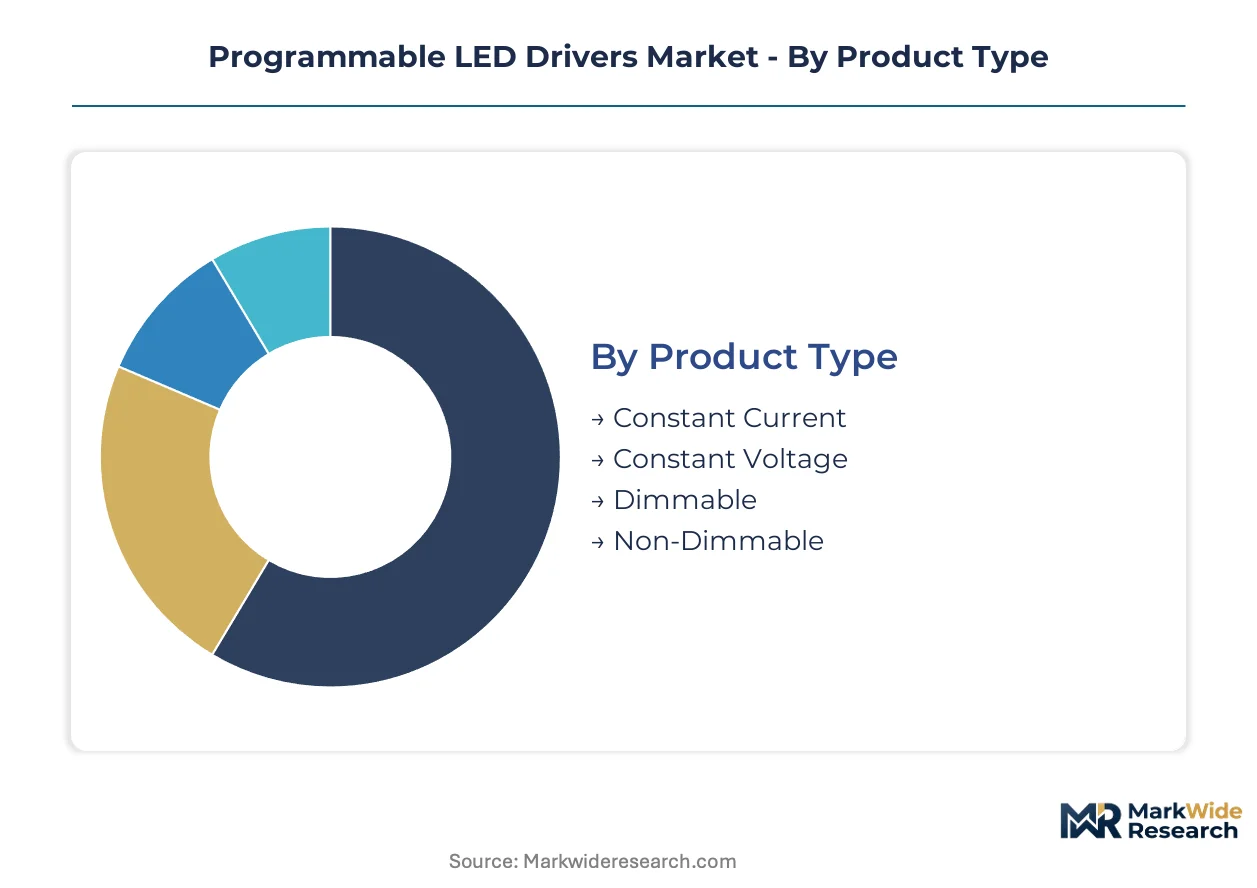
Programmable LED driver architectures fragment across power regulation topologies, signal processing methods, and connectivity standards. Each segmentation axis carries distinct margin structures and qualification requirements that shape vendor portfolio priorities.
Product Type:
Mature constant current designs anchor commercial volume, while emerging dimmable variants capture specification-driven premiums in connected installations.
- Constant Current:Regulates output current regardless of voltage fluctuations, essential for LED arrays where luminous consistency prevents color shift. Demand concentrates in Chinese manufacturing clusters serving export markets, constrained by copper and magnetic component cost volatility.
- Dimmable:Integrates control circuitry for smooth output modulation across 1-100% range, supporting human-centric lighting protocols. Procurement is accelerating in German healthcare and Dutch commercial real estate where circadian applications command specification premiums.
- Constant Voltage:Maintains fixed output voltage for LED strips and signage applications.
- Non-Dimmable:Basic power conversion without modulation capability, serving cost-sensitive replacement markets.
Constant Current retains volume leadership; Dimmable holds the steepest expansion curve.
Technology:
Cost tiers separate legacy analog implementations from digitally controlled architectures that enable networked intelligence.
- Digital:Employs microcontroller-based regulation with firmware-configurable parameters and remote diagnostics. Municipal street lighting tenders in China and the United States specify digital platforms for centralized energy management.
- PWM:Pulse-width modulation switches power at high frequency to achieve precise dimming without color degradation. Large-format display manufacturers in Taiwan and South Korea specify PWM drivers for backlight uniformity in premium panels.
- Analog:Discrete component regulation without programmable logic, remaining viable for basic commercial retrofits.
- Hybrid:Combines analog power stages with digital control interfaces, bridging legacy infrastructure and smart building requirements.
Digital architectures capture the premium tier; PWM dominates display backlighting niches.
End User:
Application diversity spans from standardized residential replacement to mission-critical industrial specifications with diverging certification burdens.
- Commercial Lighting:Office, retail, and hospitality installations requiring networked control and energy metering. Building automation integrators in Germany and the Netherlands specify API-accessible drivers under performance contracting models.
- Industrial Applications:High-bay, hazardous location, and continuous-operation environments demanding extended temperature ranges and surge protection. Manufacturing facilities in the United States prioritize drivers with IEEE 802.3bt PoE compatibility for consolidated infrastructure.
- Residential Lighting:Consumer fixture replacements with basic dimming via wall switches or mobile applications.
- Automotive Lighting:Exterior and interior vehicle illumination subject to AEC-Q100 qualification and vibration resistance standards.
Commercial Lighting retains volume leadership; Industrial Applications hold the steepest expansion curve.
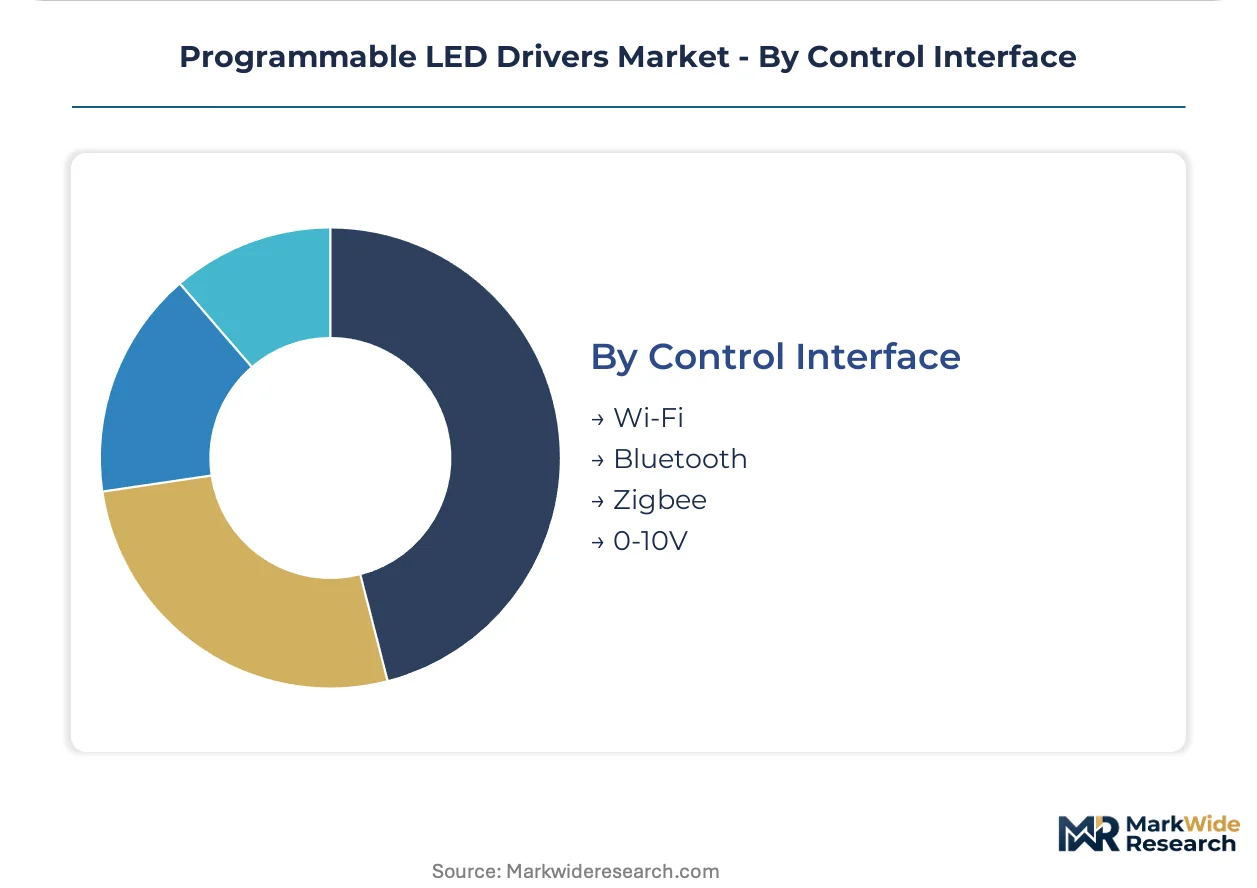
Control Interface:
Customer type stratification separates legacy electrical contractors specifying wired controls from IT-integrated procurement favoring wireless protocols.
- Bluetooth:Mesh networking enables fixture-to-fixture communication without dedicated gateway infrastructure. Retrofit contractors in North American Class A offices specify Bluetooth drivers to eliminate 0-10V wiring labor.
- Zigbee:Low-power IEEE 802.15.4 protocol with proven interoperability in building automation ecosystems. Smart city deployments in Germany and the United States standardize on Zigbee for street lighting central management compatibility.
- 0-10V:Analog voltage-level dimming entrenched in existing North American commercial building infrastructure.
- Wi-Fi:Direct IP connectivity for residential and small commercial installations without separate hub requirements.
0-10V retains installed base dominance; Bluetooth holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Dutch specification channels where performance contracting commands premium positioning, while Chinese manufacturing clusters compete on integrated module-driver bundles that compress margins for discrete component imports.
United States
Municipal smart street lighting deployments in Los Angeles and Chicago drive demand for wireless-enabled drivers with remote configurability. The EPA ENERGY STAR program and DOE lighting standards shape procurement specifications for federal and state efficiency tenders. Manufacturing facilities in Michigan and Ohio prioritize IEEE 802.3bt PoE-compatible drivers for consolidated electrical-IT infrastructure.
Germany
Healthcare and commercial real estate sectors specify tunable white drivers for circadian lighting applications under performance contracting models. The EU Ecodesign Directive and F-Gas Regulation enforce minimum efficiency tiers and thermal management requirements. The Rhine-Ruhr industrial corridor hosts building automation integrators demanding API-accessible driver platforms with verified operational data.
China
National LED procurement schemes and smart city infrastructure in Shenzhen and Hangzhou accelerate deployment of connected street lighting with embedded wireless capability. MIIT circular economy mandates and GB standards tighten domestic efficiency tiers for power electronics. Yangtze River Delta manufacturing clusters integrate programmable drivers at the LED module source, capturing value from discrete component suppliers.
Netherlands
Controlled-environment agriculture in Westland and North Brabant requires spectral-tunable drivers with precise photon flux regulation for horticultural applications. The EU Ecodesign Directive harmonizes efficiency benchmarks across Dutch commercial construction tenders. Eindhoven-region lighting specification engineers prioritize human-centric lighting convergence with building management system integration.
India
Municipal energy efficiency programs under national LED procurement schemes create volume demand for drivers with remote monitoring capability in Delhi and Mumbai. The Bureau of Energy Efficiency and CEA impose domestic efficiency tiers that foreign suppliers must meet for market access. Gujarat and Maharashtra industrial zones concentrate luminaire assembly operations sourcing programmable drivers for streetlight retrofits.
Programmable LED Drivers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base stratifies between consolidated analog semiconductor houses with precision regulation heritage and fragmented driver IC specialists serving display backlighting niches. Three archetypes dominate: vertically integrated luminaire manufacturers capturing margin pools, analog semiconductor incumbents anchoring high-precision segments, and regional fabricators competing on module-driver integration. Competitive moves center on backward integration into driver IC design and strategic partnerships with building automation platforms.
Within the analog semiconductor tier, Texas Instruments leverages its heritage in precision current regulation, while Maxim Integrated occupies a position in high-reliability industrial applications. Among vertically integrated lighting systems, Signify exemplifies the luminaire-manufacturer archetype through captive driver supply. These three entities represent distinct competitive positions: component heritage, industrial specialization, and downstream system control.
| Leading Market Players |
|---|
| Texas Instruments |
| ams OSRAM |
| Signify |
| Maxim Integrated |
| Macroblock |
| Tridonic |
| Inventronics |
| NXP Semiconductors |
| Lutron Electronics |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Taiwanese foundry capacity for driver IC fabrication compresses pricing tier spreads while forcing supply chain consolidation around qualified second-source partnerships. This concentration dynamic elevates procurement risk premiums for buyers lacking long-term offtake agreements while squeezing margin buffers for manufacturers exposed to spot-market magnetic component costs.
Pricing Analysis
Configured-to-order pricing for tunable white and wireless-enabled drivers commands 35-50% premiums over standard constant-current catalog SKUs. Three-tier pricing structure across premium, standard, and economy levels separates API-accessible digital platforms from analog-only legacy products. Cost compression in economy-tier non-dimmable drivers is intensifying because Yangtze River Delta module manufacturers integrate drivers at source. Municipal procurement offices in India and China exhibit highest price sensitivity; German healthcare facility managers under performance contracting models demonstrate lowest sensitivity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days among European luminaire OEMs are reshaping supplier financing structures, with supply-chain finance facilities emerging as competitive differentiators for component vendors. Driver IC fabrication draws from Taiwan, South Korea, and China; magnetic core winding concentrates in Vietnam and Malaysia. Transformer-grade copper and ferrite core dependencies expose margins to commodity volatility. Tariff exposure on Chinese-manufactured modules threatens North American supply continuity. Distribution runs through specialized lighting distributors and direct specification channels to building automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among building automation integrators and energy service companies, fragmenting traditional electrical contractor influence and forcing vendor requalification around API-accessible platforms.
For Market Incumbents: Entrench position by securing captive driver IC supply through backward integration or exclusive foundry allocations, insulating against Taiwan capacity constraints. Deepen certification investment in IEC 62443 cybersecurity validation to extend development timelines that challengers cannot match. Counter the threat of Chinese module manufacturers integrating drivers at source by controlling specification channels through building automation platform partnerships. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with limited incumbent specification presence and accelerating LED retrofit mandates. India's municipal streetlight national program offers volume demand with remote monitoring capability requirements that favor agile firmware developers. Horticultural lighting in Canadian controlled-environment agriculture presents premium positioning with lower certification barriers. Go-to-market angle: partner with regional luminaire assemblers in Gujarat and Maharashtra for rapid qualification. For Investors and Strategic Acquirers: The market sits at a protocol-consolidation phase that favors analog semiconductor heritage players with precision regulation IP and existing building automation relationships. Long-term viability over the next decade hinges on wireless certification breadth and thermal management engineering depth. Acquisition target archetype: driver IC specialists with display backlighting expertise seeking horizontal expansion into general illumination. Signal to watch: DALI-2 and Zigbee interoperability certification backlog durations as inflection indicator for qualification capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | Captures margin pools from Taiwanese foundry dependence while securing allocation priority. |
| Wireless Protocol Certification Expansion | Bluetooth Mesh and Zigbee interoperability unlocks German and Dutch specification channels. |
| API-Accessible Platform Development | Positions vendors for building automation integrator procurement migrating from distributors. |
| Thermal Management Engineering Acquisition | Addresses talent scarcity competing with electric vehicle and renewable energy sectors. |
| Horticultural Lighting Driver Specialization | Spectral-tunable platforms command premium positioning in Netherlands and Canadian markets. |
Research Methodology
The analysis maps constant current, dimmable, digital, and PWM driver architectures, each validated through driver IC design engineers, luminaire manufacturer procurement directors, building automation system integrators, and municipal lighting program managers. Primary interviews with these stakeholders combined with secondary validation from MIIT circular economy filings, EU Ecodesign Directive implementing measures, EPA ENERGY STAR qualified products lists, and customs trade data on LED module imports. Bottom-up unit shipment estimates triangulated against top-down addressable construction spend.
Assumptions held fixed include regulatory enforcement timelines for GB standards compliance and wireless protocol interoperability certification durations; variables tested include copper price volatility bands and foundry capacity allocation scenarios. Segmentation dimensions modeled span power regulation topology, control interface protocol, end-use application intensity, and regional procurement framework. CAGRs derived from logistic diffusion curves fitted to historical LED penetration patterns and building automation adoption rates. Industry-specific inputs include municipal streetlight tender award velocities and horticultural facility construction permits.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates and municipal bond issuance volumes would shift the trajectory. Forecasts reflect documented assumptions regarding semiconductor fabrication capacity expansion and regulatory harmonization timelines. Cybersecurity certification backlog, copper futures curve inversion, and single-source foundry disruption represent specific risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global LED Phosphor Market
LED
LED Mask Market
LED
Xenon Market
LED
Africa LED Lighting Market
LED
Chip on Board LED Market
LED
LED Display Control Card Market
LED
LED Lighting Market
LED
LED Tester Market
LED
LED Power Supplies Market
LED
North America Outdoor LED Lighting Market
LED
LED Services Market
LED
Asia Pacific Indoor LED Lighting Market
LED
North America LED Packaging Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
South America Indoor LED Lighting Market
LED
United States Micro LED Market