
 United States Busbar Market | 2026-2036
United States Busbar Market Size, Share, and Industry Trends Forecast 2026-2036
United States Busbar Market Intelligence
Maintenance-service contracts for thermal monitoring and predictive diagnostics is consolidating vendor relationships around long-term performance guarantees rather than one-time hardware sales. Eaton Corporation PLC leverages its installed base of switchgear to anchor recurring service revenue streams. Schneider Electric SE competes through software-defined power management platforms that extend customer lifetime value. Siemens Aktiengesellschaft differentiates by integrating busbar systems with building automation protocols.
A busbar is a metallic strip or bar, typically copper or aluminum, engineered to conduct substantial electrical current within switchboards, distribution boards, substations, and battery banks, with cross-sectional area and ampacity ratings determined by IEC or UL standards for thermal and mechanical performance. Copper busbar commands premium positioning in data center and semiconductor fabrication applications where conductivity efficiency directly affects cooling loads and footprint constraints. Aluminum busbar occupies cost-sensitive utility and renewable energy installations where weight reduction and material economics outweigh conductivity advantages. Insulated busbar is gaining share in commercial building retrofits where arc-fault containment and compact routing solve legacy infrastructure limitations.
UL 857 safety standards and the National Electrical Code govern busbar installation practices, while FERC Order 2222 and state-level interconnection rules shape utility procurement specifications for grid-scale power distribution equipment. OSHA electrical safety directives mandate arc-flash hazard mitigation, pushing industrial end users toward insulated and modular busbar configurations with integrated protective features. Stakeholders must monitor evolving EPA efficiency standards and state renewable portfolio mandates that will redefine ampacity requirements and material selection criteria for next-generation installations.
Market Dynamics
NEPA review timelines stretching to 48 months and IRA domestic content incentives are forcing supplier capital toward US-based manufacturing, compressing procurement cycles for hyperscale data center operators in Texas, Virginia, and Arizona.
Growth Catalysts
- Copper conductivity premiums:Data center operators prioritize copper busbar for high-density power distribution where thermal efficiency directly reduces cooling infrastructure footprint and operating expenditure.
- FERC Order 2222 implementation:Distributed energy resource interconnection rules are expanding utility procurement specifications for modular, grid-scale busbar systems with bidirectional power flow capabilities.
- Texas-Virginia-Arizona construction concentration:Hyperscale facility buildouts in these three states are concentrating demand for 4000A+ ampacity busbar configurations with integrated thermal monitoring.
Market Restraints
- Copper price volatility:LME copper price swings above 20% annually are compressing fabrication margins and forcing aluminum substitution in cost-sensitive renewable energy installations.
- NEPA permitting bottlenecks:Federal environmental review timelines averaging four years are delaying transmission infrastructure projects that anchor large-scale busbar procurement cycles.
- Aluminum conductivity ceiling:Material resistivity limits restrict aluminum busbar to sub-2000A applications, excluding it from hyperscale data center specifications where copper dominates.
Strategic Opportunities
- IRA manufacturing tax credits:Section 45X advanced manufacturing credits are incentivizing greenfield busbar fabrication facilities in Ohio, South Carolina, and Texas to qualify for domestic content requirements.
- Insulated busbar retrofit penetration:Commercial building arc-fault containment mandates in California, New York, and Illinois are creating replacement demand for compact, insulated busbar in legacy electrical infrastructure.
- Predictive diagnostics convergence:IoT thermal sensors and edge analytics are converging with busbar hardware to create recurring service revenue streams anchored to performance guarantees rather than one-time equipment sales.
Industry Challenges
- Arc-flash engineering specialization:OSHA 1910.269 compliance requirements are outstripping the supply of certified electrical engineers capable of designing arc-flash mitigation into high-ampacity busbar configurations.
- UL 857 certification timelines:Third-party safety testing and listing processes extending 16-24 weeks are misaligning with hyperscale construction schedules that demand 8-week equipment delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Busbar Market |
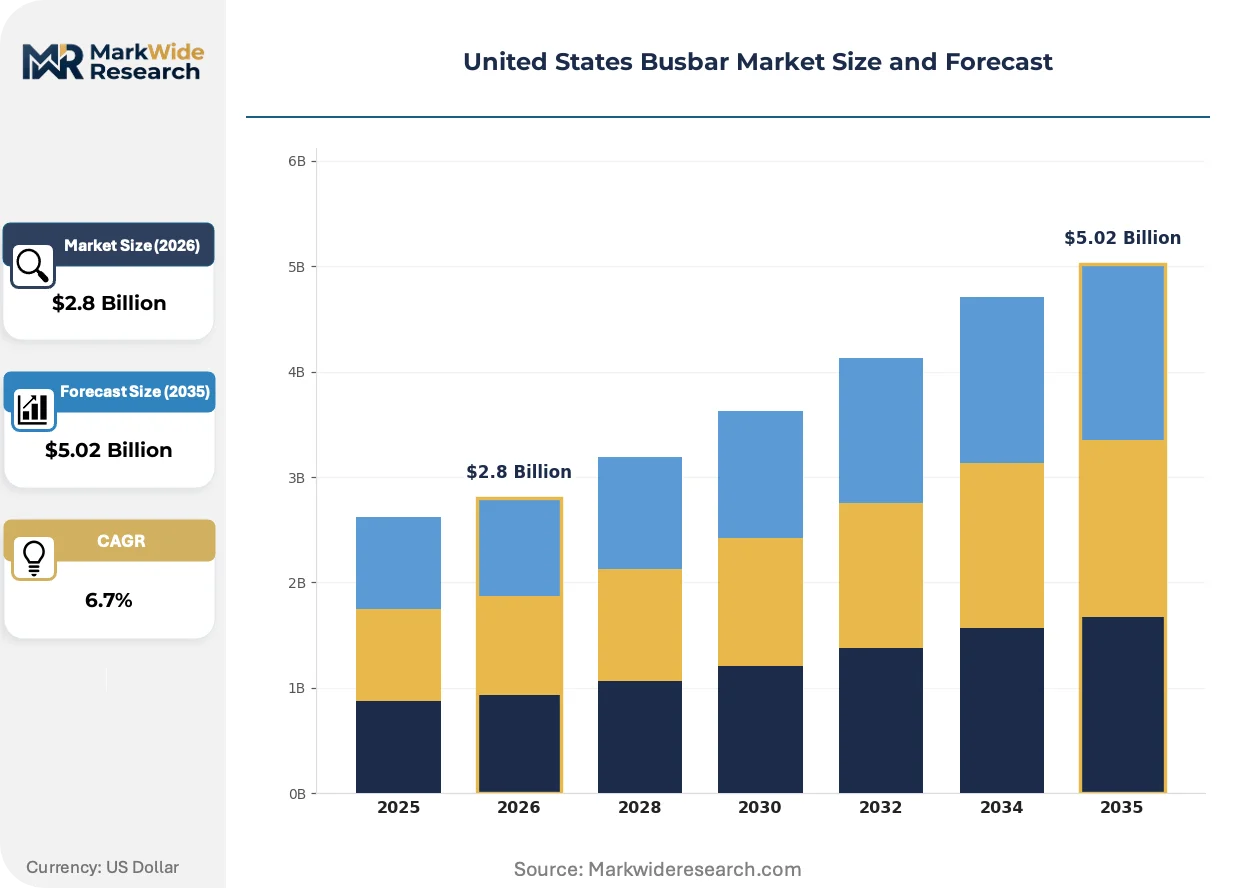
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Busbar, Aluminum Busbar, Insulated Busbar, Flexible Busbar Application: Power Distribution, Renewable Energy, Railways, Industrial Automation End User: Utilities, Manufacturing, Transportation, Commercial Buildings Installation Type: Indoor, Outdoor, Modular, Fixed |
| Companies Covered | Eaton Corporation PLC, Legrand S.A, ABB Ltd, Luvata, American Power Connection Systems Inc, Siemens Aktiengesellschaft, TE Connectivity Ltd, Rittal, Schneider Electric SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Busbar Market Strategic Shifts & Innovations
Digitalization of power distribution hardware is compressing the traditional separation between electrical infrastructure and building automation systems, creating integrated platforms that shift vendor value toward software-enabled service contracts.
Cast resin insulated busbar is converging with compact switchgear designs to enable 50% space reduction in electrical rooms. Data center operators in Northern Virginia and Phoenix are specifying these configurations for brownfield expansions where physical constraints limit equipment footprint. The technology is converging with modular data center architectures that treat power distribution as a standardized, repeatable subsystem rather than custom-engineered infrastructure.
OSHA electrical safety directive enforcement is tightening arc-flash hazard mitigation requirements across industrial facilities. Manufacturers are responding with integrated protective relaying and insulated busbar configurations that reduce incident energy calculations below 8 cal/cm². Heavy manufacturing clusters in Michigan, Ohio, and Pennsylvania are experiencing the most acute compliance pressure due to aging electrical infrastructure and high fault current levels.
Service unbundling is separating hardware procurement from long-term thermal monitoring and predictive maintenance contracts. Hyperscale operators in Texas and Arizona are negotiating outcome-based agreements where vendors guarantee maximum busbar temperature thresholds and mean-time-between-failure metrics. This restructuring shifts capital expenditure to operating expenditure and locks in multi-year vendor relationships that resist price-based competition.
United States Busbar Market Segmentation
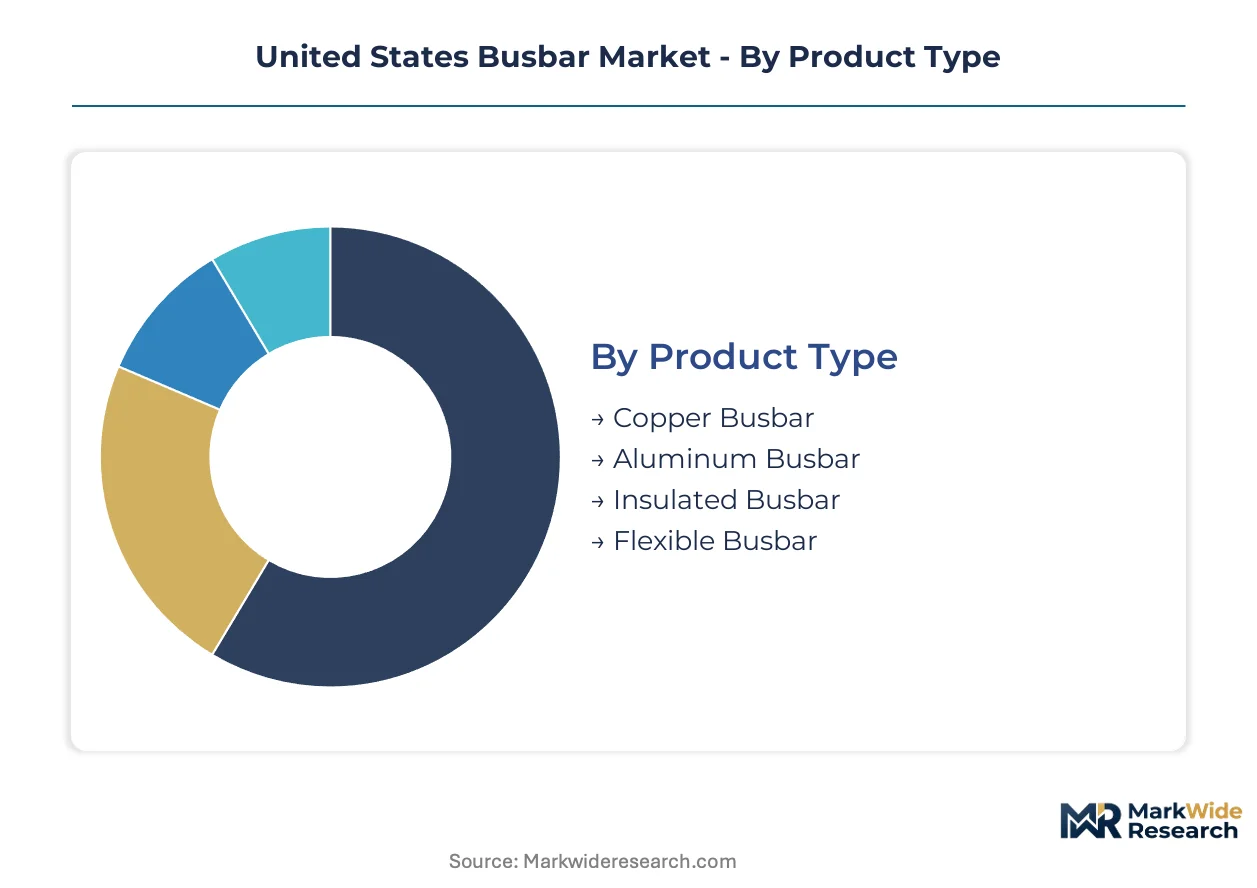
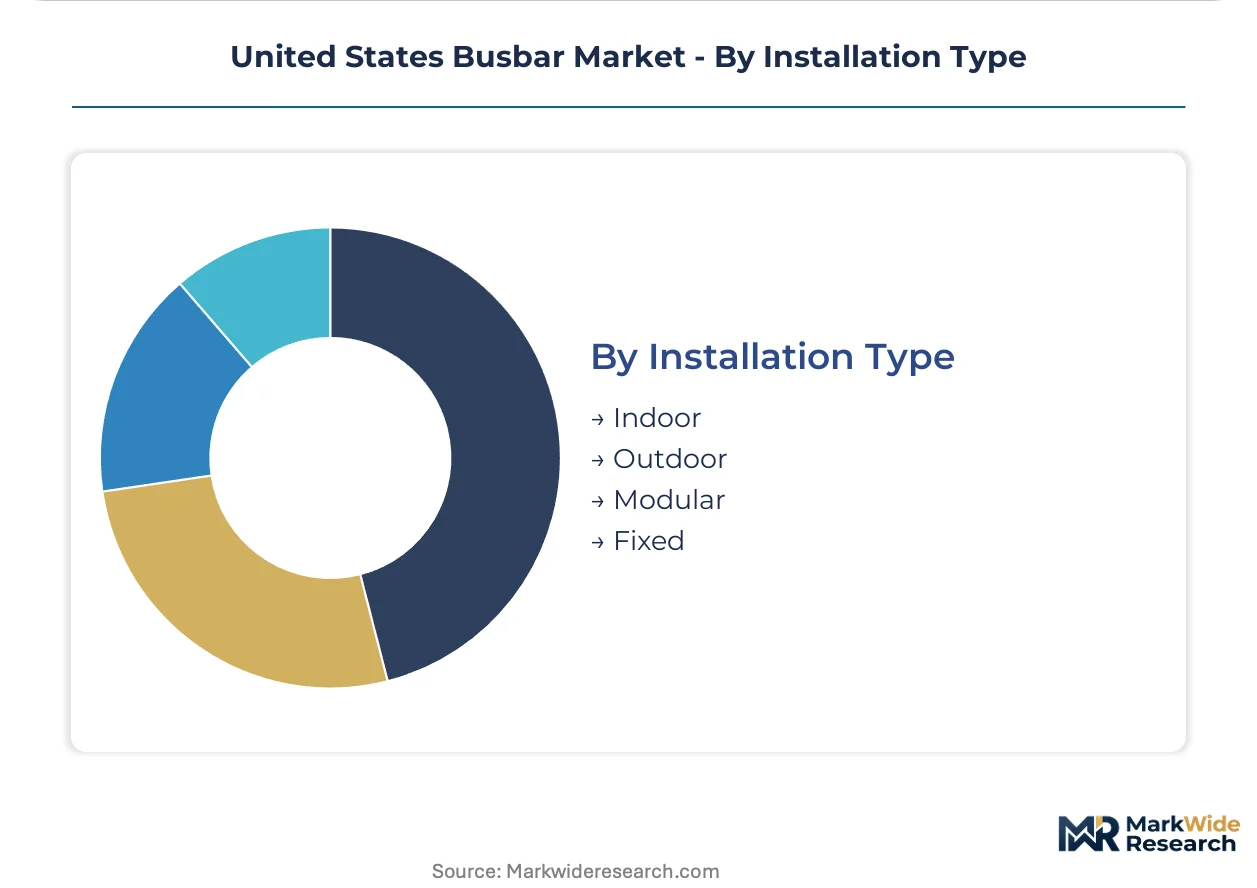
Busbar segmentation in the United States reflects divergent material economics and application-specific performance requirements. Product type splits between conductivity-optimized copper and cost-weight-optimized aluminum, while installation configurations respond to radically different site constraints across data centers, utility substations, and transportation corridors.
Product Type:
Copper commands premium positioning for thermal-critical applications, while aluminum captures volume through renewable energy scale deployment.
- Copper Busbar:99.9% pure electrolytic copper delivers 100% IACS conductivity ratings essential for 4000A+ hyperscale data center specifications. Northern Virginia and Phoenix operators specify copper exclusively for high-density power distribution where every degree of temperature rise compounds cooling infrastructure costs. Today's leader: Copper Busbar. Tomorrow's challenger: Insulated Busbar.
- Aluminum Busbar:6061-T6 alloy achieves 61% IACS conductivity at one-third copper weight and 40% lower material cost, dominating utility-scale solar and wind interconnection projects across Texas and Arizona. Sub-2000A ampacity ceiling excludes aluminum from hyperscale data center procurement, locking the material into cost-sensitive grid infrastructure.
- Insulated Busbar:Cast resin or epoxy powder coating eliminates phase-to-phase clearance requirements, enabling 50% space reduction in electrical rooms.
- Flexible Busbar:Laminated copper foil construction accommodates vibration and thermal expansion in transportation and industrial applications.
Material substitution patterns track copper LME pricing volatility, with aluminum gaining ground when spreads exceed 2.5x.
Application:
Power distribution anchors revenue through data center concentration, while renewable energy builds the fastest expansion trajectory.
- Power Distribution:Switchgear and substation busbar systems handle 15kV-38kV distribution voltages across utility and industrial networks. Texas ERCOT interconnection queues and Virginia Dominion Energy transmission upgrades are concentrating procurement for 3000A-5000A rigid busbar configurations with integrated thermal monitoring.
- Renewable Energy:Solar PV and battery storage installations require modular, bidirectional busbar systems compliant with FERC Order 2222 distributed resource interconnection rules. Arizona and California utility-scale solar farms are driving demand for aluminum busbar in 1500V DC collector systems where weight reduction accelerates field installation.
- Railways:Traction power substations and third-rail connections demand vibration-resistant flexible busbar with silver-plated contact surfaces.
- Industrial Automation:Motor control centers and robotic power feeds specify compact insulated busbar to minimize arc-flash incident energy per OSHA 1910.269.
Application mix is tilting toward renewable energy as IRA manufacturing credits accelerate domestic solar and battery supply chain buildout.
End User:
Utilities maintain procurement scale through transmission infrastructure cycles, while manufacturing and commercial buildings drive replacement demand.
- Utilities:Investor-owned utilities and rural electric cooperatives specify busbar for substation expansion and grid modernization programs. ERCOT, PJM Interconnection, and CAISO transmission operators are advancing procurement for 345kV gas-insulated switchgear with integrated busbar systems.
- Manufacturing:Automotive, semiconductor, and heavy machinery facilities require arc-flash-rated busbar configurations with protective relaying integration. Michigan and Ohio manufacturing clusters face acute OSHA compliance pressure due to aging electrical infrastructure and high fault current levels.
- Transportation:Airport, port, and rail electrification projects specify corrosion-resistant outdoor busbar installations.
- Commercial Buildings:Data center, healthcare, and high-rise office retrofits are adopting insulated busbar to solve legacy infrastructure space constraints and arc-fault containment mandates.
End user concentration is fragmenting as commercial building retrofits and transportation electrification diversify demand beyond traditional utility procurement.
Installation Type:
Indoor specifications dominate value capture through data center density premiums, while modular configurations are displacing fixed installations in fast-deploy infrastructure.
- Indoor:Climate-controlled electrical rooms in hyperscale facilities specify low-impedance copper busbar with forced-air or liquid cooling integration. Northern Virginia Ashburn-Dulles corridor operators are standardizing on 4000A+ indoor busbar with embedded fiber-optic temperature sensing.
- Modular:Prefabricated electrical skids and containerized power modules treat busbar as repeatable, factory-tested subsystems rather than field-assembled infrastructure. Phoenix and Dallas-Fort Worth data center developments are specifying modular busbar to compress construction schedules and reduce on-site commissioning risk.
- Outdoor:NEMA 3R and 4X enclosures protect busbar from moisture, dust, and temperature extremes in substation and renewable energy applications.
- Fixed:Traditional bolted rigid busbar remains standard for permanent utility substation installations with 30-40 year design lifecycles.
Installation preference is pivoting toward modular as hyperscale operators prioritize speed-to-market over customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA domestic content incentives and NEPA compliance cost differentials are redirecting supplier capital toward US-based fabrication, compressing procurement cycles for hyperscale operators concentrated in three primary state clusters.
Texas
ERCOT interconnection queues and hyperscale data center buildouts in Dallas-Fort Worth and Austin drive demand for 4000A+ copper busbar with integrated thermal monitoring. FERC Order 2222 implementation expands utility procurement specifications for modular, bidirectional systems. The Dallas-Fort Worth corridor anchors the nation's fastest-growing data center power distribution equipment market.
Virginia
Dominion Energy transmission upgrades and Northern Virginia's Ashburn-Dulles data center cluster concentrate procurement for low-impedance indoor busbar with embedded fiber-optic temperature sensing. State renewable portfolio mandates accelerate utility-scale solar interconnection projects requiring aluminum busbar in 1500V DC collector systems. Loudoun County maintains the highest data center power density per square mile nationally.
Arizona
Utility-scale solar farms and battery storage installations in Maricopa and Pima counties drive aluminum busbar demand for weight-sensitive field installation. OSHA electrical safety directive enforcement pushes industrial facilities toward insulated busbar configurations with arc-flash mitigation below 8 cal/cm². Phoenix data center operators standardize on modular busbar to compress construction schedules.
Ohio
Section 45X advanced manufacturing credits incentivize greenfield busbar fabrication facilities serving Midwest industrial and utility markets. Heavy manufacturing clusters in Cleveland and Cincinnati face acute OSHA 1910.269 compliance pressure due to aging electrical infrastructure and high fault current levels. The state anchors IRA-driven reshoring of electrical equipment supply chains.
California
Commercial building arc-fault containment mandates in Los Angeles and San Francisco metro areas create replacement demand for compact, insulated busbar in legacy electrical infrastructure. CPUC interconnection rules and state renewable portfolio standards shape utility procurement specifications for grid-scale power distribution equipment. The state leads national adoption of cast resin insulated busbar for space-constrained retrofits.
United States Busbar Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical equipment conglomerates commanding premium positioning in data center specifications while regional fabricators capture utility-scale aluminum volume. The vendor base organizes around three strategic archetypes: full-system integrators leveraging switchgear installed bases, component specialists focused on conductivity-optimized copper products, and modular power skid providers treating busbar as standardized subsystems. Dominant competitive moves include backward integration into copper and aluminum processing to secure material cost stability, and outcome-based service contracting that shifts customer relationships from equipment procurement to performance guarantees.
Among diversified electrical equipment conglomerates, Eaton Corporation PLC and Schneider Electric SE exemplify the full-system integrator archetype, anchoring competitive positioning around recurring service revenue streams and software-enabled power management platforms. Siemens Aktiengesellschaft occupies a parallel position, representing the European-based multinational approach to integrated building automation and power distribution systems. These three companies sit within the premium tier where vendor selection prioritizes long-term performance guarantees over unit economics.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Legrand S.A |
| ABB Ltd |
| Luvata |
| American Power Connection Systems Inc |
| Siemens Aktiengesellschaft |
| TE Connectivity Ltd |
| Rittal |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Hyperscale data center operators in Northern Virginia and Phoenix are mandating 8-week equipment delivery windows that compress supplier lead times and force fabrication premiums into copper busbar configurations. This procurement pressure is reshaping supplier economics toward domestic manufacturing investments that qualify for IRA Section 45X credits while insulating against LME copper volatility.
Pricing Analysis
Direct-to-OEM volume discounts dominate the channel structure, with three-tier pricing stratification across UL-certified premium, standard IEC-grade, and economy aluminum tiers. Price differentiation hinges on certification tier and after-sales thermal monitoring bundling. Cost compression in the economy aluminum segment is intensifying because of Chinese import competition. Utilities exhibit the highest price sensitivity due to procurement committee oversight, while data center operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators are forcing qualification of secondary copper suppliers across Ohio, South Carolina, and Texas. Raw material feeds draw from Chilean and Peruvian mining concentrates, domestic scrap recovery operations, and Canadian refined cathode. Single-source vulnerability concentrates in electrolytic copper rod processing. Distribution runs through electrical equipment distributors serving contractor and utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Busbar Market operates as a regulatory compounder where FERC Order 2222 distributed resource interconnection rules are mandating bidirectional power flow capabilities that expand specification complexity and vendor qualification barriers.
For Market Incumbents: Deploy backward integration into copper rod casting to secure material cost stability against LME volatility. Anchor recurring revenue through outcome-based thermal monitoring contracts that lock in multi-year relationships. Aluminum substitution threats from renewable energy procurement require defensive certification investments in high-ampacity copper configurations. For New Entrants and Emerging Players: Regional electrical contractors represent the most accessible channel partner type for penetrating commercial building retrofit demand in California and Illinois. Target insulated busbar replacement cycles driven by OSHA arc-flash compliance deadlines. White-space exists in modular power skid integration for Phoenix and Dallas-Fort Worth data center developments. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists possessing UL 857 certification capabilities and established relationships with Dominion Energy or ERCOT transmission planners. Long-term viability centers on vendors that can bridge hardware fabrication with software-enabled predictive diagnostics. Watch NEPA permitting velocity as the signal indicating transmission infrastructure procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Footprint Expansion | Section 45X credits reduce effective production costs for Ohio and Texas facilities serving hyperscale demand. |
| Software-Defined Power Management Platform | Integration with building automation protocols extends customer lifetime value beyond hardware replacement cycles. |
| Backward Integration into Copper Processing | Captive supply of electrolytic rod insulates fabrication margins from LME price swings above 20% annually. |
| Predictive Diagnostics Service Unbundling | Outcome-based temperature threshold guarantees shift capital expenditure to operating expenditure for data center operators. |
| Modular Power Skid Partnership | Prefabricated electrical subsystems compress construction schedules for Northern Virginia and Phoenix brownfield expansions. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center procurement directors, utility transmission planners, electrical contractor project managers, and busbar fabrication plant engineers with secondary validation against FERC interconnection filings, EIA generation capacity databases, SEC 10-K equipment supplier disclosures, and OSHA enforcement records. Bottom-up installation tracking and top-down utility capital expenditure analysis were triangulated to reconcile segment estimates.
Segment-weighting approaches modeled product type splits, application concentration across power distribution and renewable energy, end-user procurement patterns, and installation configuration preferences. CAGRs were derived from installation run-rate projections and capital commitment pipelines across the projection horizon. Forecast inputs incorporated copper LME forward curves, NEPA permitting velocity indicators, and IRA domestic content qualification thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility, federal environmental review timeline reforms, and state renewable portfolio mandate acceleration. Deviation in NEPA streamlining legislation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Wire Splicing Kits Market