
 United States Circuit Breaker Market | 2026-2036
United States Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
United States Circuit Breaker Market Intelligence
Modular panel configurations with pre-integrated breakers and busbars is expanding buyer choice across commercial and industrial segments. Siemens AG leverages its vertical manufacturing footprint to dominate supply contracts for large-scale utility deployments. Schneider Electric anchors its position through deep channel control in the electrical wholesale network. Eaton Corporation differentiates via specialized thermal magnetic and electronic trip units for harsh-environment applications.
A circuit breaker is an electromechanical switching device engineered to interrupt fault currents automatically when overload or short-circuit conditions exceed rated thermal or magnetic thresholds, typically specified by interrupting capacity in kiloamperes and voltage class. Its primary purpose is protecting electrical distribution systems, equipment, and personnel from thermal damage and fire hazards. Molded case circuit breakers occupy the largest volume tier across commercial and light industrial installations, while smart technology trip platforms represent the fastest-growing margin pool as facilities prioritize predictive maintenance and remote monitoring. Residential demand concentrates in miniature circuit breakers with standard thermal magnetic protection, though electronic trip precision is penetrating premium home segments.
The National Electrical Code (NEC), enforced by local authorities having jurisdiction, mandates arc-fault and ground-fault protection standards that directly dictate breaker specification in new construction and renovation. OSHA electrical safety regulations and NEMA performance standards further constrain product design and market access for non-compliant imports. Stakeholders must monitor state-level amendments to the NEC, particularly in California and Texas, where accelerated electrification timelines are forcing faster product qualification cycles.
Market Dynamics
The Inflation Reduction Act's clean energy incentives are accelerating utility-scale grid modernization, forcing breaker manufacturers to compress qualification cycles for higher interrupting capacity ratings while data center power density requirements reshape procurement specifications.
Growth Catalysts
- Data center power infrastructure expansion:Hyperscale facilities in Texas, Virginia, and Arizona are driving procurement of high-capacity breakers with electronic trip platforms and zone-selective interlocking capabilities.
- OSHA electrical safety enforcement:Enhanced workplace safety inspections are compelling industrial facilities to upgrade legacy thermal-magnetic breakers to arc-fault detection devices.
- California Title 24 electrification mandates:The state's accelerated building decarbonization timeline is forcing faster product qualification cycles for smart breaker platforms in commercial construction.
Market Restraints
- Copper and silver contact volatility:Raw material price swings in precious metal contacts are compressing gross margins for molded case circuit breaker producers.
- Asian supply concentration:Dependence on Taiwanese and South Korean semiconductor foundries for electronic trip unit chips creates vulnerability in smart breaker production.
- NEC amendment fragmentation:State-level electrical code variations between Texas, California, and Florida force redundant testing and certification costs.
Strategic Opportunities
- Florida hurricane-hardening programs:Utility resilience investments are creating demand for vacuum circuit breakers with extended mechanical endurance ratings.
- Digital twin integration:Convergence of breaker trip data with building management systems enables predictive maintenance subscription models for industrial facilities.
- Texas ERCOT grid flexibility markets:Demand response participation requirements are opening specification channels for remotely controllable smart breakers in commercial buildings.
Industry Challenges
- Power systems engineer scarcity:Specialized expertise in protective relay coordination and arc flash analysis is constraining deployment velocity for complex breaker retrofits.
- UL 489 certification backlog:Testing laboratory capacity constraints are extending time-to-market for new molded case circuit breaker designs by six to nine months.
- Legacy motor control center integration:Retrofitting electronic trip units into existing MCC buckets requires custom busbar modifications and field engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Circuit Breaker Market |
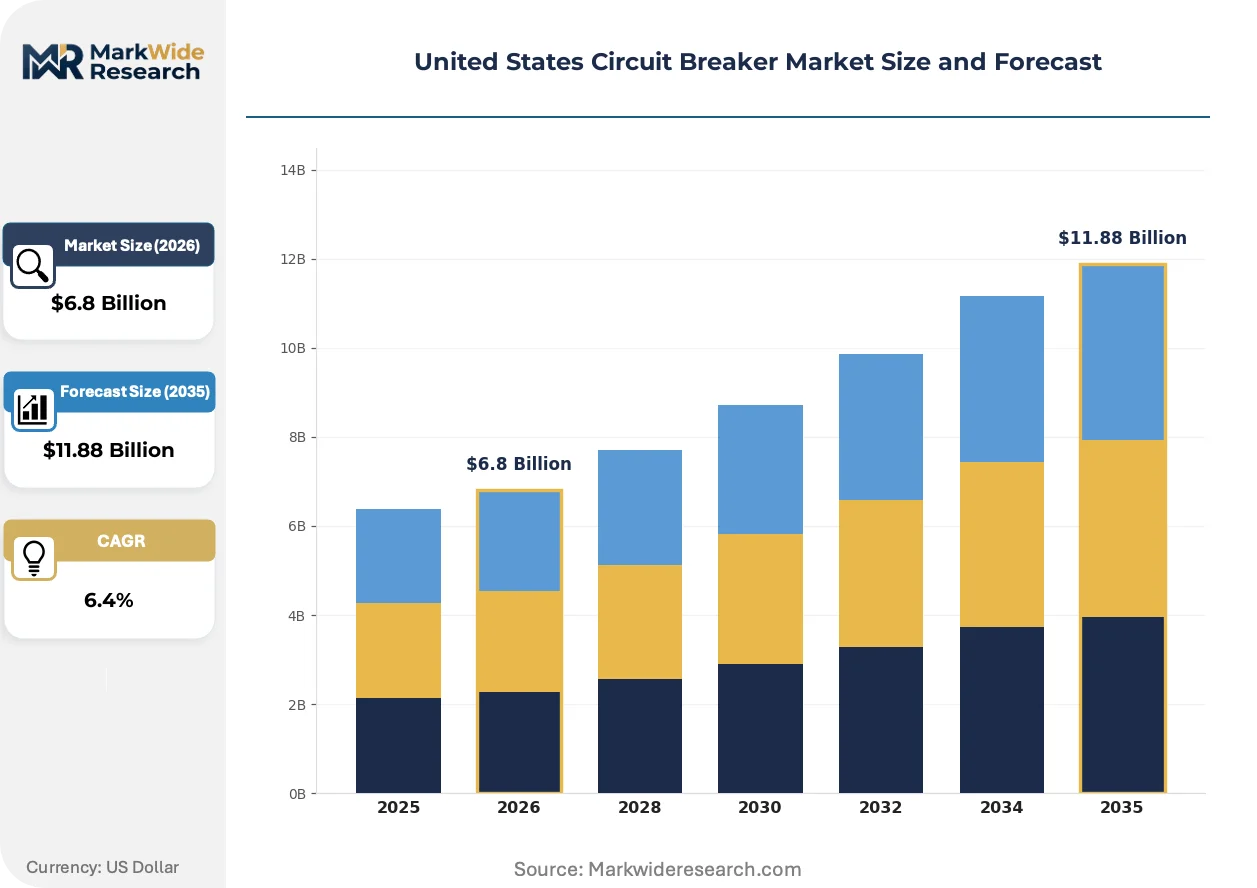
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breaker, Molded Case Circuit Breaker, Air Circuit Breaker, Earth Leakage Circuit Breaker Application: Residential, Commercial, Industrial, Utility Technology: Hydraulic Magnetic, Electronic, Thermal Magnetic, Smart Technology Installation: Panel Mounting, DIN Rail Mounting, Flush Mounting, Surface Mounting |
| Companies Covered | Siemens AG, Leviton Manufacturing, Schneider Electric, Rockwell Automation, Noark Electric, Eaton Corporation, General Electric, LS Electric USA, ABB Electrification, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Circuit Breaker Market Strategic Shifts & Innovations
Breaker technology is converging with digital infrastructure, as electromechanical protection gives way to software-defined trip characteristics and real-time power quality monitoring. This shift is compressing traditional equipment replacement cycles.
Electronic trip units with embedded power quality analytics are integrating communications protocols directly into molded case and power circuit breaker platforms. Data center operators and heavy industrial facilities are adopting these devices to enable condition-based maintenance and reduce unplanned downtime. The technology is integrating breaker status data with enterprise asset management systems, collapsing the boundary between electrical protection and operational technology infrastructure.
The National Electrical Code's 2023 expansion of arc-fault circuit interrupter requirements to dormitory and hotel applications is mandating breaker specification changes across multi-family construction. Manufacturers must now engineer dual-function AFCI/GFCI breakers with reduced nuisance tripping for commercial laundry and kitchen circuits. The residential and hospitality segments are responding by consolidating supplier relationships to secure volume pricing on compliant devices.
Electrical contractors and industrial maintenance teams are consolidating procurement through integrated supply agreements with national electrical distributors. Traditional spot purchasing through local counter sales is yielding to multi-year framework contracts with embedded technical support and inventory management services. This consolidation is most visible in the Texas and California commercial construction markets, where general contractors are bundling breaker procurement with prefabricated electrical skids.
United States Circuit Breaker Market Segmentation
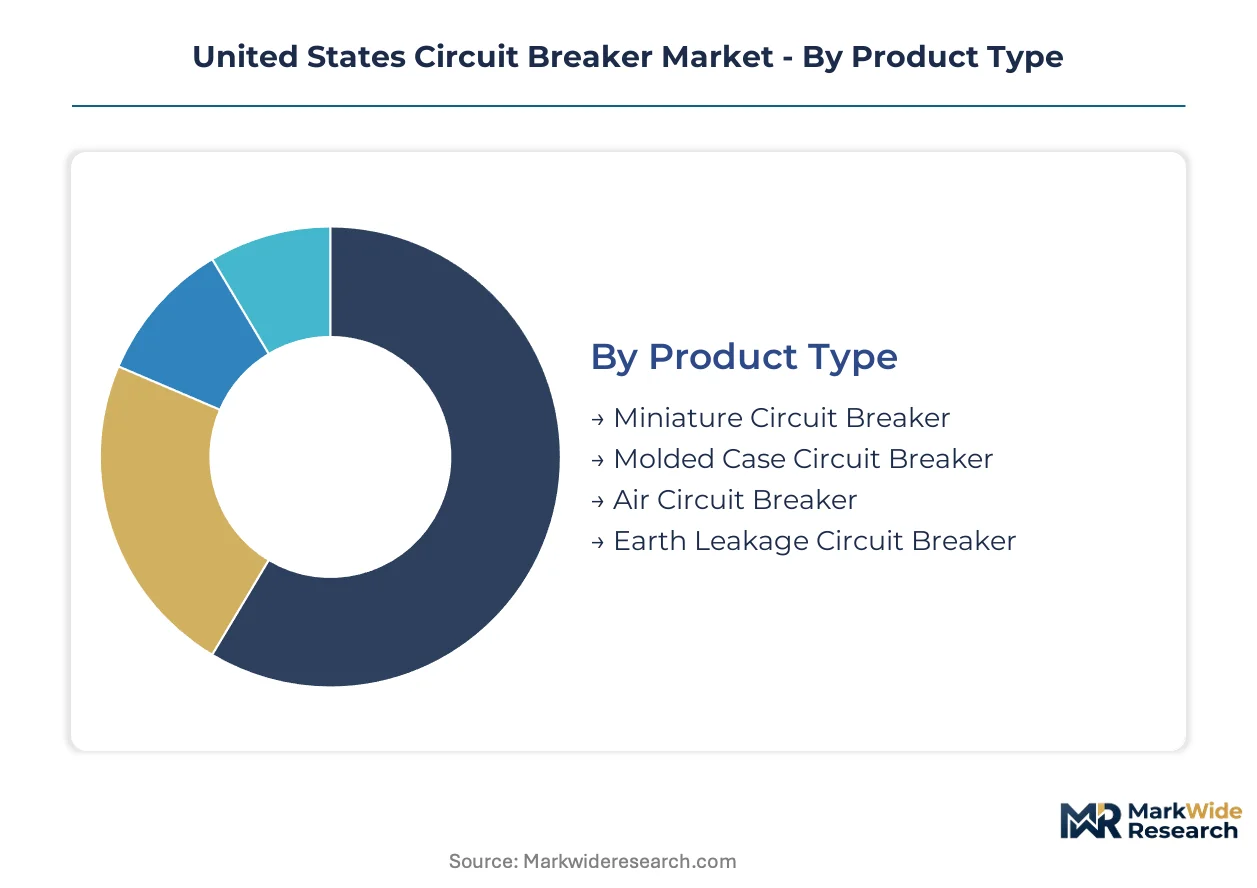
Circuit breaker procurement in the United States fragments across four distinct category axes. Buyers select product types based on interrupting capacity requirements, specify technology tiers according to maintenance sophistication, and choose mounting configurations to match existing electrical infrastructure footprints.
Product Type:
Cost tier separates buyers in this category — from commodity residential replacements to engineered utility-grade solutions.
- Miniature Circuit Breaker:Compact thermal-magnetic devices rated below 125 amperes dominate single-family residential panels. NEC arc-fault mandates in Texas and California are accelerating replacement cycles in aging housing stock.
- Molded Case Circuit Breaker:Thermoset plastic housings enclose trip mechanisms rated 15A to 2500A, forming the backbone of commercial building distribution. Texas data center construction and Florida hurricane-hardening programs are concentrating demand for higher interrupting capacity ratings.
- Air Circuit Breaker:Open-frame designs with draw-out mechanisms serve low-voltage switchgear applications above 2500A. Industrial facilities in Ohio and Michigan specify these for motor control center main breakers.
- Earth Leakage Circuit Breaker:Ground-fault detection variants protect personnel in wet-location applications. Commercial kitchen and healthcare construction in California drives specification of combined AFCI/GFCI platforms.
Molded case circuit breakers lead volumes today; smart technology trip platforms are gaining share fastest.
Application:
Application scope determines voltage class, fault current ratings, and communications requirements.
- Residential:Single-family and multi-family construction specifies miniature breakers with standard thermal-magnetic protection. California Title 24 electrification mandates are forcing faster product qualification cycles for smart breaker platforms in new home construction.
- Commercial:Office buildings, retail centers, and hospitality facilities require molded case breakers with electronic trip precision. Texas and California general contractors are consolidating procurement through integrated supply agreements with national electrical distributors.
- Industrial:Heavy manufacturing and process industries demand air circuit breakers with zone-selective interlocking. OSHA electrical safety enforcement is compelling facilities to upgrade legacy thermal-magnetic breakers to arc-fault detection devices.
- Utility:Transmission and distribution networks specify high-capacity vacuum and SF6 breakers. Florida hurricane-hardening programs are creating demand for vacuum circuit breakers with extended mechanical endurance ratings.
Commercial applications anchor current revenue; utility procurement is expanding most quickly.
Technology:
Technology tier reflects maintenance philosophy — from set-and-forget thermal devices to predictive analytics platforms.
- Thermal Magnetic:Bimetallic strips and magnetic coils provide time-current protection without external power. Legacy industrial facilities in Pennsylvania and Illinois continue specifying these for cost-sensitive motor branch circuits.
- Electronic:Microprocessor-based trip units enable precise time-current curve adjustment and ground-fault protection. Data center operators in Virginia and Arizona are adopting these for selective coordination with upstream devices.
- Hydraulic Magnetic:Fluid-filled dashpots provide temperature-stable tripping for harsh-environment applications. Marine and mining operations in Louisiana and West Virginia specify these where ambient conditions fluctuate.
- Smart Technology:Embedded communications and power quality analytics enable remote monitoring and predictive maintenance. Texas ERCOT grid flexibility markets are opening specification channels for remotely controllable smart breakers in commercial buildings.
Thermal magnetic platforms dominate installed base; smart technology is climbing the fastest.
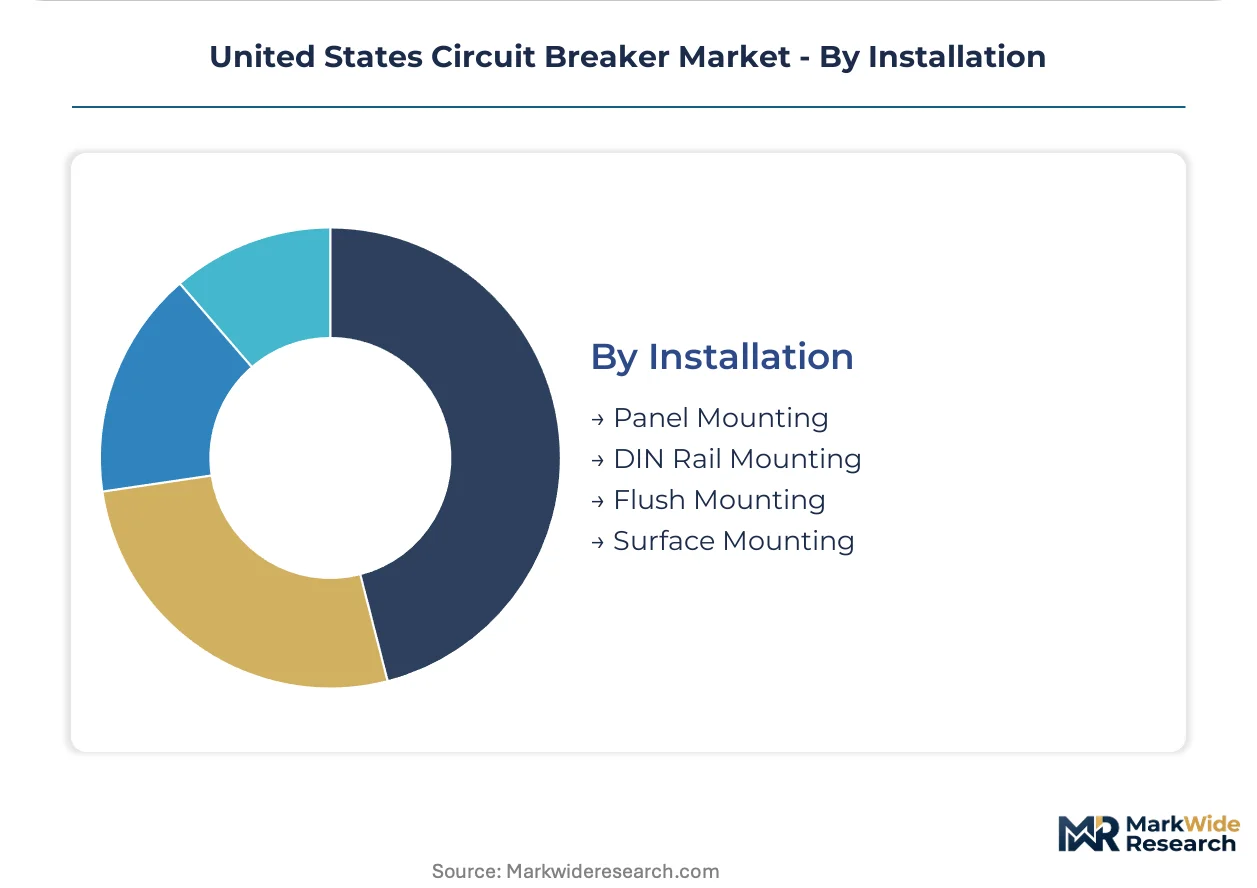
Installation:
Mounting configuration locks buyers into specific panel architectures and replacement pathways.
- Panel Mounting:Direct attachment to busbars within switchgear assemblies and motor control centers. Industrial retrofit projects in Ohio face legacy motor control center integration challenges requiring custom busbar modifications.
- DIN Rail Mounting:Standardized 35mm rail attachment dominates European-influenced control panel designs. Machine builder OEMs in Wisconsin and Illinois prefer this for compact control enclosures.
- Flush Mounting:Recessed installation within wall cavities serves residential and light commercial aesthetic requirements. California multi-family construction mandates are driving specification of dual-function AFCI/GFCI breakers in flush-mounted panels.
- Surface Mounting:Exposed enclosure attachment supports temporary power and outdoor distribution applications. Florida utility resilience investments specify surface-mounted vacuum breakers for substation hardening.
Panel mounting leads volumes today; DIN rail mounting is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States circuit breaker industry traces its commercial roots to early twentieth-century electrification programs in the Northeast, where industrial demand first standardized protective switchgear specifications before regional expansion carried manufacturing expertise across the continent.
Texas
Hyperscale data center construction in Dallas-Fort Worth and Austin drives procurement of high-capacity breakers with electronic trip platforms. ERCOT grid flexibility markets under PUCT regulations create specification channels for remotely controllable smart breakers in commercial buildings. Houston's petrochemical corridor anchors industrial demand for air circuit breakers in motor control center applications.
California
Title 24 electrification mandates accelerate product qualification cycles for smart breaker platforms in commercial and residential construction. CEC building decarbonization timelines force faster NEC adoption than federal minimums. Silicon Valley data centers and Bay Area multi-family housing concentrate demand for dual-function AFCI/GFCI breakers with reduced nuisance tripping.
Florida
Utility resilience investments under hurricane-hardening programs generate demand for vacuum circuit breakers with extended mechanical endurance ratings. FPL and Duke Energy grid modernization contracts specify surface-mounted substation equipment. Miami-Dade and Tampa-St. Petersburg metropolitan construction drives commercial molded case breaker volumes.
Illinois
Legacy industrial facilities in Chicago and Rockford face OSHA electrical safety enforcement compelling upgrades from thermal-magnetic to arc-fault detection devices. The state's manufacturing heritage preserves specification preferences for traditional panel-mounted configurations. Machine builder OEMs in the Wisconsin-Illinois border region prefer DIN rail mounting for compact control enclosures.
Virginia
Northern Virginia's data center alley concentrates procurement of breakers with zone-selective interlocking capabilities for selective coordination. Dominion Energy grid infrastructure investments support utility-grade vacuum breaker deployment. State procurement guidelines favor electronic trip precision for critical facility power distribution.
United States Circuit Breaker Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology tier and application complexity, with electronic trip and smart technology platforms commanding pricing separation from thermal-magnetic alternatives. The vendor base clusters around three strategic archetypes: diversified electrical equipment conglomerates with captive distribution, specialized protective device manufacturers with deep application engineering, and Asian-origin challengers competing on cost-position in standard ratings. Dominant competitive moves include vertical manufacturing footprint expansion and long-term integrated supply agreements with national electrical distributors.
Within the diversified conglomerate tier, Siemens AG and Schneider Electric exemplify players leveraging scale and channel control, while Eaton Corporation occupies a position bridging engineered solutions and broad market coverage. These three entities anchor the competitive structure through distinct positioning—Siemens through utility-scale deployment capability, Schneider through wholesale network penetration, and Eaton through harsh-environment specialization. LS Electric USA represents the Korean-origin challenger archetype competing on manufacturing efficiency in standard commercial ratings. The competitive dynamic centers on qualification speed for evolving NEC requirements and data center specification capture rather than pure price competition.
| Leading Market Players |
|---|
| Siemens AG |
| Leviton Manufacturing |
| Schneider Electric |
| Rockwell Automation |
| Noark Electric |
| Eaton Corporation |
| General Electric |
| LS Electric USA |
| ABB Electrification |
| Others |
Cost & Logistics Intelligence
Power systems engineer scarcity in Texas and California widens labor-cost differentials between premium electronic trip platforms and commodity thermal-magnetic alternatives, compressing margins in the standard tier while insulating pricing power for smart breaker specialists with captive field service networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UL-certified electronic trip units from IEC-compliant thermal-magnetic devices and imported commodity miniature breakers. Price differentiation centers on interrupting capacity ratings and embedded communications capability. Cost compression in the standard molded case tier intensifies because of copper contact volatility and Asian import competition. Residential contractors exhibit highest price sensitivity, while data center operators prioritize selective coordination precision over unit economics.
Supply Chain Analysis
Silver and copper contact supply rests on Chilean mining operations and domestic scrap recovery networks, with semiconductor foundry capacity for electronic trip units concentrated in Taiwan and South Korea. Raw material dependencies include precious metal contacts, thermoset plastic resins, and microprocessor chips. Single-source vulnerability in Taiwanese semiconductor fabrication creates production bottlenecks for smart breaker platforms. Distribution runs through national electrical distributors with integrated supply agreements, bypassing traditional local counter sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States circuit breaker market functions as a stable compounder, with NEC-mandated replacement cycles and data center infrastructure buildouts generating predictable demand visibility regardless of macroeconomic volatility.
For Market Incumbents: Deepen captive field engineering capabilities to accelerate legacy motor control center retrofits, insulating margin position from Korean-origin challengers competing on standard commercial ratings. Invest in UL 489 pre-certification testing capacity to compress time-to-market for dual-function AFCI/GFCI platforms ahead of state-level NEC amendments. For New Entrants and Emerging Players: The Inflation Reduction Act's clean energy incentives in Texas open a window for specification capture in utility-scale grid modernization projects. Target vacuum circuit breaker deployment for Florida hurricane-hardening programs, leveraging extended mechanical endurance ratings as the primary go-to-market angle against established air circuit breaker suppliers. For Investors and Strategic Acquirers: Diversified electrical equipment conglomerates are the most active acquirer in this space, consolidating specialized protective device manufacturers to fill smart technology gaps. Over a five-to-ten-year horizon, acquisition premiums concentrate on electronic trip engineering teams with predictive maintenance software integration capability. Watch for PUCT regulatory expansion of demand response markets as the inflection signal for remotely controllable breaker adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Manufacturing | Captive silver-copper supply insulates margins from LME price volatility. |
| Smart Breaker Platform Certification | UL 489 pre-qualification accelerates NEC amendment response in California. |
| Integrated Supply Agreement Expansion | Multi-year distributor contracts lock out spot-market competitors in Texas. |
| Field Engineering Capability Buildout | Legacy MCC retrofit expertise commands premium pricing in Ohio industrial corridors. |
| Digital Twin Integration Partnership | Breaker trip data convergence with building management systems enables subscription revenue. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrical contractors, utility procurement officers, data center facility managers, and industrial maintenance directors with secondary validation against NEC amendment filings, OSHA enforcement databases, EIA grid infrastructure disclosures, and FERC interconnection queue data. Bottom-up breaker shipment analysis triangulated against top-down construction spending estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baselines and post-IRA implementation trajectories. The analytical framework modeled segmentation across product type, application, technology tier, and installation configuration, with regional regulatory cluster as an additional dimension. CAGRs derived from shipment volume trends and average selling price movements, incorporating data center power density requirements and state electrification timelines as industry-specific inputs.
Revisions become necessary when semiconductor supply disruptions, precious metal price spikes, or NEC amendment acceleration materialize. Forecasts reflect assumptions about continued data center construction velocity and utility grid modernization commitment. A small set of triggers—Taiwanese foundry capacity constraints, Texas ERCOT market rule changes, and California Title 24 enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Residual Current Circuit Breaker Market
Switches
Optical Switches Market
Switches
Vibration Level Switch Market
Switches
Transfer Switch Market
Switches
Global Switchgear Market
Switches
Analog Switches Market
Switches
Smart Pole-Mounted Switch Market
Switches
Asia Pacific Transfer Switches Market
Switches
Drive Mode Selector Switch and Controller Systems Market
Switches
Differential Pressure Switches Market
Switches
North America Medium Voltage Switchgear Market
Switches
Europe Low Voltage Switchgear Market
Switches
United States X by Wire Systems Market
Switches
South Korea Reed Sensors Switches Market
Switches
Europe Switchgear Market
Switches
Global Smart Switch Panel Market