
 Global Chronic Lymphocytic Leukemia Treatment Market | 2026-2036
Global Chronic Lymphocytic Leukemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chronic Lymphocytic Leukemia Treatment Market Intelligence
Next-generation sequencing integration into diagnostic workflows is narrowing the gap between biomarker identification and therapy selection in CLL care. AbbVie Inc. leverages its BCL-2 inhibitor portfolio to anchor relapsed and refractory segments. Johnson & Johnson competes through its BTK franchise across both first-line and subsequent treatment lines. F. Hoffmann-La Roche AG sustains immunotherapy relevance with its monoclonal antibody presence in combination protocols.
Chronic lymphocytic leukemia treatment encompasses pharmaceutical and biologic interventions targeting malignant B-cell proliferation, including small-molecule inhibitors, monoclonal antibodies, and chemotherapeutic agents administered via oral, intravenous, or subcutaneous routes. The primary purpose centers on disease remission induction, progression delay, and survival extension in a predominantly elderly patient population. Targeted therapy now leads product type allocation as BTK and BCL-2 inhibitors displace conventional chemotherapy in frontline settings. Oral medication dominates delivery mode preference due to patient convenience and outpatient cost structures. Immunotherapy maintains stable positioning in combination regimens despite single-agent limitations.
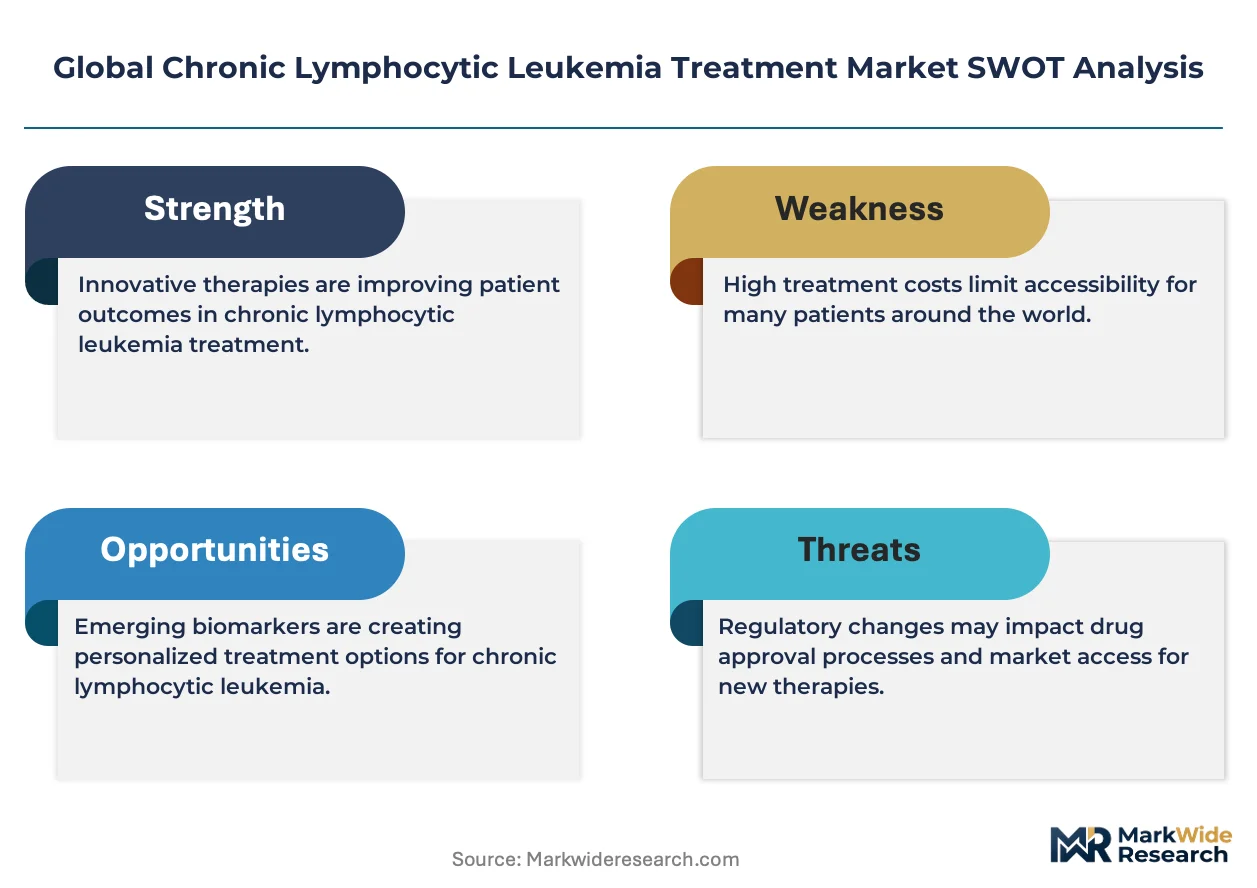
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for novel CLL agents while raising evidence thresholds for confirmatory trials. The EU MDR and FDA cGMP standards govern manufacturing quality for biologics and small molecules alike, shaping supplier qualification and facility investment requirements. WHO prequalification pathways influence access programs in lower-income settings. Stakeholders must monitor evolving EMA and FDA guidance on minimal residual disease endpoints as these criteria redefine value demonstration and reimbursement negotiations.
Market Dynamics
BTK and BCL-2 inhibitor pipelines are compressing chemotherapy's frontline role as hematology centers in the United States and Germany rewrite protocol standards. FDA breakthrough therapy pathways and EMA PRIME eligibility accelerate competitive entry timelines while raising evidentiary bars for confirmatory trials.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway compresses development timelines for novel CLL agents, enabling faster patient access to BTK inhibitor and BCL-2 inhibitor candidates.
- Next-generation sequencing integration:Diagnostic workflows in oncology hospitals narrow the biomarker-to-treatment selection gap, accelerating precision therapy adoption.
- Germany:Hematology centers in this market drive protocol standardization across Europe, anchoring BTK inhibitor-based combination regimens.
Market Restraints
- Manufacturing cost structure:Small-molecule BTK inhibitors and biologic monoclonal antibodies require specialized cGMP facilities, constraining supplier qualification.
- EMA MDR compliance burden:The Medical Device Regulation imposes stringent quality management system requirements on companion diagnostics used in CLL biomarker testing.
- Substitution pressure from biosimilars:Rituximab biosimilars erode branded monoclonal antibody pricing in relapsed settings, compressing revenue pools.
Strategic Opportunities
- India:CDSCO regulatory pathways and WHO prequalification programs create access expansion potential for oral targeted therapies in lower-income segments.
- Minimal residual disease endpoints:FDA and EMA guidance evolution redefines value demonstration criteria, opening reimbursement negotiation advantages for MRD-negative data holders.
- Fixed-duration combination protocols:BTK inhibitor plus BCL-2 inhibitor regimens without chemotherapy represent a treatment paradigm shift in frontline elderly populations.
Industry Challenges
- Confirmatory trial execution:FDA accelerated approval mandates require post-market outcome studies, stretching clinical operations capacity.
- Biomarker assay standardization:Discordance between IGHV mutation status and TP53 deletion testing across laboratories complicates therapy selection consistency.
- Supply chain cold chain integrity:Monoclonal antibody products require temperature-controlled distribution, creating logistics complexity for subcutaneous formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chronic Lymphocytic Leukemia Treatment Market |
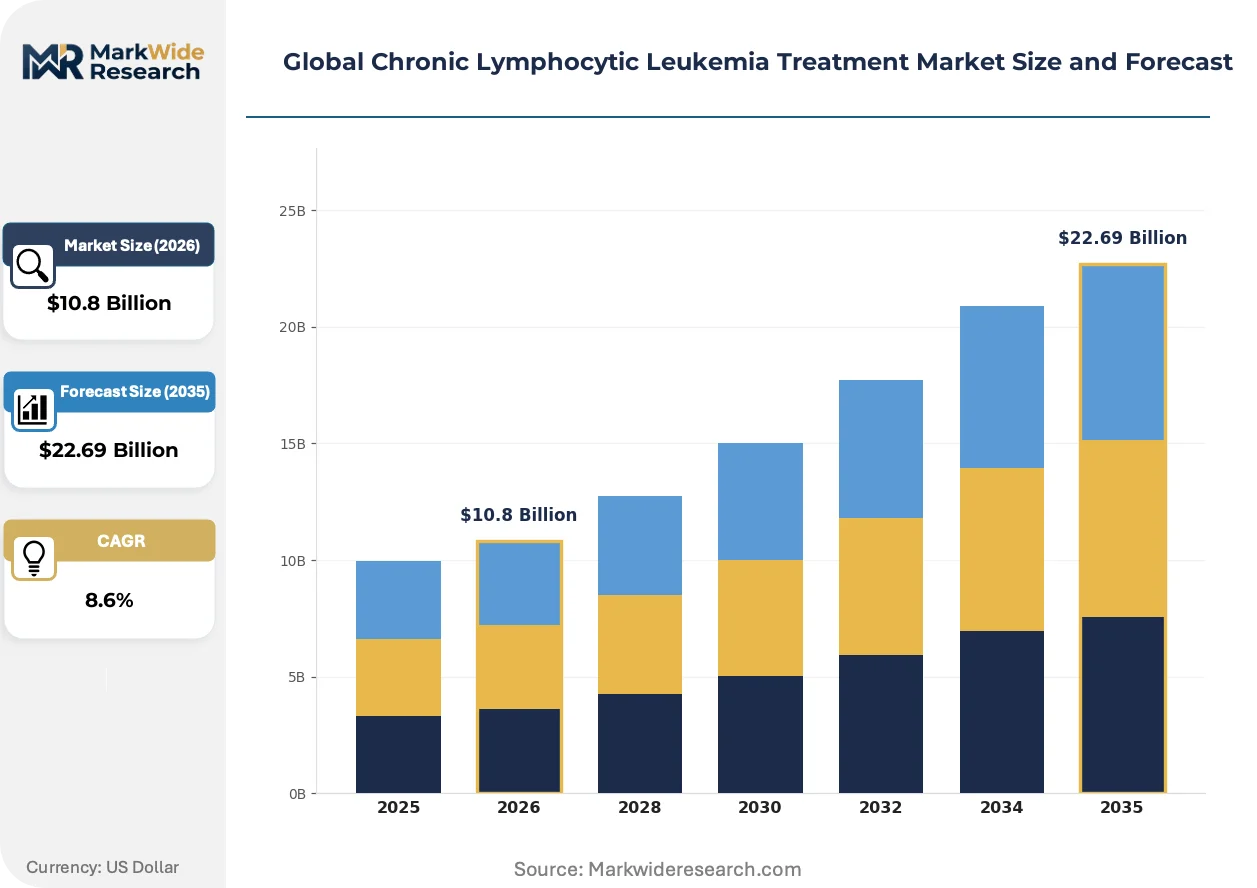
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $22.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Chemotherapy, Immunotherapy, Corticosteroids, Monoclonal Antibodies, Combination Therapy Therapy Area: First-Line Treatment, Relapsed/Refractory, Maintenance Therapy, Palliative Care End User: Specialty Clinics, Research Institutes, Hematology Centers, Diagnostic Laboratories, Oncology Hospitals Delivery Mode: Oral Medication, Intravenous Infusion, Subcutaneous Injection, Intramuscular Injection |
| Companies Covered | AstraZeneca plc, Johnson & Johnson, AbbVie Inc., Amgen Inc., Pfizer Inc., F. Hoffmann-La Roche AG, Gilead Sciences Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chronic Lymphocytic Leukemia Treatment Market Strategic Shifts & Innovations
Oral targeted therapy architectures are displacing infusion-dependent protocols across first-line and relapsed CLL settings. Three convergent forces reshape competitive positioning: technology migration toward fixed-duration combinations, regulatory elevation of MRD endpoints, and outpatient delivery model consolidation.
Next-generation BTK inhibitors with enhanced selectivity profiles are migrating from early-phase trials into frontline combination protocols. Hematology centers in the United States and Germany adopt these agents to reduce atrial fibrillation and bleeding risks associated with first-generation compounds. This migration is compressing the commercial lifespan of chemotherapy-backbone regimens and redefining prescriber education requirements.
EMA MDR and FDA cGMP standards are tightening manufacturing quality governance for biologics and small molecules alike. Facility investment requirements for aseptic processing and continuous manufacturing are rising, disqualifying smaller contract manufacturers. European oncology hospitals and United States specialty pharmacies now demand supplier ISO 13485 certification as a procurement prerequisite.
Outpatient administration models are consolidating CLL care away from infusion centers toward oral therapy management programs. United States payers and German sickness funds favor home-based monitoring to reduce hospitalization costs. This shift concentrates patient volume in hematology practices with robust remote monitoring infrastructure and pharmacy integration capabilities.
Global Chronic Lymphocytic Leukemia Treatment Market Segmentation
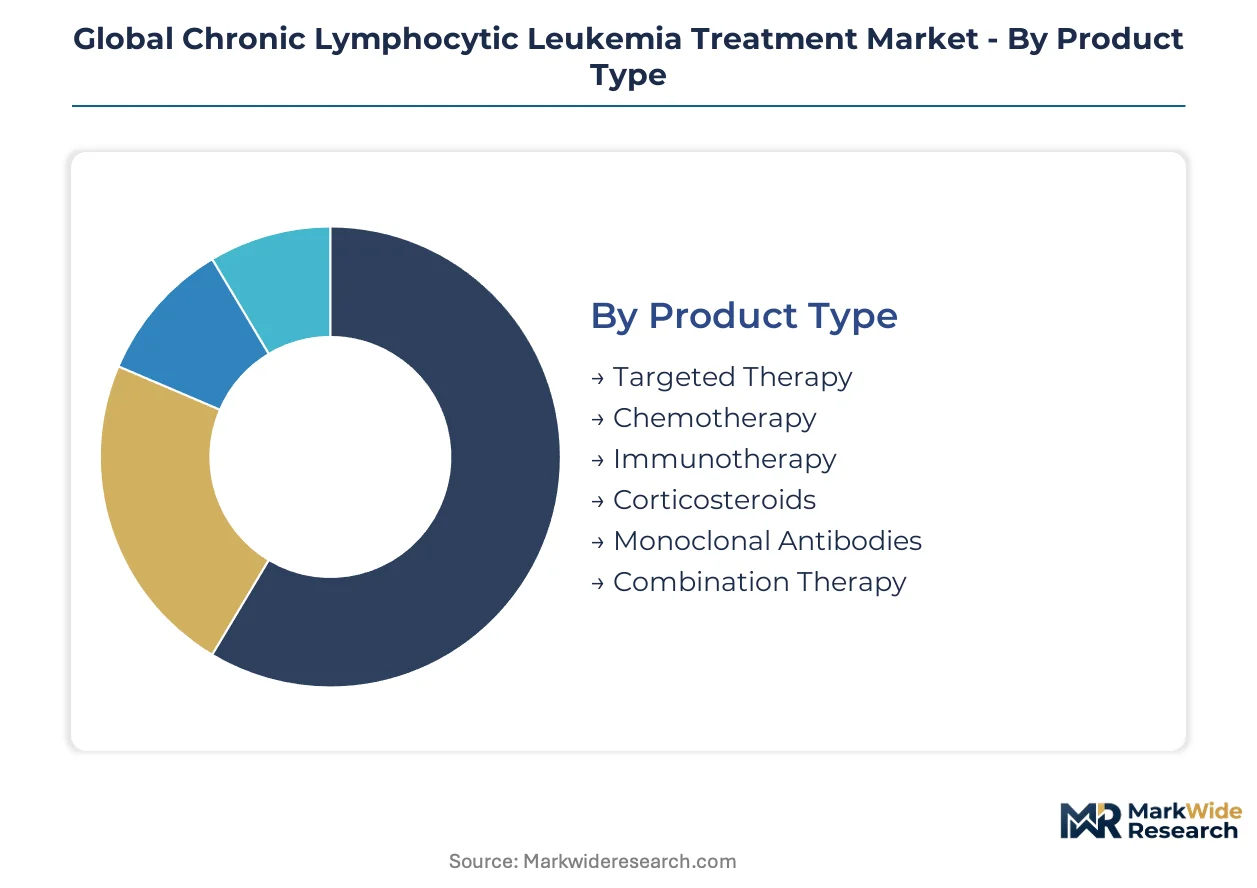
CLL treatment segmentation reveals how therapeutic innovation, patient acuity, and care setting economics fragment commercial opportunity. Each dimension carries distinct margin profiles, regulatory burdens, and service intensity requirements that shape vendor strategy.
Product Type:
After-sales service intensity varies sharply across product categories, with biologics demanding cold chain maintenance and patient monitoring programs that oral small molecules avoid.
- Targeted Therapy:BTK and BCL-2 inhibitors constitute precision pharmacology with biomarker-dependent prescribing. United States hematology centers anchor demand as FDA breakthrough designations compress trial-to-treatment timelines for these agents.
- Immunotherapy:Monoclonal antibodies like rituximab and obinutuzumab require infusion infrastructure and pre-medication protocols. Germany's sickness funds drive volume through standardized combination regimens in academic medical centers.
- Chemotherapy:Fludarabine-cyclophosphamide combinations retain niche utility in resource-constrained settings.
- Corticosteroids:Prednisone and methylprednisolone serve adjunctive roles in autoimmune complications.
- Monoclonal Antibodies:Anti-CD20 agents face biosimilar substitution pressure in relapsed populations.
- Combination Therapy:Fixed-duration BTK-BCL-2 protocols without chemotherapy represent the emerging clinical standard.
By volume, targeted therapy leads. By growth pace, combination therapy is ahead.
Therapy Area:
Patient journey positioning determines pricing power and clinical evidence requirements, with frontline settings commanding premium access terms.
- First-Line Treatment:Initial intervention in treatment-naïve patients demands durable remission data and favorable tolerability profiles. EMA PRIME eligibility accelerates novel agent entry into this high-value segment.
- Relapsed/Refractory:Progressive disease after prior therapy requires mechanism-of-action switching. United States oncology hospitals concentrate demand for CAR-T and novel inhibitor salvage regimens.
- Maintenance Therapy:Extended low-intensity intervention to prolong remission duration.
- Palliative Care:Symptom-focused management in advanced disease stages.
First-line treatment captures the largest revenue pool. Relapsed/refractory settings show the steepest expansion trajectory as resistance mechanisms multiply.
End User:
Procurement sophistication and patient volume concentration vary dramatically across site types, influencing contract structure and field force deployment.
- Oncology Hospitals:Comprehensive cancer centers integrate diagnosis, treatment, and clinical trial access. German university hospitals and United States NCI-designated centers set protocol standards that diffuse to community practice.
- Hematology Centers:Specialized units focus exclusively on blood malignancies with deep B-cell lymphoproliferative expertise. These sites drive adoption of MRD-guided treatment cessation protocols.
- Specialty Clinics:Community-based oncology practices with limited infusion capacity.
- Research Institutes:Academic centers conducting early-phase investigator-initiated trials.
- Diagnostic Laboratories:Centralized testing facilities for IGHV sequencing and FISH cytogenetics.
Oncology hospitals dominate patient volume. Hematology centers are gaining share fastest as care migrates toward subspecialized expertise.
Delivery Mode:
Administration route shapes total cost of care, with oral agents enabling outpatient management that reduces hospitalization expenditure.
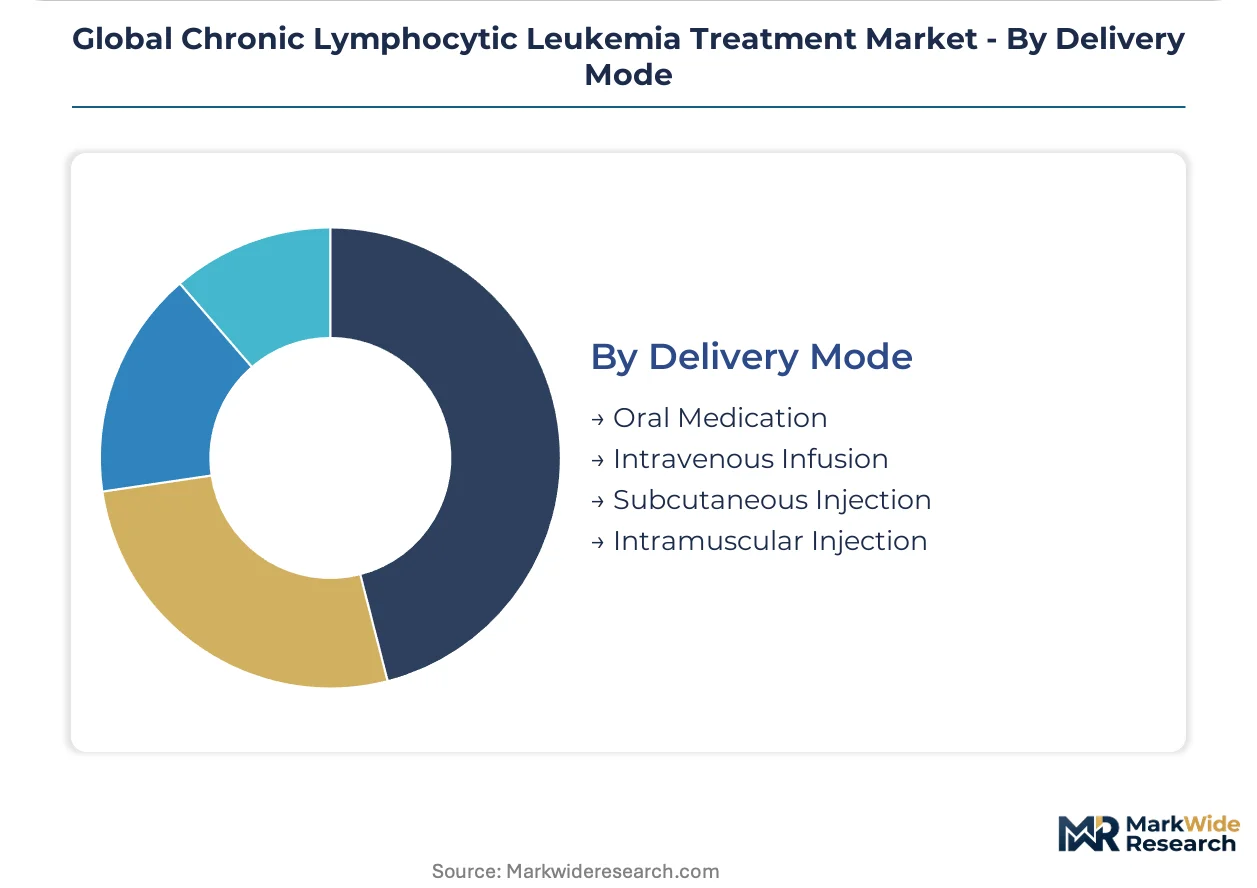
- Oral Medication:Self-administered BTK and BCL-2 inhibitors eliminate infusion center dependency. United States specialty pharmacies manage dispensing and adherence monitoring for these high-cost oral agents.
- Intravenous Infusion:Hospital-based monoclonal antibody delivery requires nursing supervision and adverse event readiness. German ambulatory care centers optimize same-day infusion throughput.
- Subcutaneous Injection:Patient-administered or clinic-based delivery with reduced chair time.
- Intramuscular Injection:Limited application for supportive care agents.
Intravenous infusion retains the largest installed base. Oral medication is climbing the fastest as fixed-duration protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports BTK inhibitor formulations to hematology centers across Central and Eastern Europe, establishing a trade corridor that anchors regional protocol standardization. The United States and Switzerland supply monoclonal antibody biologics to oncology hospitals in Canada and Mexico. Japan and South Korea import diagnostic sequencing platforms from the United States to narrow biomarker-to-treatment timelines.
United States
Oncology hospitals in Boston and Houston drive adoption of fixed-duration BTK-BCL-2 combination protocols. FDA breakthrough therapy designations compress development timelines for novel inhibitors entering frontline settings. The Mayo Clinic in Rochester anchors MRD-guided treatment cessation trials that diffuse to community hematology practices nationwide.
Germany
University hospitals in Munich and Heidelberg standardize BTK inhibitor-based regimens across European academic medical centers. EMA PRIME eligibility accelerates market entry for next-generation agents with enhanced selectivity profiles. The German sickness fund system favors outpatient oral therapy management to reduce hospitalization expenditure in elderly CLL populations.
Switzerland
F. Hoffmann-La Roche AG anchors monoclonal antibody production for combination protocols exported to France and Italy. Swissmedic maintains stringent cGMP oversight of biologic manufacturing facilities in Basel. The Lake Geneva biotech cluster concentrates contract development organizations supporting EU MDR-compliant diagnostic assay commercialization.
Japan
PMDA accelerated approval pathways enable faster patient access to BCL-2 inhibitors in relapsed and refractory segments. Hematology centers in Tokyo and Osaka integrate next-generation sequencing into diagnostic workflows to guide precision therapy selection. METI funding programs support domestic manufacturing capacity for oral small-molecule targeted therapies.
India
CDSCO regulatory pathways and WHO prequalification programs create access expansion potential for oral targeted therapies in lower-income patient segments. Oncology hospitals in Mumbai and Delhi pilot fixed-duration protocols adapted to resource-constrained settings. The country's national pharmaceutical regulator streamlines abbreviated approval routes for essential CLL medicines.
Global Chronic Lymphocytic Leukemia Treatment Market Key Industry Players
Channel-controlling players compete with product-specialist players across oral small-molecule and biologic monoclonal antibody segments. The market structure concentrates around large-cap pharmaceutical entities with integrated hematology franchises and mid-cap biotech specialists with single-mechanism depth. Three archetypes dominate: diversified oncology portfolio holders, precision-targeted therapy developers, and immunotherapy backbone suppliers. M&A activity targets BTK and BCL-2 inhibitor pipelines, while strategic partnerships secure companion diagnostic co-development rights.
Within the diversified oncology tier, AstraZeneca plc and Johnson & Johnson occupy positions spanning small-molecule inhibitors and biologic combinations. AbbVie Inc. exemplifies the precision-targeted archetype through its BCL-2 inhibitor concentration. These three entities anchor competitive dynamics as hematology centers in the United States and Germany rewrite protocol standards around fixed-duration oral regimens.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Johnson & Johnson |
| AbbVie Inc. |
| Amgen Inc. |
| Pfizer Inc. |
| F. Hoffmann-La Roche AG |
| Gilead Sciences Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Chinese active pharmaceutical ingredient manufacturers for BTK inhibitor intermediates compresses margin buffers while amplifying price volatility across branded and generic tiers. This concentration forces oncology hospitals and specialty pharmacies to absorb tariff pass-throughs or seek alternative sourcing, restructuring procurement relationships around dual-qualified suppliers.
Pricing Analysis
First-generation BTK inhibitors now trade at steep discounts to next-generation covalent and non-covalent agents with improved selectivity profiles. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, EMA PRIME eligibility, and biomarker-specific labeling. Cost compression in the chemotherapy-backbone segment intensifies as fixed-duration oral protocols displace infusion regimens. Community oncology practices exhibit highest price sensitivity; academic medical centers with formulary control demonstrate lowest sensitivity due to trial access and protocol leadership.
Supply Chain Analysis
Tariff exposure between China and the United States dominates API procurement risk for small-molecule BTK and BCL-2 inhibitors. Manufacturing concentration in China, India, and Switzerland feeds formulation and packaging operations in Germany and the United States. Cold chain integrity for monoclonal antibodies hinges on single-use bioreactor supply from German and Japanese vendors. Distribution runs through United States specialty pharmacy networks and German sickness fund-contracted ambulatory care centers with integrated dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosimilar rituximab and emerging CAR-T salvage regimens threaten incumbent monoclonal antibody franchises, demanding active substitution defense through fixed-duration combination lock-in.
For Market Incumbents: Build regulatory data exclusivity moats around MRD-negative endpoint submissions to EMA and FDA. Anchor formulary position through hematology center partnership programs in Munich and Houston that standardize protocol adoption ahead of competitor entry. Secure backward integration into diagnostic assay co-development to control biomarker-to-treatment workflow. For New Entrants and Emerging Players: Build out fixed-duration BTK-BCL-2 combination capabilities targeting the relapsed/refractory segment where resistance mechanisms create therapy-switching demand. India's CDSCO abbreviated approval pathway offers the most penetrable regulatory entry for oral targeted therapies. Deploy hospital pharmacy direct contracting to bypass established wholesale distribution. For Investors and Strategic Acquirers: FDA guidance evolution on minimal residual disease endpoints reshapes the acquisition landscape toward data packages with registrational-ready MRD readouts. Five-to-ten year viability favors precision-targeted developers with single-mechanism depth over diversified oncology portfolios facing patent cliff exposure. Watch EMA PRIME eligibility announcements as inflection indicators for competitive entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough designation compresses trial-to-treatment timelines for novel BTK inhibitors. |
| Manufacturing Scale-Up | cGMP facility investment in Switzerland and Germany secures EMA MDR-compliant biologic supply. |
| Pipeline Diversification | Next-generation sequencing companion diagnostics narrow biomarker-to-therapy selection gaps. |
| Licensing Agreement | CDSCO and WHO prequalification partnerships unlock access expansion in Indian oncology hospitals. |
| Clinical Trial Advancement | MRD-guided treatment cessation trials at Mayo Clinic and Heidelberg diffuse protocol standards nationwide. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Calibration against historical approval-to-peak-sales curves and therapy-class substitution patterns shaped projections across the analysis window. Segmentation dimensions included treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs derived from therapy-class analogs and epidemiological incidence projections. Forecast inputs incorporated biomarker testing penetration rates and fixed-duration protocol adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biosimilar entrants or CAR-T developers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market