
 Primary Sclerosing Cholangitis Treatment Market | 2026-2036
Primary Sclerosing Cholangitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Sclerosing Cholangitis Treatment Market Outlook
Hospital-based hepatology and transplant center demand is shifting toward biologic-intensive protocols as surgical deferral strategies gain preference. Dr. Falk Pharma anchors European clinical development through its established gastroenterology franchise. Gilead Sciences leverages its antiviral and immunology manufacturing scale to compete in inflammation-modulating pipelines. Intercept Pharmaceuticals specializes in bile acid receptor targeting, a mechanism distinct from competitors.
Primary sclerosing cholangitis treatment encompasses pharmacologic and interventional modalities directed at halting bile duct fibrosis, managing cholestatic complications, and delaying liver transplant necessity; formulations range from small-molecule bile acid derivatives to monoclonal antibodies requiring cold-chain distribution at two to eight degrees Celsius. Biologics command expanding prescriber attention as proof-of-concept data accumulates for fibro-inflammatory pathway blockade, while oral medications retain volume leadership due to payer familiarity and generic availability. Injectable delivery modes capture growing share in outpatient clinic settings where infusion supervision aligns with biologic administration requirements.
The FDA orphan drug program and EMA's Committee for Orphan Medicinal Products shape trial design incentives and post-approval market exclusivity timelines for developers. REACH compliance and ISO 13485 certification govern biologic manufacturing materials and quality management systems, respectively, constraining supplier qualification and batch release protocols. Stakeholders must monitor regulatory guidance evolution on surrogate endpoint acceptability, as biomarker-based approval pathways could reshape competitive timelines without warning.
Market Dynamics
Biologic-intensive treatment protocols are displacing surgical-first approaches in hepatology departments, as transplant deferral strategies gain clinical traction and cold-chain infrastructure expands into outpatient infusion centers.
Growth Catalysts
- FDA Orphan Drug Incentives:The FDA's orphan drug designation pathway accelerates clinical trial tax credits and market exclusivity timelines, drawing developers toward rare cholestatic indications previously deemed commercially unviable.
- Transplant Center Concentration:Specialist referral networks clustering around major US transplant hubs create concentrated demand pools that justify biologic manufacturing scale investments.
- Bile Acid Receptor Science:Advances in farnesoid X receptor pharmacology are unlocking mechanism-based endpoints that satisfy regulatory biomarker requirements for accelerated approval.
Market Restraints
- Biologic Cold-Chain Costs:Monoclonal antibodies requiring two-to-eight-degrees-Celsius distribution impose infrastructure burdens that exclude smaller hepatology practices from protocol adoption.
- Surrogate Endpoint Uncertainty:Regulatory guidance evolution on biomarker-based approval pathways creates unpredictable exclusivity timelines that compress developer return calculations.
- Generic Ursodeoxycholic Acid Availability:Low-cost oral bile acid derivatives anchor payer formularies, creating reimbursement friction for novel mechanism therapies.
Strategic Opportunities
- Pediatric PSC Indications:Underpenetrated adolescent and young-adult patient segments offer label expansion pathways with extended exclusivity protections.
- EMA Orphan Medicinal Products Committee Alignment:Coordinated FDA-EMA trial designs enable simultaneous US-European submissions that compress regulatory lag.
- Home Infusion Channel Development:Partnerships with specialty pharmacy distributors are creating ambulatory administration models that reduce transplant center capacity constraints.
Industry Challenges
- Hepatology Biomarker Standardization:Discordance between alkaline phosphatase response and histologic fibrosis progression complicates Phase III endpoint selection and regulatory negotiation.
- ISO 13485 Certification Timelines:Biologic manufacturing quality management system audits impose eighteen-to-twenty-four-month supplier qualification delays that constrain batch release flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Sclerosing Cholangitis Treatment Market |
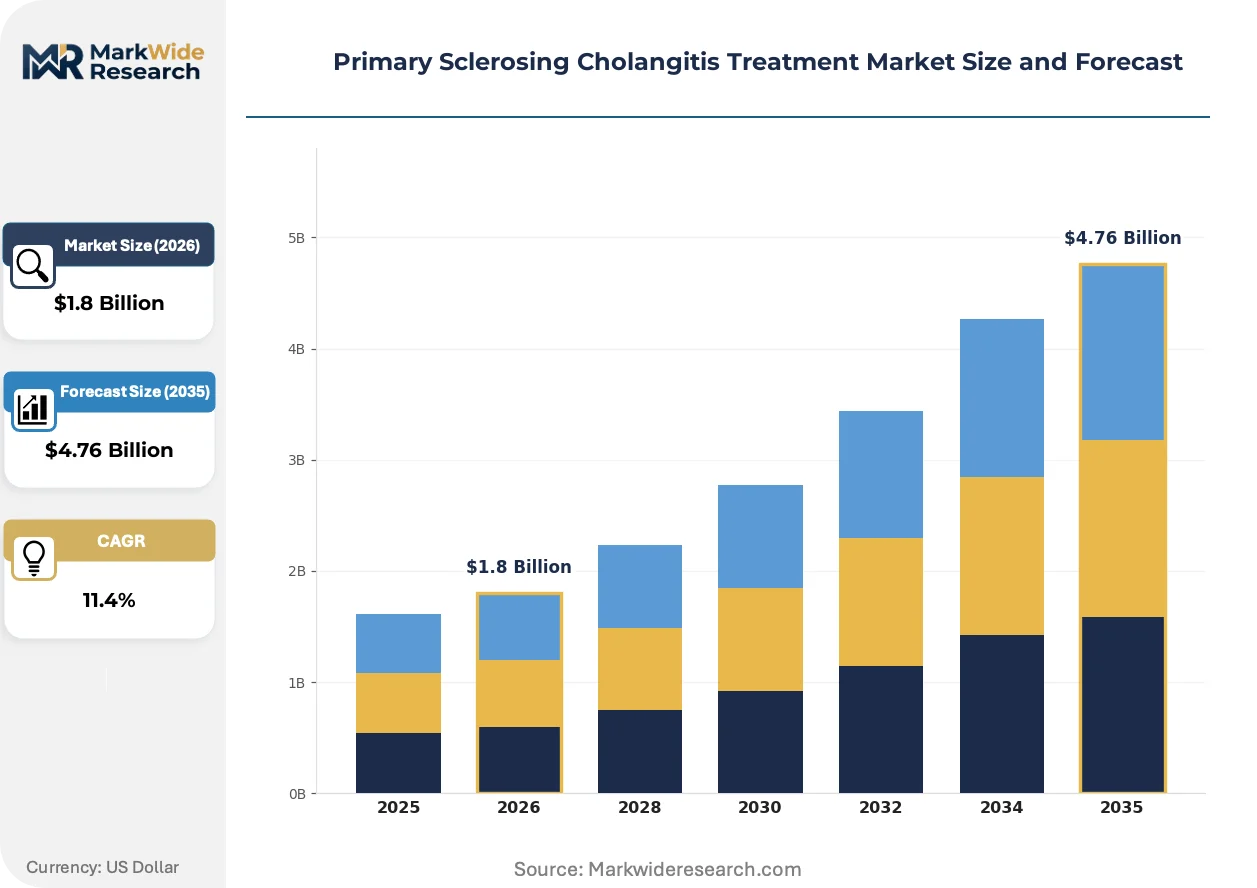
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Biologics, Surgical Procedures, Lifestyle Interventions Therapy Area: Liver Disorders, Autoimmune Conditions, Gastroenterology, Chronic Inflammation Delivery Mode: Oral, Injectable, Intravenous, Infusion End User: Hospitals, Outpatient Clinics, Research Laboratories, Homecare Settings |
| Companies Covered | Dr. Falk Pharma, CymaBay Therapeutics, Gilead Sciences, NGM Biopharmaceuticals, Chemomab Therapeutics, HighTide Biopharma, Pliant Therapeutics, Intercept Pharmaceuticals, Mirum Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Sclerosing Cholangitis Treatment Market Strategic Shifts
Mechanism-based drug development is supplanting empirical bile acid replacement, as fibro-inflammatory pathway science matures and regulatory frameworks adapt to surrogate biomarker endpoints.
Fibroblast growth factor 19 analogs are electrifying cholestatic disease management by targeting ileal bile acid signaling with subcutaneous delivery profiles. Academic medical centers in the United States and Germany are prioritizing these agents in comparative-effectiveness protocols against standard-of-care ursodeoxycholic acid. The technology is electrifying prescriber expectations around non-invasive fibrosis regression, compressing timelines for surgical referral decisions.
EMA's Committee for Orphan Medicinal Products has harmonized pediatric investigation plan requirements with FDA rare disease guidance, enabling synchronized transatlantic development strategies. This convergence reduces duplicate clinical trial costs and accelerates patient access timelines across European transplant networks. Biologic developers targeting PSC are responding by embedding EU sites in Phase IIb studies earlier than historical orphan disease norms.
Specialist procurement committees at US academic medical centers are consolidating biologic purchasing through limited distribution networks that bundle infusion services with drug acquisition. Specialty pharmacy intermediaries are displacing traditional wholesale relationships in hepatology clinics, capturing margin through cold-chain logistics and patient adherence monitoring. This channel consolidation is most visible in California, Texas, and Florida, where transplant center density supports hub-and-spoke infusion models.
Primary Sclerosing Cholangitis Treatment Market Segmentation
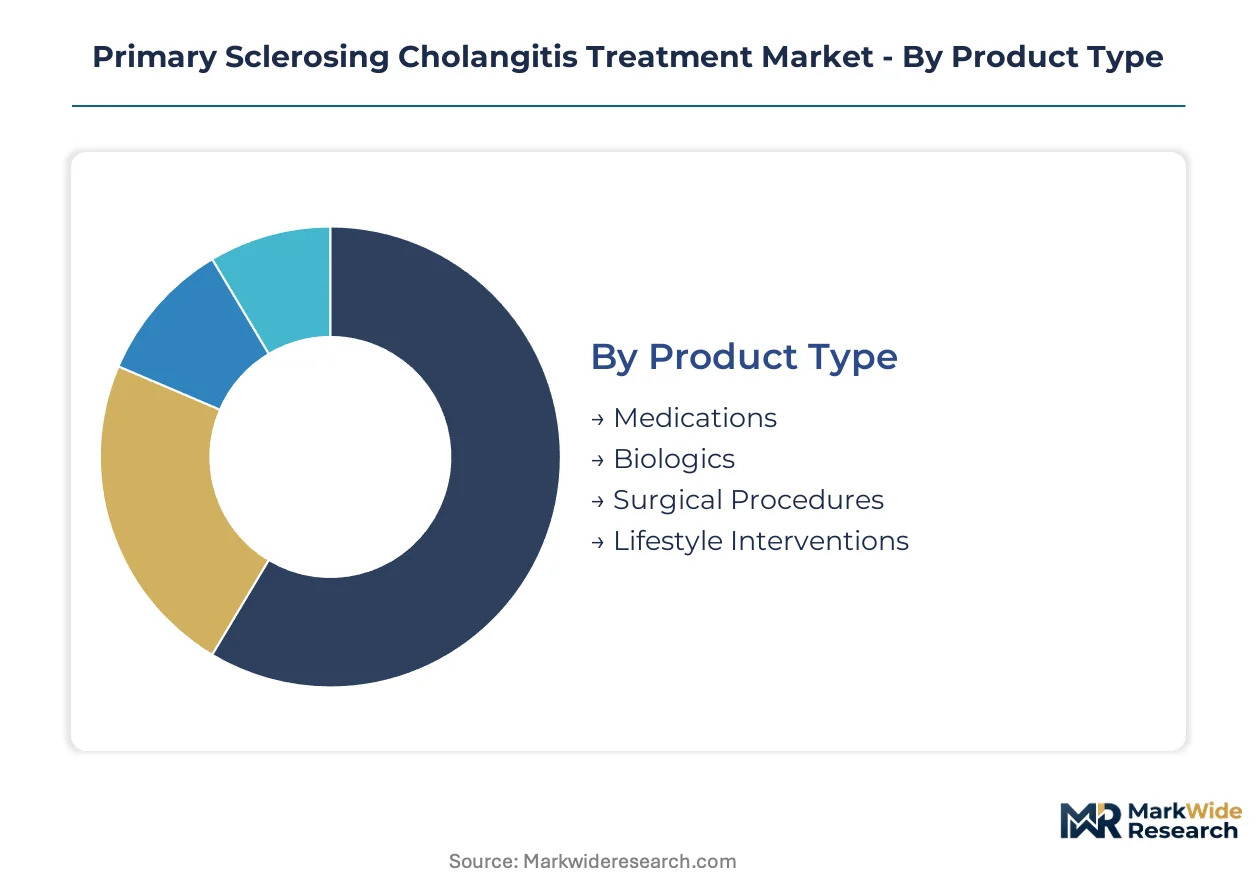
PSC treatment segmentation reveals competing pathways between established oral therapies and emerging biologic modalities. Understanding how volume, delivery complexity, and site-of-care requirements divide across segments illuminates where infrastructure investments and regulatory strategies must concentrate.
Product Type:
Volume leadership sits with oral small molecules while premium capture concentrates in cold-chain biologics requiring infusion supervision.
- Medications:Ursodeoxycholic acid derivatives and obeticholic acid formulations dominate prescription volumes through payer familiarity and generic availability. Community hepatology practices in the United States rely on these agents as first-line therapy, though alkaline phosphatase response rates limit long-term efficacy expectations.
- Biologics:Monoclonal antibodies targeting fibro-inflammatory pathways require two-to-eight-degrees-Celsius distribution and outpatient infusion capacity. Major US transplant centers cluster adoption of these agents where surgical deferral protocols justify cold-chain infrastructure investment.
- Surgical Procedures:Biliary drainage interventions and transplant evaluation represent procedural endpoints when pharmacologic control fails.
- Lifestyle Interventions:Nutritional optimization and physical therapy protocols serve as adjunctive support without standalone disease-modifying claims.
Today's leader: Medications. Tomorrow's challenger: Biologics.
Therapy Area:
Application focus determines whether development programs target hepatology specialists or broader gastroenterology referral networks.
- Liver Disorders:Pure cholestatic indications command transplant center concentration and orphan drug designation pathways. FDA incentives accelerate timelines for agents demonstrating fibrosis regression biomarkers.
- Autoimmune Conditions:Overlap syndromes with inflammatory bowel disease expand addressable populations beyond isolated PSC diagnoses. Academic medical centers in Germany prioritize these patients in comparative-effectiveness protocols.
- Gastroenterology:General GI practices manage early-stage disease identification and referral coordination without advanced therapeutic intervention.
- Chronic Inflammation:Broad immunomodulatory mechanisms attract platform technologies from inflammation-focused developers seeking indication expansion.
Transplant center density favors Liver Disorders. Autoimmune Conditions offer the broadest label expansion runway.
Delivery Mode:
Route of administration dictates site-of-care requirements and whether patient acquisition flows through retail pharmacy or specialty infusion networks.
- Oral:Bile acid derivatives and receptor agonists permit home administration with periodic laboratory monitoring. Payer formularies favor this route for step-therapy protocols prior to biologic authorization.
- Injectable:Subcutaneous FGF19 analogs enable self-administration with reduced cold-chain burden compared to intravenous alternatives. Outpatient clinics in Texas and Florida pilot home-injection training programs.
- Intravenous:Hospital-based administration reserves capacity for acute cholangitis episodes and perioperative management.
- Infusion:Monoclonal antibody protocols require supervised administration in centers with emergency response capability and immunology nursing expertise.
Oral agents sustain volume leadership. Injectable biologics are climbing the fastest as home administration models mature.
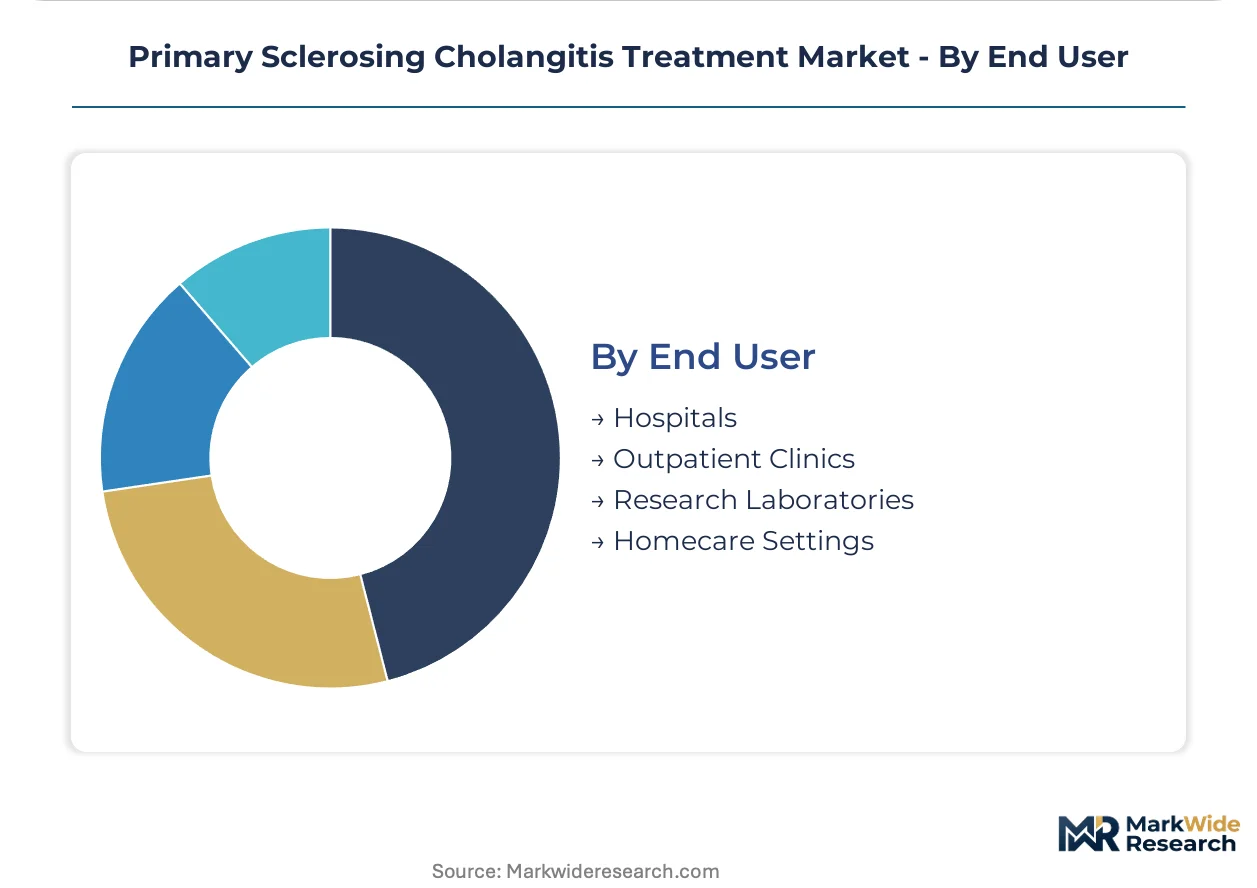
End User:
Customer type segmentation maps to disease severity gradients and whether care delivery requires transplant surgical capability or longitudinal medical management.
- Hospitals:Tertiary academic centers concentrate advanced fibrosis cases, transplant evaluation, and biologic infusion capacity. REACH compliance and ISO 13485 certification govern supplier qualification for these institutional purchasers.
- Outpatient Clinics:Community hepatology practices manage stable disease with oral therapies and routine surveillance imaging. Limited distribution networks increasingly bundle drug acquisition with infusion services for clinic-based biologic administration.
- Research Laboratories:Academic sites conduct biomarker validation and surrogate endpoint development for regulatory submission packages.
- Homecare Settings:Specialty pharmacy intermediaries enable ambulatory administration models that reduce transplant center capacity constraints through hub-and-spoke logistics.
Hospitals anchor premium biologic uptake. Homecare Settings represent the steepest expansion trajectory as cold-chain infrastructure decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting clinical trial investment toward jurisdictions with streamlined orphan drug pathways and concentrated transplant infrastructure. Developers migrate Phase IIb operations to markets where FDA-EMA alignment compresses approval timelines and site activation costs diverge significantly.
United States
Specialist referral networks cluster around Mayo Clinic Rochester, Cleveland Clinic, and UCLA Medical Center, creating concentrated demand pools for biologic infusion protocols. FDA orphan drug tax credits and seven-year market exclusivity accelerate developer incentives for rare cholestatic indications. Texas and Florida transplant hubs pilot home-injection training programs for subcutaneous FGF19 analogs.
Germany
Academic medical centers in Heidelberg and Berlin prioritize comparative-effectiveness protocols against standard-of-care ursodeoxycholic acid. EMA Committee for Orphan Medicinal Products harmonizes pediatric investigation plans with FDA guidance, enabling synchronized transatlantic submissions. Dr. Falk Pharma anchors European clinical development through its established gastroenterology franchise in Freiburg.
United Kingdom
NHS England's specialized commissioning framework concentrates biologic access through designated liver center networks in London, Birmingham, and Leeds. MHRA post-Brexit recognition agreements with FDA and EMA preserve streamlined regulatory pathways for multinational trial designs. Cambridge and Oxford academic sites drive biomarker validation for surrogate endpoint development.
Switzerland
Swissmedic's rapid scientific advice procedures attract developers seeking early regulatory feedback on fibrosis regression biomarkers. Basel and Zurich host contract research organizations specializing in orphan disease trial execution. The country's central European location supports cold-chain distribution hub operations serving German, French, and Italian transplant networks.
Japan
PMDA's sakigake designation system provides priority review for PSC therapies demonstrating novel mechanisms. Tokyo and Osaka academic medical centers participate in multinational Phase III protocols through Asian liver disease consortiums. Domestic developers leverage platform immunology technologies toward inflammation-modulating pipelines for cholestatic indications.
Primary Sclerosing Cholangitis Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with biologic developers retaining formulation control while outsourcing fill-finish operations to ISO 13485-certified facilities. Market structure concentrates around three to five developers with active Phase IIb or Phase III assets, creating tiered competition between mechanism-based innovators and reformulation specialists. Strategic archetypes include bile acid receptor specialists, fibro-inflammatory pathway blockade developers, and transplant deferral protocol integrators. Dominant competitive moves encompass strategic partnerships with specialty pharmacy distributors and geographic expansion through coordinated FDA-EMA trial designs.
Within the mechanism-based innovation tier, Intercept Pharmaceuticals exemplifies bile acid receptor targeting specialization distinct from immunology-focused competitors. Gilead Sciences occupies a position leveraging antiviral and immunology manufacturing scale toward inflammation-modulating pipelines. Dr. Falk Pharma anchors European market presence through its established gastroenterology franchise and regional clinical development infrastructure.
| Leading Market Players |
|---|
| Dr. Falk Pharma |
| CymaBay Therapeutics |
| Gilead Sciences |
| NGM Biopharmaceuticals |
| Chemomab Therapeutics |
| HighTide Biopharma |
| Pliant Therapeutics |
| Intercept Pharmaceuticals |
| Mirum Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Biologic cold-chain infrastructure expansion into outpatient infusion centers simultaneously elevates distribution costs and consolidates purchasing leverage among transplant center networks in the United States, Germany, and Switzerland. This dual shift compresses margins for oral generic alternatives while amplifying price capture for monoclonal antibodies requiring two-to-eight-degrees-Celsius handling.
Pricing Analysis
Specialty pharmacy distributor margins bundle drug acquisition with infusion supervision services, creating a three-tier pricing structure across premium biologics, standard oral formulations, and economy generic ursodeoxycholic acid. Price differentiation rests on certification tier (FDA orphan drug exclusivity versus EMA Committee for Orphan Medicinal Products alignment) and cold-chain infrastructure investment. Cost compression in oral generics intensifies because of Indian and Chinese API oversupply, while transplant centers exhibit lowest price sensitivity due to surgical deferral protocol value.
Supply Chain Analysis
Single-source vulnerability sits with ISO 13485-certified fill-finish contractors concentrated in Switzerland, Germany, and the United States. Raw material dependencies include recombinant cell lines, pharmaceutical-grade excipients, and temperature-controlled packaging materials. Supply chain risk centers on eighteen-to-twenty-four-month supplier qualification delays that constrain batch release flexibility. Distribution runs through limited specialty pharmacy networks bundling cold-chain logistics with patient adherence monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Primary sclerosing cholangitis treatment functions as a regulatory compounder where FDA orphan drug tax credits and seven-year market exclusivity timelines accelerate developer returns beyond standard hepatology indications.
For Market Incumbents: Anticipate biosimilar pressure from inflammation-focused platform technologies by deepening captive supply of recombinant manufacturing capacity in Basel and Zurich corridor facilities. Anchor formulary position through backward integration into specialty pharmacy distribution partnerships that bundle infusion services with drug acquisition, neutralizing emerging entrant channel access. For New Entrants and Emerging Players: Launch via home-injection training programs for subcutaneous FGF19 analogs targeting Texas and Florida transplant hub spillover markets. Pediatric PSC indications offer the most penetrable segment with extended exclusivity protections and harmonized FDA-EMA pediatric investigation plan requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mechanism-based innovators with Phase IIb fibro-inflammatory pathway assets awaiting surrogate endpoint validation. Long-term viability across the analysis window hinges on biomarker-based approval pathway convergence between FDA and EMA regulators. Watch alkaline phosphatase response discordance with histologic fibrosis progression as the critical inflection signal for regulatory negotiation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA tax credits and exclusivity accelerate PSC asset development timelines. |
| Coordinated FDA-EMA Trial Design | Synchronized submissions compress regulatory lag across transatlantic transplant networks. |
| Specialty Pharmacy Partnership | Limited distribution networks bundle cold-chain logistics with patient adherence monitoring. |
| Pediatric Investigation Plan Alignment | EMA harmonization with FDA guidance extends exclusivity into adolescent segments. |
| Biomarker Validation Investment | Academic medical center partnerships secure surrogate endpoint acceptability for accelerated approval. |
Study Parameters
Multiple input streams — regulatory filing databases, clinical trial registries, and hospital procurement records — were reconciled against primary interviews with drug development executives, formulary directors, hepatology department heads, and specialty pharmacy distribution managers. Secondary validation drew from FDA orphan drug designations, EMA Committee for Orphan Medicinal Products opinions, ClinicalTrials.gov protocols, and CMS Medicare reimbursement data. Bottom-up prescription volume modeling and top-down market sizing triangulated segment-level estimates.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeled by product type (oral small molecule, biologic, surgical procedure), therapy area (liver disorders, autoimmune conditions), delivery mode (oral, injectable, infusion), and end user (hospital, outpatient clinic, homecare setting). CAGRs were derived from trend extrapolation of orphan drug approval timelines and transplant center capacity expansion. Forecast inputs included cold-chain infrastructure investment trajectories and surrogate endpoint regulatory guidance evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under biomarker endpoint rejection or generic ursodeoxycholic acid formulary lock-in scenarios. Forecasts reflect documented assumptions regarding FDA-EMA regulatory convergence and transplant surgical capacity constraints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Dupuytrens Disease Market