
 Musculoskeletal System Disorders Market | 2026-2036
Musculoskeletal System Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Musculoskeletal System Disorders Market Outlook
Project finance and equipment leasing for surgical robotics and advanced imaging is tilting competitive dynamics toward health systems with stronger capital access. Stryker Corporation leverages its integrated robotics and implant portfolio to anchor high-volume orthopedic service lines. Zimmer Biomet Holdings, Inc. sustains market presence through specialized knee and hip reconstruction platforms. Johnson & Johnson competes across the surgical continuum with its diversified MedTech and pharmaceutical assets.
Musculoskeletal system disorders encompass pathologies affecting bones, joints, muscles, ligaments, and tendons, typically diagnosed through radiographic imaging, arthroscopy, or biomarker assessment and treated via pharmacologic intervention, surgical reconstruction, or physical rehabilitation to restore mobility and reduce pain. Orthopedic devices represent the mature revenue core where implant manufacturers capture recurring procedure volumes, while pain management therapies command expanding share as multimodal analgesia protocols replace opioid-centric approaches. Rehabilitation equipment shows accelerating growth as post-acute care shifts toward outpatient and home-based settings.
FDA premarket notification and PMA pathways govern orthopedic device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for implantable products. CMS bundled payment models and the FDA's breakthrough device designation program shape investment priorities by rewarding outcomes documentation and accelerated regulatory pathways. Stakeholders must monitor how reimbursement compression interacts with capital-intensive technology adoption to determine sustainable competitive positioning.
Market Dynamics
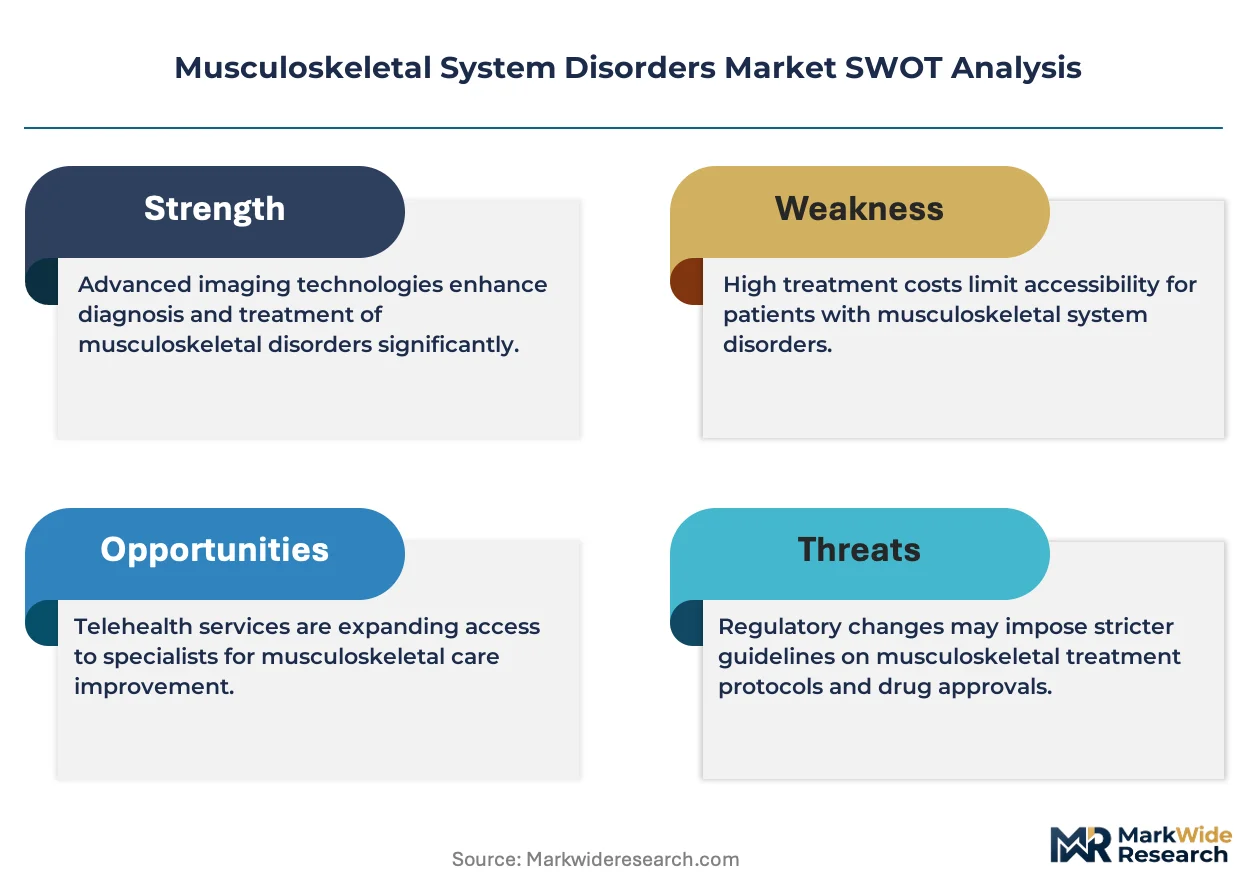
The migration toward value-based reimbursement from CMS is compressing fee-for-service margins and forcing orthopedic service lines to consolidate procedural volume around capital-intensive robotics platforms.
Growth Catalysts
- CMS bundled payment mandates:Hospital systems in the United States are consolidating orthopedic procedures into integrated service lines to capture episode-based reimbursement incentives.
- Sports medicine volume expansion:Rising participation in competitive athletics and recreational fitness across aging demographics is driving arthroscopic procedure demand.
- Polyethylene cross-linking advances:Bearing surface innovations are extending implant longevity and expanding candidacy to younger patient populations.
Market Restraints
- Titanium alloy supply concentration:Aerospace and medical-grade titanium sourcing clusters in limited foundry capacity, exposing implant manufacturers to input volatility.
- FDA PMA pathway duration:Premarket approval timelines for novel implantable devices extend commercialization cycles and compress return on R&D investment.
- Outpatient surgical substitution:Ambulatory surgery centers are capturing lower-acuity orthopedic volume from traditional hospital inpatient settings.
Strategic Opportunities
- Home-based rehabilitation expansion:Remote patient monitoring platforms and wearable motion sensors are enabling post-acute care outside institutional settings.
- EU MDR regulatory tailwinds:Stricter clinical evidence requirements for implantable products favor established manufacturers with robust trial infrastructure over smaller competitors.
- Biologics-adjacent procedures:Platelet-rich plasma and bone marrow concentrate applications are creating ancillary revenue streams alongside traditional hardware implantation.
Industry Challenges
- Robotics technician scarcity:Health systems face recruitment bottlenecks for specialized surgical technologists trained on integrated navigation platforms.
- Legacy EHR integration friction:Orthopedic-specific workflows for preoperative planning and implant tracking resist seamless incorporation into enterprise electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Musculoskeletal System Disorders Market |
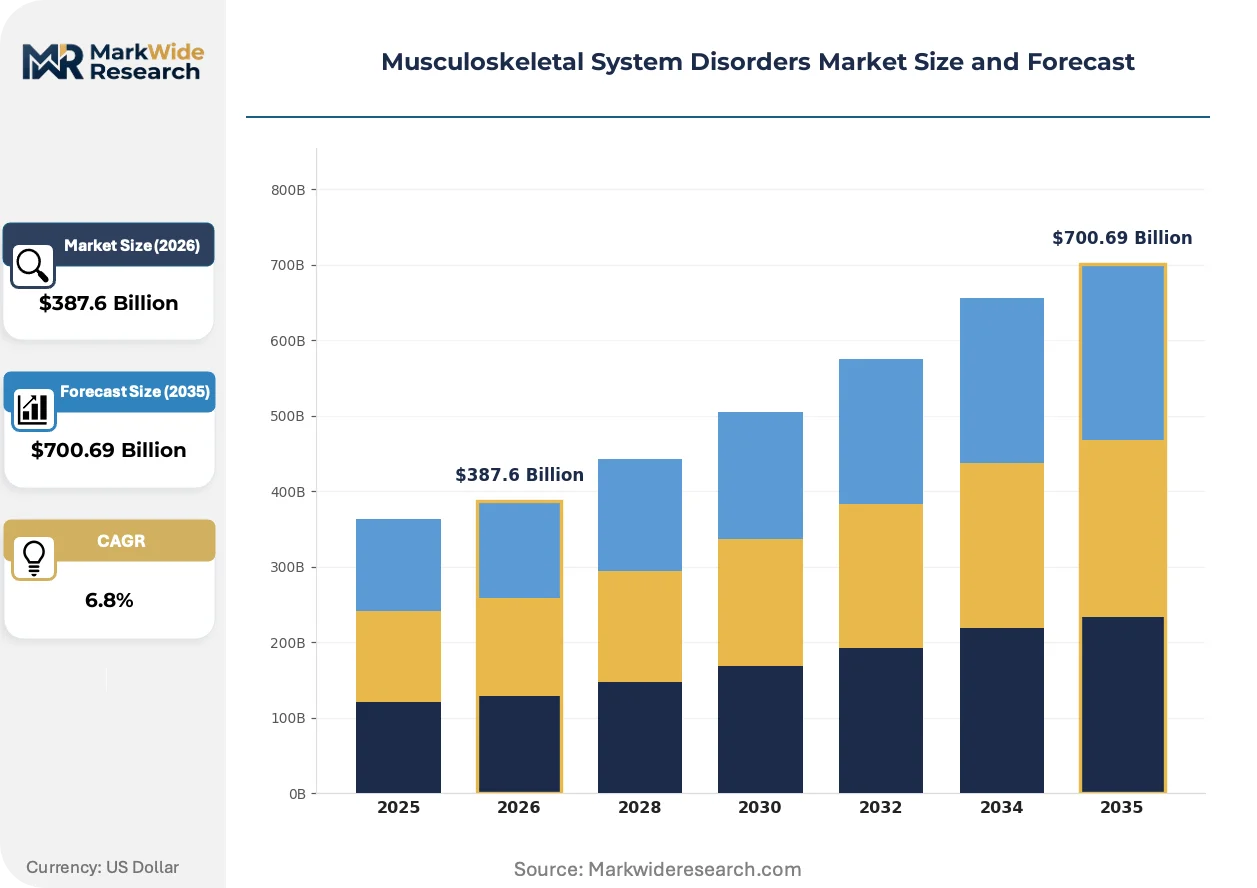
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Devices, Pain Management Therapies, Rehabilitation Equipment, Imaging Systems Therapy Area: Arthritis, Osteoporosis, Back Pain, Sports Injuries End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Delivery Mode: Intravenous, Oral, Topical, Intra-articular |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., Johnson & Johnson, Amgen Inc., Pfizer Inc., Medtronic, AbbVie Inc., Arthrex, Inc., Globus Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Musculoskeletal System Disorders Market Strategic Shifts
Orthopedic care delivery is fragmenting across settings as technology enables procedure migration and reimbursement models reward site-of-care optimization.
Patient-specific instrumentation is migrating from experimental niches to standard-of-care protocols for total joint arthroplasty. Academic medical centers and high-volume community hospitals are adopting 3D-printed surgical guides and preoperative planning software at accelerating rates. This technology is migrating from premium-priced positioning toward commoditized inclusion in implant system contracts, compressing standalone software revenue models.
The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evidence requirements for implantable orthopedic products. Manufacturers must maintain systematic literature reviews and periodic safety update reports across their device portfolios. Knee and hip reconstruction platforms face the most intensive scrutiny, prompting firms to consolidate regulatory affairs functions in Dublin and Brussels.
Hospital supply chain directors are unbundling implant procurement from traditional distributor relationships. Integrated delivery networks are establishing direct contracting with manufacturers for high-volume joint reconstruction systems, displacing independent sales representative intermediaries. This consolidation is most visible in the southeastern United States where IDN formation has outpaced other regions.
Musculoskeletal System Disorders Market Segmentation
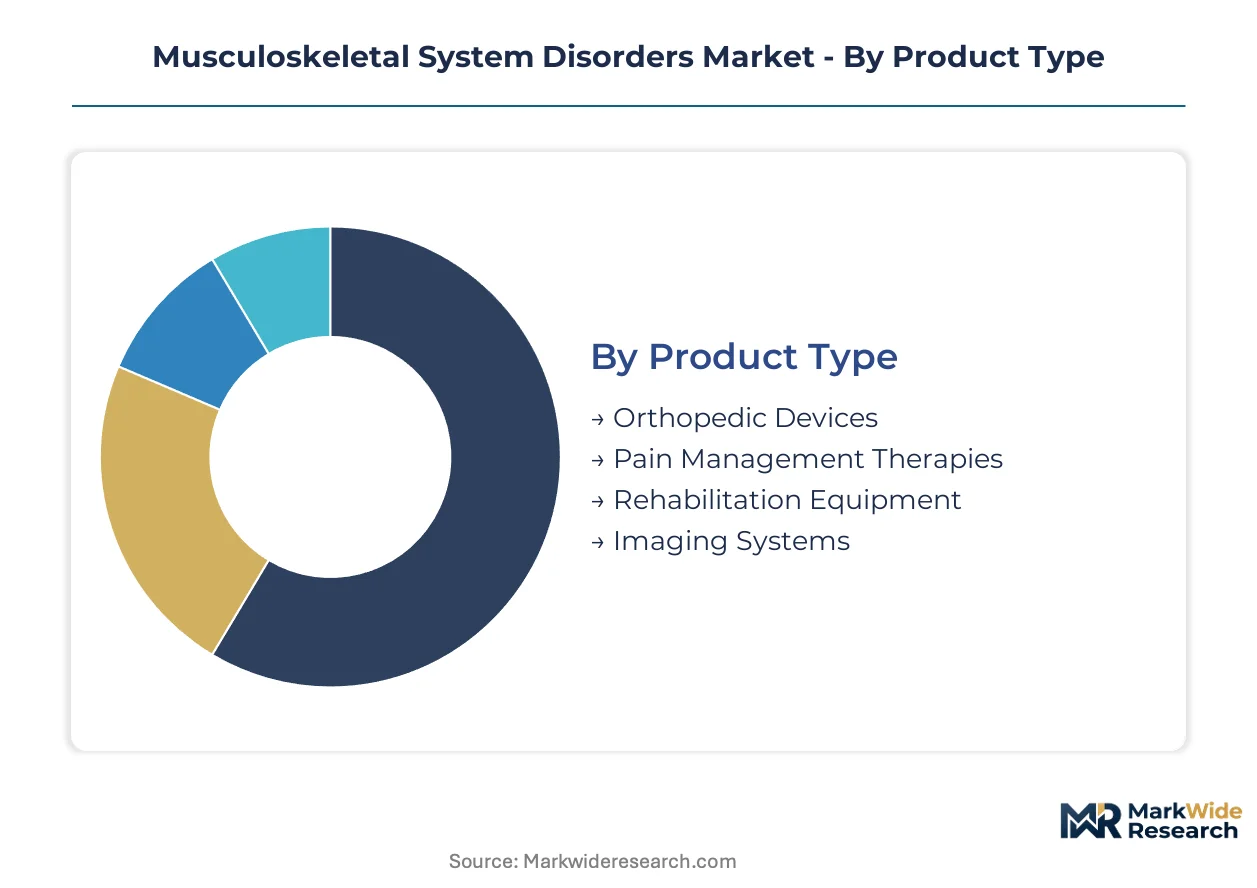
Segmentation in musculoskeletal care reflects divergent capital intensity across settings. Product type splits between durable hardware and consumable therapies, while therapy area and end user dimensions capture shifting site-of-care economics.
Product Type:
Maturity varies sharply across this dimension, with implantable hardware representing established revenue bases and digital rehabilitation tools capturing venture funding.
- Orthopedic Devices:Implant systems for joint reconstruction and spinal fusion utilize cobalt-chrome alloys and cross-linked polyethylene bearings. Demand concentrates in high-volume arthroplasty centers across the United States as CMS bundled payments reward procedure consolidation.
- Pain Management Therapies:Multimodal analgesia protocols combine NSAIDs, nerve blocks, and neuromodulation to reduce opioid dependence. Hospital formularies in Germany and Japan are expanding non-opioid coverage under national health technology assessments.
- Rehabilitation Equipment:Continuous passive motion devices and robotic exoskeletons for post-surgical recovery.
- Imaging Systems:Weight-bearing CT and portable ultrasound for point-of-care diagnosis.
Orthopedic devices handle the majority of throughput; pain management therapies are expanding most quickly on share.
Therapy Area:
Application severity drives reimbursement tiering, with acute surgical interventions commanding premium rates over chronic management protocols.
- Arthritis:Degenerative and inflammatory joint disease affecting synovial membranes and articular cartilage. Rheumatology practices in the United Kingdom and Australia are adopting treat-to-target protocols with biologic disease-modifying agents.
- Sports Injuries:Ligament ruptures, meniscal tears, and rotator cuff pathology from athletic activity. Orthopedic clinics in Brazil and South Korea report rising arthroscopic volumes among aging recreational athletes.
- Osteoporosis:Systemic bone density reduction elevating fracture risk in post-menopausal populations.
- Back Pain:Degenerative disc disease and spinal stenosis requiring surgical or conservative management.
Arthritis generates the largest addressable population; sports injuries show the steepest procedure volume climb.
End User:
Customer type determines procurement sophistication, with integrated delivery networks negotiating system-wide contracts against fragmented outpatient purchasing.
- Hospitals:Inpatient surgical suites and dedicated orthopedic institutes with robotics capital budgets. Academic medical centers in Canada and the Netherlands are consolidating service lines around navigation-assisted platforms.
- Home Care:Remote monitoring and telehealth-enabled physical therapy for post-acute recovery. Medicare Advantage plans in the United States are expanding home-based benefit carve-outs for joint replacement episodes.
- Clinics:Ambulatory settings for diagnostic workup and minor procedures.
- Rehabilitation Centers:Dedicated facilities for intensive physical and occupational therapy.
Hospitals retain the capital-intensive surgical volume; home care is gaining share fastest as reimbursement shifts site-neutral.
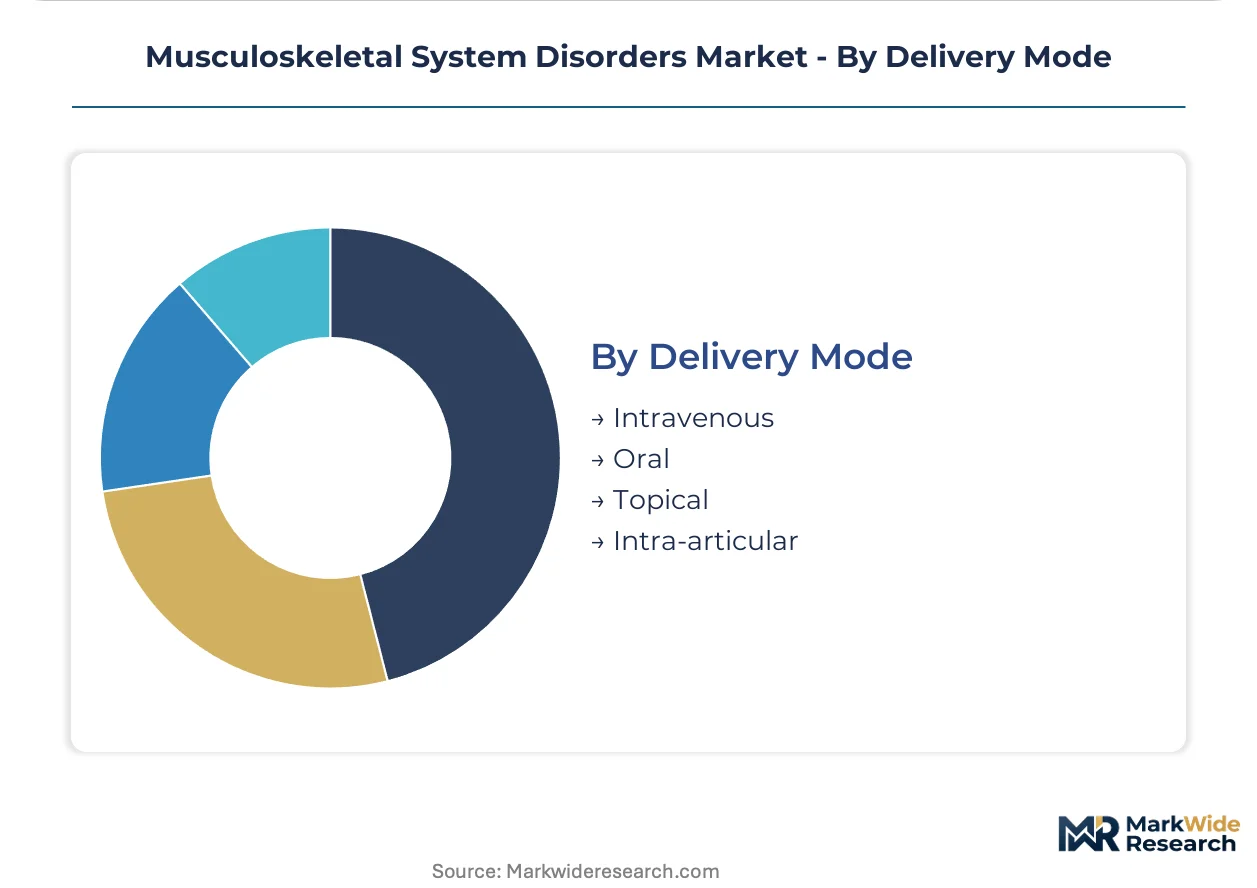
Delivery Mode:
Route of administration shapes regulatory pathway complexity and manufacturing scale economics.
- Oral:Small-molecule NSAIDs and disease-modifying agents for chronic management. Generic manufacturers in India supply bulk APIs to formulation facilities in Italy and Spain.
- Intra-articular:Corticosteroid and hyaluronic acid injections for localized joint therapy. Orthobiologic compounding in Singapore and Switzerland serves regional outpatient networks.
- Intravenous:Biologic infusions for inflammatory arthritis requiring infusion center infrastructure.
- Topical:Transdermal analgesics and anti-inflammatory patches for superficial application.
Oral formulations dominate prescription volume; intra-articular delivery is climbing fastest on procedure-linked revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement directors in the United States command the largest capital budgets for orthopedic robotics, while aging demographics in Germany and Japan drive replacement procedure volumes. Government reimbursement policies in each market determine whether manufacturers capture premium pricing for navigation-assisted platforms.
United States
Medicare Advantage plans are expanding bundled payment carve-outs for joint replacement episodes, incentivizing hospital systems to consolidate orthopedic service lines. The FDA's breakthrough device designation program accelerates commercialization timelines for novel implantable products. Academic medical centers in Boston and Rochester anchor high-volume arthroplasty networks with dedicated robotics capital budgets.
Germany
Statutory health insurance funds are expanding coverage for patient-specific instrumentation under national health technology assessments. The EU Medical Device Regulation imposes stricter clinical evidence requirements for implantable knee and hip reconstruction platforms. Industrial clusters in Bavaria and Baden-Württemberg host regulatory affairs functions serving continental European markets.
Japan
PMDA reimbursement reviews for innovative orthopedic devices are compressing time-to-market for foreign manufacturers. METI industrial policy supports domestic production of advanced biomaterials for bearing surfaces. Medical device distributors in Osaka and Tokyo are consolidating procurement relationships around high-volume joint reconstruction systems.
China
NMPA centralized procurement campaigns are driving price compression for standard orthopedic implants across provincial hospital networks. Volume-based purchasing reforms favor domestic manufacturers with scale advantages in titanium alloy processing. Yangtze River Delta medical device clusters in Suzhou and Shanghai are expanding cleanroom capacity for implantable product assembly.
Switzerland
Swissmedic post-market surveillance requirements align with EU MDR standards for implantable orthopedic devices. Private hospital networks in Zurich and Geneva are adopting robotic navigation platforms for premium-tier joint replacement procedures. Basel-area regulatory consulting firms are consolidating European clinical trial management for multinational manufacturers.
Musculoskeletal System Disorders Market Competitive Environment
Channel-controlling players compete with product-specialist players across capital-intensive robotics platforms and consumable implant systems. The market structure tilts toward consolidated procurement relationships where integrated delivery networks negotiate system-wide contracts displacing independent sales intermediaries. Three archetypes dominate: diversified MedTech conglomerates with robotics-implant integration, pure-play orthopedic device specialists with focused joint reconstruction portfolios, and biopharmaceutical firms with biologics-adjacent musculoskeletal therapies. Dominant competitive moves include direct contracting with hospital supply chain directors and regulatory affairs consolidation in Dublin and Brussels to manage EU MDR compliance.
Among diversified MedTech conglomerates, Stryker Corporation and Johnson & Johnson exemplify channel-controlling archetypes with robotics-implant integration capabilities. Zimmer Biomet Holdings, Inc. occupies a position within the orthopedic device specialist tier, representing focused joint reconstruction platform providers. These three entities anchor competitive dynamics as hospital procurement unbundles implant sourcing from traditional distributor relationships.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Johnson & Johnson |
| Amgen Inc. |
| Pfizer Inc. |
| Medtronic |
| AbbVie Inc. |
| Arthrex, Inc. |
| Globus Medical, Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese titanium alloy foundries is compressing input costs for implant manufacturers while simultaneously eroding pricing power for mid-tier suppliers serving provincial hospital networks. This utilization dynamic forces suppliers toward extended payment terms and inventory financing to maintain procurement relationships with capital-constrained health systems.
Pricing Analysis
Certification level creates the primary spread across implant price tiers, with FDA PMA-approved devices commanding premium positioning against CE-marked equivalents in European markets. Three-tier pricing structure across premium navigation-assisted platforms, standard mechanical systems, and economy cemented stems reflects both regulatory investment recovery and volume scale economics. Pricing pressure stems from NMPA centralized procurement campaigns in China that consolidate provincial purchasing power. Academic medical centers in the United States exhibit lowest price sensitivity due to bundled payment capture incentives, while ambulatory surgery centers in Brazil and India drive hardest bargain on standard implant systems.
Supply Chain Analysis
Extended payment terms from 60 to 120 days are becoming standard for distributor relationships serving integrated delivery networks in the southeastern United States. Supply concentrates in China for titanium alloy processing, Ireland for regulatory affairs consolidation, and Switzerland for precision bearing surface manufacturing. Raw material dependencies center on aerospace-grade titanium sponge, cross-linked polyethylene resin, and cobalt-chrome alloy feedstock. Single-source vulnerability runs through limited foundry capacity for medical-grade titanium. Distribution runs through direct manufacturer contracts with hospital supply chain directors, displacing independent sales representative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The musculoskeletal system disorders market functions as a regulatory-entrenchment story where FDA PMA pathways and EU MDR compliance costs create durable moats against unproven competitors. Switching costs for hospital systems locked into robotics-implant ecosystems reinforce incumbent positioning.
For Market Incumbents: Build switching-cost moats through deep integration of surgical navigation platforms with proprietary implant tracking systems. Consolidate regulatory affairs functions in Dublin and Brussels to capture EU MDR compliance efficiencies that strain smaller competitors. Expand direct contracting with integrated delivery networks to displace independent distributor intermediaries. Counter ambulatory surgery center volume capture by developing outpatient-compatible instrumentation platforms. For New Entrants and Emerging Players: Build out white-space positions in home-based rehabilitation monitoring and wearable motion analytics where capital requirements stay modest. Target Medicare Advantage plans expanding home-based benefit carve-outs for joint replacement episodes. Penetrate biologics-adjacent procedures including platelet-rich plasma and bone marrow concentrate applications. Establish go-to-market through telehealth-enabled physical therapy platforms rather than capital-intensive robotics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among orthopedic device specialists with installed robotics bases generating disposable instrument and implant pull-through. Long-term viability favors firms with demonstrated EU MDR technical documentation and systematic post-market surveillance infrastructure. Acquisition target archetype: mid-scale rehabilitation equipment manufacturers with remote patient monitoring software stacks. Monitor FDA breakthrough device designation grants as inflection signal for accelerated commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Buildout | Stricter clinical evidence requirements favor established manufacturers with Dublin-based regulatory infrastructure. |
| Direct Hospital System Contracting | Integrated delivery networks in the southeastern United States are consolidating procurement around manufacturer-direct relationships. |
| Robotics-Implant Ecosystem Integration | Stryker and Johnson & Johnson anchor competitive positioning through navigation platform and consumable hardware bundling. |
| Home-Based Rehabilitation Platform Development | Medicare Advantage expansion of post-acute carve-outs creates reimbursement tailwind for remote monitoring technologies. |
| Titanium Alloy Backward Integration | Input volatility from aerospace demand competition drives manufacturers toward captive supply arrangements with Chinese foundries. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital supply chain directors, biomedical engineers, and GPO contracts managers; and secondary validation against FDA PMA filings, EU MDR technical documentation databases, CMS bundled payment records, and hospital procurement contract registries. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Forecast inputs incorporated procedure migration patterns between inpatient and ambulatory settings, robotics platform adoption curves, and reimbursement model evolution. Segmentation dimensions spanned product type, therapy area, end user, and delivery mode with additional modeling of regulatory pathway complexity across FDA, EU MDR, PMDA, and NMPA jurisdictions. CAGRs derived from logarithmic trend fitting across historical procedure volumes and manufacturer reported segment growth.
Practitioners should monitor NMPA procurement campaign intensity, EU MDR notified body capacity constraints, and CMS site-neutral payment expansion for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market