
 Disruptive Behavior Disorders Market | 2026-2036
Disruptive Behavior Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Disruptive Behavior Disorders Market Outlook
Long-acting injectable formulations are hardening as the preferred delivery modality for stimulant and non-stimulant therapies in adolescent populations. Eli Lilly leverages its endocrinology-neuroscience crossover infrastructure to sustain manufacturing scale for extended-release platforms. Pfizer Inc. competes through geographic dominance in European hospital formularies, while Teva Pharmaceuticals Industries Ltd. anchors its position in generic oral disintegrating tablets for pediatric compliance.
Disruptive behavior disorders encompass clinically significant patterns of aggression, defiance, and rule-breaking that impair social, academic, or occupational functioning, typically assessed via structured diagnostic interviews and behavioral rating scales with symptom duration thresholds. The primary commercial purpose is to reduce lifetime burden of antisocial progression through early pharmacologic and psychosocial intervention. Medication remains the largest revenue pool, though teletherapy represents the fastest-expanding delivery mode as asynchronous platforms gain payer acceptance. Childhood disorders command the deepest clinical trial investment, while behavioral interventions in school settings attract value-based contracting pilots.
FDA pediatric exclusivity provisions and EMA's Paediatric Investigation Plans shape development timelines and label expansions for novel therapeutics, directly influencing portfolio prioritization decisions. HIPAA interoperability rules and GDPR health data provisions constrain real-world evidence collection architectures, raising compliance costs for digital therapeutic adjuncts. Stakeholders must monitor how CMS reimbursement for remote therapeutic monitoring converges with state-level telehealth parity laws to determine capital allocation between in-person clinic networks and platform-based service models.
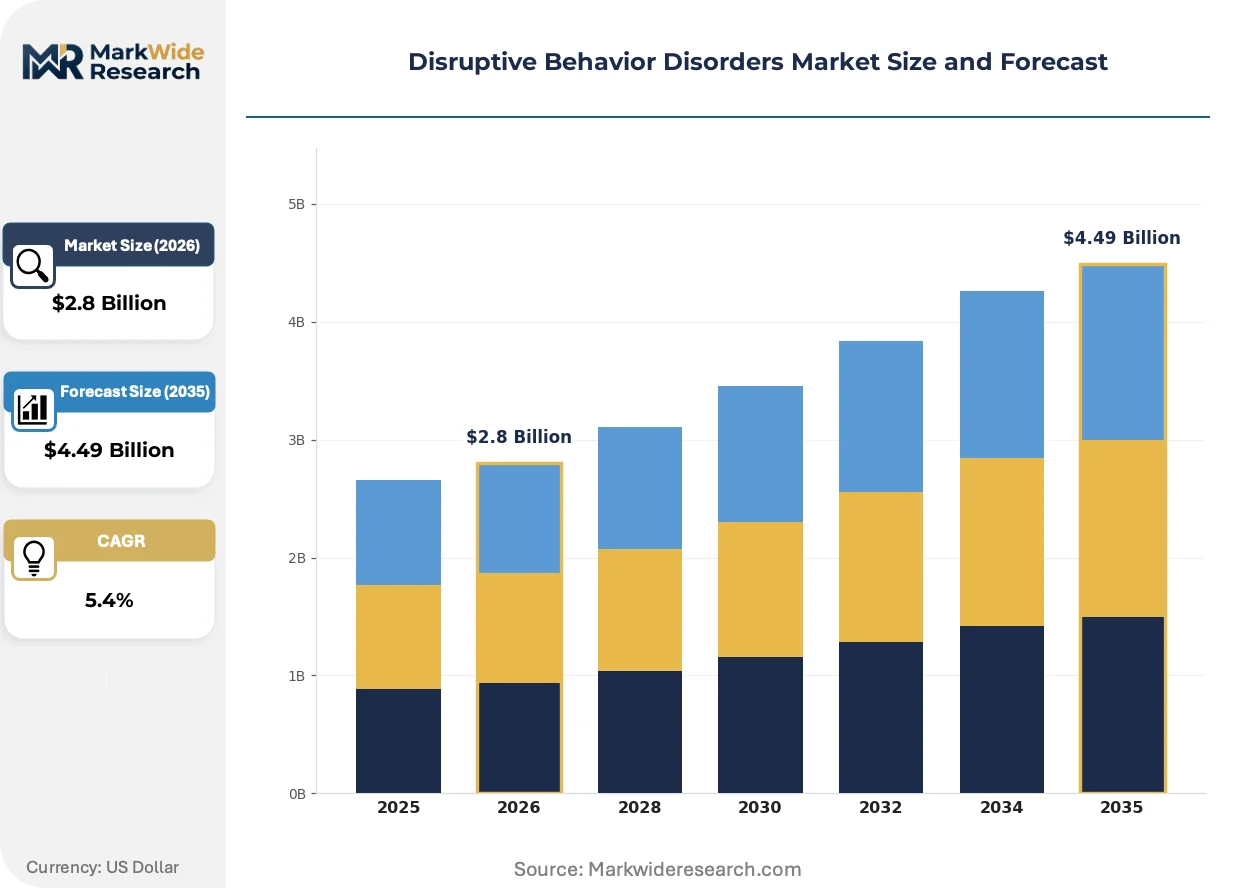
Market Dynamics
Long-acting injectable stimulant formulations are compressing treatment adherence gaps and reordering competitive priorities across pediatric and adolescent psychiatry.
Growth Catalysts
- FDA Pediatric Exclusivity:Extended market protection for approved pediatric indications incentivizes sponsors to conduct dedicated trials in conduct disorder populations.
- Germany's Statutory Health Insurance:Broadened reimbursement for behavioral parent training programs expands addressable service volume for non-pharmacologic interventions.
- Telehealth Platform Maturation:Asynchronous digital therapeutic delivery gains CMS and private payer coding acceptance, reducing geographic access barriers.
Market Restraints
- EMA Paediatric Investigation Plan Timelines:Mandatory pediatric study requirements extend development cycles by 24-36 months for novel molecular entities.
- HIPAA-GDPR Data Architecture Costs:Real-world evidence collection for digital therapeutics requires dual-compliant infrastructure, elevating platform operational overhead.
- Specialized Child Psychiatry Workforce:Concentrated supply of board-certified clinicians in urban academic centers limits service expansion velocity.
Strategic Opportunities
- School-Based Value-Based Contracts:District-level bundled payment pilots for conduct disorder interventions create new procurement channels outside traditional clinic billing.
- Remote Therapeutic Monitoring Codes:CMS reimbursement convergence with state telehealth parity laws enables capital-light platform scaling.
- Extended-Release Manufacturing Crossover:Endocrinology-neuroscience infrastructure reuse reduces capital requirements for long-acting formulation production.
Industry Challenges
- Pediatric Psychopharmacology Trial Design:FDA's tightening placebo-control and safety-monitoring standards elevate protocol complexity and site qualification costs.
- Interoperable Electronic Health Record Integration:Behavioral rating scale data capture requires custom API development across fragmented school and clinic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disruptive Behavior Disorders Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapy, Medication, Counseling, Support Groups End User: Clinics, Hospitals, Family Services, Schools Application: Childhood Disorders, Adolescent Issues, Family Therapy, Behavioral Interventions Delivery Mode: In-Person, Teletherapy, Group Sessions, Home Visits |
| Companies Covered | Novartis AG, GlaxoSmithKline plc, Eli Lilly, DURECT Corporation, Bionomics, Pfizer Inc., Teva Pharmaceuticals Industries Ltd., Chelsea Therapeutics International, Ltd., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disruptive Behavior Disorders Market Strategic Shifts
Digital measurement-based care tools and novel delivery modalities are restructuring how disruptive behavior disorders are diagnosed, treated, and reimbursed across outpatient and institutional settings.
Long-acting injectable methylphenidate and amphetamine formulations is rewriting adherence assumptions in adolescent populations. Residential treatment centers and juvenile justice facilities are adopting these platforms to reduce daily medication administration burden. The technology is compressing relapse-driven readmission cycles and shifting site-of-care economics toward lower-intensity outpatient management.
EMA's Paediatric Investigation Plans and FDA's pediatric psychopharmacology guidance documents are synchronizing juvenile toxicity study requirements across Atlantic regulatory regimes. Sponsors now face harmonized preclinical juvenile animal testing mandates that extend IND-enabling timelines. Small and mid-cap developers are responding through contract research organization partnerships and portfolio prioritization toward adult-onset indications with clearer paths to pediatric label expansion.
Asynchronous teletherapy platforms are displacing synchronous video consultation as the dominant remote delivery mode for behavioral parent training. Payers in Germany and select US Medicaid programs are establishing discrete reimbursement codes for platform-delivered modules with automated progress tracking. The shift is most visible in rural and underserved urban catchment areas where synchronous provider availability remains constrained.
Disruptive Behavior Disorders Market Segmentation
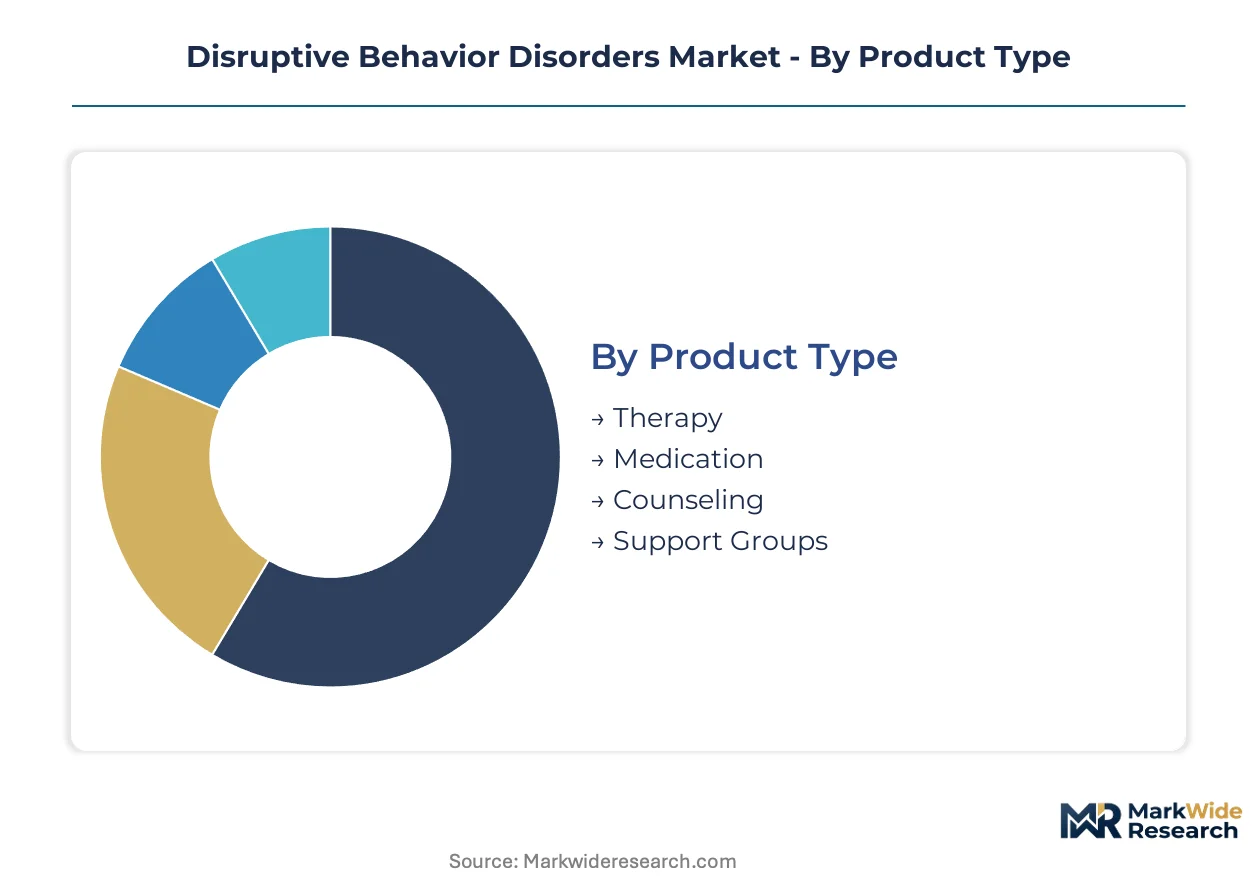
Service configuration and reimbursement pathways vary sharply across delivery settings for disruptive behavior disorders. Segment-level investment priorities reflect divergent regulatory compliance burdens, workforce availability, and payer contracting flexibility.
Product Type:
Replacement cycles for therapeutic modalities accelerate as digital platforms displace legacy service formats and pharmacologic pipelines mature.
- Therapy:Structured behavioral interventions including cognitive-behavioral protocols and parent management training constitute the foundational non-pharmacologic approach. Demand concentrates in Germany's statutory health insurance system following reimbursement expansion for behavioral parent training programs.
- Medication:Stimulant and non-stimulant pharmacotherapies administered in extended-release and long-acting injectable forms dominate revenue concentration. FDA pediatric exclusivity provisions incentivize sponsors to conduct dedicated pediatric trials, extending market protection for approved conduct disorder indications.
- Counseling:Individual and family-focused supportive services address milder symptom presentations and adjunctive care needs.
- Support Groups:Peer-based facilitation models serve maintenance-phase populations with reduced clinical intensity requirements.
Volume placements concentrate in Medication; the faster expansion belongs to Therapy.
End User:
Procurement authority and payment mechanisms fragment sharply across institutional settings, reshaping vendor go-to-market requirements.
- Clinics:Outpatient mental health facilities and specialized pediatric psychiatry centers deliver the majority of diagnostic and maintenance care. Pediatric mental health clinics across the United States are expanding service lines for conduct disorder interventions.
- Hospitals:Inpatient psychiatric units and emergency departments manage acute crisis presentations and medication initiation.
- Family Services:Community-based agencies and child welfare organizations provide court-mandated and protective-service-linked interventions.
- Schools:District-level bundled payment pilots for conduct disorder interventions create new procurement channels outside traditional clinic billing.
Revenue concentration sits with Clinics; Schools are climbing the fastest as value-based contracts proliferate.
Application:
Developmental timing determines intervention design, trial investment levels, and lifetime burden reduction calculus.
- Childhood Disorders:Early-onset conduct disorder and oppositional defiant disorder presentations command the deepest clinical trial investment. Childhood disorders attract priority labeling from FDA pediatric psychopharmacology guidance.
- Adolescent Issues:Juvenile justice-involved and residential treatment populations drive adoption of long-acting injectable formulations to reduce daily administration burden.
- Family Therapy:Systems-based interventions targeting interaction patterns rather than individual symptom reduction.
- Behavioral Interventions:School-based and community-deployed protocols emphasizing skill acquisition over diagnostic categorization.
Clinical trial investment peaks in Childhood Disorders; Adolescent Issues are gaining share fastest through institutional formulary adoption.
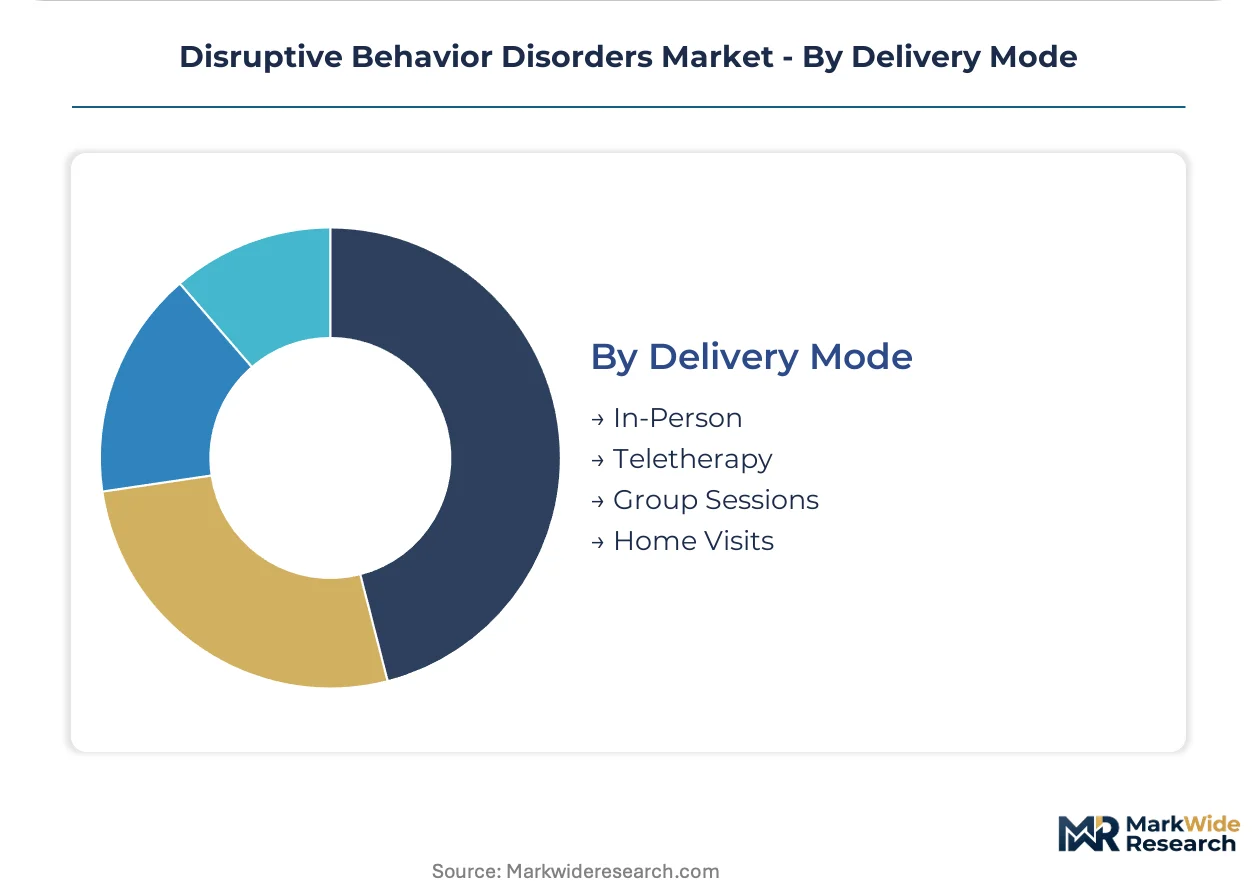
Delivery Mode:
Technology infrastructure and regulatory compliance costs determine platform economics and geographic reach.
- In-Person:Traditional clinic-based and facility-delivered services remain the reimbursement baseline. Concentrated supply of board-certified child psychiatrists in urban academic centers limits service expansion velocity.
- Teletherapy:Asynchronous digital therapeutic delivery gains CMS and private payer coding acceptance. HIPAA interoperability rules and GDPR health data provisions constrain real-world evidence collection architectures.
- Group Sessions:Cost-efficient modality for behavioral parent training and social skills development.
- Home Visits:Intensive in-home family preservation services for high-acuity or protective-service-mandated cases.
Reimbursement anchoring favors In-Person; Teletherapy shows the steepest expansion trajectory as asynchronous platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
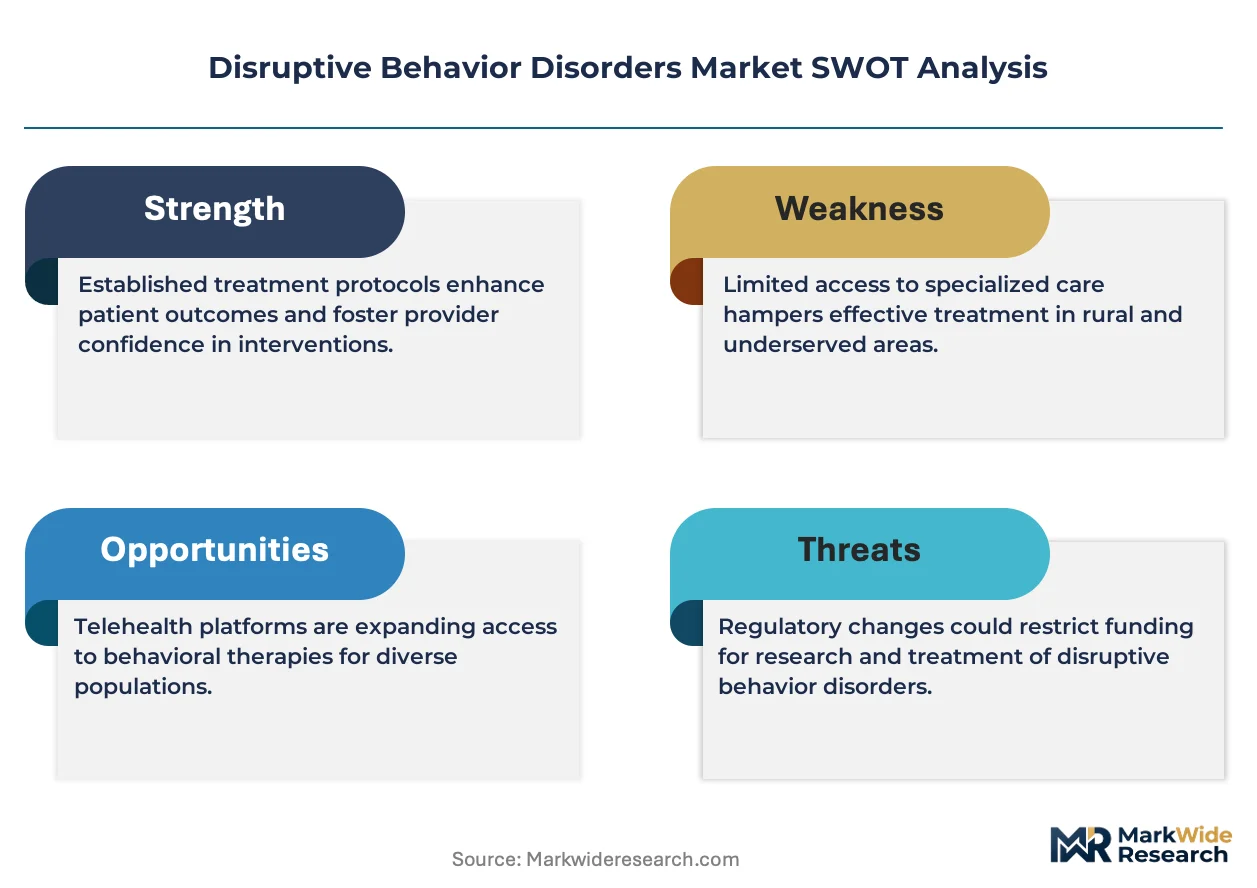
Demand concentrates in Germany's statutory health insurance system and United States pediatric mental health networks, with reimbursement policy shifts determining regional investment priority.
United States
Pediatric mental health clinics in Boston, New York, and Los Angeles metropolitan areas are expanding conduct disorder service lines. FDA pediatric exclusivity provisions incentivize sponsors to conduct dedicated trials, extending market protection for approved indications. HIPAA interoperability rules constrain real-world evidence collection architectures for digital therapeutic platforms.
Germany
Statutory health insurance reimbursement for behavioral parent training has broadened, expanding addressable service volume for non-pharmacologic interventions. EMA Paediatric Investigation Plans synchronize juvenile toxicity study requirements with FDA guidance. Munich and Berlin academic medical centers anchor clinical trial infrastructure for extended-release formulation development.
United Kingdom
NHS England's Mental Health Services for Children and Young People transformation program drives procurement for school-based interventions. GDPR health data provisions elevate compliance costs for platform-based service models. London's Great Ormond Street Hospital and Cambridge University Hospitals cluster pediatric psychiatry research capacity.
Japan
PMDA pediatric psychopharmacology guidance documents shape trial design for novel molecular entities in conduct disorder populations. METI funding for digital health platforms accelerates asynchronous teletherapy adoption. Tokyo and Osaka metropolitan areas concentrate board-certified child psychiatrist supply.
Canada
Health Canada's pediatric drug development framework aligns with FDA and EMA requirements for juvenile animal testing mandates. Provincial health authorities in Ontario and British Columbia pilot value-based contracts for school-based behavioral interventions. Toronto's Hospital for Sick Children anchors North American pediatric psychopharmacology research networks.
Disruptive Behavior Disorders Market Competitive Environment
Portfolio diversification dominates the current landscape as established pharmaceutical manufacturers extend pediatric indications for existing neurological platforms. The market structures around three tiers: large-cap diversified pharmas with endocrinology-neuroscience crossover infrastructure, mid-cap specialty developers with long-acting formulation expertise, and generic manufacturers competing on pediatric compliance formats. Strategic archetypes include extended-release platform specialists, behavioral parent training platform operators, and institutional formulary incumbents. M&A activity and geographic expansion into European hospital systems represent the dominant competitive moves.
Among large-cap diversified manufacturers, Novartis AG and Eli Lilly occupy positions as archetypal platform infrastructure holders, while Pfizer Inc. exemplifies the institutional formulary incumbent model. GlaxoSmithKline plc represents the European hospital network specialist archetype. Teva Pharmaceuticals Industries Ltd. anchors the generic pediatric compliance tier. Johnson & Johnson sits within the diversified health conglomerate structure with cross-divisional pediatric development capabilities.
| Leading Market Players |
|---|
| Novartis AG |
| GlaxoSmithKline plc |
| Eli Lilly |
| DURECT Corporation |
| Bionomics |
| Pfizer Inc. |
| Teva Pharmaceuticals Industries Ltd. |
| Chelsea Therapeutics International, Ltd. |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient costs for long-acting methylphenidate formulations flow from Indian and Chinese contract manufacturers through Eli Lilly's endocrinology-neuroscience crossover facilities, stratifying final pricing across premium extended-release injectables, standard oral disintegrating tablets, and economy generic stimulants.
Pricing Analysis
Volume concentration in generic oral disintegrating tablets compresses margins, while premium long-acting injectables sustain pricing power through FDA pediatric exclusivity protections and institutional formulary lock-in. Price differentiation rests on bioequivalence certification tier and administration route complexity, with daily-dose generics facing intensifying cost compression from Teva Pharmaceuticals Industries Ltd. and peer manufacturers. School-based value-based contract pilots exhibit highest price sensitivity; juvenile justice facilities and residential treatment centers show lowest sensitivity due to adherence-driven total-cost-of-care economics.
Supply Chain Analysis
Reverse-logistics flows for controlled-substance stimulants impose specialized custody requirements, with unused long-acting injectables returning through DEA-authorized reverse distributors rather than standard pharmaceutical wholesaler channels. API manufacturing concentrates in India, China, and Switzerland, with controlled-substance quota allocations from the US Drug Enforcement Administration constraining production scheduling. Supply chain risk centers on single-source vulnerability for osmotic-release oral system technology used in extended-release platforms. Distribution runs through three-tier pharmaceutical wholesaler networks, with specialty pharmacy channels gaining share for patient-administered long-acting formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portfolio holders are racing to secure upstream control over extended-release formulation technology and downstream access to school-based procurement channels, with vertical integration into pediatric psychiatry clinic networks emerging as the decisive capability differentiator.
For Market Incumbents: Anticipate displacement from asynchronous teletherapy platforms by acquiring behavioral parent training software assets or licensing automated progress-tracking modules to Medicaid plans. Secure manufacturing capacity reservations for long-acting injectable fill-finish operations in Germany and the United States ahead of EMA Paediatric Investigation Plan submission deadlines. Backward integration into API synthesis for non-stimulant alternatives reduces exposure to DEA quota volatility. For New Entrants and Emerging Players: Enter via school-based bundled payment pilots in Ontario, British Columbia, and Texas districts where value-based contracting infrastructure lacks incumbent vendor relationships. Target rural and underserved urban catchment areas where synchronous provider availability constraints create white-space demand for asynchronous platform delivery. Pursue partnership routes with statutory health insurance funds in Germany rather than direct-to-clinic sales models. For Investors and Strategic Acquirers: CMS reimbursement convergence with state telehealth parity laws is the leading indicator that capital-light platform scaling will outperform clinic network expansion over the five-to-ten year horizon. Prioritize acquisition targets with FDA pediatric exclusivity-protected labels and established EMA Paediatric Investigation Plan compliance records. Monitor DEA controlled-substance quota allocation announcements for early signals of API supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA pediatric exclusivity provisions extend market protection for approved conduct disorder indications. |
| Regulatory Approval Pathway | EMA Paediatric Investigation Plans synchronize juvenile toxicity requirements with FDA guidance documents. |
| Manufacturing Scale-Up | Endocrinology-neuroscience infrastructure reuse reduces capital requirements for long-acting formulation production. |
| Pipeline Diversification | Non-stimulant alternatives address reimbursement pressure on controlled-substance schedules. |
| Strategic Partnership | School district value-based contracts create procurement channels outside traditional clinic billing. |
Study Parameters
Independent corroboration across FDA pediatric psychopharmacology guidance documents, EMA Paediatric Investigation Plan submissions, and CMS reimbursement rulemaking underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at European hospital systems, and payer access specialists combined with secondary validation from ClinicalTrials.gov, FDA filings, formulary databases, and statutory health insurance reimbursement bulletins. Bottom-up service line expansion data from pediatric mental health clinics triangulated against top-down pharmaceutical manufacturer revenue segment disclosures.
Comparable-period anchoring to historical FDA pediatric exclusivity award patterns and EMA approval timelines established the forecast window boundaries. Segmentation modeling spanned product type, end user, application, and delivery mode dimensions across the projection horizon. CAGRs derived from patent expiry schedules, generic entry assumptions, and teletherapy platform adoption curves. Forecast inputs included DEA controlled-substance quota trajectories and state telehealth parity law enactment velocities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DEA scheduling reclassification or CMS remote therapeutic monitoring code deletion scenarios. Practitioners should monitor FDA pediatric psychopharmacology guidance revisions and German statutory health insurance reimbursement bulletins for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market