
 Myelofibrosis Market | 2026-2036
Myelofibrosis Market Size, Share, and Industry Trends Forecast 2026-2036
Myelofibrosis Market Outlook
Companion diagnostic revenue is fragmenting across biomarker platforms and decentralized testing nodes. Incyte Corporation anchors the JAK inhibitor segment through regulatory precedents established with ruxolitinib. Pfizer competes through pipeline diversification into novel mechanism combinations. Novartis extends its position via manufacturing scale for targeted myelofibrosis therapeutics.
Myelofibrosis constitutes a Philadelphia chromosome-negative myeloproliferative neoplasm characterized by clonal megakaryocyte proliferation, progressive bone marrow fibrosis, and extramedullary hematopoiesis, requiring molecular profiling for JAK2, CALR, or MPL mutation status to guide therapeutic selection. JAK Inhibitors dominate current product type revenue due to established efficacy in splenomegaly reduction and symptom burden improvement. Immunotherapy represents the fastest-expanding category as checkpoint inhibitors and cellular therapies enter clinical development for treatment-resistant populations. Hospital Treatment applications sustain the largest volume share, though Home Care channels are deepening as oral agent tolerability improves and remote monitoring infrastructure matures.
FDA oversees approval pathways through the Oncology Center of Excellence, while EMA coordinates centralized marketing authorization via the Committee for Medicinal Products for Human Use, and both frameworks increasingly mandate real-world evidence generation for accelerated designations. These regulatory structures elevate clinical trial costs but compress time-to-market for breakthrough therapies addressing unmet need in intermediate and high-risk disease. Stakeholders must monitor evolving biomarker-driven trial designs and payer negotiation dynamics for combination regimens.
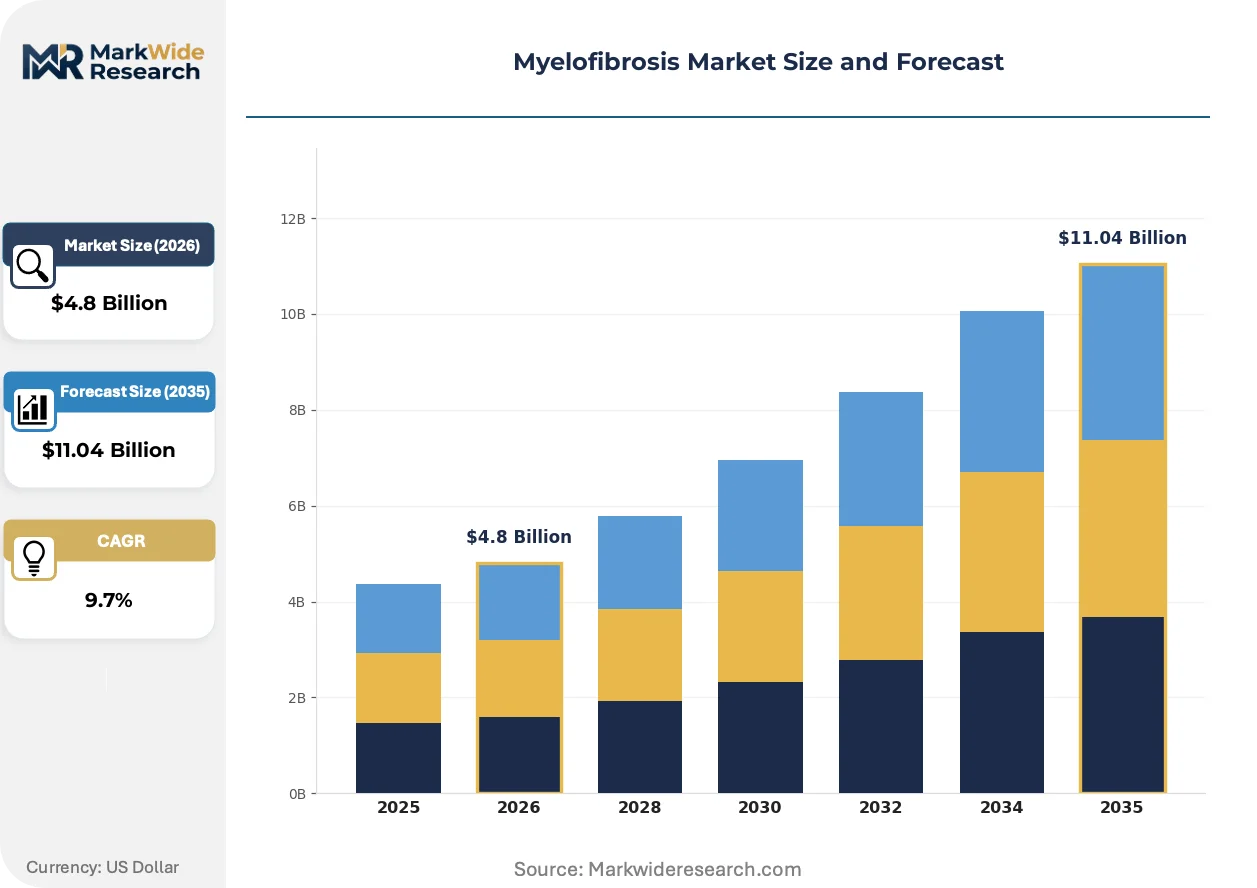
Market Dynamics
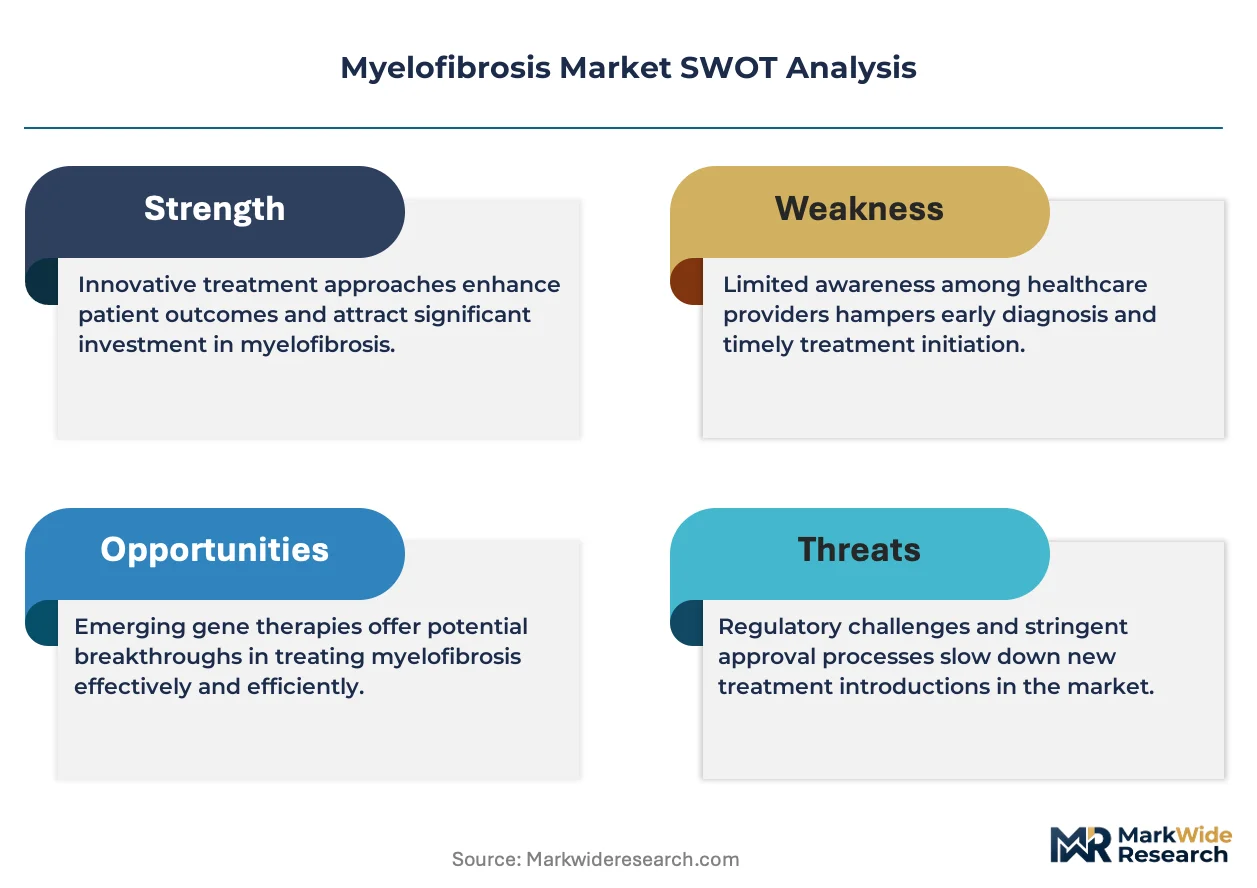
JAK inhibitor saturation in first-line settings is forcing pipeline developers toward combination architectures and biomarker-stratified trial designs to secure differentiation.
Growth Catalysts
- FDA Accelerated Approval:The Oncology Center of Excellence compresses development timelines for agents addressing intermediate-risk disease, rewarding sponsors with real-world evidence generation mandates.
- Splenomegary Measurement Standardization:IWG-MRT consensus criteria enable cross-trial comparability, reducing regulatory friction for novel mechanism submissions.
- Specialty Oncology Clinic Expansion:United States referral networks for myeloproliferative neoplasms deepen patient capture and protocol adherence.
Market Restraints
- JAK Inhibitor Class Ceiling:Established agents exhaust their addressable population in intermediate-risk disease, leaving high-risk and triple-negative subpopulations with limited options.
- Bone Marrow Biopsy Dependency:Diagnostic confirmation requires invasive sampling, creating friction in community oncology settings where hematopathology expertise concentrates in academic centers.
- Reimbursement Compression:Payer negotiation dynamics for oral oncology agents intensify as combination regimens threaten budget impact thresholds.
Strategic Opportunities
- CALR-Mutant Stratification:Companion diagnostic development for calreticulin-mutant subpopulations opens addressable space beyond JAK2-dominated trial history.
- Home Care Channel Maturation:Remote monitoring infrastructure and oral agent tolerability enable treatment displacement from infusion centers to ambulatory settings.
- Immunotherapy Convergence:Checkpoint inhibitor and cellular therapy platforms create combination potential for treatment-resistant populations.
Industry Challenges
- Hematopathology Talent Scarcity:Bone marrow morphology expertise concentrates in tertiary centers, constraining diagnostic throughput in community settings.
- Biomarker Assay Harmonization:JAK2 V617F allele burden quantification varies across PCR platforms, complicating patient selection for mutation-directed trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myelofibrosis Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: JAK Inhibitors, Chemotherapy Agents, Immunotherapy, Supportive Care Application: Clinical Trials, Hospital Treatment, Home Care, Palliative Care End User: Oncology Clinics, Research Institutions, Hospitals, Home Healthcare Treatment Line: First-Line, Second-Line, Third-Line, Subsequent Therapy |
| Companies Covered | Pfizer, Roche, Incyte Corporation, Geron Corporation, GSK, Novartis, AbbVie, MorphoSys, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myelofibrosis Market Strategic Shifts
Therapeutic development is pivoting from monotherapy dominance toward mechanism-diverse combinations, while regulatory frameworks and care delivery models co-evolve to accommodate complexity.
Next-generation JAK inhibitors with differentiated selectivity profiles are migrating from hematologic malignancy portfolios into myelofibrosis-specific development. Biotechnology sponsors prioritize candidates with reduced myelosuppression to enable combination with hypomethylating agents. This migration is compressing the development timeline advantage historically held by first-mover JAK inhibitors.
EMA centralized marketing authorization via the Committee for Medicinal Products for Human Use now mandates real-world evidence generation for accelerated designations. Post-approval study commitments extend trial infrastructure costs but compress time-to-reimbursement for breakthrough therapies. German reference pricing authorities weight these evidence packages heavily in AMNOG benefit assessments.
Site-of-care decisions increasingly favor oral agent administration with remote monitoring over hospital-based infusion. United States specialty pharmacy networks capture dispensing volume as oral JAK inhibitor protocols mature. Germany's structured treatment programs (Anwendungsbegleitende Information) provide a template for ambulatory oversight frameworks.
Myelofibrosis Market Segmentation
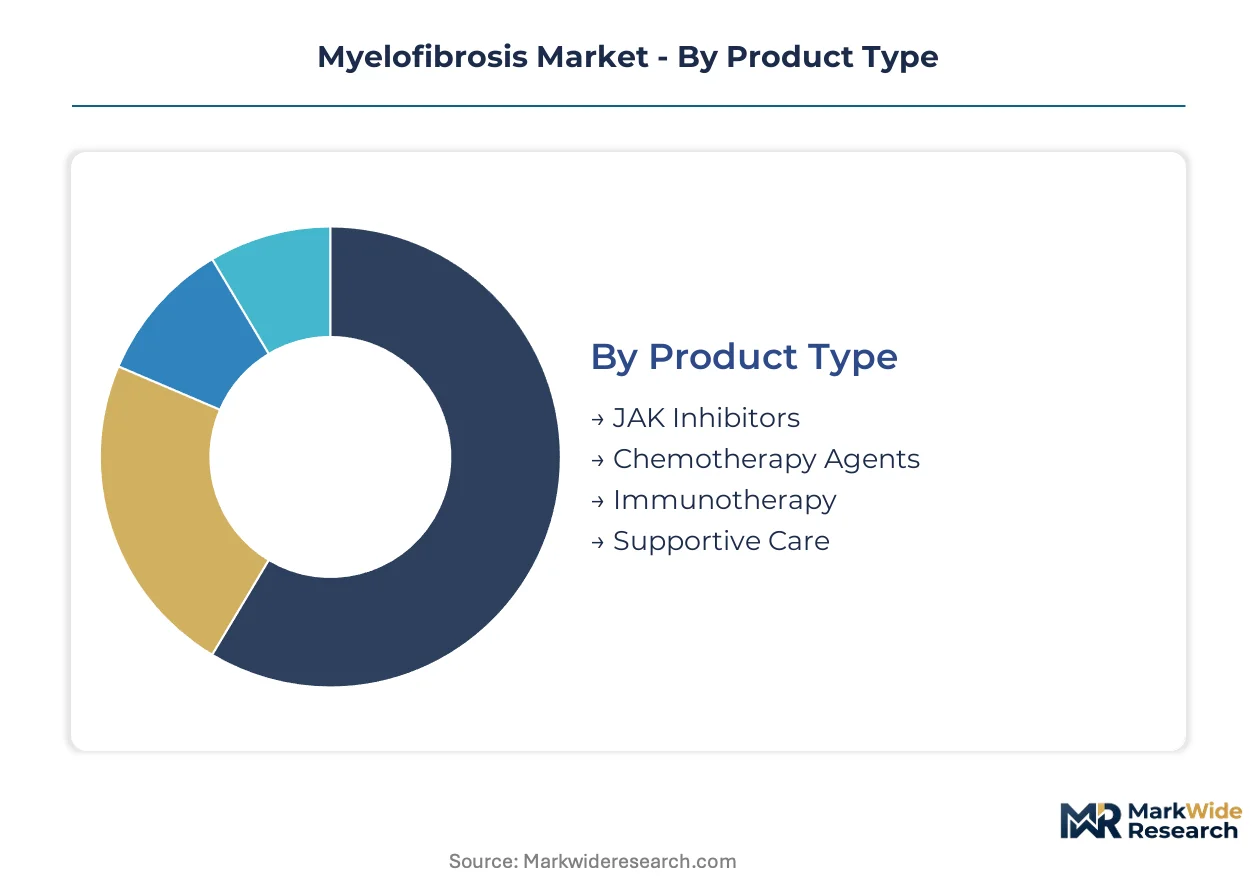
Myelofibrosis treatment pathways fragment across molecular subtypes, risk stratification, and care delivery settings. Segmentation reveals where pharmaceutical investment concentrates and where unmet need persists.
Product Type:
Therapeutic modalities span targeted kinase inhibition through immune modulation, with each class carrying distinct development timelines and reimbursement profiles.
- JAK Inhibitors:Small-molecule agents targeting JAK1/JAK2 kinases reduce splenomegaly and constitutional symptoms. United States specialty oncology clinics drive volume as ruxolitinib and fedratinib establish first-line protocols, though myelosuppression limits combination potential.
- Immunotherapy:Checkpoint inhibitors and cellular therapy platforms address treatment-resistant populations. Germany's academic medical centers concentrate early-phase trial enrollment for CAR-T and bispecific constructs in triple-negative disease.
- Chemotherapy Agents:Hypomethylating agents and hydroxyurea manage cytoreduction in high-risk transformation. Demand clusters in Japan where transplant-eligible patients require bridging therapy.
- Supportive Care:Transfusion management, growth factors, and symptom-directed interventions sustain quality of life. Home healthcare networks in the United States capture dispensing as oral supportive agents expand.
The dominant share belongs to JAK Inhibitors, while Immunotherapy is closing the gap fastest.
Application:
Site-of-care decisions reflect therapy complexity, monitoring intensity, and patient functional status.
- Hospital Treatment:Infusion-based protocols, transplant coordination, and acute complication management occur in tertiary hematology centers. Germany's university hospitals anchor volume through structured treatment programs.
- Home Care:Oral JAK inhibitor administration with remote monitoring displaces hospital visits. United States specialty pharmacy networks deepen penetration as tolerability data mature.
- Clinical Trials:Experimental agent access concentrates in academic centers with molecular profiling capability. Japan's PMDA-registered sites expand enrollment for novel mechanism studies.
- Palliative Care:Symptom-directed interventions for end-stage disease focus on quality-of-life preservation. Hospice partnerships in the United States integrate hematology expertise.
Hospital Treatment retains the largest volume footprint, yet Home Care demonstrates the steepest expansion trajectory.
End User:
Provider type determines diagnostic sophistication, treatment protocol access, and patient risk stratification.
- Oncology Clinics:Dedicated myeloproliferative neoplasm programs deliver molecular profiling and clinical trial access. United States referral networks deepen patient capture in metropolitan clusters.
- Hospitals:Transplant centers and academic medical centers manage high-risk disease and complications. Germany's comprehensive cancer centers coordinate multidisciplinary care.
- Research Institutions:Academic centers drive biomarker discovery and early-phase therapeutic development. Japan's National Cancer Center anchors translational programs.
- Home Healthcare:Ambulatory monitoring and oral therapy administration extend care beyond institutional settings. United States home infusion networks expand JAK inhibitor oversight.
Oncology Clinics command the primary revenue channel, though Home Healthcare is gaining share fastest.
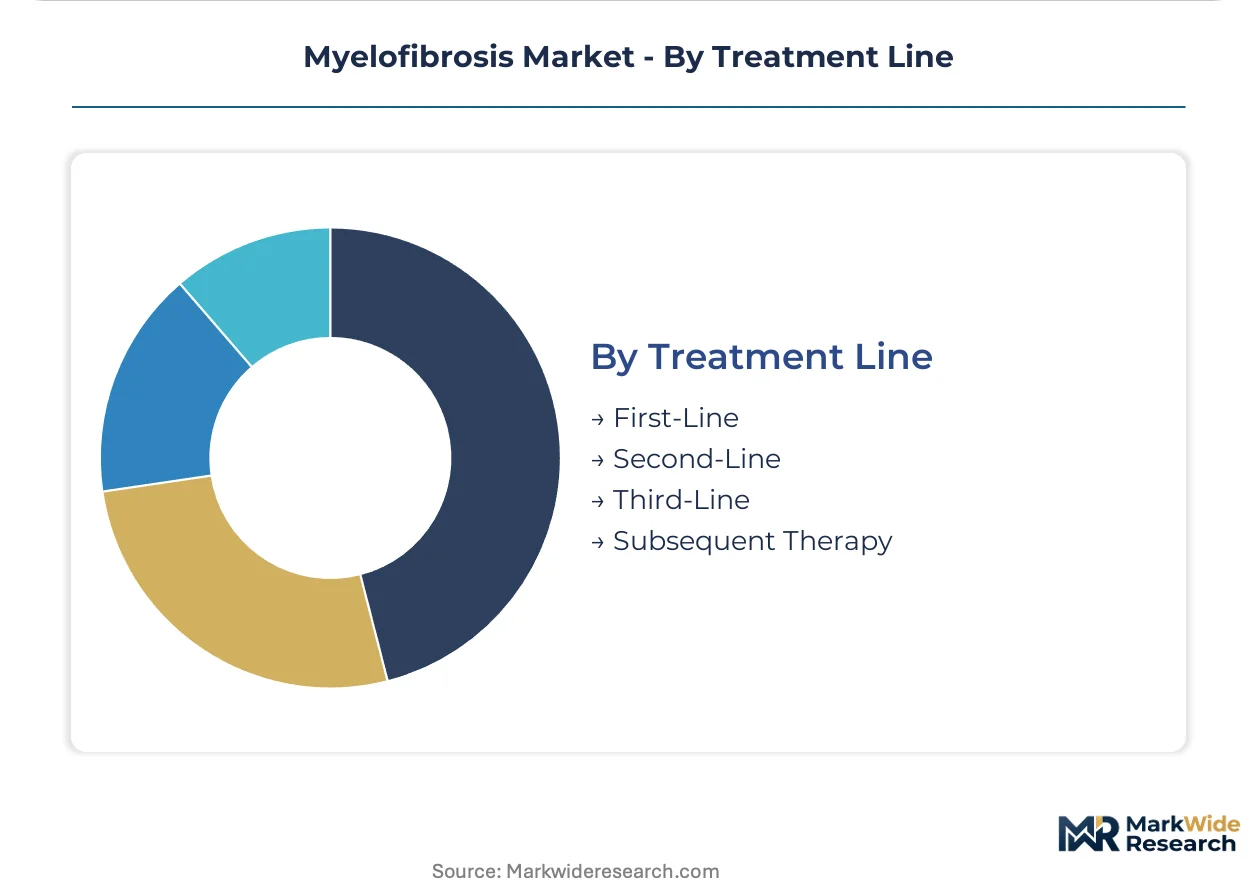
Treatment Line:
Sequential therapy placement reflects disease progression, prior response, and molecular resistance mechanisms.
- First-Line:JAK inhibitor monotherapy dominates intermediate-risk disease initiation. United States community oncology adoption accelerates as diagnostic pathways standardize.
- Second-Line:Alternative JAK inhibitors or clinical trial entry follows primary failure. Germany's reference pricing authorities scrutinize incremental benefit evidence.
- Third-Line:Novel mechanism exploration and combination approaches target refractory disease. Japan's regulatory framework supports conditional approvals in this setting.
- Subsequent Therapy:Transplant evaluation, palliative protocols, and experimental agents address end-stage options. United States academic centers concentrate allogeneic stem cell volume.
First-Line holds the dominant position, while Third-Line is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients access JAK inhibitors through specialty oncology networks, while German protocols emphasize structured treatment programs with centralized reimbursement oversight. Japanese demand clusters around transplant-eligible bridging therapy and novel mechanism trials.
United States
Specialty oncology clinics drive JAK inhibitor volume through metropolitan referral networks. FDA's Oncology Center of Excellence accelerates breakthrough therapy designations for intermediate-risk disease. Boston and New York academic medical centers anchor early-phase trial enrollment for combination architectures.
Germany
Comprehensive cancer centers coordinate multidisciplinary myeloproliferative neoplasm care with molecular profiling. EMA centralized marketing authorization via the Committee for Medicinal Products for Human Use mandates real-world evidence generation. Heidelberg and Munich university hospitals concentrate transplant evaluation and structured treatment program administration.
Japan
PMDA-registered sites expand enrollment for novel mechanism studies in treatment-resistant subpopulations. The country's national pharmaceutical regulator supports conditional approvals for third-line and subsequent therapy settings. Tokyo's National Cancer Center anchors translational research and biomarker discovery programs.
United Kingdom
NHS specialized commissioning frameworks concentrate myelofibrosis care in designated hematology centers. NICE technology appraisals scrutinize incremental cost-effectiveness for JAK inhibitor reimbursement. London and Manchester academic networks drive clinical trial access and molecular diagnostics standardization.
Canada
Provincial formularies negotiate JAK inhibitor coverage through pan-Canadian Oncology Drug Review processes. Health Canada prioritizes accelerated pathways for drugs addressing unmet need in high-risk disease. Toronto and Vancouver tertiary centers concentrate transplant volume and experimental therapy access.
Myelofibrosis Market Competitive Environment
Capability concentration sits with established oncology franchises; scale advantage sits with diversified pharmaceutical conglomerates. The market structure organizes into three tiers: JAK inhibitor incumbents with regulatory precedents, immunotherapy platform developers, and hematology-focused biotechnology specialists. Dominant competitive moves include pipeline diversification into novel mechanism combinations and strategic partnerships for companion diagnostic co-development.
Within the JAK inhibitor tier, Incyte Corporation and Pfizer occupy anchor positions shaped by first-mover regulatory pathways. Novartis exemplifies the diversified pharmaceutical archetype with manufacturing scale for targeted therapeutics. These three entities represent distinct strategic postures: specialized hematology focus, broad oncology portfolio expansion, and integrated global supply infrastructure.
| Leading Market Players |
|---|
| Pfizer |
| Roche |
| Incyte Corporation |
| Geron Corporation |
| GSK |
| Novartis |
| AbbVie |
| MorphoSys |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Air freight corridors linking Swiss pharmaceutical manufacturing hubs to United States specialty pharmacy distribution centers impose cost premiums that concentrate pricing power among JAK inhibitor incumbents while forcing tiered reimbursement negotiations across molecular subtypes.
Pricing Analysis
Long-term offtake agreements between Novartis and United States specialty pharmacy networks anchor first-line JAK inhibitor pricing, while spot procurement for clinical-trial-grade immunotherapy agents commands premiums tied to CALR-mutant stratification requirements. Price differentiation hinges on biomarker-directed companion diagnostic bundling and FDA breakthrough therapy designation status. Cost compression in second-line JAK inhibitor substitution is intensifying as fedratinib and ruxolitinib face formulary parity pressures. Community oncology clinics exhibit highest price sensitivity due to reimbursement lag and prior authorization friction, whereas academic medical centers absorb premium pricing for trial access and molecular profiling integration.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates active pharmaceutical ingredient flow security for JAK inhibitor synthesis, constraining buffer inventory strategies for Incyte Corporation and Pfizer manufacturing partners. API production concentrates in Switzerland, Ireland, and Singapore, drawing from specialized kinase inhibitor intermediate streams and controlled-substance precursor catalogs. Single-source vulnerability in JAK2 V617F assay reagent supply threatens companion diagnostic throughput. Distribution runs through cold-chain validated specialty pharmacy networks with patient-specific dispensing protocols and REMS compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of hematopathology talent capable of bone marrow morphology interpretation and molecular profiling integration constrains diagnostic throughput and fragments patient capture across community and academic settings.
For Market Incumbents: Entrench JAK inhibitor market position through backward integration into companion diagnostic assay manufacturing and exclusive site-of-service partnerships with United States specialty oncology clinic networks. Counter emerging bispecific construct threats by accelerating next-generation selective JAK inhibitor combinations through FDA Oncology Center of Excellence breakthrough pathways. Prioritize CALR-mutant stratification capabilities as a defensive moat against immunotherapy platform encroachment. For New Entrants and Emerging Players: German community oncology settings outside Heidelberg and Munich academic clusters present underpenetration for oral JAK inhibitor home care protocols with remote monitoring infrastructure. Target Japan's transplant-eligible bridging therapy segment where hypomethylating agent demand concentrates and novel mechanism trial access remains constrained. Pursue licensing arrangements with established specialty pharmacy networks rather than building captive distribution. For Investors and Strategic Acquirers: Hematology-focused biotechnology specialists with Phase II-ready immunotherapy assets in triple-negative myelofibrosis represent the most defensible acquisition profile for long-term viability across a five-to-ten-year therapeutic convergence window. Monitor EMA Committee for Medicinal Products for Human Use accelerated designation grants as the primary inflection signal for reimbursement velocity and manufacturing scale commitment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | CALR-mutant stratification protocols in German academic centers accelerate biomarker-directed enrollment timelines. |
| Regulatory Approval Pathway | FDA Oncology Center of Excellence breakthrough designations compress development timelines for intermediate-risk disease agents. |
| Manufacturing Scale-Up | Novartis kinase inhibitor production infrastructure enables global supply security for JAK inhibitor combination regimens. |
| Pipeline Diversification | Pfizer immunotherapy platform investments address treatment-resistant populations beyond JAK inhibitor saturation. |
| Licensing Agreement | Companion diagnostic co-development partnerships resolve JAK2 V617F assay harmonization across PCR platforms. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling across treatment lines and top-down revenue triangulation against disclosed pharmaceutical sales established convergent estimates.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product type, application, end user, treatment line, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated JAK inhibitor protocol adoption rates and immunotherapy clinical trial expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical R&D tax credit policy or Medicare reimbursement rate indexing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval velocity and payer negotiation outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
US Mobile Physician Practice Market