
 Radioimmunotherapy (RIT) Market | 2026-2036
Radioimmunotherapy (RIT) Market Size, Share, and Industry Trends Forecast 2026-2036
Radioimmunotherapy (RIT) Market Analytics
The United States is reshaping radioimmunotherapy manufacturing capacity through new radiopharmaceutical production facilities and cyclotron installations. Novartis leverages its established radioligand therapy platform to sustain leadership in lutetium-based conjugates. Bayer anchors European supply chains with its specialized isotope production network. Actinium Pharmaceuticals competes through targeted alpha-emitter platforms for resistant malignancies.
Radioimmunotherapy combines monoclonal antibodies with radioisotopes to deliver cytotoxic radiation directly to tumor cells, with formulations typically incorporating beta-emitters like iodine-131 or lutetium-177 for hematologic and solid tumor applications. Conjugated antibodies occupy the dominant revenue position due to established clinical validation in non-Hodgkin lymphoma. Oncology applications generate the fastest growth trajectory as solid tumor indications expand beyond the current hematologic focus. Hospitals remain the primary end-user channel, though specialty clinics are capturing margin pools through outpatient administration protocols.
FDA radiopharmaceutical guidance and EMA's centralized marketing authorization procedures govern product standards and market access timelines across North America and Europe. REACH and RoHS frameworks in Europe additionally constrain isotope sourcing and waste management protocols for manufacturers. Stakeholders must monitor reimbursement decisions by national health technology assessment bodies and radiopharmaceutical supply chain vulnerabilities tied to reactor-dependent isotope production.
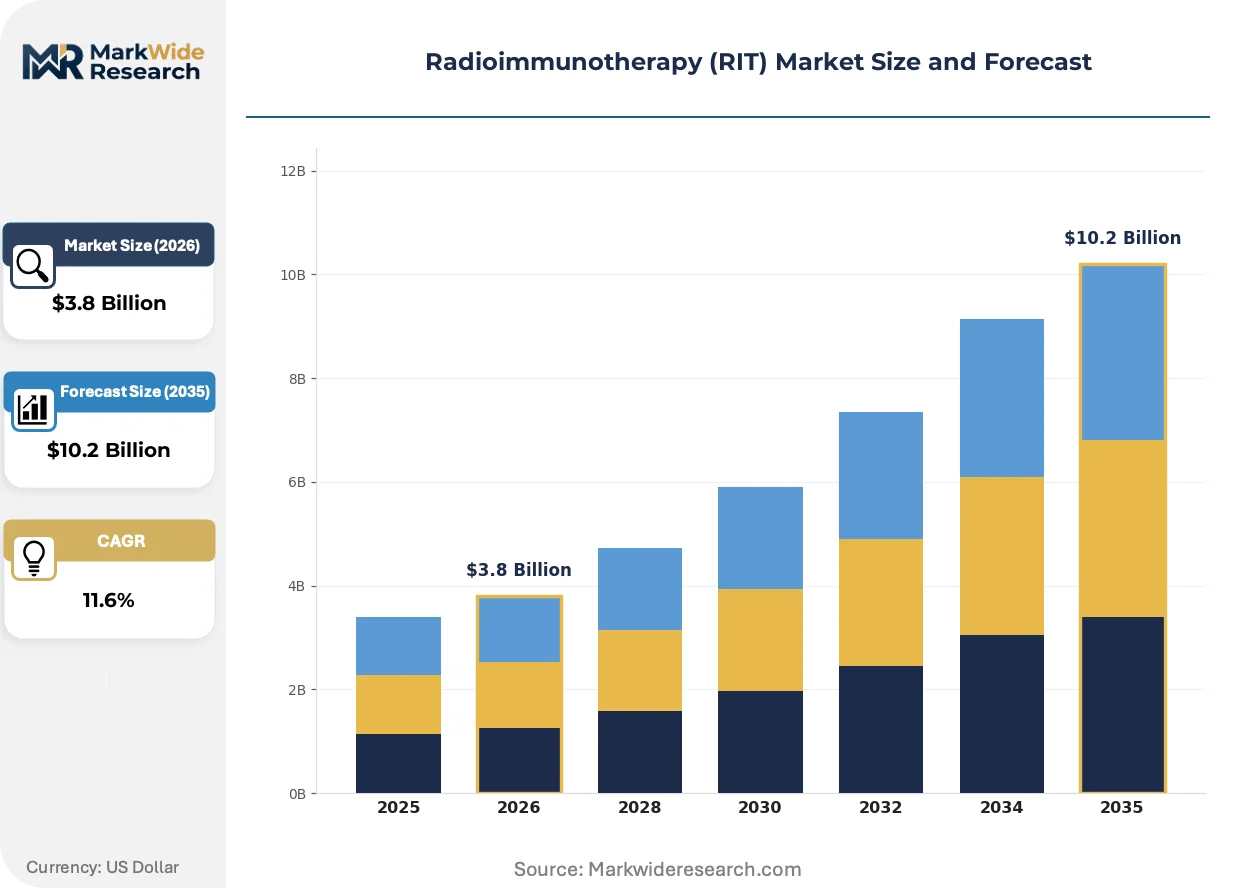
Market Dynamics
Reactor-dependent isotope production bottlenecks are forcing radioimmunotherapy manufacturers to reconfigure supply chains around cyclotron-based alternatives and decentralized radiopharmaceutical networks. This structural pressure reshapes competitive positioning between centralized reactor operators and distributed production platforms.
Growth Catalysts
- FDA Streamlined Pathways:The FDA's radiopharmaceutical guidance accelerates approval timelines for targeted alpha and beta emitters, reducing development-to-market intervals for novel conjugates.
- Oncology Department Expansion:Major hospital systems in the United States, Germany, and Japan are establishing dedicated radioimmunotherapy protocols, creating institutional demand pull for lymphoma and leukemia indications.
- Lutetium-177 Supply Diversification:Cyclotron installations across North America and Europe are reducing dependence on aging research reactors, stabilizing isotope availability for clinical manufacturing.
Market Restraints
- Reactor Concentration Risk:Over 60 percent of medical isotope supply originates from five aging nuclear reactors in Belgium, the Netherlands, Canada, South Africa, and Australia, creating single-point vulnerability.
- Short Half-Life Logistics:Lutetium-177's 6.7-day half-life and actinium-225's 10-day half-life impose just-in-time production constraints that inflate distribution costs and limit geographic reach.
- REACH and RoHS Compliance Burden:European manufacturers face escalating waste management and isotope sourcing protocols that extend facility certification timelines and constrain supplier pools.
Strategic Opportunities
- Solid Tumor Indication Expansion:Prostate-specific membrane antigen targeting and other non-hematologic applications represent underpenetrated clinical segments with substantial addressable patient populations.
- Specialty Clinic Channel Development:Outpatient administration protocols enable margin capture outside hospital systems, particularly in Germany and Japan where reimbursement supports ambulatory radiopharmaceutical delivery.
- Targeted Alpha-Emitter Platforms:Actinium-225 and bismuth-213 conjugates for resistant malignancies offer differentiation from established beta-emitter competition, with EMA centralized marketing authorization providing European pathway clarity.
Industry Challenges
- Radiopharmaceutical Manufacturing Talent Scarcity:Qualified personnel for GMP-compliant isotope handling, conjugation chemistry, and quality assurance remain concentrated at established nuclear medicine centers, constraining facility expansion.
- Cyclotron Capital Intensity:Each high-energy cyclotron installation requires 15-25 million dollars in equipment and shielding infrastructure, with 3-5 year construction timelines delaying supply diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radioimmunotherapy (RIT) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conjugated Antibodies, Radiolabeled Antigens, Radioisotope Therapeutics, Combination Therapies Application: Oncology, Hematology, Autoimmune Disorders, Infectious Diseases End User: Hospitals, Research Laboratories, Specialty Clinics, Academic Institutions Distribution Channel: Direct Sales, Distributors, Online Sales, Group Purchasing Organizations |
| Companies Covered | AstraZeneca, Mariana Oncology, Novartis, Lantern Pharma, RayzeBio, Bayer, Eli Lilly, Actinium Pharmaceuticals, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radioimmunotherapy (RIT) Market Evolving Landscape
Alpha-emitter technology is collapsing the historical beta-emitter dominance in radioimmunotherapy, while regulatory frameworks and procurement models simultaneously restructure how radiopharmaceuticals reach patients. These intersecting forces compress development cycles and redistribute value across the supply chain.
Targeted alpha-therapy is collapsing the therapeutic index limitations that constrained earlier radioimmunotherapy generations. Actinium-225 and lead-212 conjugates deliver linear energy transfer values 50-80 times higher than lutetium-177 or iodine-131, enabling single-cell cytotoxicity with reduced bone marrow toxicity. Academic medical centers in the United States and Switzerland are accelerating clinical protocol development for resistant prostate and ovarian malignancies. This is collapsing the addressable market boundary between hematologic and solid tumor applications, forcing beta-emitter specialists to defend position through combination therapy strategies.
EMA's centralized marketing authorization procedures are harmonizing radiopharmaceutical standards across 27 member states, replacing fragmented national approval pathways. The EU's revised pharmaceutical legislation proposal includes specific provisions for radiopharmaceutical manufacturing flexibility, acknowledging short half-life constraints. German and French manufacturers are consolidating production networks to capture economies of scale under this unified framework, while smaller national operators face compliance cost pressures that accelerate market concentration.
Hospital procurement departments are unbundling radiopharmaceutical sourcing from equipment vendor relationships, creating direct contracting channels with specialized isotope suppliers. This disintermediation compresses margin pools for integrated device-and-drug vendors and rewards pure-play radiopharmaceutical manufacturers with GMP certification depth. The United States exhibits this pattern most prominently, where group purchasing organizations for oncology services are establishing preferred supplier tiers based on supply reliability metrics rather than historical relationships.
Radioimmunotherapy (RIT) Market Segmentation
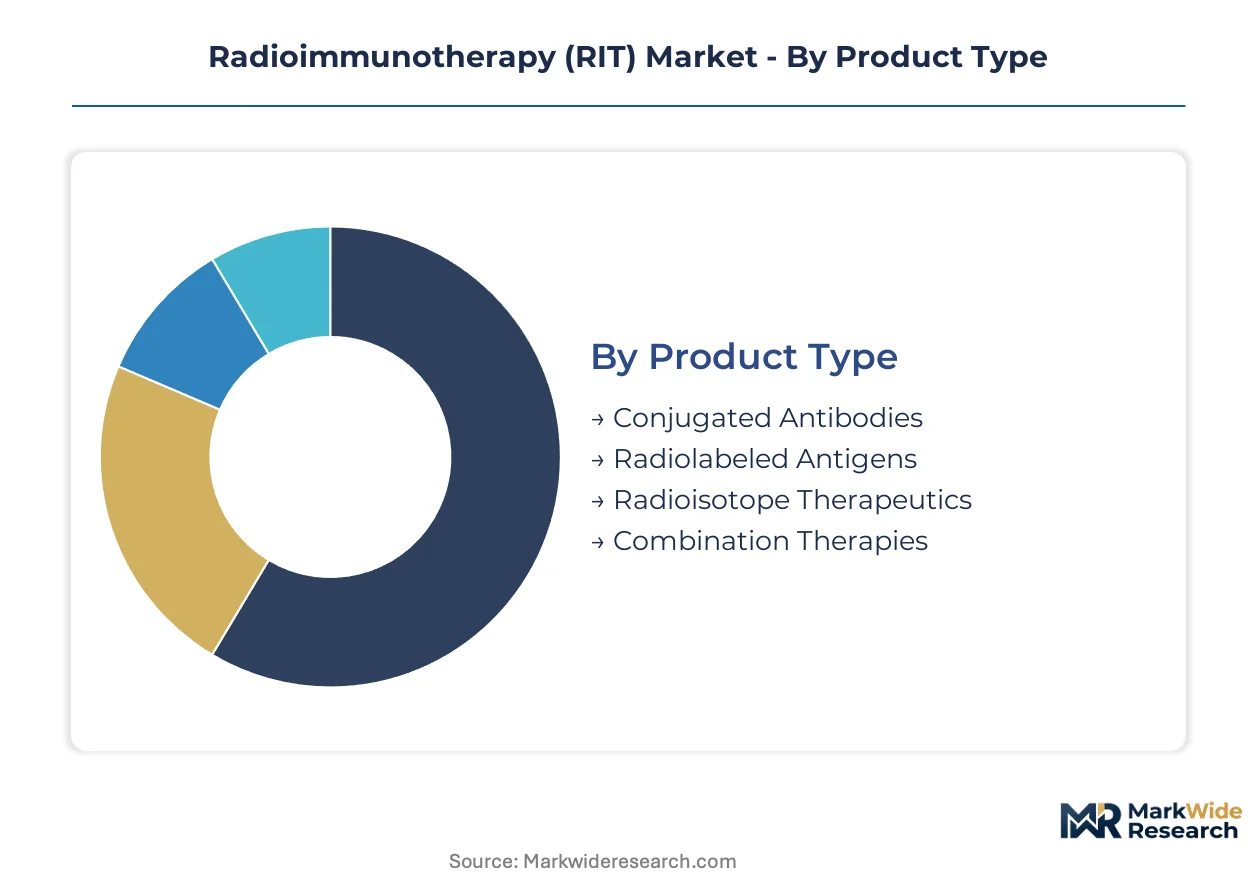
Radioimmunotherapy segmentation reflects distinct manufacturing requirements, clinical validation pathways, and reimbursement structures across product categories. Each dimension shapes procurement patterns and competitive positioning differently.
Product Type:
Mature formulations dominate current revenue while emerging modalities reshape clinical protocols.
- Conjugated Antibodies:Monoclonal antibodies covalently linked to radioisotopes such as iodine-131 or lutetium-177. United States hospital systems concentrate demand for non-Hodgkin lymphoma protocols, driven by established FDA reimbursement codes and cyclotron network proximity.
- Radiolabeled Antigens:Tumor-associated antigens tagged with therapeutic radionuclides for targeted delivery. German oncology departments generate accelerating procurement volumes as EMA centralized authorization streamlines multi-site deployment.
- Radioisotope Therapeutics:Pure radionuclide formulations without antibody carriers.
- Combination Therapies:RIT paired with checkpoint inhibitors or chemotherapy regimens.
Conjugated antibodies handle the majority of throughput; combination therapies are the fastest mover on share.
Application:
Clinical focus determines isotope selection, dosing protocols, and regulatory submission strategies.
- Oncology:Solid tumor and hematologic malignancy treatments using alpha and beta emitters. Japanese nuclear medicine centers drive adoption for prostate-specific membrane antigen targeting, constrained by reactor-dependent supply chains and METI import licensing.
- Hematology:Leukemia and lymphoma applications with established clinical endpoints. United States academic medical centers anchor demand through NCI-sponsored protocol networks and specialized radioisotope handling infrastructure.
- Autoimmune Disorders:Experimental lymphodepletion protocols prior to stem cell transplantation.
- Infectious Diseases:Investigational applications for targeted microbial elimination.
Oncology captures the steepest expansion trajectory; hematology maintains the deepest installed base.
End User:
Facility type dictates capital requirements, staffing models, and patient throughput economics.
- Hospitals:Integrated inpatient-outpatient administration with on-site cyclotron or radiopharmacy capabilities. United States health systems concentrate procurement through group purchasing organizations, prioritizing supply reliability metrics over unit pricing.
- Specialty Clinics:Ambulatory-focused administration with outsourced isotope sourcing. German outpatient oncology centers expand capacity under statutory health insurance reimbursement for lutetium-177 therapies.
- Research Laboratories:Preclinical and early-phase clinical investigation.
- Academic Institutions:Investigator-initiated trials and training programs.
Hospitals absorb the dominant procurement volume; specialty clinics are expanding most quickly in European markets.
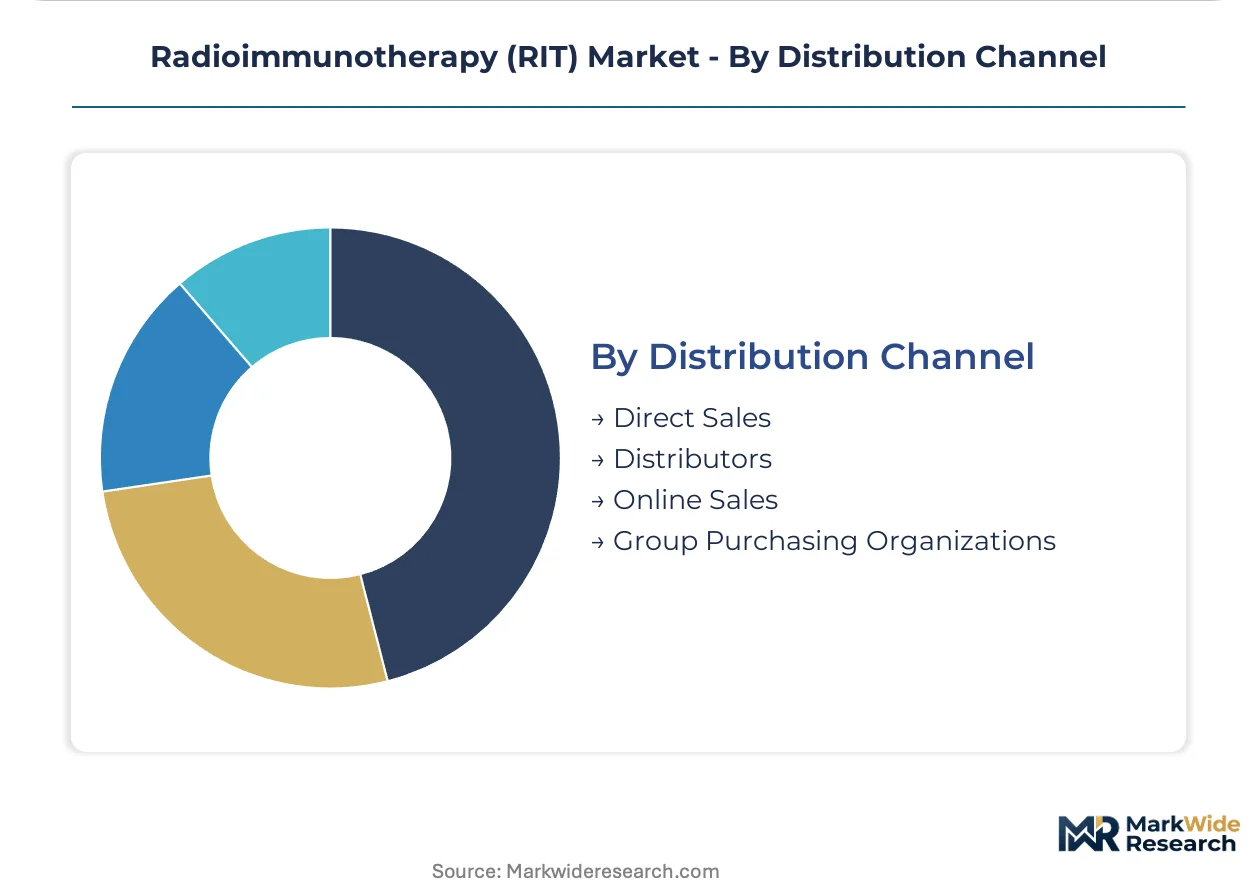
Distribution Channel:
Channel selection reflects just-in-time logistics constraints and GMP certification requirements.
- Direct Sales:Manufacturer-to-facility contracting for high-volume hospital systems. Novartis and Bayer leverage direct relationships with United States oncology departments to secure multi-year supply agreements.
- Group Purchasing Organizations:Consolidated procurement for health system networks. United States GPOs increasingly unbundle radiopharmaceutical sourcing from equipment vendor relationships, creating preferred supplier tiers based on delivery reliability.
- Distributors:Regional logistics intermediaries for fragmented geographic coverage.
- Online Sales:Limited to reference materials and non-therapeutic isotopes.
Direct sales command the largest contract value; group purchasing organizations are gaining share fastest through health system consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA radiopharmaceutical guidance anchors United States market expansion, while cyclotron installations across North America and Europe reduce reactor-dependent supply vulnerabilities. Hospital systems in Germany and Japan are establishing dedicated radioimmunotherapy protocols under streamlined regulatory frameworks.
United States
Oncology departments in major hospital systems are expanding lymphoma and leukemia treatment protocols, creating institutional demand pull for lutetium-based conjugates. FDA radiopharmaceutical guidance accelerates approval timelines for targeted alpha and beta emitters. Novartis leverages its established radioligand therapy platform from East Coast manufacturing facilities.
Germany
Outpatient oncology centers expand capacity under statutory health insurance reimbursement for lutetium-177 therapies. EMA centralized marketing authorization procedures streamline multi-site deployment across member states. Bayer anchors European supply chains with specialized isotope production networks concentrated in Western industrial corridors.
Japan
Nuclear medicine centers drive adoption for prostate-specific membrane antigen targeting applications. METI import licensing frameworks govern radiopharmaceutical supply security. Tokyo and Osaka metropolitan clusters house specialized radioisotope handling infrastructure constrained by reactor-dependent supply chains.
Switzerland
Academic medical centers accelerate clinical protocol development for resistant prostate and ovarian malignancies using targeted alpha-therapy. Swissmedic maintains alignment with EMA centralized procedures for market access. Basel and Zurich pharmaceutical clusters concentrate radiopharmaceutical manufacturing expertise.
United Kingdom
NCI-sponsored protocol networks and specialized radioisotope handling infrastructure anchor hematologic application demand. MHRA operates under EMA-aligned frameworks post-Brexit transition. London and Cambridge medical research clusters house early-phase clinical investigation capabilities.
Radioimmunotherapy (RIT) Market Competitive Landscape
Established pharmaceutical conglomerates and targeted radiopharmaceutical specialists split the market between scale-driven manufacturing and precision-therapy innovation. The vendor base concentrates around cyclotron-network operators and reactor-dependent isotope suppliers. Three archetypes dominate: integrated radioligand therapy platforms, pure-play alpha-emitter developers, and diversified oncology portfolio holders. Competitive moves center on supply chain diversification through cyclotron partnerships and indication expansion beyond hematologic malignancies.
Among diversified pharmaceutical conglomerates, Novartis, Bayer, and AstraZeneca occupy positions representing distinct strategic approaches to radiopharmaceutical market participation. Novartis exemplifies the integrated radioligand therapy platform archetype through its established manufacturing infrastructure. Bayer represents European supply chain anchoring with specialized isotope production capabilities. AstraZeneca sits within the diversified oncology portfolio tier, leveraging broader therapeutic area presence to inform radioimmunotherapy positioning.
| Leading Market Players |
|---|
| AstraZeneca |
| Mariana Oncology |
| Novartis |
| Lantern Pharma |
| RayzeBio |
| Bayer |
| Eli Lilly |
| Actinium Pharmaceuticals |
| Bristol Myers Squibb |
| Others |
Value Network & Pricing Analysis
Belgium-to-United States cold-chain corridors carry lutetium-177 shipments with freight costs that compound reactor concentration premiums, forcing downstream price stratification between hospital systems with captive cyclotron access and those dependent on spot-market isotope procurement. This logistics-cost layering amplifies margin compression for decentralized clinics while reinforcing pricing power among vertically integrated manufacturers with shielded production assets.
Pricing Analysis
Geographic price spreads between United States academic medical centers and German outpatient oncology clinics reflect divergent reimbursement mechanics rather than manufacturing cost differentials. Pricing stratifies across GMP-certified premium tiers, standard clinical-grade formulations, and economy research-isotope bands, with certification level and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because cyclotron network expansion is democratizing lutetium-177 access. Hospital systems with group purchasing organization leverage exhibit lowest price sensitivity; standalone specialty clinics face acute margin pressure from just-in-time logistics premiums.
Supply Chain Analysis
Export-control regimes governing actinium-225 and other high-specific-activity isotopes constrain cross-border flows between United States production facilities and European clinical sites, fragmenting supply security assessments. Manufacturing concentrates in Belgium, the Netherlands, and the United States, with raw material dependencies on enriched uranium feedstock, specialized chelating agents, and GMP-grade antibody intermediates. Single-source vulnerability runs through the five aging research reactors supplying over half of medical isotope demand. Distribution runs through direct manufacturer-to-hospital contracting for high-volume accounts, with regional distributors serving fragmented geographic coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified personnel for GMP-compliant isotope handling and conjugation chemistry remain concentrated at established nuclear medicine centers, constraining facility expansion and creating acquisition premiums for teams with proven regulatory submission track records.
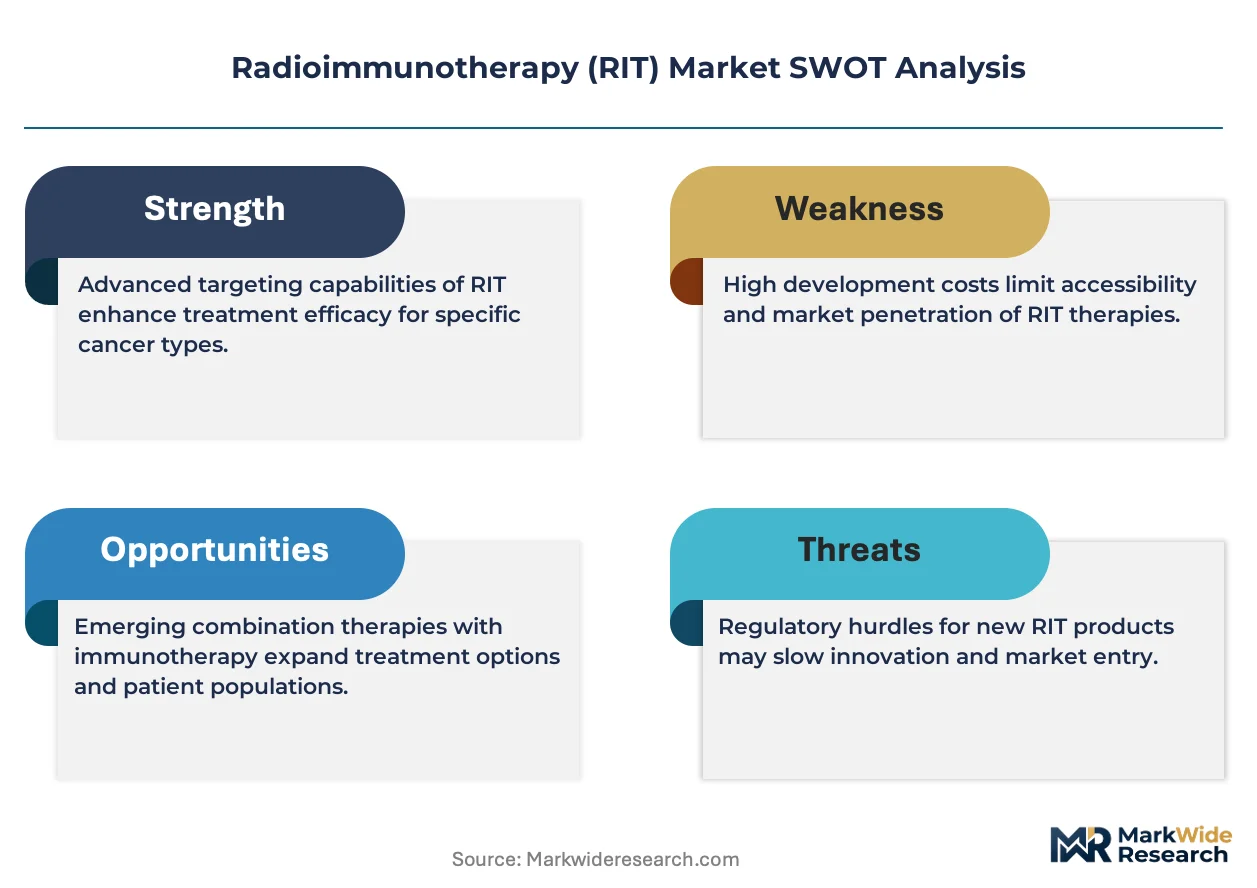
For Market Incumbents: Insulate manufacturing margins through backward integration into cyclotron assets in North American corridors with favorable state-level nuclear regulatory frameworks, while securing long-term supply agreements for actinium-225 feedstock ahead of targeted alpha-therapy protocol expansion. Priority levers include captive isotope production and EMA centralized marketing authorization investment to preempt competitive entry. For New Entrants and Emerging Players: Japanese metropolitan clusters outside Tokyo and Osaka represent the most penetrable geography, where METI import licensing constraints have slowed lutetium-177 adoption relative to patient demand. Target prostate-specific membrane antigen indication expansion with outsourced manufacturing partnerships that bypass capital-intensive cyclotron installation timelines, leveraging Swiss or German contract manufacturing organizations with existing EMA certifications. For Investors and Strategic Acquirers: Pure-play alpha-emitter developers with clinical-stage actinium-225 conjugates and established FDA investigational new drug filings offer the strongest long-term viability profile across a five-to-ten year window. The signal to monitor is EMA centralized marketing authorization grant velocity for novel radioligand therapies, which would validate platform scalability and trigger valuation step-functions for acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Reduces reactor-dependent supply vulnerability for lutetium-177 manufacturing. |
| Targeted Alpha-Emitter Pipeline Advancement | Captures differentiation from beta-emitter competition in resistant malignancies. |
| EMA Centralized Marketing Authorization | Harmonizes multi-state deployment across German and French hospital networks. |
| Specialty Clinic Channel Partnership | Enables margin capture outside hospital systems in German outpatient reimbursement environment. |
| GMP Certification Depth Investment | Creates preferred supplier status with United States group purchasing organizations. |
Research Methodology
Initial hypotheses were tested against primary input from nuclear medicine department heads, radiopharmaceutical manufacturing executives, regulatory affairs specialists, and hospital procurement directors, and refined through secondary validation against FDA radiopharmaceutical guidance documents, EMA centralized marketing authorization procedures, ClinicalTrials.gov protocol registries, and reactor operator supply disclosures. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Demand-supply-balance framing structured the analytical approach across the analysis window, with treatment line, isotope emitter type, administration setting, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from patient population expansion rates, reimbursement trajectory assumptions, and manufacturing capacity buildout schedules. Forecast inputs included cyclotron installation pipelines and EMA authorization timelines for novel conjugates.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, nuclear reactor operational continuity, or radiopharmaceutical supply chain security would shift the trajectory. Forecasts reflect documented assumptions regarding isotope availability and regulatory pathway efficiency. Material shifts in FDA radiopharmaceutical guidance or reactor decommissioning schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Microcephaly Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market