
 Global Major Depressive Disorder (MDD) Market | 2026-2036
Global Major Depressive Disorder (MDD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Major Depressive Disorder (MDD) Market Foresight
Primary care centers is decoupling from traditional psychiatric clinic referrals as the first point of diagnosis for MDD patients. Eli Lilly and Company leverages its neuroscience R&D pipeline to sustain leadership in atypical antidepressant development. Pfizer Inc. anchors its position through extensive primary care channel control. Johnson & Johnson competes with its intranasal delivery platform for treatment-resistant populations.
Major Depressive Disorder constitutes a chronic psychiatric condition characterized by persistent low mood, anhedonia, and cognitive impairment lasting at least two weeks, diagnosed under DSM-5 criteria with severity indexed by the Hamilton Depression Rating Scale. Selective Serotonin Reuptake Inhibitors dominate prescription volume as the established first-line pharmacotherapy, while Serotonin-Norepinephrine Reuptake Inhibitors capture expanding share among patients with comorbid chronic pain. Extended-Release Capsules within delivery mode represent the fastest-growing formulation category as adherence programs prioritize reduced dosing frequency.
The FDA's Breakthrough Therapy designation and EMA's priority medicines scheme accelerate market access for novel MDD therapeutics, while the EU AI Act shapes digital diagnostic tool deployment across European psychiatric clinics. The WHO's Mental Health Action Plan influences national reimbursement frameworks in emerging markets. Stakeholders must monitor evolving psychedelic-assisted therapy regulatory pathways and their potential to displace conventional antidepressant protocols.
Market Dynamics
The FDA's accelerated approval pathways for novel antidepressants are compressing development timelines while reshaping how pharmaceutical firms allocate R&D capital across neuroscience portfolios.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review pathway for treatment-resistant depression candidates reduces time-to-market for intranasal and psychedelic-derived formulations. This mechanism attracts venture funding toward novel mechanisms of action.
- Primary Care Integration:Mental health hospitals are expanding outpatient psychiatric services that embed depression screening into routine chronic disease management. This structural shift expands addressable patient pools beyond traditional psychiatric referrals.
- Digital Phenotyping:Smartphone-based passive monitoring and ecological momentary assessment tools are enabling real-time symptom tracking. These technologies support personalized dosing adjustments and adherence interventions.
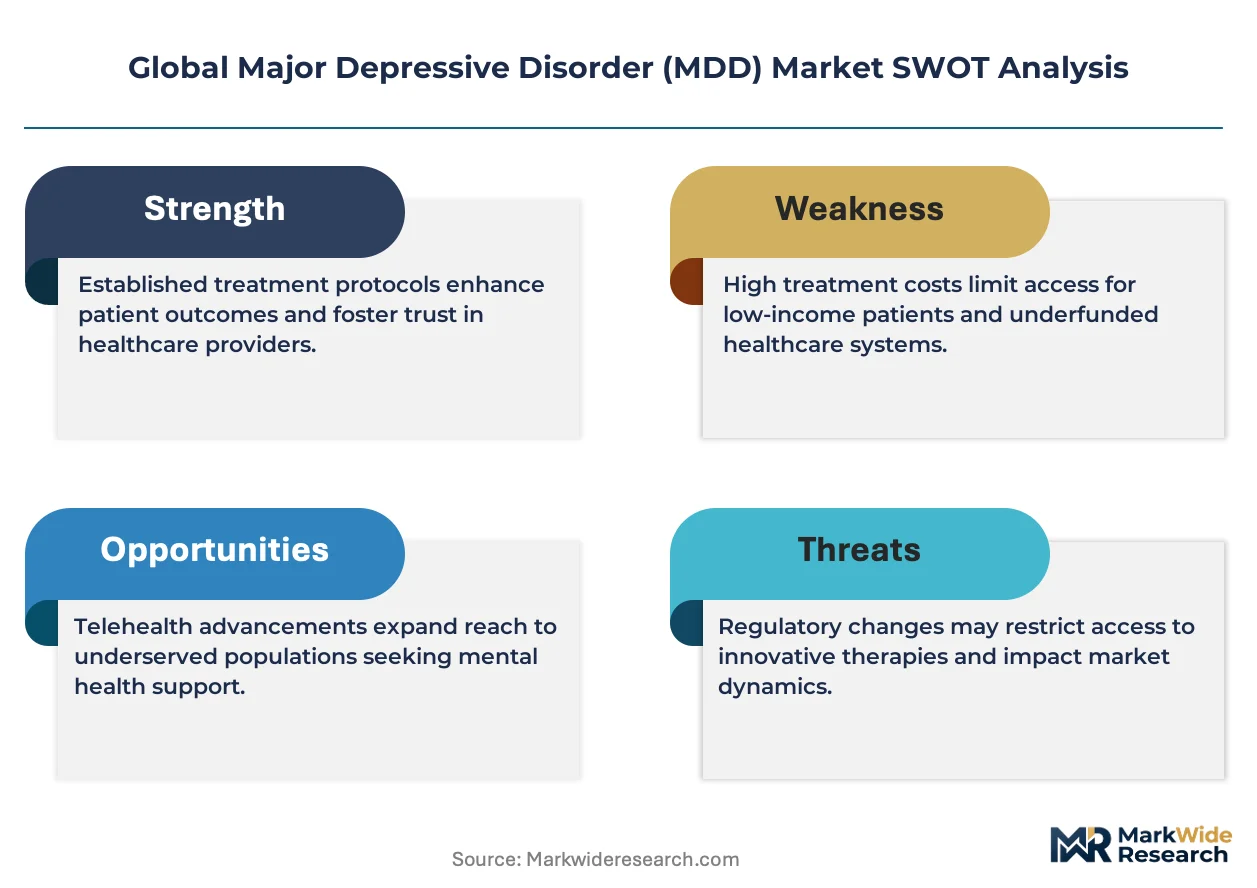
Market Restraints
- Serotonin Receptor Complexity:The incomplete mechanistic understanding of rapid-acting antidepressants limits predictable efficacy profiling. This scientific gap constrains regulatory confidence in novel compound classes.
- Specialty Pharmacy Concentration:Distribution of intranasal esketamine and similar controlled substances concentrates among REMS-certified infusion centers. This channel bottleneck restricts geographic accessibility and creates capacity constraints.
- Reimbursement Lag:Germany's Federal Joint Committee (G-BA) and analogous bodies in France and England impose extended health technology assessment timelines for digital therapeutics. These procedural delays compress commercial runway for app-based interventions.
Strategic Opportunities
- Brazil's Unified Health System Expansion:The Ministry of Health's Psychosocial Care Network restructuring creates procurement scale for first-line pharmacotherapies. This public-sector channel remains underpenetrated by extended-release formulations.
- Pharmacogenomic Testing Convergence:Integration of CYP2D6/CYP2C19 genotyping with antidepressant selection protocols is emerging in Dutch and Swedish integrated care networks. This dual-technology combination supports premium positioning for precision-guided prescribing.
- Employer-Sponsored Mental Health Benefits:Large self-insured employers in the United States are carving out depression management as a distinct benefits category. This channel innovation bypasses traditional pharmacy benefit manager formulary controls.
Industry Challenges
- Psychiatrist Workforce Density:The shortage of board-certified psychiatrists in rural United States counties and comparable gaps in Australia's regional areas forces reliance on non-specialist prescribers. This talent compression elevates litigation exposure and quality variation.
- REMS Infrastructure Burden:The Risk Evaluation and Mitigation Strategy requirements for ketamine-derived therapies impose facility certification costs and monitoring protocols that strain clinic operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Major Depressive Disorder (MDD) Market |
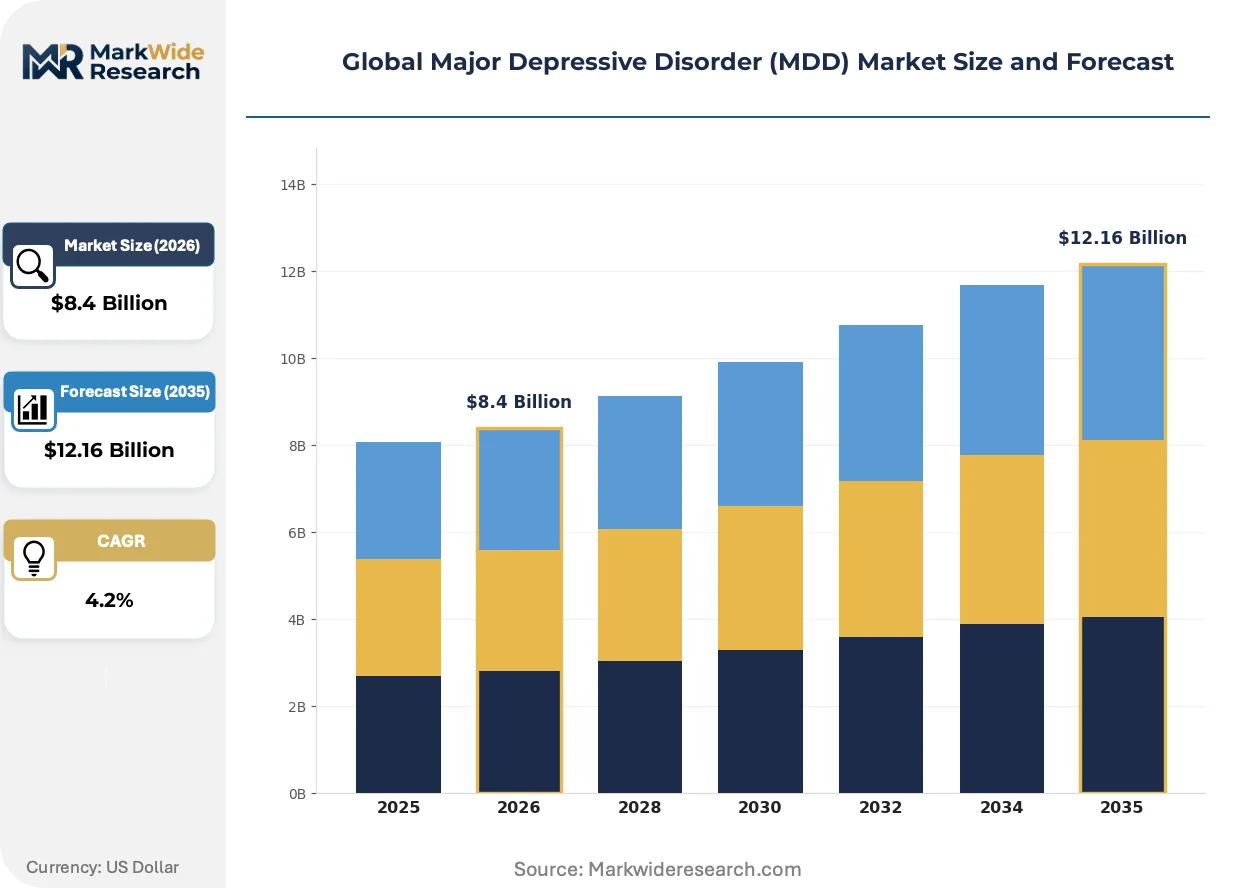
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Unipolar Depression, Bipolar Depression, Treatment-Resistant Depression, Postpartum Depression, Seasonal Affective Disorder Product Type: Selective Serotonin Reuptake Inhibitors, Serotonin-Norepinephrine Reuptake Inhibitors, Tricyclic Antidepressants, Monoamine Oxidase Inhibitors, Atypical Antidepressants End User: Psychiatric Clinics, Mental Health Hospitals, Primary Care Centers, Rehabilitation Facilities, Research Institutes Delivery Mode: Oral Tablets, Extended-Release Capsules, Intravenous Infusion, Transdermal Patches, Intramuscular Injections |
| Companies Covered | Eli Lilly and Company, Pfizer Inc., Johnson & Johnson, AstraZeneca, Otsuka Pharmaceuticals, Lundbeck, Takeda Pharmaceutical Company Limited, AbbVie Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Major Depressive Disorder (MDD) Market Shifts & Advancements
Digital diagnostic platforms and novel delivery mechanisms are fragmenting the traditional antidepressant value chain while creating new interface points between technology developers and clinical service providers.
Intranasal delivery systems for rapid-onset antidepressants are modularizing the administration infrastructure required for treatment-resistant depression protocols. Psychiatric clinics and hospital-based infusion centers are retrofitting existing spaces with specialized monitoring capabilities rather than constructing dedicated facilities. This architectural flexibility is compressing capital deployment timelines and enabling faster geographic expansion of access points.
The EU AI Act's risk classification framework for medical device software is imposing conformity assessment obligations on digital phenotyping and AI-assisted diagnostic tools deployed across European psychiatric clinics. Manufacturers must demonstrate algorithmic transparency and clinical validation to secure CE marking under the Medical Device Regulation. German and French mental health service providers are prioritizing vendors with established quality management system certifications to preempt regulatory friction.
Integrated care networks in the United States are unbundling depression screening from specialty psychiatric encounters and embedding standardized assessment protocols within primary care workflows. The PHQ-9 and GAD-7 instruments are displacing unstructured clinical interviews as the dominant diagnostic interface. This procedural standardization is most visible in Kaiser Permanente and Veterans Health Administration systems, where automated scoring triggers stepped-care algorithm activation.
Global Major Depressive Disorder (MDD) Market Segmentation
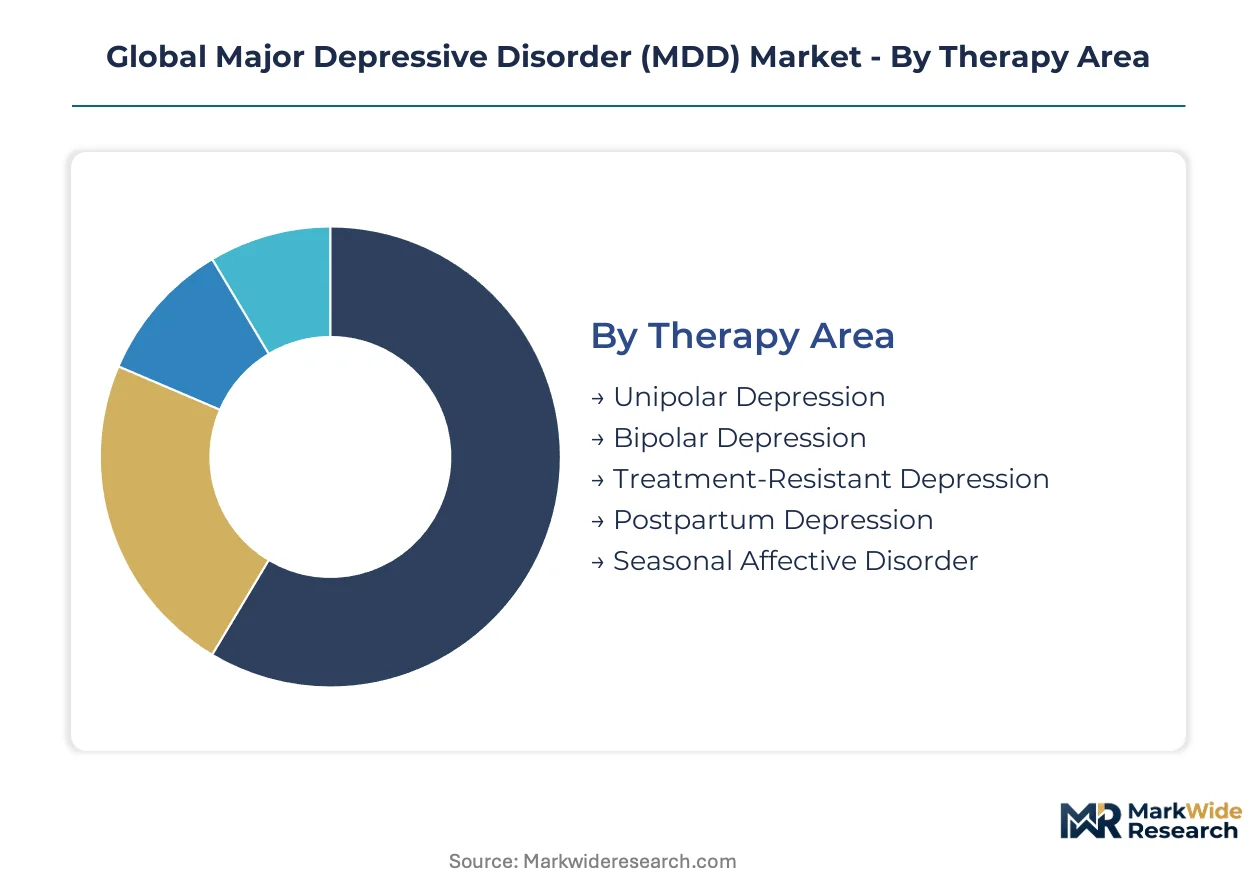
MDD market segmentation reveals divergent capital requirements across therapeutic modalities and care delivery settings. Pharmaceutical firms allocate R&D investment unevenly across mechanism classes, while healthcare infrastructure spending concentrates in specific end-user channels.
Therapy Area:
Capital deployment varies sharply across indication subsets, with clinical trial complexity and regulatory pathway costs driving differential investment thresholds.
- Treatment-Resistant Depression:Intranasal esketamine and emerging psychedelic protocols demand specialized REMS-certified infrastructure and intensive monitoring protocols. Psychiatric clinics in the United States absorb the highest per-patient facility investment due to FDA-mandated observation periods.
- Unipolar Depression:First-line SSRI and SNRI development requires substantial Phase III trial expenditure but leverages established primary care distribution networks. Germany's Federal Joint Committee and analogous bodies in France impose extended health technology assessment timelines that compress commercial runway.
- Bipolar Depression:Mood stabilizer combinations with antidepressant adjuncts require careful pharmacovigilance infrastructure.
- Postpartum Depression:Zuranolone and similar neuroactive steroid formulations target a narrowly defined perinatal population with distinct reimbursement coding.
- Seasonal Affective Disorder:Light therapy device integration and chronobiological interventions occupy a niche position with limited pharmaceutical investment.
Unipolar Depression absorbs the bulk of installed capacity; Treatment-Resistant Depression is expanding most quickly.
Product Type:
Manufacturing complexity and patent cliff exposure create divergent margin profiles across pharmacological classes.
- Selective Serotonin Reuptake Inhibitors:Fluoxetine, sertraline, and escitalopram formulations dominate prescription volume through established generic availability and primary care familiarity. India's CDSCO and Brazil's ANVISA drive volume through national essential medicines lists.
- Atypical Antidepressants:Vortioxetine and brexpiprazole combinations command premium positioning through cognitive enhancement claims and differentiated reimbursement. Dutch and Swedish integrated care networks prioritize these agents for precision-guided prescribing protocols.
- Serotonin-Norepinephrine Reuptake Inhibitors:Venlafaxine and duloxetine capture expanding share among patients with comorbid chronic pain conditions.
- Tricyclic Antidepressants:Amitriptyline and nortriptyline persist in secondary care for neuropathic pain comorbidities despite cardiovascular side effect burdens.
- Monoamine Oxidase Inhibitors:Phenelzine and tranylcypromine remain restricted to specialist-managed populations due to dietary interaction requirements.
Selective Serotonin Reuptake Inhibitors anchor volume throughput; Atypical Antidepressants gain share fastest.
End User:
Facility certification requirements and reimbursement rate differentials concentrate investment in specific care settings.
- Mental Health Hospitals:Inpatient and intensive outpatient programs command the highest capital expenditure per bed for ketamine-derived therapy administration. The United States Veterans Health Administration and Kaiser Permanente systems embed depression screening into chronic disease management workflows.
- Psychiatric Clinics:Specialized REMS certification for esketamine delivery creates capacity constraints and geographic access bottlenecks. Australia's regional areas face psychiatrist workforce density gaps that strain operational scaling.
- Primary Care Centers:PHQ-9 and GAD-7 instrument standardization enables stepped-care algorithm activation without specialist referral.
- Rehabilitation Facilities:Substance use disorder comorbidity management drives antidepressant integration into recovery protocols.
- Research Institutes:Academic medical centers conduct psychedelic-assisted therapy trials under FDA Investigational New Drug protocols.
Mental Health Hospitals concentrate the heaviest infrastructure investment; Primary Care Centers are scaling fastest.
Delivery Mode:
Formulation technology and administration infrastructure determine patient adherence economics and channel control.
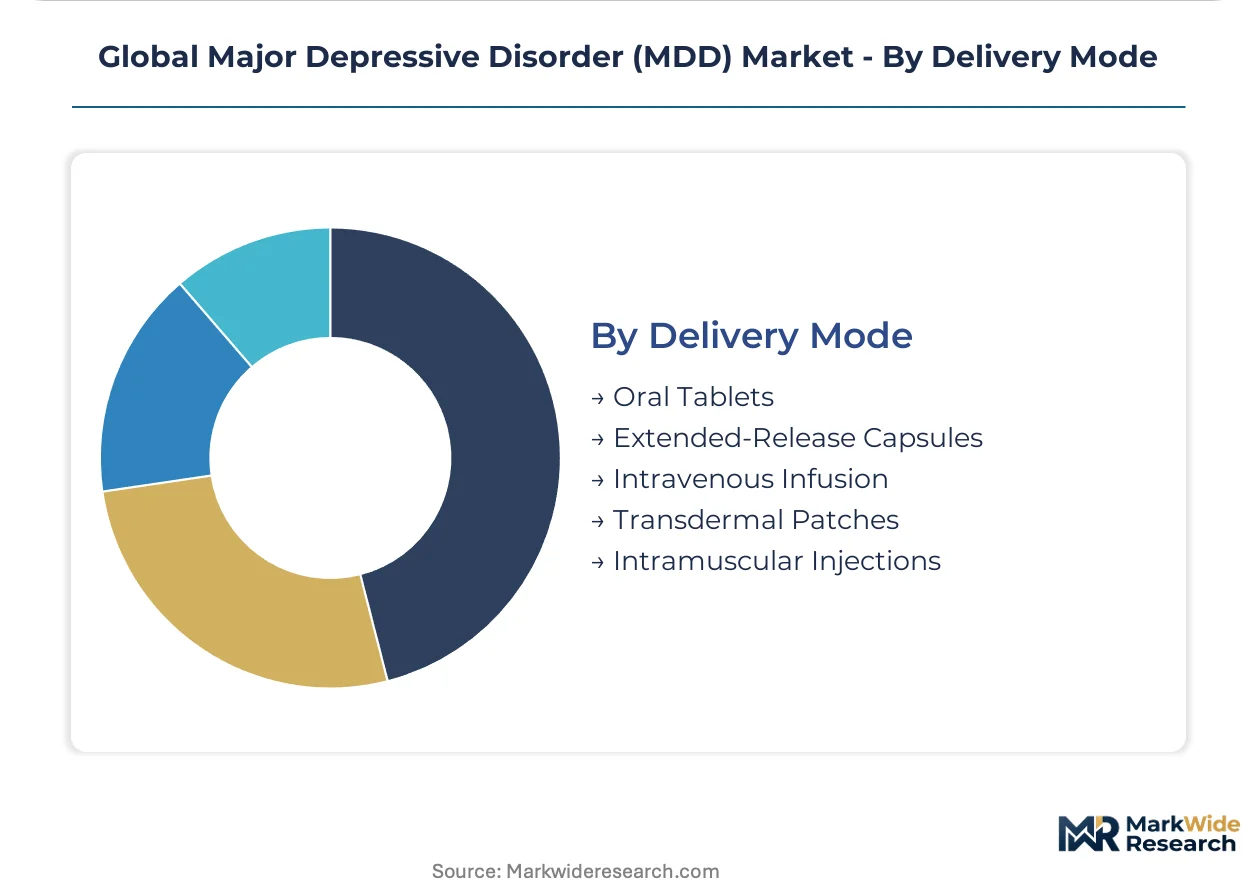
- Extended-Release Capsules:Reduced dosing frequency supports adherence program prioritization and premium pricing through convenience differentiation. Once-daily or weekly formulations minimize pill burden in employer-sponsored benefits carve-outs.
- Intravenous Infusion:Esketamine administration requires certified infusion centers with continuous monitoring capabilities. REMS infrastructure burden strains clinic operational capacity and restricts geographic accessibility.
- Oral Tablets:Immediate-release formulations maintain cost-competitive positioning in generic-saturated markets.
- Intranasal Delivery:Rapid-onset antidepressants modularize administration infrastructure through existing psychiatric clinic retrofitting.
- Transdermal Patches:Selegiline patches serve MAOI-intolerant populations with reduced dietary restriction burden.
Oral Tablets retain volume dominance; Extended-Release Capsules climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical zones in the United States concentrate clinical trial infrastructure and REMS-certified treatment centers. Germany's biotech clusters anchor European neuroscience R&D. Japan's metropolitan hospital networks drive precision psychiatry adoption.
United States
Integrated care networks embed depression screening into chronic disease management workflows. FDA Breakthrough Therapy designations compress development timelines for novel antidepressants. The Veterans Health Administration operates the largest psychiatric treatment infrastructure, with stepped-care algorithms triggering automated referral protocols.
Germany
Federal Joint Committee health technology assessments impose extended reimbursement timelines for digital therapeutics. The EU AI Act's risk classification framework shapes CE marking requirements for diagnostic software. Berlin-Brandenburg clusters host pharmacogenomic testing convergence with Dutch and Swedish care networks.
Japan
PMDA priority review vouchers accelerate market access for treatment-resistant depression candidates. METI funding supports digital phenotyping platform development. Kanto region hospitals deploy smartphone-based passive monitoring for real-time symptom tracking.
Brazil
Ministry of Health Psychosocial Care Network restructuring creates procurement scale for first-line pharmacotherapies. ANVISA national essential medicines lists drive volume for generic SSRI formulations. São Paulo's public-sector channel remains underpenetrated by extended-release formulations.
India
CDSCO national essential medicines lists prioritize cost-competitive antidepressant access. The country's central pharmaceutical regulator streamlines generic approval pathways for established SSRI molecules. Maharashtra and Gujarat manufacturing clusters supply active pharmaceutical ingredients to European formulation facilities.
Global Major Depressive Disorder (MDD) Market Competitive Landscape
Top-tier vendors anchor integrated neuroscience portfolios, while mid-cap specialists concentrate on mechanism-specific development. The vendor base stratifies across three tiers: diversified pharmaceutical conglomerates, regional generic manufacturers, and emerging biotechnology firms. Two strategic archetypes dominate: primary care channel controllers and treatment-resistant depression specialists. Competitive moves concentrate on intranasal delivery platform licensing and pharmacogenomic testing partnerships.
Within the diversified pharmaceutical tier, Eli Lilly and Company, Pfizer Inc., and Johnson & Johnson occupy positions defined by channel control and delivery innovation. Eli Lilly exemplifies atypical antidepressant development through neuroscience R&D concentration. Pfizer anchors primary care distribution networks. Johnson & Johnson represents rapid-onset delivery specialization for treatment-resistant populations.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Pfizer Inc. |
| Johnson & Johnson |
| AstraZeneca |
| Otsuka Pharmaceuticals |
| Lundbeck |
| Takeda Pharmaceutical Company Limited |
| AbbVie Inc. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Captive integration into REMS-certified infusion infrastructure anchors supply positioning for rapid-acting antidepressants while simultaneously concentrating pricing power among facility owners with certified capacity. This structural coupling between regulatory compliance and physical distribution creates tiered access economics that reward early certification investments.
Pricing Analysis
Short lead-time premiums apply to intranasal esketamine and ketamine-derived therapies requiring immediate REMS-certified facility access, while extended-release oral formulations trade at spot discounts through generic-saturated primary care channels. Three-tier pricing structure across REMS-certified specialty, standard hospital outpatient, and economy generic retail levels reflects certification burden and monitoring intensity. Pricing pressure stems from India's CDSCO and Brazil's ANVISA driving volume through national essential medicines lists. Employer-sponsored benefits carve-outs show lowest price sensitivity; uninsured cash-pay patients in rural United States counties face highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Maharashtra and Gujarat manufacturing clusters supplying active pharmaceutical ingredients for SSRI and SNRI formulations to European and North American finishers. API production draws from India, China, and selected Italian facilities for atypical antidepressant precursors. Key inputs include serotonin precursor chemicals, specialized coating polymers for extended-release formulations, and nasal delivery device components. Tariff exposure on Chinese-sourced intermediates creates margin compression risk. Distribution runs through REMS-certified specialty pharmacy networks for controlled substances, with primary care wholesale channels handling standard oral generics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Risk Evaluation and Mitigation Strategy requirements erect a cost-of-compliance moat that protects certified infrastructure owners while excluding undercapitalized entrants from the treatment-resistant depression segment.
For Market Incumbents: Deploy pharmacogenomic testing partnerships as a defensive lever against precision-medicine challengers. Consolidate REMS-certified facility networks through selective acquisition of distressed psychiatric clinics facing certification renewal costs. Channel control investments in employer-sponsored benefits carve-outs offset primary care generic erosion. For New Entrants and Emerging Players: Digital phenotyping platforms offer a technology-first wedge into stepped-care protocols preceding pharmacological intervention. Brazil's public-sector Psychosocial Care Network restructuring presents the most penetrable geography for extended-release formulation tenders. Partner with Dutch and Swedish integrated care networks for pharmacogenomic-guided prescribing validation. For Investors and Strategic Acquirers: Exit pathways concentrate in platform licensing deals to diversified pharmaceutical conglomerates seeking neuroscience R&D augmentation. Five-to-ten year viability hinges on psychedelic-assisted therapy regulatory pathway maturation. Monitor FDA Breakthrough Therapy designation velocity as the critical inflection signal for mechanism-class revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Expansion | Facility certification investments capture geographic exclusivity in treatment-resistant depression administration. |
| Pharmacogenomic Testing Integration | CYP2D6/CYP2C19 genotyping partnerships with Dutch care networks enable precision-guided premium positioning. |
| Employer Benefits Carve-Out | Direct contracting with self-insured employers bypasses traditional pharmacy benefit manager formulary controls. |
| Digital Phenotyping Platform Launch | Smartphone-based passive monitoring tools secure stepped-care algorithm placement before antidepressant initiation. |
| Psychedelic-Assisted Therapy Pipeline | FDA Investigational New Drug protocol advancement builds optionality for regulatory pathway displacement of conventional antidepressants. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for regulatory pathway and pipeline status validation. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers supplied forward-looking commercial intelligence. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Historical trendline analysis of SSRI and SNRI prescription patterns informed patient flow assumptions across the projection horizon. Segmentation dimensions included treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs derived from patent expiry schedules, biosimilar entry timelines, and reimbursement trajectory modeling. Forecast inputs incorporated FDA Breakthrough Therapy designation velocity and employer-sponsored benefits adoption curves.
Several conditions sit outside the modeled scope, including psychedelic-assisted therapy full regulatory approval timelines and national health system restructuring outcomes in emerging markets. Forecasts reflect documented assumptions regarding psychiatrist workforce density and REMS infrastructure expansion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Bronchiectasis Therapeutic Market