
 Combined Immune Deficiency (CID) Market | 2026-2036
Combined Immune Deficiency (CID) Market Size, Share, and Industry Trends Forecast 2026-2036
Combined Immune Deficiency (CID) Market Analytics
Modular dosing configurations for immunoglobulin replacement is broadening buyer choice across home care and hospital settings. Baxter International leverages its plasma fractionation scale to sustain supply security for chronic CID patients. CSL Behring anchors its position through vertically integrated plasma collection networks spanning multiple continents. Grifols competes on manufacturing throughput, operating some of the largest production facilities serving European and North American demand.
Combined Immune Deficiency comprises a heterogeneous group of genetic disorders impairing both adaptive and innate immune function, typically requiring lifelong immunoglobulin infusion or hematopoietic stem cell intervention to prevent recurrent opportunistic infections. Immunoglobulin Therapy dominates current revenue flows due to established reimbursement pathways and decades of clinical validation, while Gene Therapy represents the fastest-expanding segment as lentiviral and CRISPR-based platforms advance through pivotal trials. Pediatric Applications command premium pricing supported by orphan drug designations, though Adult indications are deepening as diagnostic screening expands beyond infancy.
FDA orphan drug incentives and EMA's PRIME designation framework accelerate market access for novel CID therapeutics, compressing development timelines for gene and cell therapy developers. The EU's ATMP Regulation and Japan's PMDA regenerative medicine policies establish divergent compliance burdens that manufacturers must navigate for multi-territory launches. Stakeholders should monitor real-world evidence requirements from national health technology assessment bodies, as these criteria increasingly determine reimbursement and adoption velocity for transformative modalities.
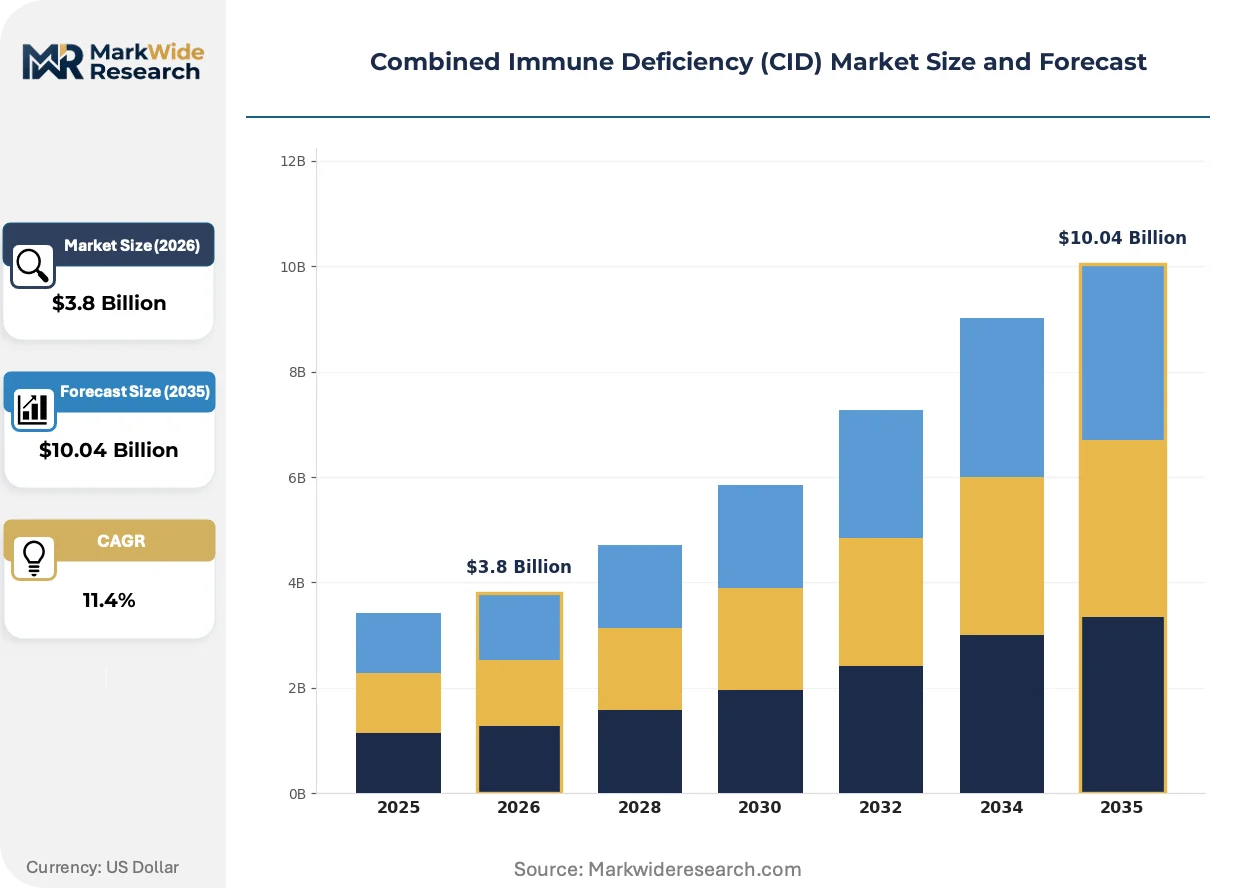
Market Dynamics
Gene therapy platform maturation is compressing development timelines for curative CID interventions while reshaping capital allocation across plasma-derived and biologic manufacturing footprints.
Growth Catalysts
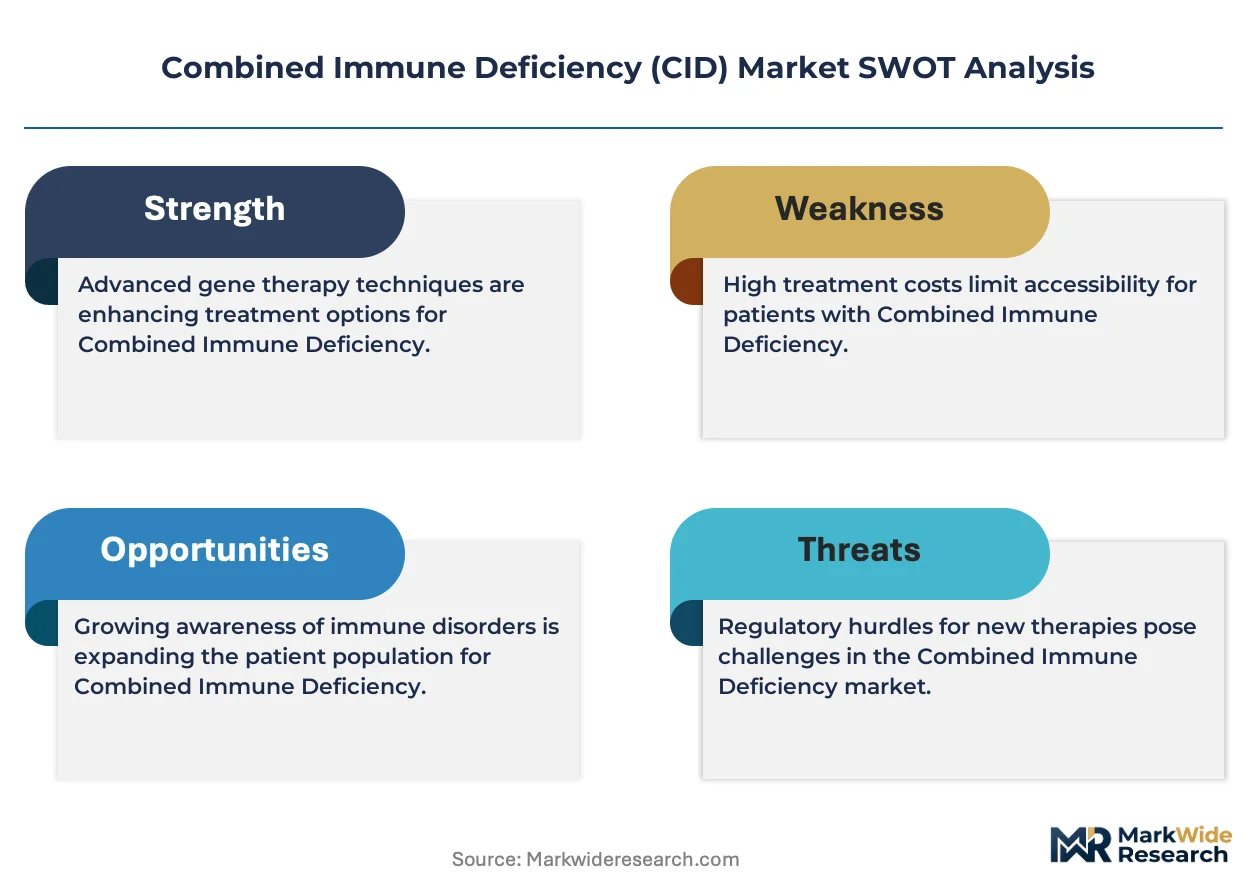
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate pivotal trial investment for rare immunodeficiency indications.
- Home Infusion Infrastructure:Subcutaneous immunoglobulin delivery systems expand patient-managed care models beyond hospital-centric administration.
- Neonatal Screening Expansion:State-level newborn screening programs in the United States identify SCID and related CID variants earlier, extending treatment windows.
Market Restraints
- Plasma Supply Concentration:North American and European collection networks dominate raw material sourcing for immunoglobulin fractionation.
- EMA ATMP Compliance Burden:Advanced therapy medicinal product classification imposes costly manufacturing and pharmacovigilance requirements on gene therapy developers.
- Allogeneic Stem Cell Limitations:Donor matching constraints and graft-versus-host risk restrict hematopoietic transplant applicability.
Strategic Opportunities
- Japan Regenerative Medicine Framework:Conditional approval pathways under PMDA guidance compress time-to-market for autologous gene-modified cell therapies.
- CRISPR-Lentiviral Convergence:Dual-platform editing and delivery systems enable precision targeting of IL2RG and RAG1 mutations.
- Specialized Treatment Center Networks:Hub-and-spoke referral models in Germany concentrate patient volume for complex diagnostic and therapeutic protocols.
Industry Challenges
- Gene Therapy Manufacturing Scale-Up:Viral vector production capacity constraints limit batch sizes for lentiviral-based CID treatments.
- Real-World Evidence Collection:Payer requirements for long-term durability data extend post-approval study obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combined Immune Deficiency (CID) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Stem Cell Therapy, Enzyme Replacement Therapy, Immunoglobulin Therapy Application: Pediatrics, Adults, Clinical Research, Emergency Care End User: Hospitals, Specialty Clinics, Research Facilities, Home Care Delivery Mode: Intravenous, Subcutaneous, Intraosseous, Oral |
| Companies Covered | Baxter International, CSL Behring, Grifols, Octapharma, Kedrion Biopharma, LFB, Takeda Pharmaceutical, ADMA Biologics, Biotest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combined Immune Deficiency (CID) Market Evolving Landscape
Platform standardization across viral vector manufacturing is compressing unit economics while regulatory convergence on gene therapy quality standards accelerates multi-territory filing strategies.
Lentiviral vector production is consolidating around suspension-adapted cell line platforms. Contract development and manufacturing organizations in the United States and Switzerland are adopting chemically defined media formulations to reduce lot-to-lot variability. This consolidation is enabling single-source supply agreements for pivotal trial material.
EMA's PRIME designation framework compresses scientific advice timelines for advanced therapy developers. Manufacturers receive accelerated assessment pathways and enhanced regulatory dialogue access. Gene therapy sponsors targeting IL2RG-deficient SCID variants leverage this mechanism to align CMC development with clinical milestones.
Hospital procurement committees now require health technology assessment dossiers prior to immunoglobulin contract renewal. Pediatric centers in Germany and academic medical centers in the United States prioritize real-world infection rate data over historical clinical trial endpoints. This behavioral shift pressures manufacturers to invest in patient registry infrastructure.
Combined Immune Deficiency (CID) Market Segmentation
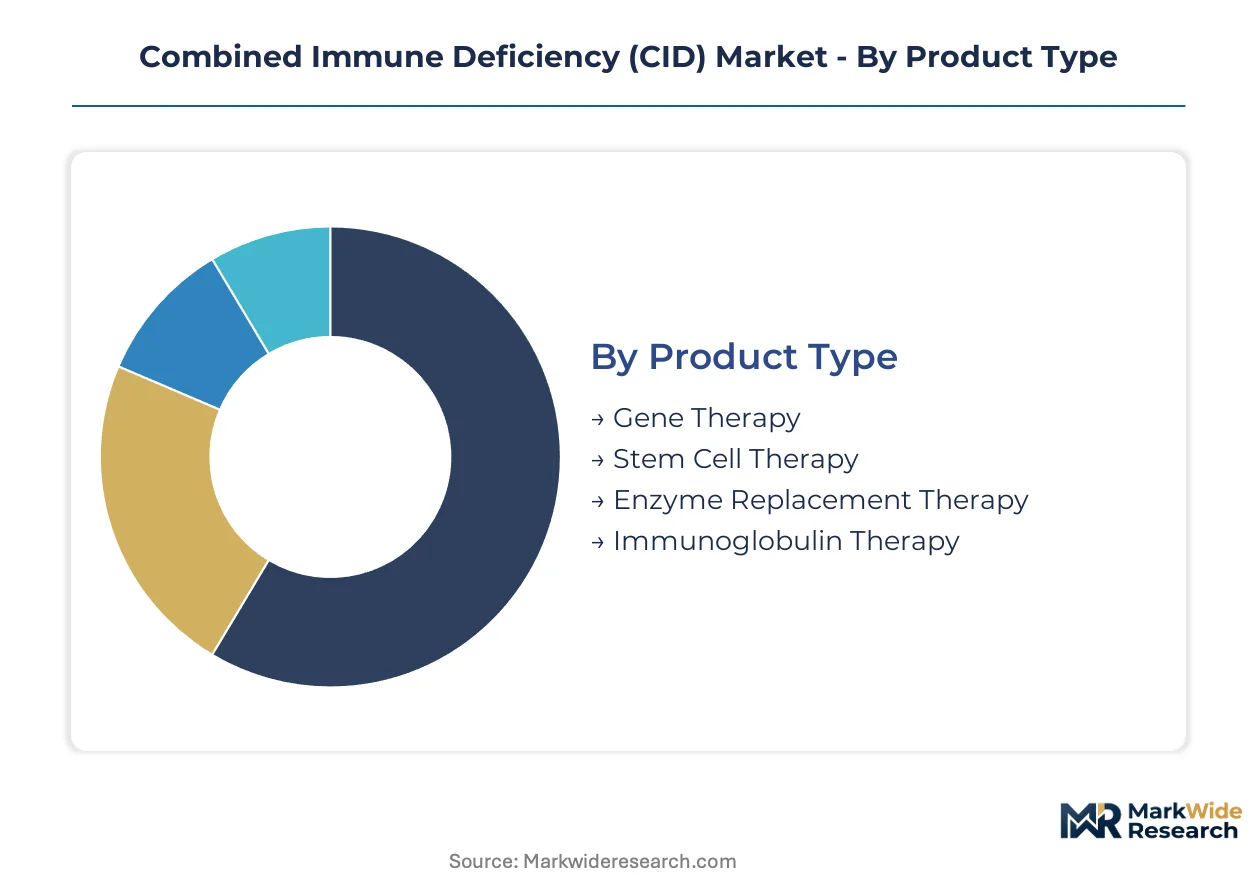
CID treatment modalities span curative versus chronic management paradigms, with each segment demanding distinct manufacturing capabilities, reimbursement frameworks, and patient access infrastructure. Understanding these divides reveals where capital deployment concentrates and which platforms reshape competitive boundaries.
Product Type:
Gene Therapy and Stem Cell Therapy demand billion-dollar manufacturing investments and dedicated viral vector facilities, while established plasma fractionation for Immunoglobulin Therapy operates at depreciated scale.
- Gene Therapy:Lentiviral and CRISPR-based platforms target IL2RG and RAG1 mutations with potential single-dose curative outcomes. United States-based developers leverage FDA accelerated approval pathways to compress clinical timelines for SCID variants.
- Immunoglobulin Therapy:Plasma-derived IgG formulations require sustained fractionation capacity and secure raw material sourcing. Hospital procurement committees in Germany and Japan prioritize supply security over unit cost for chronic pediatric patients.
- Stem Cell Therapy:Allogeneic and autologous hematopoietic interventions face donor matching constraints.
- Enzyme Replacement Therapy:Adjunctive modalities address metabolic complications in select CID subtypes.
Immunoglobulin Therapy absorbs the bulk of installed capacity; Gene Therapy is expanding most quickly.
Application:
Pediatric cases command premium orphan drug pricing and concentrated treatment center referral patterns, while Adult indications deepen as newborn screening extends diagnostic capture beyond infancy.
- Pediatrics:Neonatal SCID screening programs in the United States identify patients requiring immediate intervention. Academic medical centers anchor specialized care networks with dedicated immunology units.
- Adults:Late-diagnosed CID variants and transition-of-care patients from pediatric programs drive sustained immunoglobulin demand. German referral hospitals manage complex adult cases through hub-and-spoke models.
- Clinical Research:Natural history studies and gene therapy trials require dedicated patient registries.
- Emergency Care:Acute infection management in undiagnosed patients presents diagnostic challenges.
Pediatrics captures the dominant revenue share; Adults are climbing the fastest as diagnostic thresholds broaden.
End User:
Hospital-based administration retains reimbursement advantages for intravenous immunoglobulin, while Home Care infrastructure expands for subcutaneous self-administration.
- Hospitals:Tertiary centers concentrate gene therapy administration and stem cell transplant protocols. Japanese designated cancer hospitals anchor regional CID treatment networks under PMDA oversight.
- Home Care:Subcutaneous immunoglobulin delivery systems enable patient-managed chronic replacement. United States payers increasingly mandate home infusion to reduce hospital cost burdens.
- Specialty Clinics:Immunology-focused outpatient facilities manage stable chronic patients.
- Research Facilities:Academic centers conduct pivotal gene therapy trials and long-term follow-up studies.
Hospitals retain the majority of high-acuity procedures; Home Care is gaining share fastest as delivery technology matures.
Delivery Mode:
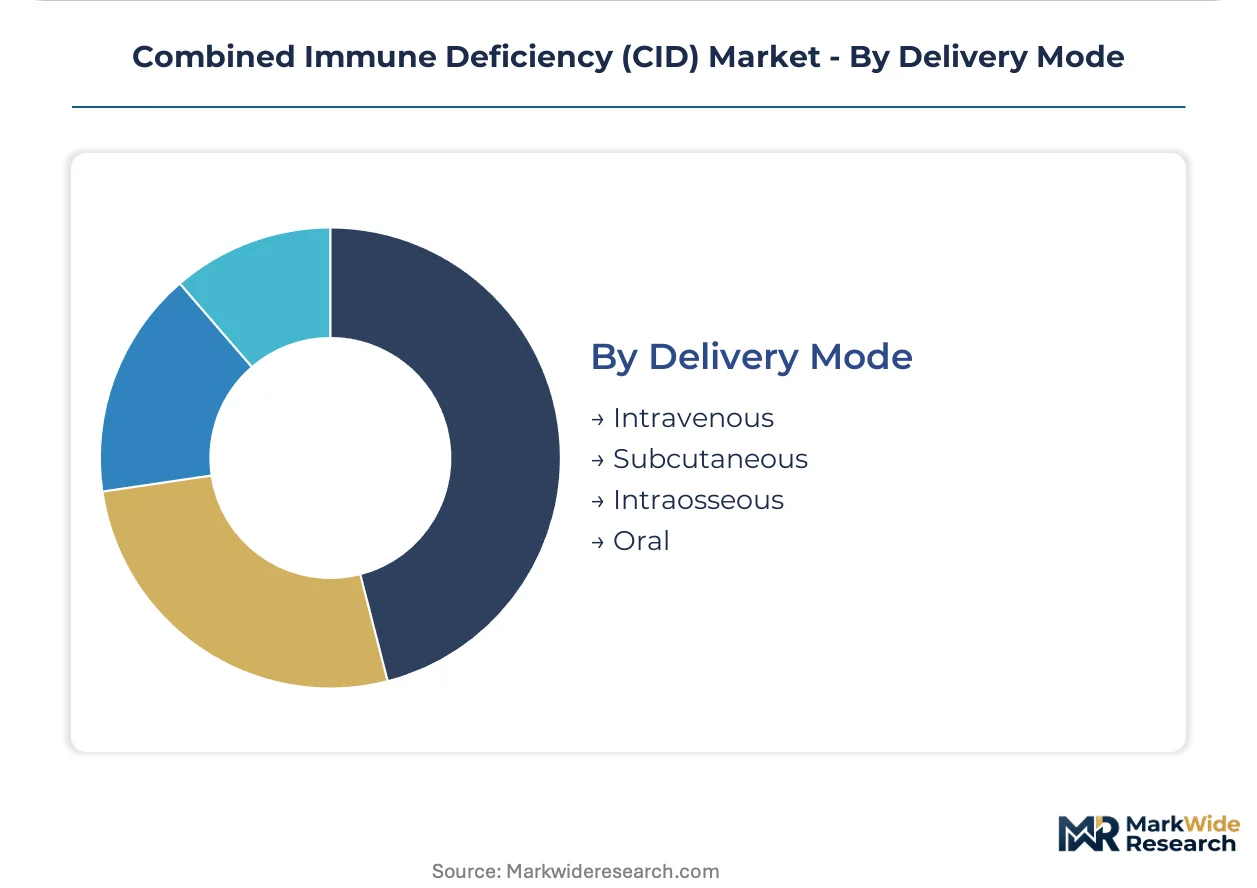
Intravenous administration requires clinical infrastructure and trained nursing, whereas Subcutaneous formats shift cost structures toward patient training and device supply.
- Intravenous:Monthly high-dose immunoglobulin infusions dominate hospital outpatient schedules. Plasma fractionators optimize 10% and 20% concentration formulations for infusion center throughput.
- Subcutaneous:Weekly low-volume self-administration reduces systemic adverse event profiles. German home care nursing networks support patient training for subcutaneous immunoglobulin transitions.
- Intraosseous:Emergency vascular access for acute sepsis in undiagnosed infants.
- Oral:Limited applicability for CID due to protein degradation in gastrointestinal tract.
Intravenous maintains the largest patient volume base; Subcutaneous shows the steepest expansion trajectory as home care infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation capacity concentrates in the United States and Germany while patient demand spreads across high-income markets with specialized immunology infrastructure. Consumption patterns diverge sharply between chronic immunoglobulin replacement markets and emerging gene therapy access corridors.
United States
FDA orphan drug incentives and accelerated approval pathways compress development timelines for SCID gene therapies. Newborn screening programs in all states identify CID variants within days of birth, extending treatment windows. Boston and Philadelphia anchor specialized treatment networks where academic medical centers conduct pivotal lentiviral vector trials.
Germany
Hub-and-spoke referral models concentrate complex CID cases in university hospitals across Bavaria and North Rhine-Westphalia. EMA's PRIME designation framework provides accelerated scientific advice for advanced therapy developers targeting IL2RG mutations. Frankfurt and Munich house dedicated immunology centers managing both pediatric transitions and adult late diagnoses.
Japan
PMDA's regenerative medicine framework enables conditional approval pathways for autologous gene-modified cell therapies. Designated cancer hospitals anchor regional CID treatment networks under centralized oversight. Tokyo and Osaka academic centers lead natural history studies supporting gene therapy durability claims.
United Kingdom
NHS specialized commissioning routes immunoglobulin procurement through designated immunology centers in London and Manchester. MHRA alignment with EMA ATMP standards streamlines multi-territory filing for gene therapy sponsors. Cambridge and Oxford research clusters advance CRISPR editing platforms for RAG1-deficient variants.
Switzerland
Swissmedic's streamlined ATMP assessment procedures attract gene therapy developers seeking European market entry. Basel and Zurich host contract manufacturing organizations producing chemically defined media for viral vector suspension platforms. The country's central European location supports distribution logistics for plasma-derived products.
Combined Immune Deficiency (CID) Market Competitive Landscape
The competitive structure tilts toward plasma fractionation specialists with depreciated manufacturing scale. Three tiers separate global plasma collectors with captive supply networks from regional fractionators and emerging gene therapy platforms. Dominant competitive moves center on backward integration into plasma collection and strategic partnerships for viral vector manufacturing capacity.
Among plasma-derived therapy specialists, Baxter International, CSL Behring, and Grifols occupy positions defined by manufacturing throughput and collection network reach. Baxter represents the hospital supply security archetype with established fractionation infrastructure. CSL Behring exemplifies vertical control spanning multiple continents. Grifols anchors the European-North American demand corridor through large-scale production facilities. These three collectively illustrate how raw material access and manufacturing scale determine competitive position in chronic replacement markets.
| Leading Market Players |
|---|
| Baxter International |
| CSL Behring |
| Grifols |
| Octapharma |
| Kedrion Biopharma |
| LFB |
| Takeda Pharmaceutical |
| ADMA Biologics |
| Biotest |
| Others |
Value Network & Pricing Analysis
Plasma collection labor costs in the United States cascade through fractionation economics into three-tier pricing structure across premium, standard, and economy levels for immunoglobulin therapies, with German hospital procurement committees absorbing premium tiers for pediatric orphan indications while home care payers in Japan drive cost-down negotiations on subcutaneous formulations.
Pricing Analysis
Margin tightening in standard-tier immunoglobulin reflects volume concentration among plasma fractionators competing on manufacturing throughput. Pricing stratifies across premium, standard, and economy tiers based on concentration formulation and supply security guarantees, with pediatric orphan designations commanding least price sensitivity and adult chronic replacement facing greatest payer pressure. Cost compression in economy-tier subcutaneous products accelerates because United States insurers mandate home infusion to reduce hospital cost burdens.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees in Germany and Japan mandate qualified suppliers across both North American and European plasma collection networks. Raw material sourcing draws from United States, Germany, and Austria collection centers, with viral vector production capacity resting on Swiss and United States contract manufacturing organizations. Single-source vulnerability in lentiviral vector batch production constrains gene therapy scale-up, while distribution runs through cold-chain logistics to tertiary immunology centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's ATMP Regulation and FDA's gene therapy CMC guidance erect compliance moats that favor incumbents with dedicated viral vector facilities and established pharmacovigilance infrastructure, raising capital thresholds for market entry.
For Market Incumbents: Deepen backward integration into plasma collection networks to secure raw material supply against emerging gene therapy substitution threats. Expand viral vector manufacturing capacity in Switzerland or United States to capture pivot trial demand from CRISPR-lentiviral convergence platforms. Certification investment in EMA's PRIME designation framework accelerates scientific advice access for IL2RG-targeted programs. For New Entrants and Emerging Players: Enter via Japan's PMDA conditional approval pathway for autologous gene-modified cell therapies, where regenerative medicine policies compress time-to-market relative to EMA or FDA routes. Target adult late-diagnosed CID variants in German hub-and-spoke referral networks, where diagnostic expansion outpaces pediatric screening saturation. A hospital system partnership model with academic medical centers in Boston or Philadelphia anchors credibility for pivotal trial recruitment. For Investors and Strategic Acquirers: First FDA accelerated approval for a lentiviral-based SCID gene therapy is the leading indicator that curative modality economics will displace chronic immunoglobulin replacement volumes over a multi-year horizon. Acquisition target archetype: mid-cap gene therapy developers with IL2RG or RAG1 pipeline assets and existing CMC relationships with Swiss or United States viral vector manufacturers. Watch for real-world evidence requirements from Germany's IQWiG or England's NICE as signals of reimbursement velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pivotal lentiviral vector trials for IL2RG-deficient SCID variants anchor curative modality credibility. |
| Regulatory Approval Pathway | EMA's PRIME designation compresses scientific advice timelines for advanced therapy medicinal products. |
| Manufacturing Scale-Up | Suspension-adapted cell line platforms at Swiss and United States CDMOs reduce viral vector lot-to-lot variability. |
| Long-term Supply Agreement | Single-source plasma supply contracts with German hospital procurement committees secure chronic replacement revenue. |
| Reimbursement Strategy | Real-world infection rate data from patient registries satisfies England's NICE and Germany's IQWiG durability requirements. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for pipeline and regulatory tracking, supplemented by formulary database reviews and hospital procurement records. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated commercial assumptions. Bottom-up patient volume estimates and top-down plasma fractionation capacity analysis were triangulated against immunoglobulin demand forecasts.
Historical trendline analysis of immunoglobulin pricing and gene therapy development timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include treatment modality, patient population, administration route, and regional regulatory cluster. CAGRs were derived from epidemiological expansion, newborn screening penetration rates, and manufacturing capacity buildout schedules for viral vector platforms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gene therapy durability failures or plasma supply disruptions. Forecasts reflect documented assumptions on regulatory approval timelines and reimbursement adoption curves. Deviation in EMA ATMP inspection outcomes or PMDA conditional approval renewal criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Carcinoid Syndrome Management Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market