
 Pseudobulbar Treatment Market | 2026-2036
Pseudobulbar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pseudobulbar Treatment Market Analytics
Premium branded dextromethorphan-quinidine combinations and commodity generic antidepressants are decoupling on reimbursement and prescriber loyalty. Avanir Pharmaceuticals anchors the branded segment through orphan exclusivity and specialty pharmacy distribution. Pfizer competes via its neurology portfolio breadth and hospital formulary relationships. Dr. Reddy's Laboratories positions in the generic antidepressant tier with cost-focused manufacturing scale.
Pseudobulbar affect treatment addresses involuntary emotional outbursts through NMDA receptor antagonism and sigma-1 agonism, with the dextromethorphan-quinidine pairing requiring precise metabolic inhibition to achieve therapeutic plasma levels. The oral delivery mode dominates prescription volumes due to patient self-administration convenience, while injectable formats capture the inpatient and emergency settings where rapid symptom control proves critical. Home care end users represent the fastest-expanding segment as payors push post-acute management outside institutional walls.
FDA orphan drug incentives and EMA's centralized pediatric investigation plans shape developer pipelines and trial design requirements for novel pseudobulbar affect therapies. The FDA's Breakthrough Therapy designation pathway accelerates review timelines for candidates demonstrating substantial improvement over existing dextromethorphan-quinidine regimens. Stakeholders must monitor CMS national coverage determination proceedings for neuropsychiatric indications, as these rulings will dictate whether home-based administration achieves sustainable reimbursement parity with clinic-infused alternatives.
Market Dynamics
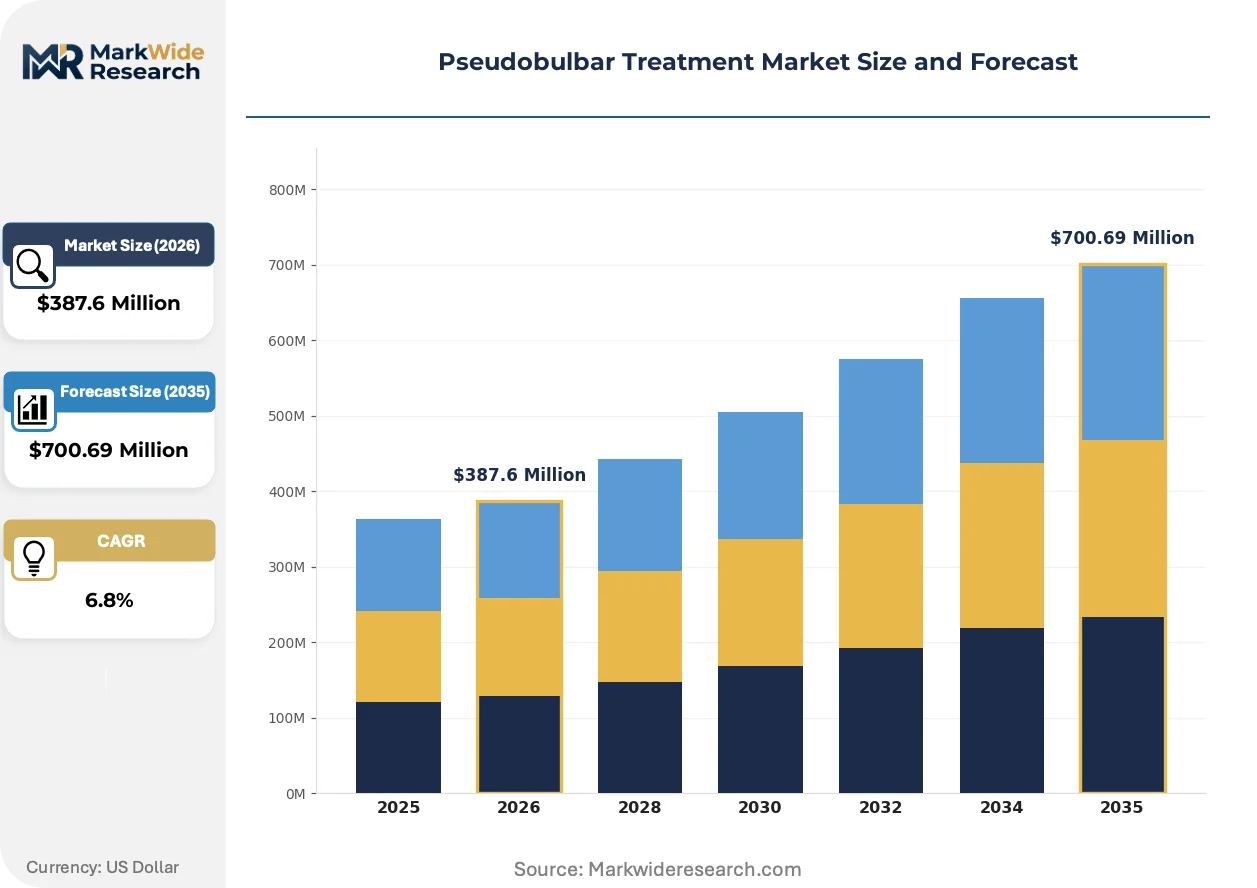
Orphan drug exclusivity windows and CMS reimbursement determinations for home-based neuropsychiatric administration are restructuring competitive positioning across the pseudobulbar treatment landscape. Developers now sequence clinical programs around regulatory incentive capture rather than traditional therapeutic category expansion.
Growth Catalysts
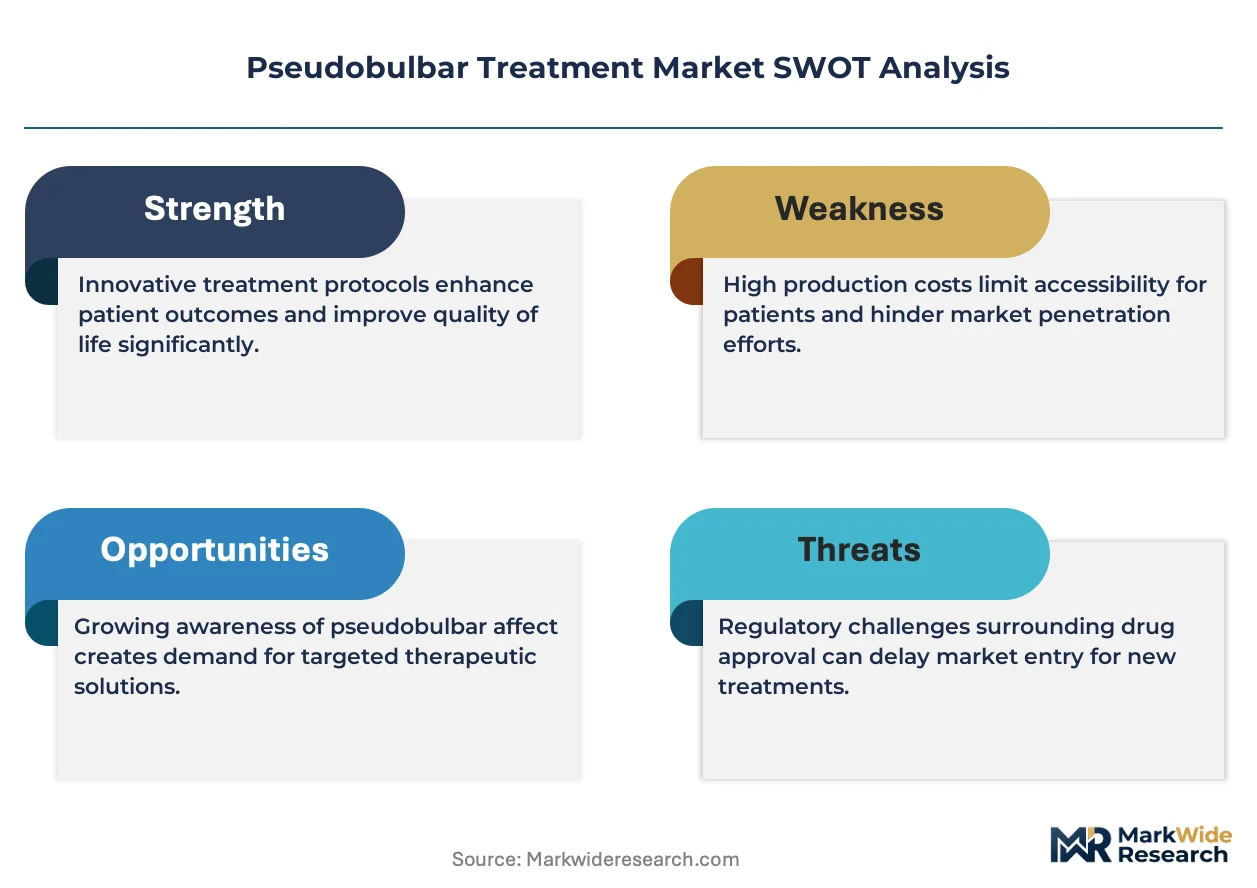
- FDA Breakthrough Therapy pathway:Accelerated review timelines for candidates demonstrating substantial improvement over dextromethorphan-quinidine standards compress development-to-commercialization cycles.
- Home care end-use expansion:Post-acute management migration outside institutional walls creates demand for oral self-administration formats with stable outpatient reimbursement.
- EMA centralized pediatric investigation plans:Harmonized trial design requirements streamline multi-jurisdictional development for juvenile-onset neurological indications.
Market Restraints
- Specialty pharmacy distribution concentration:Limited-channel access for branded orphan therapies creates bottleneck risk and patient access friction.
- Generic antidepressant substitution pressure:Commodity SSRI and tricyclic alternatives at substantially lower acquisition costs displace formulary positioning for mechanism-specific therapies.
- CYP2D6 metabolic variability:Precision dosing requirements for quinidine-mediated dextromethorphan potentiation complicate standardized prescribing protocols.
Strategic Opportunities
- Long-acting injectable formulations:Depot delivery technologies addressing adherence gaps in movement disorder populations with cognitive comorbidities.
- Digital therapeutic adjuncts:Smartphone-based symptom monitoring paired with pharmacotherapy for real-world evidence generation and payor contracting.
- Japan PMDA orphan drug framework:Sakigake designation and priority review vouchers for novel mechanisms in amyotrophic lateral sclerosis-associated emotional lability.
Industry Challenges
- Biomarker-validated endpoint development:Regulatory acceptance of objective pseudobulbar affect severity measures beyond clinician-reported scales remains inconsistent across FDA and EMA.
- Specialty pharmacy credentialing timelines:REMS-compliant distribution network expansion requires 18-24 month accreditation cycles that constrain launch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pseudobulbar Treatment Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dextromethorphan, Quinidine, Opioids, Antidepressants End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Delivery Mode: Oral, Injectable, Transdermal, Inhalation Treatment Setting: Outpatient, Inpatient, Long-term Care, Emergency |
| Companies Covered | Avanir Pharmaceuticals, Inc., Pfizer Inc., Bayer AG, Dr. Reddy’s Laboratories Ltd., F. Hoffmann-La Roche Ltd., GlaxoSmithKline plc, Novartis AG, Sanofi, Otsuka Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pseudobulbar Treatment Market Evolving Landscape
Neuropharmacology development is pivoting toward precision receptor targeting and delivery format diversification, with developers exploring alternatives to the established metabolic inhibition approach.
Extended-release dextromethorphan formulations with novel quinidine-sparing CYP inhibition strategies are consolidating competitive positioning among developers seeking to reduce cardiovascular liability profiles. Tertiary care movement disorder programs are piloting these candidates in head-to-head protocols against existing standards. The technology is consolidating development priorities around safety differentiation rather than efficacy superiority alone.
EMA's expanded orphan drug maintenance fee structure and pediatric investigation plan enforcement are tightening compliance requirements for developers with centralized European filings. Sponsors must now commit to post-authorization pediatric study completion timelines as a condition of market exclusivity retention. Small-cap neurology specialists with limited regulatory affairs infrastructure face disproportionate resource allocation pressure.
Hospital formulary committees are unbundling neuropsychiatric pharmacy benefits from bundled neurology service contracts, creating direct therapeutic category competition at the point of admission. This purchasing autonomy shift enables mechanism-specific therapy selection independent of historical antidepressant prescribing patterns. The change is most pronounced in United States academic medical centers with dedicated ALS and multiple sclerosis centers of excellence.
Pseudobulbar Treatment Market Segmentation
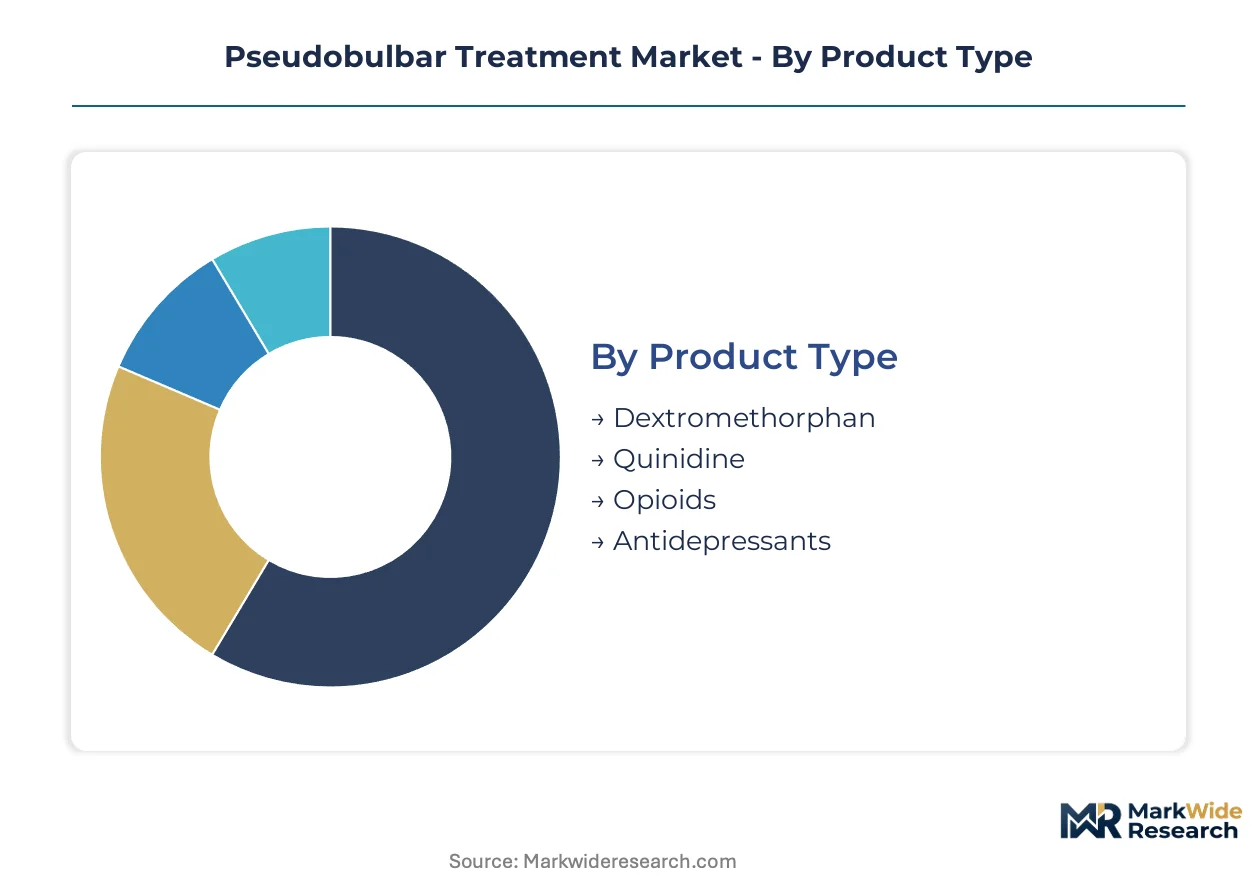
Pseudobulbar treatment segmentation reveals how therapeutic mechanisms, care settings, and administration formats intersect to shape prescribing economics. Each dimension carries distinct reimbursement profiles and patient adherence implications that influence developer portfolio priorities.
Product Type:
Upgrade cycles in this category track patent cliffs and orphan exclusivity expirations rather than traditional product lifecycles.
- Dextromethorphan:The NMDA receptor antagonist requires metabolic potentiation to achieve therapeutic plasma concentrations for pseudobulbar affect suppression. ALS and multiple sclerosis centers in the United States concentrate prescription volume as movement disorder specialists favor mechanism-specific targeting over symptomatic alternatives.
- Quinidine:CYP2D6 inhibition at sub-antiarrhythmic doses enables dextromethorphan bioavailability but introduces cardiovascular monitoring requirements that complicate outpatient protocols. Tertiary neurology programs absorb the liability through embedded cardiology consultation pathways.
- Opioids:Morphine and codeine derivatives retain niche positioning for refractory emotional lability in palliative care settings where sedation tolerance exists.
- Antidepressants:SSRIs and tricyclics compete on acquisition cost in markets where mechanism specificity carries limited formulary premium.
Antidepressants sit at the top of the volume ranking, with dextromethorphan climbing the fastest as orphan-designated combinations expand prescriber familiarity.
End User:
Cost tier stratification separates institutional purchasers with bundled neurology contracts from fragmented outpatient reimbursement pathways.
- Hospitals:Academic medical centers with dedicated ALS and MS centers of excellence anchor branded therapy adoption through embedded movement disorder specialists and pharmacy therapeutics committees.
- Home Care:Post-acute management migration outside institutional walls creates demand for oral self-administration formats with sustainable outpatient reimbursement under Medicare Part D and commercial pharmacy benefits.
- Rehabilitation Centers:Skilled nursing facilities with neurology-focused subacute programs represent a contracting channel as length-of-stay compression limits medication optimization windows.
- Clinics:Community neurology practices in the United States drive generic antidepressant volume through primary care referral pathways with limited mechanism-specific diagnostic penetration.
Home care sits at the top of the volume ranking, with hospitals climbing the fastest as bundled payment models incentivize readmission prevention through effective symptom control.
Delivery Mode:
Application requirements differentiate acute intervention formats from maintenance regimens in chronic neurodegenerative populations.
- Oral:Immediate-release and extended-release tablet formulations dominate prescription volumes due to patient self-administration convenience and established specialty pharmacy distribution infrastructure.
- Injectable:Intramuscular and intravenous formats capture inpatient and emergency department settings where rapid symptom control proves critical for patient safety and staff workflow efficiency.
- Transdermal:Patch-based delivery remains developmental for pseudobulbar indications, with absorption variability across dermal conditions in elderly and cachectic patient populations presenting formulation challenges.
- Inhalation:Nebulized and dry powder approaches occupy preclinical exploration for patients with compromised swallowing function in advanced ALS stages.
Oral delivery sits at the top of the volume ranking, with injectable climbing the fastest as hospital-based neurology services expand observation protocols.
Treatment Setting:
Maturity gradients separate established outpatient management from emerging long-term care protocols in institutionalized neurodegenerative populations.
- Outpatient:Neurology clinic and home-based administration represents the commercial core, with Medicare coverage determinations for neuropsychiatric indications dictating sustainable access economics.
- Inpatient:Hospital admission triggers mechanism-specific therapy selection independent of historical antidepressant prescribing patterns as formulary committees unbundle pharmacy benefits from bundled service contracts.
- Long-term Care:Nursing facility protocols increasingly incorporate pseudobulbar affect screening as part of standardized dementia and movement disorder assessment batteries.
- Emergency:Emergency department utilization concentrates in academic medical centers with dedicated neuropsychiatric consultation services and established rapid sedation alternatives.
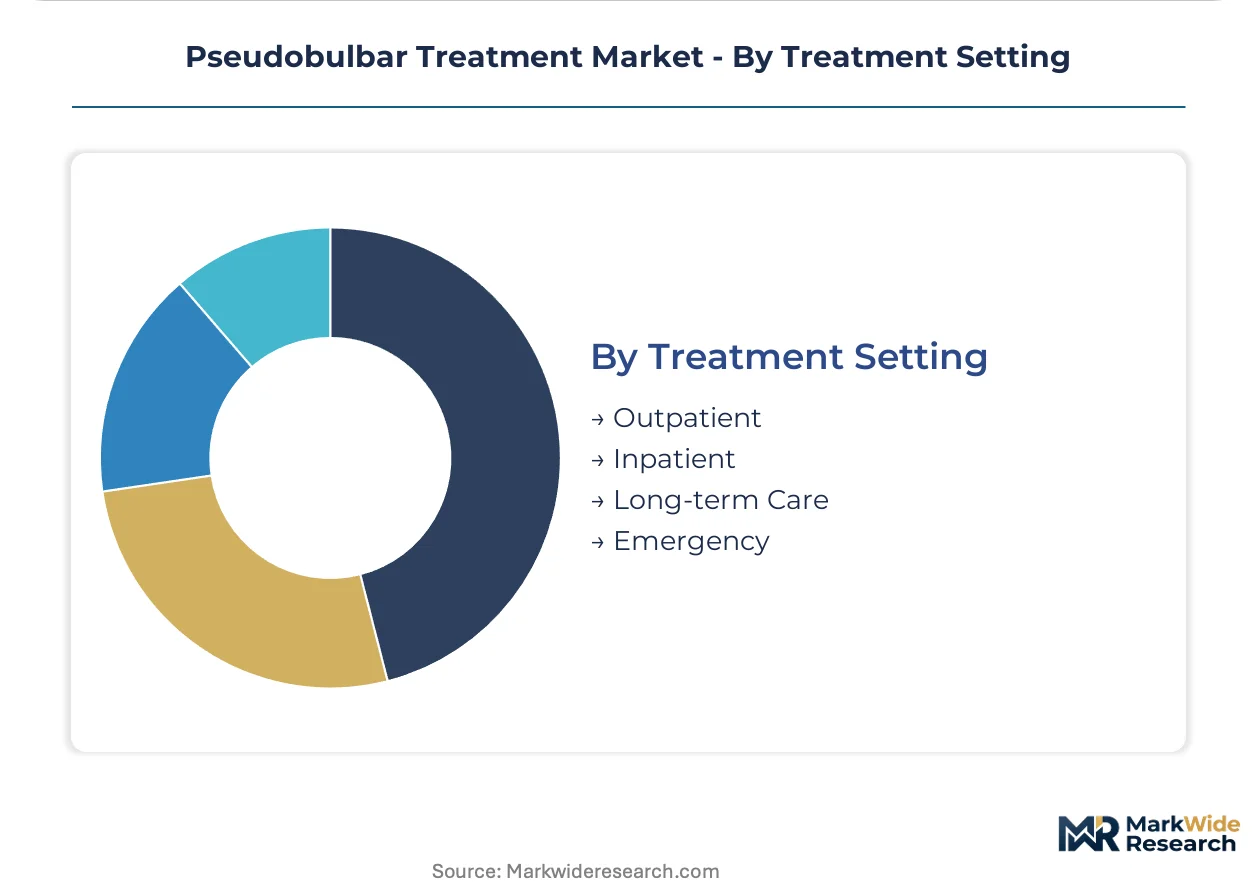
Outpatient settings sit at the top of the volume ranking, with long-term care climbing the fastest as payor pressure drives post-acute management outside hospital walls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurology specialists cluster in tertiary care corridors across five countries where movement disorder programs drive pseudobulbar affect therapy adoption. Each geography shapes demand through distinct regulatory pathways and institutional purchasing patterns.
United States
FDA orphan drug incentives accelerate developer timelines while Medicare Part D reimbursement structures dictate outpatient access economics. The agency's Breakthrough Therapy designation compresses review cycles for novel formulations. Boston and Cleveland anchor prescription volume through embedded ALS and multiple sclerosis centers of excellence.
Germany
EMA centralized procedures harmonize pediatric investigation requirements across member states while hospital formulary committees unbundle pharmacy benefits from neurology service contracts. The country's statutory health insurance funds negotiate mechanism-specific therapy coverage. Heidelberg and Munich concentrate movement disorder specialist density in academic medical networks.
Japan
PMDA Sakigake designation and priority review vouchers attract developers targeting amyotrophic lateral sclerosis-associated emotional lability. METI coordinates orphan drug framework implementation with national health technology assessment timelines. Tokyo and Osaka host the tertiary neurology programs piloting novel receptor-targeting candidates.
United Kingdom
NICE technology appraisals determine NHS England coverage for dextromethorphan-quinidine combinations against generic antidepressant alternatives. The MHRA operates post-Brexit recognition procedures with FDA and EMA. London and Manchester anchor prescription volume through dedicated neurodegenerative disease centers.
Switzerland
Swissmedic expedites market authorization for therapies with prior FDA or EMA approval while cantonal hospital networks negotiate therapeutic category placement. The country's compulsory health insurance mandates coverage for orphan-designated indications. Basel and Zurich concentrate neurology research infrastructure with embedded movement disorder programs.
Pseudobulbar Treatment Market Competitive Landscape
Top-tier vendors anchor the branded orphan segment, while commodity manufacturers compete on acquisition cost in generic antidepressant tiers. The structure concentrates around three strategic archetypes: neurology portfolio majors leveraging hospital formulary relationships, specialty pharmaceutical developers exploiting regulatory exclusivity windows, and cost-focused generic houses scaling manufacturing across SSRI and tricyclic categories. Competitive moves center on long-acting injectable formulation development and digital therapeutic adjunct partnerships.
Within the orphan-designated specialty tier, Avanir Pharmaceuticals occupies a position exemplifying regulatory incentive capture through metabolic potentiation combinations. Pfizer Inc. represents the diversified neurology major archetype with breadth across movement disorder and neuropsychiatric portfolios. Dr. Reddy's Laboratories Ltd. anchors the generic manufacturing scale archetype, competing on cost-positioned antidepressant alternatives.
| Leading Market Players |
|---|
| Avanir Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Bayer AG |
| Dr. Reddy’s Laboratories Ltd. |
| F. Hoffmann-La Roche Ltd. |
| GlaxoSmithKline plc |
| Novartis AG |
| Sanofi |
| Otsuka Pharmaceutical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Quinidine procurement costs from Indian and Chinese API manufacturers cascade through three distinct pricing tiers as specialty pharmacy distributors apply markup differentials based on REMS compliance tier and orphan exclusivity status. The metabolic potentiation requirement ties dextromethorphan-quinidine combinations to dual-source active pharmaceutical ingredient qualification, creating cost stickiness that generic antidepressant alternatives exploit.
Pricing Analysis
Hospital formulary committees now unbundle neuropsychiatric pharmacy benefits from bundled neurology service contracts, creating direct therapeutic category competition at admission. Price differentiation separates mechanism-specific orphan therapies with REMS-mandated distribution from commodity SSRI alternatives sourced through standard wholesale channels. Pricing pressure stems from generic antidepressant substitution in community neurology practices with limited movement disorder specialization. Medicare Part D beneficiaries in home care settings exhibit highest price sensitivity, while academic medical centers with embedded ALS centers absorb branded therapy premiums through bundled payment structures.
Supply Chain Analysis
Dual-sourcing requirements for quinidine active pharmaceutical ingredients mandate multi-supplier qualification across Indian and Chinese API manufacturers, with secondary validation from European chemical synthesis facilities. Raw material dependencies center on dextromethorphan base compounds, quinidine sulfate, and specialized coating excipients for extended-release formulations. Supply chain risk concentrates in single-source vulnerability for CYP2D6 inhibitor compounds with limited qualified manufacturers. Distribution runs through REMS-accredited specialty pharmacy networks with 18-24 month credentialing cycles that constrain launch velocity for novel entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pseudobulbar treatment market functions as a geographic-arbitrage play where FDA orphan drug exclusivity windows in the United States contrast with EMA pediatric investigation plan cost burdens in Europe, creating divergent capital deployment returns.
For Market Incumbents: Lock in formulary positioning at academic medical centers with dedicated ALS and multiple sclerosis centers of excellence before bundled payment models fully mature. Deepen backward integration into quinidine API supply through strategic manufacturing partnerships in India, insulating against generic antidepressant substitution pressure in community neurology channels. Channel control through REMS-compliant specialty pharmacy networks represents the critical defensive lever.
For New Entrants and Emerging Players: Skilled nursing facilities with neurology-focused subacute programs represent an underserved buyer archetype with compressed medication optimization windows and limited mechanism-specific diagnostic penetration. Long-term care settings in Japan under PMDA Sakigake designation offer the most penetrable geography for novel receptor-targeting candidates. A go-to-market angle pairing digital therapeutic adjuncts with pharmacotherapy for real-world evidence generation unlocks payor contracting advantages.
For Investors and Strategic Acquirers: Consolidation pressure builds where small-cap neurology specialists face disproportionate resource allocation pressure from EMA expanded orphan drug maintenance fee structures and pediatric investigation plan enforcement. Acquisition targets center on developers with long-acting injectable formulation platforms addressing adherence gaps in movement disorder populations with cognitive comorbidities. The signal to watch is CMS national coverage determination proceedings for home-based neuropsychiatric administration, which would shift reimbursement parity materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Development | Depot delivery technologies address adherence gaps in ALS and MS populations with cognitive comorbidities. |
| REMS-Accredited Distribution Expansion | Specialty pharmacy network credentialing reduces patient access friction for orphan-designated therapies. |
| Digital Therapeutic Adjunct Partnership | Smartphone-based symptom monitoring generates real-world evidence for payor contracting negotiations. |
| Pediatric Investigation Plan Harmonization | EMA centralized procedures streamline multi-jurisdictional development for juvenile-onset neurological indications. |
| API Backward Integration | In-house quinidine production insulates against supply concentration in Indian and Chinese manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists with secondary validation against FDA orphan drug designations, EMA centralized procedure filings, ClinicalTrials.gov protocols, and CMS national coverage determination records. Bottom-up prescription volume modeling and top-down market sizing triangulated across neurology clinic expansion data and specialty pharmacy distribution reports.
Segment-weighting approaches applied differential growth assumptions across treatment settings, with outpatient administration receiving distinct coefficient calibration from inpatient and long-term care channels. CAGRs derived from fitted trend extrapolation anchored to orphan exclusivity expiration timelines and patent cliff modeling. Forecast inputs incorporated Medicare Part D reimbursement trajectory assumptions and movement disorder program expansion rates at tertiary care centers.
Underlying measurement precision varies by segment; home care end-use and oral delivery mode carry tighter precision than transdermal developmental formats and inhalation preclinical approaches. Forecasts reflect documented assumptions regarding FDA Breakthrough Therapy designation velocity and EMA pediatric investigation plan enforcement intensity. Deviation in CMS national coverage determination timing for home-based neuropsychiatric administration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market