
 North America Pharmaceutical Isolator Market | 2026-2036
North America Pharmaceutical Isolator Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Isolator Market Analytics
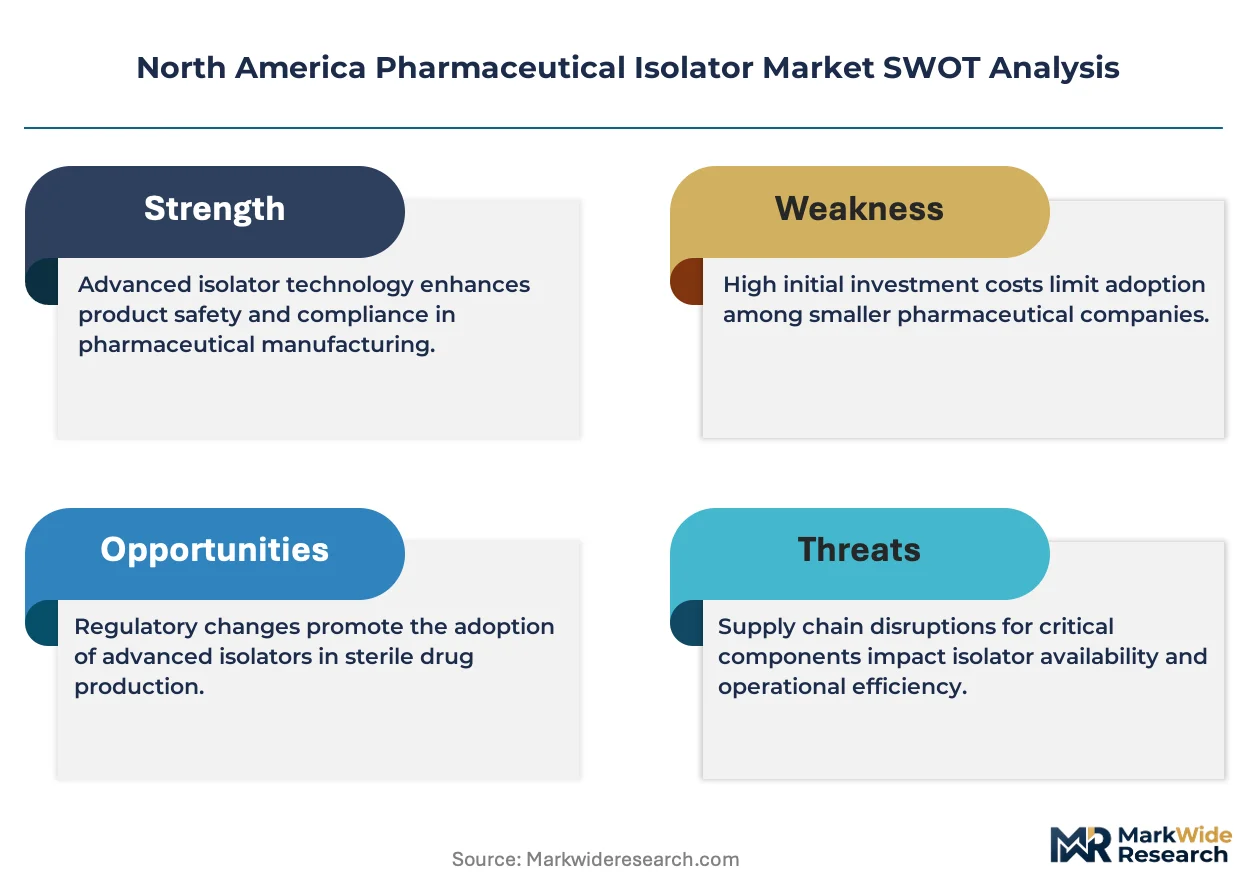
Single-use material integration with stainless steel containment shells is narrowing the performance gap between flexible and rigid isolator platforms. Getinge leverages its installed base of sterilization equipment to cross-sell integrated isolator lines across major US pharmaceutical manufacturing hubs. SKAN AG anchors its North American position through Swiss-engineered containment systems purpose-built for potent compound handling. Hosokawa Micron differentiates via micronization-specific isolator designs that address occupational exposure limits in API production.
A pharmaceutical isolator constitutes a sealed, pressure-controlled enclosure engineered from stainless steel or polymer composites with HEPA-filtered airlocks and glove ports, designed to maintain ISO 5 or better air quality while enabling operator manipulation of sterile or hazardous materials. Restricted Access Barrier Systems now dominate capital expenditure among large-scale sterile injectable manufacturers due to their compatibility with existing filling line infrastructure. Compounding Isolators represent the fastest-growing product category as US hospital pharmacies and 503B outsourcing facilities replace biological safety cabinets ahead of enforceable USP 797 sterility standards. Positive Pressure technology configurations command premium positioning in aseptic manufacturing applications where product protection overrides operator safety priorities.
FDA Current Good Manufacturing Practice enforcement and USP Chapter 797 compounding standards directly shape isolator validation protocols and installation timelines across the United States. Health Canada and PMRA guidelines for sterile drug manufacturing extend similar containment expectations to Canadian production facilities, creating cross-border harmonization pressure on equipment specifications. The EPA's National Emission Standards for Hazardous Air Pollutants further constrain venting architectures for isolators handling cytotoxic or genotoxic compounds. Stakeholders must weigh total cost of ownership against modular upgrade pathways as regulatory stringency escalates without corresponding reimbursement expansion.
Market Dynamics
USP Chapter 797 revisions are forcing compounding pharmacies and 503B outsourcing facilities across the United States to replace biological safety cabinets with certified isolators ahead of enforceable sterility deadlines, compressing procurement timelines and validating equipment selection.
Growth Catalysts
- Regulatory Enforcement:FDA Current Good Manufacturing Practice inspections are accelerating validation protocols for sterile injectable manufacturers, mandating isolator deployment in legacy facilities.
- Biotech Cluster Expansion:United States Northeast corridor demand concentrates replacement cycles for open-front hoods as cell and gene therapy manufacturing scales.
- Material Convergence:Single-use polymer integration with stainless steel containment shells is narrowing performance gaps between rigid and flexible isolator platforms.
Market Restraints
- Capital Intensity:Restricted Access Barrier Systems require seven-figure installation costs with extended commissioning timelines that strain mid-tier facility budgets.
- Supply Concentration:HEPA filtration media and specialized glove port assemblies concentrate among limited European and Asian component suppliers.
- Technical Limitation:Positive pressure configurations sacrifice operator protection for product sterility, constraining deployment in potent compound handling.
Strategic Opportunities
- Canadian Market Development:Health Canada and PMRA guideline harmonization with US standards creates cross-border equipment specification alignment for manufacturers serving both markets.
- 503B Facility Buildout:Hospital pharmacy outsourcing to 503B compounders is generating demand for compounding isolators with integrated environmental monitoring.
- Technology Convergence:Isolator-integrated rapid microbial detection systems are enabling real-time release testing that compresses batch disposition cycles.
Industry Challenges
- Validation Expertise Scarcity:IQ/OQ/PQ documentation for isolator installations requires specialized cleanroom commissioning engineers in short supply across North America.
- Legacy Line Integration:Retrofitting Restricted Access Barrier Systems onto existing filling equipment demands mechanical customization that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Isolator Market |
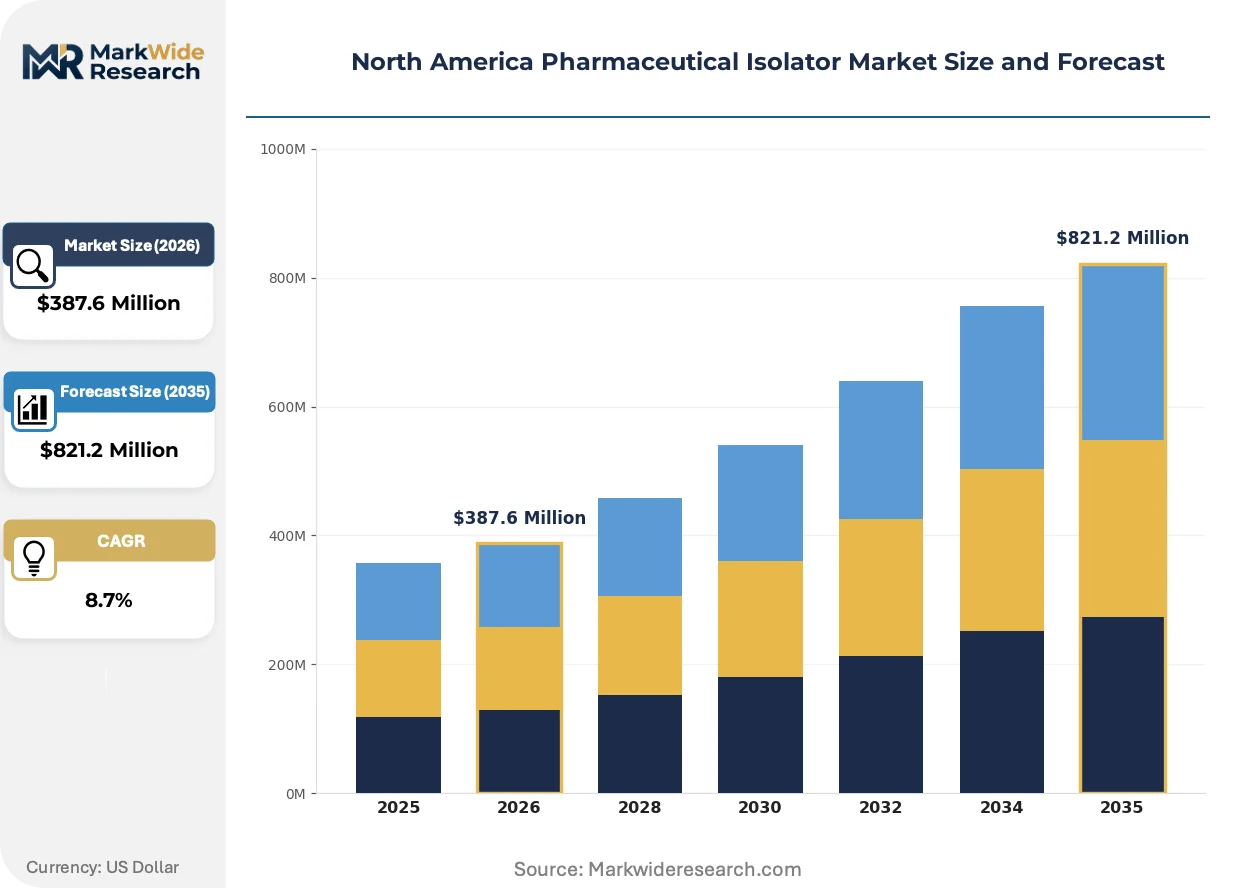
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glovebox Isolators, Restricted Access Barrier Systems, Compounding Isolators, Bio-Isolators Application: Research Laboratories, Production Facilities, Sterile Processing, Pharmaceutical Manufacturing End User: Biotechnology Firms, Contract Manufacturers, Pharmaceutical Companies, Academic Institutions Technology: Negative Pressure, Positive Pressure, Hybrid Systems, Microbial Barrier Technologies |
| Companies Covered | Getinge, SKAN AG, Hosokawa Micron, Azbil Corporation, Germfree Laboratories, NuAire, Comecer, M. Braun Inertgas-Systeme, Bioquell, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Isolator Market Evolving Landscape
Equipment architecture is pivoting toward modular configurations that accommodate rapid product changeover, while containment philosophy shifts from operator exclusion to integrated manipulation systems.
Continuous monitoring technology is migrating from standalone particle counters to embedded isolator sensor networks. Large-scale sterile injectable manufacturers are adopting these systems to satisfy FDA process analytical technology initiatives. The shift is compressing batch release timelines while elevating data integrity requirements for environmental monitoring.
EPA National Emission Standards for Hazardous Air Pollutants are constraining venting architectures for cytotoxic compound isolators. Manufacturers must engineer closed-loop filtration systems that capture genotoxic residues before atmospheric release. This regulatory pressure falls most heavily on oncology API production facilities in New Jersey and Puerto Rico, where legacy venting infrastructure requires complete replacement.
Hospital pharmacy procurement is consolidating vendor relationships around single-source isolator-service contracts. 503B outsourcing facilities are abandoning transactional equipment purchases in favor of multi-year service agreements bundling validation, maintenance, and consumables. This pattern concentrates most visibly in Texas and Florida, where private equity-backed compounder rollups are standardizing fleet specifications.
North America Pharmaceutical Isolator Market Segmentation
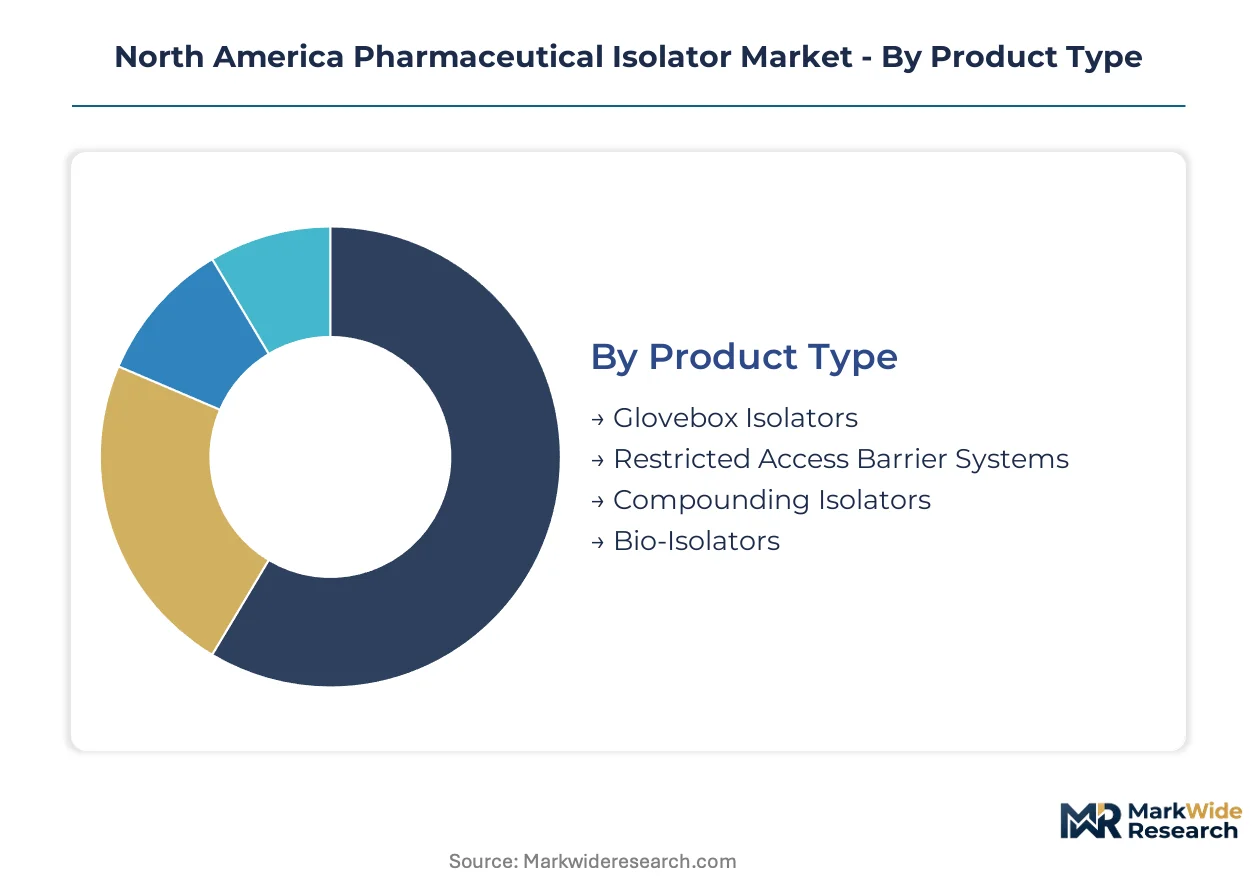
Isolator procurement patterns diverge sharply between sterile injectable manufacturers upgrading legacy lines and compounding pharmacies racing to meet USP 797 deadlines. Segment-level dynamics reveal where capital concentrates and which configurations face supply bottlenecks.
Product Type:
Equipment architecture determines installation complexity, validation burden, and integration pathways with existing cleanroom infrastructure.
- Restricted Access Barrier Systems:These rigid enclosures integrate directly with filling lines through sealed transfer ports and automated decontamination cycles. Large-scale sterile injectable manufacturers in the United States Northeast corridor deploy these systems to satisfy FDA Current Good Manufacturing Practice enforcement without complete facility reconstruction.
- Compounding Isolators:Compact units engineered for 503B outsourcing facilities and hospital pharmacies incorporate integrated environmental monitoring and rapid transfer ports. USP Chapter 797 revision timelines are compressing procurement cycles for these systems across Texas and Florida, where private equity-backed compounder rollups standardize fleet specifications.
- Glovebox Isolators:Stainless steel enclosures with fixed glove ports serve laboratory-scale potent compound handling and early-phase API development.
- Bio-Isolators:Polymer composite systems support cell and gene therapy manufacturing where single-use fluid paths eliminate cross-contamination risks.
Restricted Access Barrier Systems command the established base. The steepest expansion runs through Compounding Isolators.
Application:
Facility type dictates containment philosophy, with production environments prioritizing product protection and research settings balancing flexibility with biosafety.
- Pharmaceutical Manufacturing:Commercial-scale aseptic filling operations require continuous monitoring integration and closed-loop filtration architectures. EPA National Emission Standards for Hazardous Air Pollutants constrain venting designs for cytotoxic compound handling in New Jersey and Puerto Rico facilities.
- Sterile Processing:Central sterile supply departments and contract manufacturing organizations deploy isolators for terminal sterilization validation and depyrogenation cycles. Health Canada guideline harmonization with US standards extends equipment specification alignment across cross-border production networks.
- Production Facilities:Dedicated API synthesis and formulation suites employ negative pressure configurations to protect operators from potent compound exposure.
- Research Laboratories:Academic and discovery-stage biotechnology operations prioritize rapid reconfiguration over validated continuous operation.
Pharmaceutical Manufacturing anchors capital deployment. Sterile Processing is gaining share fastest as outsourcing penetration deepens.
End User:
Customer scale and regulatory exposure create distinct procurement patterns, from enterprise fleet standardization to single-unit validation for specialized applications.
- Contract Manufacturers:CDMOs and CMOs serving multiple pharmaceutical clients require modular isolator platforms that accommodate rapid product changeover and dedicated campaign segregation. These operators concentrate investment in the United States Northeast corridor to capture cell and gene therapy manufacturing scale-up.
- Pharmaceutical Companies:Integrated manufacturers with captive sterile filling capacity pursue Restricted Access Barrier System retrofits that extend legacy line viability while satisfying FDA inspection priorities.
- Biotechnology Firms:Venture-backed developers of novel modalities prioritize flexible containment that scales from clinical to commercial without platform replacement.
- Academic Institutions:University medical centers and research hospitals procure compounding isolators for in-house 503A pharmacy operations and investigator-initiated trials.
Contract Manufacturers drive volume concentration. Biotechnology Firms are expanding most quickly as novel modality pipelines mature.
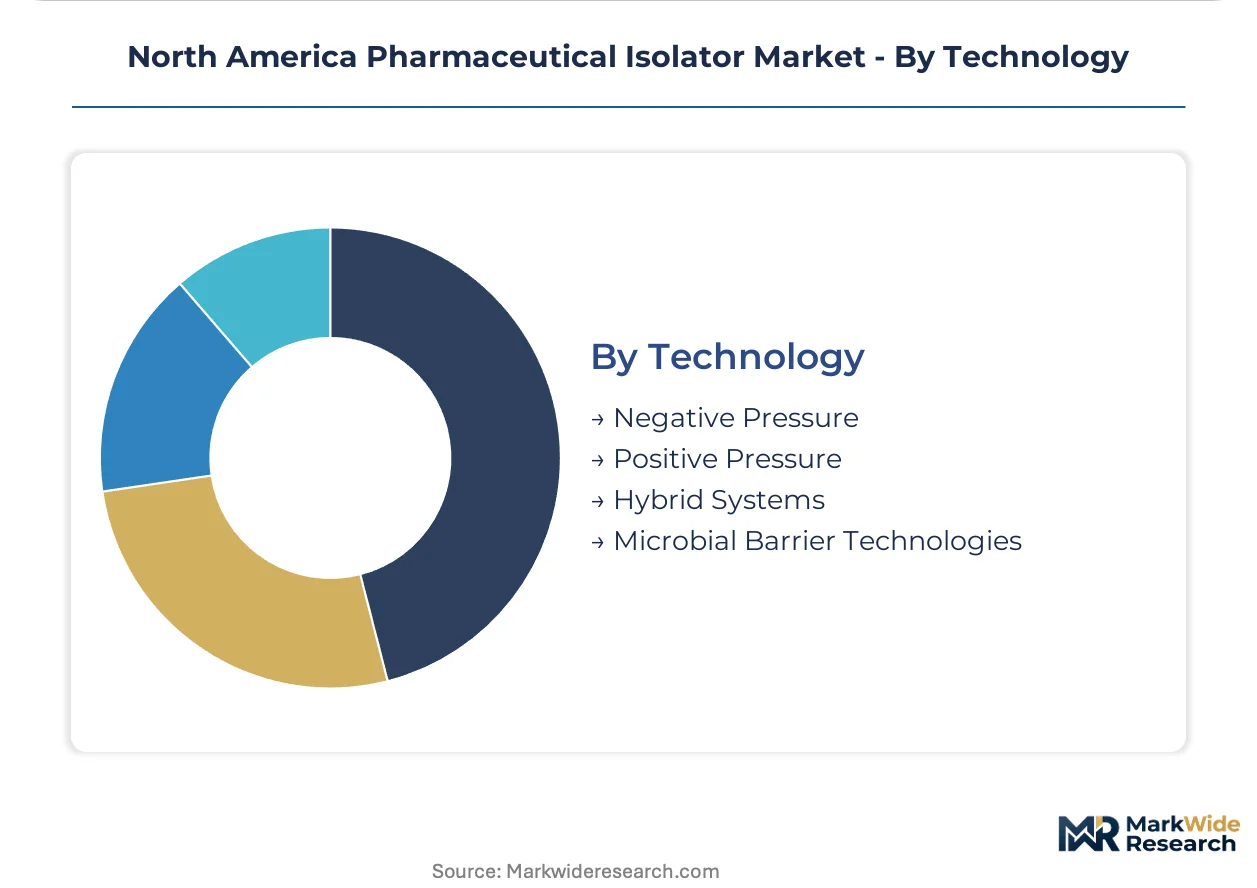
Technology:
Pressure differential philosophy determines the fundamental trade-off between product sterility assurance and operator exposure control.
- Positive Pressure:Inward airflow from HEPA-filtered supply plenums maintains ISO 5 or better conditions within the work zone, prioritizing product protection over personnel safety. Aseptic filling applications in sterile injectable manufacturing favor this configuration despite its limitation for potent compound handling.
- Negative Pressure:Outward airflow containment captures hazardous aerosols and particulates through exhaust filtration before atmospheric release. Oncology API production facilities employ these systems to satisfy occupational exposure limit compliance under EPA venting constraints.
- Hybrid Systems:Switchable pressure modes accommodate multi-product facilities where campaign sequencing alternates between sterile and potent compound handling.
- Microbial Barrier Technologies:Specialized filtration and surface treatment approaches extend continuous operation intervals between decontamination cycles.
Positive Pressure dominates installed capacity. Negative Pressure is climbing the fastest as potent compound pipelines expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers and hospital pharmacy outsourcing facilities drive isolator procurement across North America, with regulatory enforcement timelines compressing installation schedules in concentrated biotech corridors.
United States Northeast Corridor
Cell and gene therapy manufacturing scale-up in Massachusetts and New Jersey drives replacement cycles for legacy open-front hoods. FDA Current Good Manufacturing Practice inspections mandate isolator deployment in legacy sterile injectable facilities. Boston-Cambridge biotech clusters concentrate demand for flexible containment systems that accommodate rapid product changeover.
United States South Atlantic
Private equity-backed 503B compounder rollups in Texas and Florida standardize fleet specifications around integrated service contracts. USP Chapter 797 revision deadlines compress procurement timelines for compounding isolators with environmental monitoring. Hospital pharmacy outsourcing generates concentrated demand for compact units with rapid transfer ports.
United States Midwest
Legacy pharmaceutical manufacturing hubs in Illinois and Ohio pursue Restricted Access Barrier System retrofits to extend filling line viability. EPA National Emission Standards constrain venting architectures for facilities handling cytotoxic compounds. Chicago-area contract manufacturers invest in modular platforms serving multiple pharmaceutical clients.
Canada
Health Canada and PMRA guideline harmonization with US standards creates cross-border equipment specification alignment. Ontario-based sterile drug manufacturers adopt isolator validation protocols matching FDA enforcement timelines. Toronto-area production facilities upgrade containment systems to satisfy dual-market export requirements.
North America Pharmaceutical Isolator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base concentrates among European-origin equipment fabricators with North American distribution networks and domestic service capabilities. Two strategic archetypes dominate: sterilization equipment incumbents leveraging installed base cross-sell opportunities, and containment specialists engineering purpose-built systems for potent compound handling. Competitive moves center on multi-year service contract bundling and modular platform development that accommodates rapid product changeover.
Among European-origin system integrators, Getinge and SKAN AG occupy positions that exemplify contrasting archetype strategies. Getinge represents the sterilization-equipment-incumbent model, while SKAN AG anchors the Swiss-engineered containment-specialist tier. Hosokawa Micron sits within a narrower specialization vector addressing micronization-specific occupational exposure requirements. These three fabricators collectively illustrate how geographic origin and legacy capability shape competitive positioning in North American pharmaceutical containment procurement.
| Leading Market Players |
|---|
| Getinge |
| SKAN AG |
| Hosokawa Micron |
| Azbil Corporation |
| Germfree Laboratories |
| NuAire |
| Comecer |
| M. Braun Inertgas-Systeme |
| Bioquell |
| Others |
Value Network & Pricing Analysis
Overcapacity in European HEPA filtration component manufacturing is compressing supplier pricing power while extending payment terms for North American isolator fabricators. This utilization slack allows buyers to negotiate multi-year service bundling without hardware premiums, reshaping how 503B compounders and contract manufacturers structure procurement.
Pricing Analysis
Cost-plus contracts with stainless steel indexation dominate large-scale Restricted Access Barrier System procurements, insulating vendors from raw material volatility while capping buyer exposure. Price differentiation hinges on FDA validation tier and integrated environmental monitoring depth, with validated systems commanding substantial premiums over base configurations. Pricing pressure stems from private equity-backed 503B rollups standardizing fleet specifications around single-source contracts. Hospital pharmacy procurement teams exhibit highest price sensitivity, whereas cell and gene therapy manufacturers prioritize containment performance over capital outlay.
Supply Chain Analysis
Upstream feedstock for isolator fabrication draws from German precision engineering clusters for glove port assemblies, Swiss specialty polymer suppliers for single-use fluid paths, and domestic North American stainless steel processors for containment shells. Critical dependencies include HEPA filtration media, specialized elastomer seals, and automated decontamination cycle controllers. Single-source vulnerability concentrates in European glove port component suppliers, exposing lead times to transatlantic logistics disruptions. Distribution runs through direct OEM sales teams for enterprise installations and regional service integrators for mid-tier compounding pharmacy deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are flattening across the installed base while validation, maintenance, and consumables contracts expand at double the rate of equipment sales, reframing competitive advantage around service-attach depth rather than unit throughput.
For Market Incumbents: Entrench cross-sell relationships by embedding continuous monitoring sensors that lock in recurring calibration and data integrity service revenue. Acquire specialized validation engineering capabilities to address IQ/OQ/PQ documentation scarcity constraining installation timelines. Defend against modular platform challengers by extending legacy line retrofit compatibility. For New Entrants and Emerging Players: Mid-market 503B compounders in the United States South Atlantic represent the most penetrable entry point, where private equity consolidation has created standardized fleet specifications without entrenched vendor loyalty. Canadian sterile drug manufacturers upgrading to dual-market export capability offer secondary white-space with lower competitive intensity. Pursue equipment-as-a-service positioning that bundles validation and maintenance to bypass capital budget gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across compounding isolator manufacturing as single-use polymer integration reduces stainless steel fabrication requirements. Long-term viability favors platforms with embedded software and sensor networks generating recurring revenue. Target acquisition candidates with installed base scale in hospital pharmacy and 503B segments. Monitor Health Canada-PMRA harmonization implementation velocity as inflection signal for cross-border specification alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Bundling | Captures multi-year validation and maintenance revenue from 503B compounder rollups in Texas and Florida. |
| Modular Platform Development | Enables rapid product changeover for CDMOs serving cell and gene therapy clients in the Northeast corridor. |
| Rapid Microbial Detection Integration | Compresses batch release timelines for FDA Current Good Manufacturing Practice enforcement compliance. |
| Canadian Market Certification Investment | Aligns equipment specifications with Health Canada-PMRA guidelines for dual-market export capability. |
| Closed-Loop Filtration Engineering | Satisfies EPA National Emission Standards for cytotoxic compound handling in New Jersey and Puerto Rico facilities. |
Research Methodology
A spread of perspectives from sterile processing department managers, regulatory affairs leads at 503B facilities, hospital pharmacy procurement directors, and contract manufacturing organization engineering heads converged on the working assumptions. These primary insights were cross-referenced against FDA warning letter databases, Health Canada guideline publications, USP Chapter 797 revision documentation, and EPA enforcement records. Bottom-up equipment shipment tracking and top-down pharmaceutical capital expenditure analysis were triangulated to anchor volume estimates.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation, pressure configuration technology tiers, and end-user scale categories. The analytical framework weighted replacement cycle dynamics for legacy open-front hoods against greenfield 503B facility buildout. CAGRs were derived from regression analysis of historical procurement patterns and regulatory deadline compression effects. Forecast inputs included USP 797 enforcement timeline assumptions and cell and gene therapy manufacturing capacity expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting hospital capital budgets or private equity deployment pacing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and component supply chain stability. Cross-checking against FDA inspection citation trends and 503B facility licensing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market