
 Global Appendiceal Cancer Treatment Market | 2026-2036
Global Appendiceal Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Appendiceal Cancer Treatment Market Intelligence
Precision medicine biomarker stratification is tilting appendiceal cancer treatment toward molecularly guided therapy selection. Roche Holding leverages its companion diagnostic infrastructure to anchor clinical decision-making in this rare indication. Amgen competes through targeted pathway inhibition, while Bristol-Myers Squibb extends its immuno-oncology franchise into neuroendocrine and mucinous subtypes.
Appendiceal cancer treatment encompasses multimodal interventions for malignancies originating in the vermiform appendix, including systemic chemotherapy regimens, cytoreductive surgery with heated intraperitoneal chemotherapy, and emerging immunotherapeutic approaches. The primary purpose centers on managing peritoneal dissemination patterns unique to appendiceal primaries, particularly pseudomyxoma peritonei and mucinous adenocarcinoma variants. Chemotherapy agents occupy the largest current revenue pool given established reimbursement for platinum-fluoropyrimidine doublets, though targeted therapeutics represent the fastest-expanding segment as FGFR and HER2-directed agents advance through clinical pipelines. Immunotherapy remains structurally constrained by low tumor mutational burden in most appendiceal subtypes, limiting near-term penetration.
The FDA's orphan drug designation framework and EMA's PRIME pathway for rare malignancies shape development incentives and market access timelines for appendiceal cancer therapies. Japan's PMDA Sakigake designation accelerates regulatory review for innovative oncology products addressing unmet needs in rare cancers. Stakeholders must monitor evolving cytoreductive surgery reimbursement policies across national health systems and the maturation of circulating tumor DNA assays for peritoneal malignancy monitoring.
Market Dynamics
Precision medicine infrastructure is restructuring appendiceal cancer treatment decisions, as molecular profiling platforms shift therapeutic selection from histology-based protocols toward biomarker-driven regimens across oncology networks.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation framework accelerates development timelines for rare malignancy therapies, reducing regulatory burden for sponsors targeting mucinous adenocarcinoma subtypes.
- Cytoreductive Surgery Centers:Clustering of specialized HIPEC-capable facilities in the United States, Germany, and Japan concentrates patient volume and drives protocol standardization for peritoneal surface malignancies.
- Companion Diagnostic Infrastructure:Roche Holding's integrated diagnostic platforms enable real-time biomarker stratification, anchoring clinical trial enrollment and therapy selection in FGFR and HER2-directed pathways.
Market Restraints
- Low Tumor Mutational Burden:Most appendiceal cancer subtypes exhibit insufficient neoantigen load, structurally constraining checkpoint inhibitor efficacy and limiting immunotherapy penetration.
- Platinum-Fluoropyrimidine Cost Exposure:Established chemotherapy doublets face input cost volatility from active pharmaceutical ingredient supply concentration in Chinese and Indian manufacturing hubs.
- EMA Regulatory Friction:Divergent evidentiary requirements for accelerated approval across EU member states create reimbursement uncertainty for novel targeted agents.
Strategic Opportunities
- Circulating Tumor DNA Monitoring:Liquid biopsy platforms for peritoneal malignancy surveillance represent underdeveloped service lines in community oncology settings.
- Japan's Sakigake Pathway:PMDA's priority review designation for innovative oncology products creates first-mover advantage windows for sponsors addressing neuroendocrine subtypes.
- HIPEC-Immunotherapy Convergence:Combination protocols integrating heated intraperitoneal chemotherapy with regional immunotherapy delivery are entering early-phase investigation.
Industry Challenges
- Cytoreductive Surgery Workforce Gap:Training pipelines for peritoneal surface oncology surgeons remain insufficient to match patient referral volumes at tertiary centers.
- Biomarker Assay Standardization:Discordance between FGFR amplification detection methods across CLIA-certified laboratories complicates clinical trial enrollment and therapy assignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Appendiceal Cancer Treatment Market |
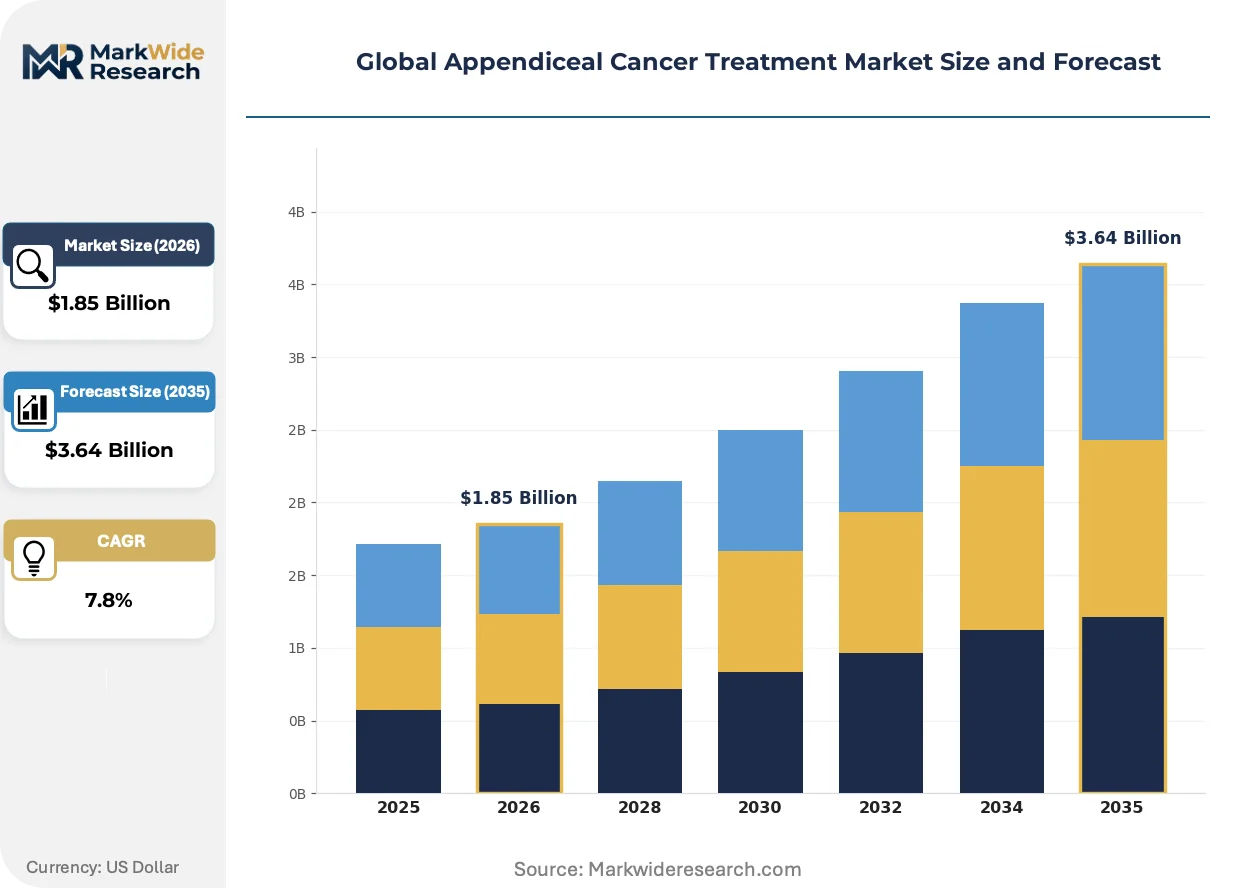
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Agents, Targeted Therapeutics, Immunotherapy, Surgical Devices, Radiation Equipment Therapy Area: Peritoneal Carcinomatosis, Pseudomyxoma Peritonei, Neuroendocrine Tumors, Mucinous Adenocarcinoma, Signet Ring Cell Adenocarcinoma Application: First-Line Treatment, Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care, Recurrence Management End User: Oncology Clinics, Specialized Cancer Centers, Research Institutions, Ambulatory Surgical Centers, Diagnostic Laboratories |
| Companies Covered | AbbVie, Roche Holding, Amgen, Novartis, Becton Dickinson, Pfizer, Bristol-Myers Squibb, AstraZeneca, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Appendiceal Cancer Treatment Market Strategic Shifts & Innovations
Digital pathology and artificial intelligence platforms are penetrating diagnostic workflows, compressing turnaround times for molecular characterization and reshaping how treatment centers manage rare cancer case volumes.
Next-generation sequencing panels are digitizing appendiceal cancer diagnostic pathways by automating biomarker reporting from formalin-fixed tissue specimens. Academic medical centers and specialized oncology networks are deploying these platforms at scale, replacing sequential single-gene testing. This digitization is compressing the interval between diagnosis and therapy initiation, forcing community hospitals to outsource molecular profiling or invest in capital-intensive sequencing infrastructure.
The FDA's accelerated approval pathway for rare cancer indications is compressing traditional phase III requirements, permitting surrogate endpoint-based authorizations that reshape post-market confirmatory trial obligations. Oncology sponsors are restructuring development programs to leverage this framework, prioritizing biomarker-enriched cohorts over broad histology-based enrollment. Mucinous adenocarcinoma and pseudomyxoma peritonei subtypes are experiencing the most pronounced regulatory timeline compression.
Consolidation of patient referrals toward high-volume cytoreductive surgery centers is displacing distributed care models across the United States and Western Europe. Community oncologists are ceding surgical management to designated HIPEC-capable institutions, while payers are narrowing networks around outcome-verified centers. This concentration is most visible in Germany, where regional cancer consortia mandate referral pathways for peritoneal surface malignancies.
Global Appendiceal Cancer Treatment Market Segmentation
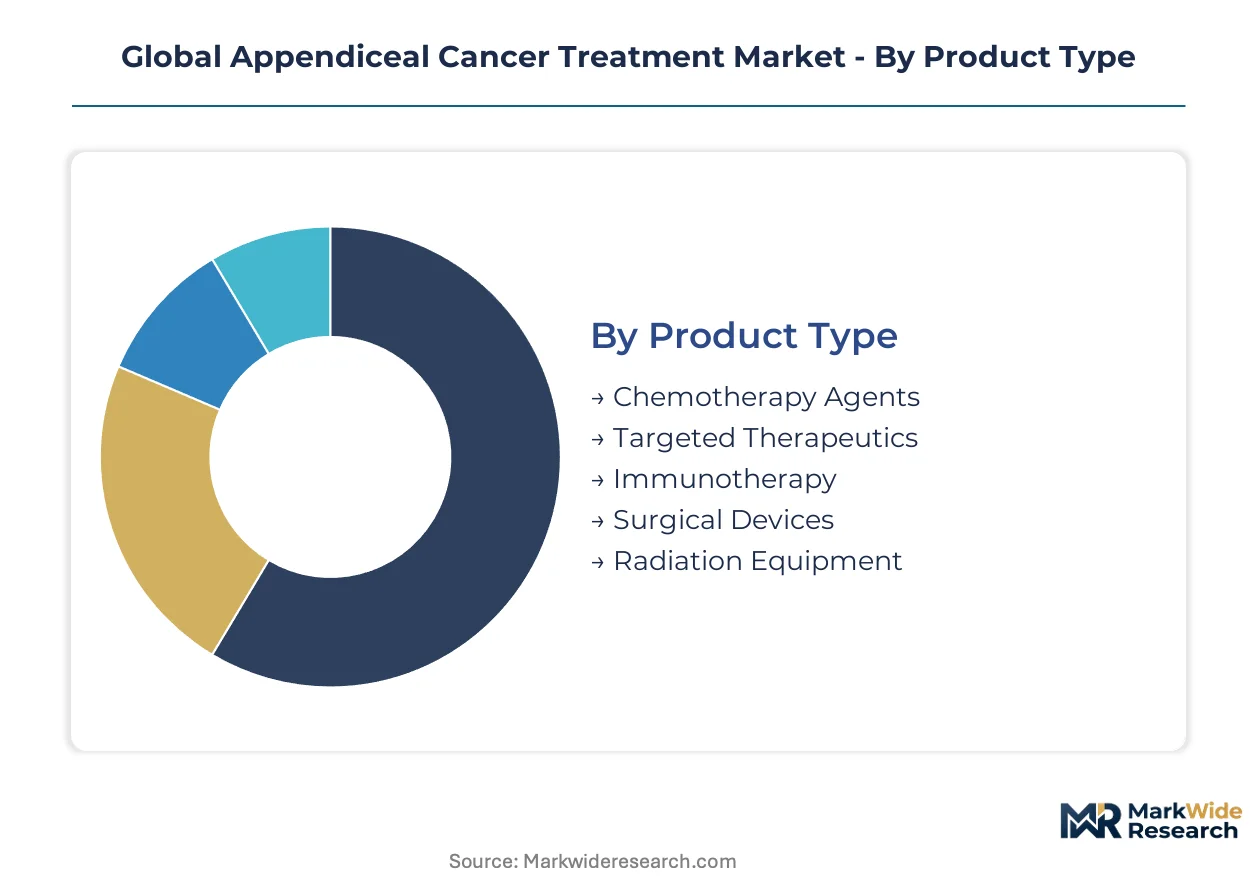
Appendiceal cancer treatment markets fragment across intervention modalities, disease subtypes, and care delivery settings. Each segmentation dimension carries distinct reimbursement logic and clinical adoption patterns that shape competitive positioning.
Product Type:
Cost tier stratification separates established systemic therapies from capital-intensive surgical platforms and emerging biologics.
- Chemotherapy Agents:Platinum-fluoropyrimidine doublets constitute the backbone of systemic treatment for mucinous and non-mucinous subtypes. Demand concentrates in Germany and the United States where established reimbursement pathways support community oncology administration. Cost volatility in active pharmaceutical ingredient supply from Asian manufacturing hubs pressures margin stability.
- Targeted Therapeutics:FGFR inhibitors and HER2-directed antibodies are advancing through clinical pipelines with companion diagnostic requirements. The steepest expansion runs through this segment as biomarker-enriched trial designs accelerate regulatory timelines at FDA and EMA.
- Immunotherapy:Checkpoint inhibitors face structural constraints from low tumor mutational burden in most appendiceal subtypes. Japan's PMDA Sakigake pathway offers accelerated review for novel immuno-oncology combinations in neuroendocrine variants.
- Surgical Devices:HIPEC perfusion systems and cytoreductive instrumentation anchor peritoneal surface malignancy protocols. Specialized cancer centers in Japan and Germany drive procurement volumes.
- Radiation Equipment:External beam and intraoperative radiotherapy platforms serve niche palliative applications. Limited penetration reflects anatomical challenges with peritoneal dissemination patterns.
Chemotherapy agents command the established base. The steepest expansion runs through targeted therapeutics.
Therapy Area:
Disease biology heterogeneity creates distinct addressable populations with varying intervention intensities and outcomes.
- Peritoneal Carcinomatosis:Widespread peritoneal seeding from appendiceal primaries necessitates multimodal management combining cytoreductive surgery with heated intraperitoneal chemotherapy. United States tertiary centers concentrate referral volumes for complex debulking procedures.
- Pseudomyxoma Peritonei:Low-grade mucinous neoplasms with characteristic gelatinous ascites require specialized HIPEC protocols. German regional cancer consortia mandate standardized referral pathways for this subtype.
- Neuroendocrine Tumors:Well-differentiated variants with somatostatin receptor expression enable peptide receptor radionuclide therapy. Japan's specialized cancer centers lead adoption of lutetium-177 based regimens.
- Mucinous Adenocarcinoma:High-grade mucinous histology with signet ring features drives aggressive systemic therapy approaches. FDA orphan drug designation accelerates development timelines for targeted agents in this population.
- Signet Ring Cell Adenocarcinoma:Poorly differentiated morphology with diffuse infiltration patterns limits surgical resectability. Palliative systemic therapy dominates clinical management.
Peritoneal carcinomatosis captures the largest addressable population. Pseudomyxoma peritonei shows the most pronounced protocol standardization.
Application:
Treatment sequencing reflects curative intent, disease stage, and prior therapy exposure.
- First-Line Treatment:Initial systemic therapy or surgical cytoreduction establishes disease control. Oncology clinics in the United States and Germany administer the majority of frontline regimens.
- Adjuvant Therapy:Post-surgical systemic treatment reduces recurrence risk following complete cytoreduction. EMA reimbursement policies vary across member states for adjuvant indications.
- Neoadjuvant Therapy:Preoperative systemic or regional treatment aims to downstage unresectable disease. Specialized cancer centers deploy this approach for borderline resectable peritoneal disease.
- Palliative Care:Symptom-focused interventions for advanced or refractory disease. Hospice-integrated oncology networks in Japan emphasize quality-of-life endpoints.
- Recurrence Management:Second-line systemic therapy or repeat cytoreduction for relapsed disease. Circulating tumor DNA monitoring is emerging to guide intervention timing.
First-line treatment anchors revenue concentration. Recurrence management is gaining strategic attention as surveillance protocols mature.
End User:
Site-of-care economics and technical capability requirements concentrate specific interventions to designated settings.
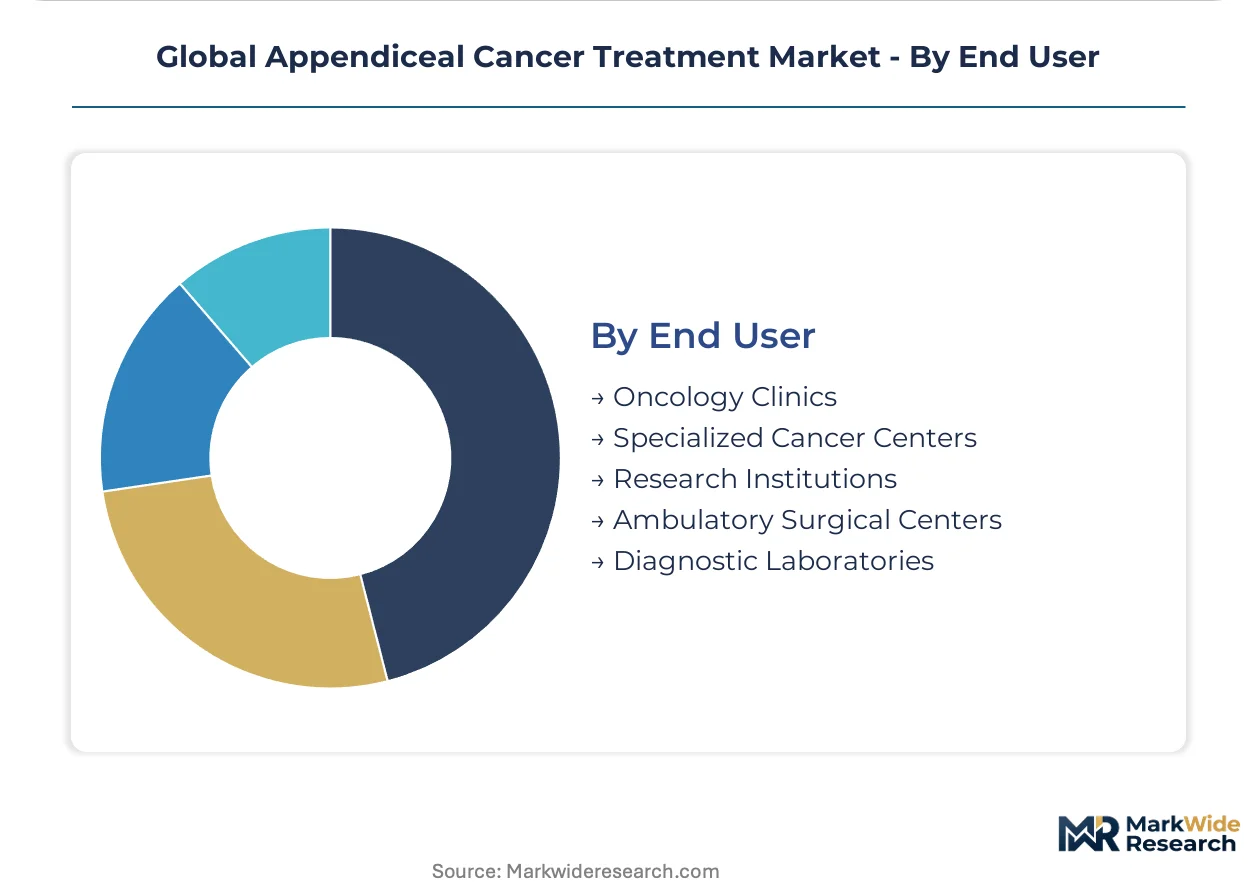
- Oncology Clinics:Community and hospital-affiliated infusion centers administer systemic chemotherapy and targeted therapy. United States networks are consolidating around outcome-based contracts.
- Specialized Cancer Centers:Designated HIPEC-capable institutions perform cytoreductive surgery with heated intraperitoneal chemotherapy. Germany's regional cancer consortia concentrate referrals to verified high-volume centers.
- Research Institutions:Academic medical centers host early-phase clinical trials for novel targeted and immunotherapy agents. Japan's National Cancer Center drives biomarker-driven protocol development.
- Ambulatory Surgical Centers:Limited role given complexity of appendiceal cancer interventions; diagnostic laparoscopy represents primary applicable procedure.
- Diagnostic Laboratories:CLIA-certified molecular profiling facilities enable biomarker stratification. Next-generation sequencing panels are digitizing diagnostic pathways across United States and European networks.
Specialized cancer centers command complex procedure volumes. Diagnostic laboratories are expanding fastest as molecular profiling becomes standard-of-care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exports supply specialized oncology centers across Central Europe with cytoreductive surgery protocols and companion diagnostic platforms.
United States
Academic medical centers in Houston and New York City drive HIPEC procedure volumes for pseudomyxoma peritonei. The FDA's orphan drug designation framework accelerates development timelines for mucinous adenocarcinoma therapies. The University of Texas MD Anderson Cancer Center anchors national referral networks for peritoneal surface malignancies.
Germany
Regional cancer consortia concentrate patient referrals to verified high-volume cytoreductive surgery centers. EMA's PRIME pathway for rare malignancies shapes market access timelines for novel targeted agents. The University Hospital of Munich and Berlin Charité standardize HIPEC protocols across federal state networks.
Japan
PMDA's Sakigake designation accelerates regulatory review for innovative oncology products addressing neuroendocrine subtypes. National Cancer Center hospitals in Tokyo and Osaka lead biomarker-driven protocol development. Lutetium-177 based peptide receptor radionuclide therapy adoption concentrates in Kanto region specialized centers.
United Kingdom
London teaching hospitals integrate digital pathology platforms into appendiceal cancer diagnostic workflows. NHS England's specialized commissioning frameworks concentrate complex cytoreductive procedures to designated centers. The Royal Marsden Hospital anchors peritoneal surface oncology referral networks across Southeast England.
Switzerland
Roche Holding's companion diagnostic infrastructure enables real-time biomarker stratification for FGFR-directed therapy selection. Swissmedic's accelerated access pathways compress timelines for rare cancer indications. Basel and Zurich oncology networks anchor molecular profiling standardization across Alpine region treatment centers.
Global Appendiceal Cancer Treatment Market Key Industry Players
On the supply side, the industry is consolidating around integrated diagnostic-therapeutic platforms with tiered participation across biologics, devices, and service layers. Large-cap pharmaceutical sponsors anchor molecularly guided development programs through companion diagnostic partnerships. Mid-tier surgical device specialists concentrate on HIPEC perfusion system innovation. Dominant competitive moves include strategic partnerships between diagnostic platform developers and oncology sponsors, plus geographic expansion of cytoreductive surgery center networks into underserved markets.
Within the integrated pharmaceutical-diagnostic tier, Roche Holding exemplifies companion diagnostic infrastructure deployment. Amgen occupies a position representing targeted pathway inhibition specialists, while Bristol-Myers Squibb anchors immuno-oncology franchise extension into neuroendocrine and mucinous subtypes.
| Leading Market Players |
|---|
| AbbVie |
| Roche Holding |
| Amgen |
| Novartis |
| Becton Dickinson |
| Pfizer |
| Bristol-Myers Squibb |
| AstraZeneca |
| Eli Lilly and Company |
| Others |
Cost & Logistics Intelligence
Shanghai and Suzhou pharmaceutical manufacturing clusters anchor active pharmaceutical ingredient production for platinum-fluoropyrimidine doublets, concentrating cost leverage among contract manufacturers serving oncology formulators in Germany and the United States. This geographic concentration of intermediate synthesis capacity shapes margin structures across the chemotherapy segment.
Pricing Analysis
Next-generation FGFR inhibitors command substantial premiums over established platinum-fluoropyrimidine doublets, while prior-generation generic fluoropyrimidines occupy the economy tier. Three-tier pricing structure across premium targeted therapeutics, standard chemotherapy, and economy generics reflects FDA orphan drug exclusivity windows and companion diagnostic bundling. Cost compression in the chemotherapy tier intensifies because API supply concentration in Chinese manufacturing hubs exposes formulators to input volatility. Community oncology clinics in the United States exhibit the highest price sensitivity due to thin reimbursement margins, while specialized cancer centers in Germany absorb premium pricing for biomarker-directed regimens.
Supply Chain Analysis
Upstream feedstock for oncology APIs draws from specialized chemical intermediates manufactured in India, China, and select European facilities. Platinum salts, fluoropyrimidine precursors, and monoclonal antibody cell culture media constitute critical input dependencies. Single-source vulnerability runs through Chinese API manufacturing concentration, where environmental compliance shutdowns disrupt global supply. Distribution runs through regional wholesaler networks in the United States, direct hospital contracting in Germany, and centralized procurement via Japan's National Health Insurance system.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision medicine fragmentation in appendiceal cancer creates distinct competitive niches as molecular profiling splinters historically uniform treatment protocols into biomarker-specific addressable populations.
For Market Incumbents: Insulate market position by deepening companion diagnostic infrastructure partnerships to lock in biomarker-directed therapy selection, and accelerate capacity addition in Switzerland for FGFR inhibitor manufacturing to reduce API exposure. Roche Holding's integrated platform model represents the defensive benchmark against emerging targeted therapy sponsors. For New Entrants and Emerging Players: Establish a beachhead in circulating tumor DNA monitoring services for peritoneal malignancy surveillance, where community oncology settings lack standardized platforms. Japan's neuroendocrine subtype segment offers the most penetrable entry point via PMDA Sakigake pathway acceleration. A laboratory-services partnership model with existing CLIA-certified facilities minimizes capital requirements versus sequencing infrastructure buildout. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cytoreductive surgery center networks concentrate patient volume and reimbursement influence in fewer institutions over time. Target acquisition archetype: mid-tier HIPEC device specialists with installed base expansion potential in underserved United States markets. The signal to watch is FDA accelerated approval pathway expansion for surrogate endpoint-based authorizations in mucinous subtypes.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Roche Holding anchors biomarker stratification infrastructure across oncology networks. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses development timelines for mucinous adenocarcinoma therapies. |
| Manufacturing Scale-Up | Swiss and German facilities reduce API supply concentration risk from Asian hubs. |
| Clinical Trial Advancement | Academic medical centers in Houston and New York City drive HIPEC protocol standardization. |
| Licensing Agreement | Japanese National Cancer Center networks enable lutetium-177 therapy access in neuroendocrine variants. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads at FDA and EMA, formulary directors at United States payers, and hospital procurement managers converged on the working assumptions. Secondary validation drew from FDA orphan drug designation filings, EMA PRIME pathway submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions including treatment line, disease subtype, administration route, and regional regulatory cluster. CAGRs were derived from patient incidence projections cross-referenced with therapy penetration curves and pricing trajectory assumptions. Forecast inputs incorporated cytoreductive surgery center capacity expansion plans and companion diagnostic platform deployment timelines.
Stress conditions across API supply disruption, reimbursement policy shifts, and biomarker assay standardization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway access and therapy adoption curves. Material shifts in FDA accelerated approval criteria or EMA evidentiary requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Ovarian Cancer Therapeutics Market