
 Global Plasma Therapeutics Market | 2026-2036
Global Plasma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plasma Therapeutics Market Foresight
The EU Green Deal's pharmaceutical sustainability benchmarks are consolidating procurement criteria across European hospital networks. CSL Limited leverages vertically integrated plasma collection networks spanning the United States and Germany to sustain fractionation throughput. Grifols anchors European supply through its Barcelona production complex, while Takeda Pharmaceutical Company competes on recombinant-alternative portfolios that reduce plasma dependency.
Plasma therapeutics comprise purified human blood proteins—immunoglobulins, albumin, coagulation factors, and hyperimmune globulins—recovered via cold ethanol fractionation or chromatographic separation, then formulated for intravenous or subcutaneous administration to treat congenital deficiencies, autoimmune neuropathies, and critical bleeding events. Immunoglobulin commands the largest revenue pool due to chronic replacement therapy in primary immune deficiency, though coagulation factors extract premium pricing in hemophilia care where recombinant alternatives remain cost-prohibitive for many health systems. Subcutaneous delivery modes are gaining fastest adoption as patients shift from hospital-based infusions toward home administration protocols.
FDA plasma-sourcing regulations and EMA's Good Manufacturing Practice directives for biologicals govern collection volume, viral inactivation standards, and traceability requirements, directly constraining which fractionators qualify for institutional tenders. WHO's plasma quality guidelines further harmonize export pathways for derivatives moving between regulated and emerging markets. Stakeholders must monitor regulatory divergence between FDA's pathogen-reduction mandates and EMA's emerging environmental-impact disclosures for biological manufacturing.
Market Dynamics
Fractionators face mounting pressure from EMA's emerging environmental-impact disclosure requirements for biological manufacturing, which is absorbing capital that previously expanded collection infrastructure and forcing selective investment in higher-purity chromatographic platforms.
Growth Catalysts
- FDA Pathogen-Reduction Mandates:Tighter viral inactivation standards are consolidating qualified suppliers and locking in long-term institutional contracts with certified fractionators.
- Subcutaneous Delivery Protocols:Patient migration from hospital-based infusions toward home administration is expanding addressable volume in primary immune deficiency management.
- Japan's Aging Cohort:Expanding elderly populations requiring chronic immunoglobulin replacement are sustaining reimbursement-stable demand expansion.
Market Restraints
- Plasma Collection Bottlenecks:Dependence on US and German donor networks creates geographic concentration risk that constrains fractionation throughput during supply disruptions.
- Recombinant Substitution Pressure:Engineered coagulation factors threaten pricing power in hemophilia care where health systems prioritize cost containment.
- EMA Sustainability Benchmarks:EU Green Deal pharmaceutical disclosure requirements impose compliance friction that elevates fixed costs for European production assets.
Strategic Opportunities
- Indian Specialty Clinic Expansion:Underpenetrated immunodeficiency diagnosis rates in tier-2 cities offer volume expansion potential as CDSCO streamlines biological import pathways.
- Chromatography-Cold Ethanol Hybrid Platforms:Convergent purification technologies enable higher-yield immunoglobulin recovery that reduces unit production costs.
- Direct-to-Patient Distribution:Bypassing hospital pharmacy intermediaries through home infusion nursing networks captures margin previously lost to institutional procurement.
Industry Challenges
- Fractionation Specialist Shortage:Scarce expertise in plasma protein biochemistry and viral validation protocols extends facility commissioning timelines.
- Legacy Batch Record Integration:Digital traceability upgrades for EMA Good Manufacturing Practice compliance collide with paper-based quality systems at established plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plasma Therapeutics Market |
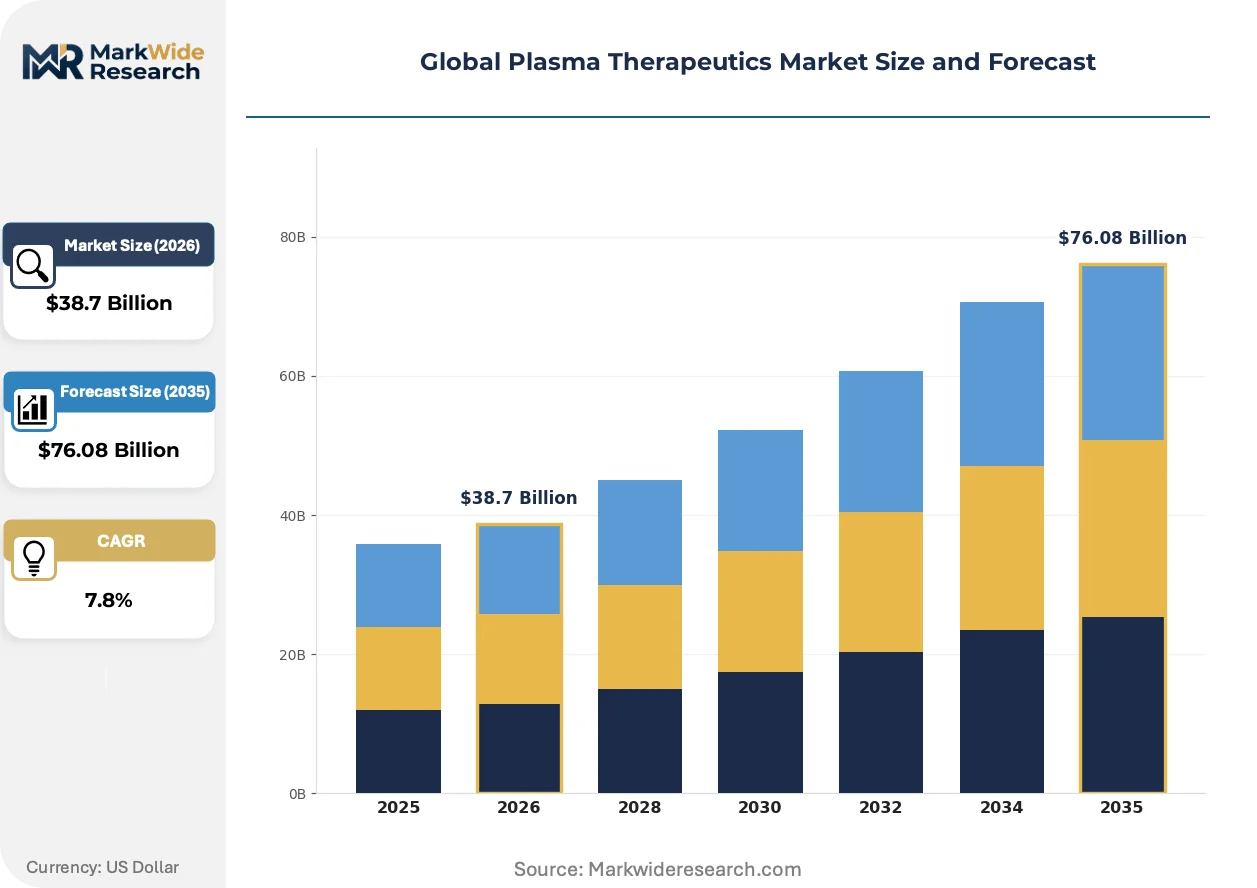
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulin, Albumin, Coagulation Factors, Hyperimmune Globulin, Plasma Derivatives Therapy Area: Primary Immune Deficiency, Neurological Disorders, Bleeding Disorders, Infectious Diseases, Critical Care End User: Blood Banks, Clinical Laboratories, Specialty Clinics, Transfusion Centers, Research Institutes Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral, Topical |
| Companies Covered | CSL Limited, Grifols, Takeda Pharmaceutical Company, Octapharma, Kedrion, Biotest, Bio Products Laboratory, LFB Group, ADMA Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plasma Therapeutics Market Shifts & Advancements
Continuous processing technologies and sustainability-driven regulatory disclosure are compressing traditional batch economics while enabling new competitive positioning through purity differentiation and carbon-accounted supply chains.
Capto MMC multimodal chromatography resins are absorbing the separation burden previously handled by sequential cold ethanol precipitation, enabling simultaneous impurity clearance and yield optimization. Specialty clinics in Germany and Japan are adopting these platforms fastest, drawn by reduced facility footprint and water consumption. The technology is absorbing capital from conventional fractionation expansions and compressing the viable scale threshold for new market entrants.
EMA's Corporate Sustainability Reporting Directive pharmaceutical extension is mandating scope 3 emissions disclosure across plasma supply chains, forcing fractionators to document collection transport and donor center energy intensity. This regulatory layer is elevating compliance costs most acutely for mid-scale European producers lacking vertically controlled donor networks. German hospital procurement coalitions are responding by embedding carbon thresholds alongside purity specifications in tender evaluations.
Patients with primary immune deficiency are compressing infusion frequency through extended half-life immunoglobulin formulations that enable monthly rather than biweekly administration. Home nursing services are displacing outpatient clinic visits as the dominant delivery channel in US and Japanese markets. This behavioral pivot is most visible among working-age cohorts prioritizing treatment schedule flexibility over institutional supervision.
Global Plasma Therapeutics Market Segmentation
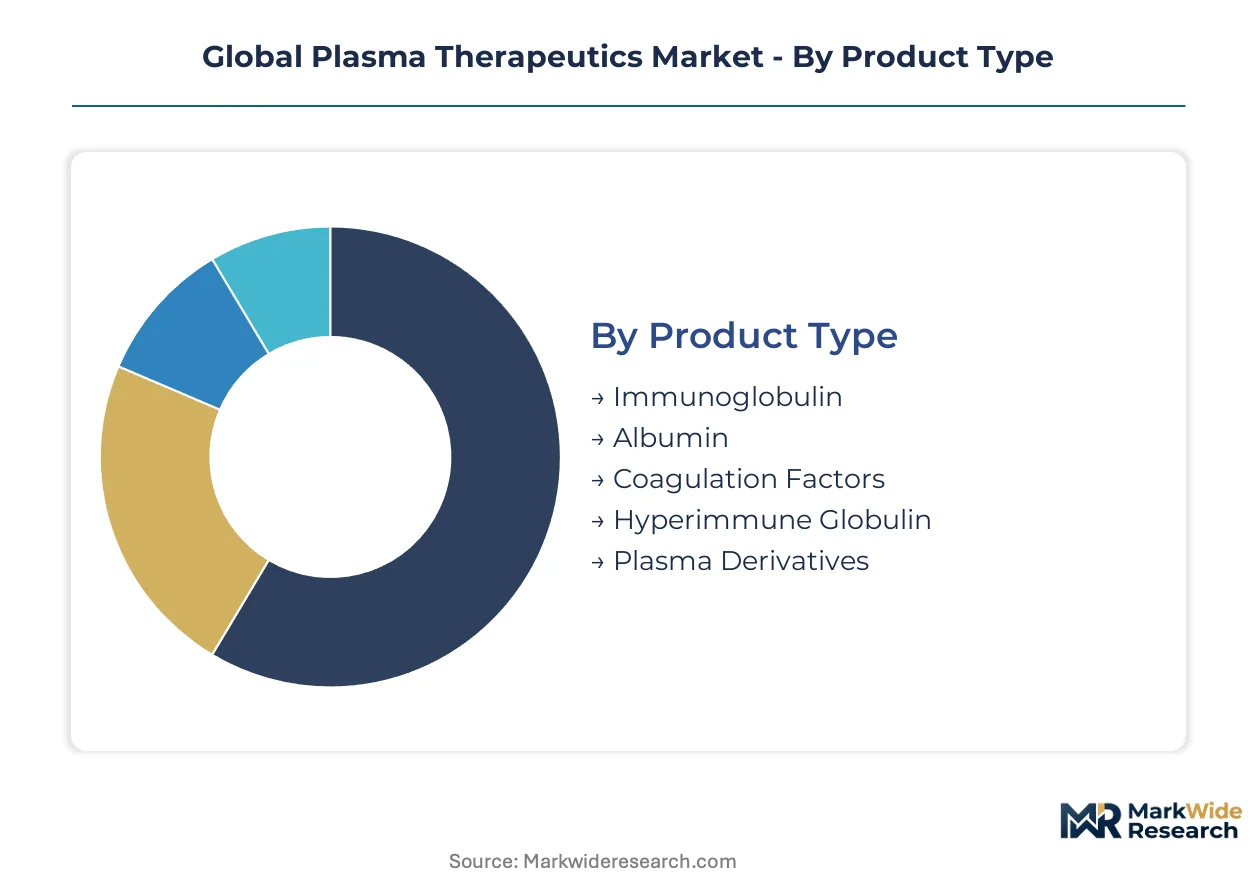
Plasma therapeutics segmentation reveals how purification technology, clinical application, and delivery infrastructure shape procurement decisions across institutional buyers. Understanding these category boundaries exposes where fractionation investment concentrates and which patient pathways drive volume economics.
Product Type:
Chromatographic separation capabilities and viral inactivation complexity differentiate margin structures across protein classes.
- Immunoglobulin:Polyclonal antibody concentrates derived from pooled plasma via cold ethanol precipitation or protein A chromatography. Chronic replacement protocols in primary immune deficiency sustain the largest revenue pool, with subcutaneous formulations capturing working-age patients seeking schedule flexibility.
- Albumin:Heat-stabilized plasma protein fraction with colloid osmotic pressure maintenance properties. Volume expansion applications in German and Japanese critical care units dominate procurement, though biosynthetic alternatives from recombinant yeast fermentation threaten pricing power in cost-sensitive health systems.
- Coagulation Factors:Factor VIII and IX concentrates for hemophilia prophylaxis, with extended half-life formulations reducing infusion frequency.
- Hyperimmune Globulin:Pathogen-specific antibody preparations from vaccinated donor pools, targeting tetanus, hepatitis B, and rabies post-exposure prophylaxis.
- Plasma Derivatives:C1 esterase inhibitor, alpha-1 antitrypsin, and fibrin sealants serving niche hereditary angioedema and surgical applications.
Mature deployment sits with Immunoglobulin. Newer deployment is concentrated in extended half-life Coagulation Factors.
Therapy Area:
Reimbursement stability and diagnostic penetration rates determine addressable patient populations across clinical indications.
- Primary Immune Deficiency:Lifelong immunoglobulin replacement for congenital antibody production failures. US specialty clinics and Japanese university hospitals anchor demand, with newborn screening expansion in Germany identifying previously undiagnosed cohorts.
- Neurological Disorders:Chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy represent expanding off-label and approved indications. IVIG protocols at US academic medical centers and French neurology departments are displacing corticosteroid-first treatment sequences.
- Bleeding Disorders:Hemophilia A and B prophylaxis with plasma-derived or recombinant factor concentrates.
- Infectious Diseases:Hepatitis B and rabies post-exposure prophylaxis using hyperimmune preparations.
- Critical Care:Albumin resuscitation and coagulopathy correction in trauma and sepsis protocols.
Volume concentration favors Primary Immune Deficiency. Steepest expansion trajectory belongs to Neurological Disorders as diagnostic coding improves.
End User:
Procurement authority and patient throughput capacity segment institutional buyers by contract scale and formulation requirements.
- Specialty Clinics:Dedicated immunology and hematology centers managing chronic replacement therapy. US independent infusion centers and German physician-owned day clinics are capturing patient volumes from hospital outpatient departments through home nursing coordination.
- Blood Banks:Collection and distribution infrastructure for fresh frozen plasma and cryoprecipitate. National blood services in Japan and regional hospital networks in France maintain fractionation partnerships or captive processing capabilities.
- Clinical Laboratories:Diagnostic testing facilities supporting immunodeficiency workup and therapeutic drug monitoring.
- Transfusion Centers:Hospital-based units managing perioperative coagulation support and massive transfusion protocols.
- Research Institutes:Academic and commercial R&D consuming rare plasma proteins for assay development and cell culture applications.
Contract value concentrates with Specialty Clinics. Procurement innovation is emerging fastest among Blood Banks exploring direct-to-patient distribution partnerships.
Delivery Mode:
Administration route determines site-of-care economics, patient compliance, and nursing resource allocation.
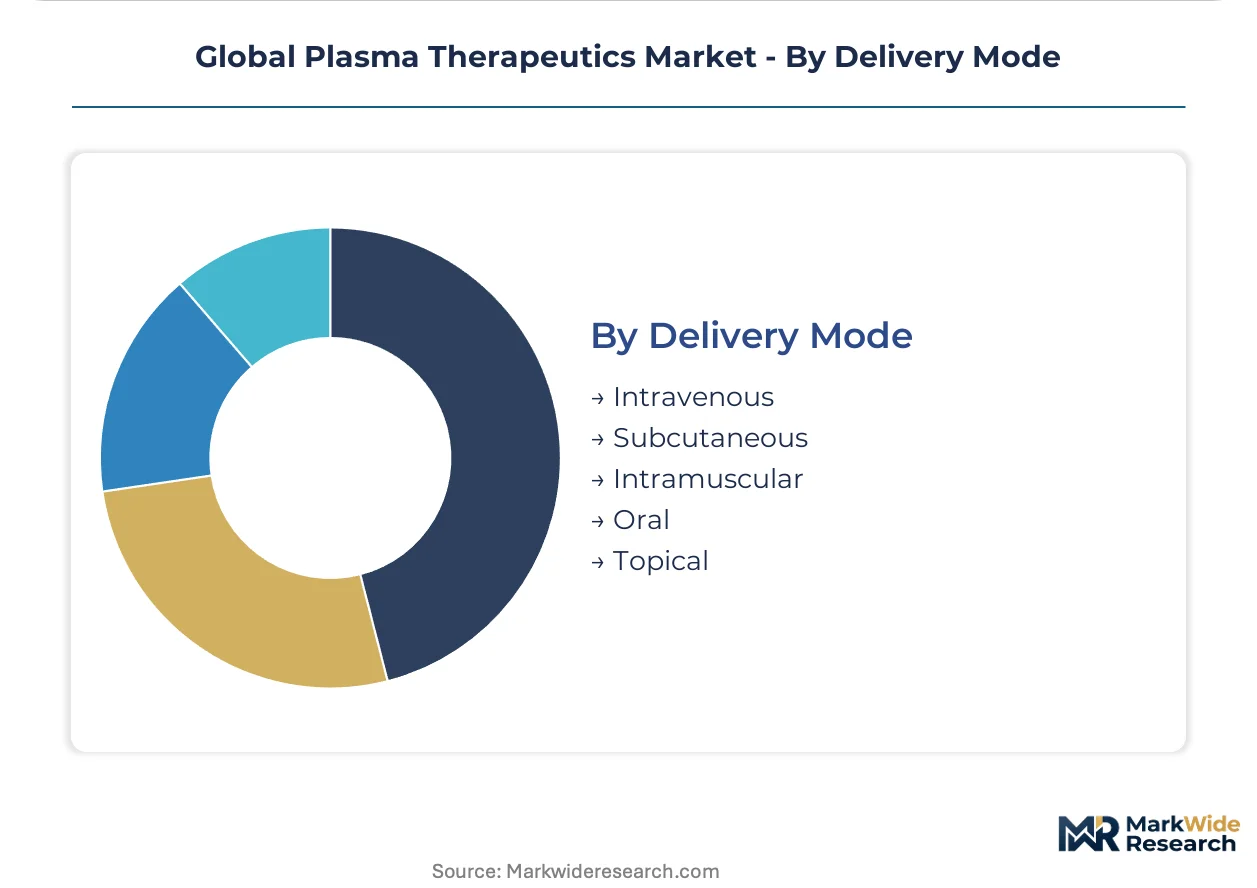
- Intravenous:Hospital or infusion center-based administration requiring venous access and monitoring infrastructure. Remains dominant for high-dose immunoglobulin loading and acute bleeding disorder episodes.
- Subcutaneous:Home-based self-administration via portable infusion pumps. US and Japanese markets show fastest uptake among primary immune deficiency patients prioritizing treatment autonomy.
- Intramuscular:Hyperimmune globulin delivery for post-exposure prophylaxis in emergency department settings.
- Oral:Limited to plasma-derived enzyme preparations and nutritional protein supplements.
- Topical:Fibrin sealants and thrombin preparations for surgical hemostasis.
Institutional preference still favors Intravenous. Patient-driven switching is concentrating most rapidly in Subcutaneous across reimbursed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Rhine-Main plasma cluster anchors European fractionation capacity, with CSL Behring's Marburg facility processing donor material from across Germany's dense collection network. The United States, Germany, and Japan concentrate the bulk of global plasma collection infrastructure and regulatory-qualified production assets.
United States
Specialty clinics in Texas and Florida drive immunoglobulin consumption for primary immune deficiency patients seeking home infusion flexibility. FDA pathogen-reduction mandates for plasma-sourced biologicals have consolidated institutional procurement around certified fractionators with validated viral inactivation protocols. The Research Triangle Park corridor in North Carolina hosts contract manufacturing organizations supporting plasma protein analytical development.
Germany
Aging cohorts in Bavaria and North Rhine-Westphalia sustain chronic replacement therapy demand for immunoglobulin and albumin. EMA's Corporate Sustainability Reporting Directive pharmaceutical extension imposes scope 3 emissions disclosure across plasma supply chains, elevating compliance costs for mid-scale producers. Frankfurt's Rhine-Main region concentrates fractionation expertise with integrated donor networks spanning Hesse and Baden-Württemberg.
Japan
Tokyo and Osaka university hospitals anchor hemophilia care with plasma-derived and recombinant factor concentrates. PMDA's biological manufacturing standards enforce stringent viral validation protocols that limit qualified import sources. The Kanto region's specialty infusion centers are expanding subcutaneous immunoglobulin protocols for working-age primary immune deficiency patients.
India
Tier-2 cities in Maharashtra and Gujarat present underpenetrated immunodeficiency diagnosis opportunities as CDSCO streamlines biological import pathways. The country's national pharmaceutical regulator is harmonizing plasma derivative registration with WHO quality guidelines to accelerate market access. Hyderabad's biotech corridor is incubating local fractionation ventures targeting domestic albumin and immunoglobulin supply security.
United Kingdom
London and Manchester hematology centers maintain plasma-derived coagulation factor procurement despite NHS England's cost-containment pressures on hemophilia care. The Medicines and Healthcare products Regulatory Agency enforces traceability requirements for plasma derivatives that align with EMA Good Manufacturing Practice directives. Oxford's research institutes consume rare plasma proteins for therapeutic protein characterization and assay development.
Global Plasma Therapeutics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purification technology sophistication and vertical control of donor networks. The market consolidates around fractionators with validated chromatographic platforms and captive plasma collection infrastructure. Three archetypes dominate: integrated multinationals with transnational donor networks, regional specialists with concentrated geographic footprints, and emerging biologics developers pursuing recombinant alternatives. Capacity expansion and regulatory certification for EMA environmental disclosure represent the dominant competitive moves.
Within the integrated multinational tier, CSL Limited and Grifols exemplify archetypes defined by geographic scope and production asset configuration. Takeda Pharmaceutical Company occupies a position representing recombinant-alternative strategies that reduce plasma dependency. These three anchors illustrate how competitive positioning diverges across sourcing models, with integrated donor networks, regional production concentration, and biotechnology substitution each commanding distinct margin structures and risk profiles.
| Leading Market Players |
|---|
| CSL Limited |
| Grifols |
| Takeda Pharmaceutical Company |
| Octapharma |
| Kedrion |
| Biotest |
| Bio Products Laboratory |
| LFB Group |
| ADMA Biologics |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty clinic networks in the United States and Germany are consolidating procurement volumes and squeezing fractionator margins through multi-year tender lock-ins, while simultaneously demanding carbon-accounted supply chains that elevate compliance costs for mid-scale producers lacking vertically controlled donor networks.
Pricing Analysis
Value-based pricing anchored to clinical outcomes in primary immune deficiency protocols separates premium chromatography-purified immunoglobulin from standard cold ethanol fractions. Price differentiation rests on viral validation tier and subcutaneous formulation convenience, with German hospital procurement coalitions embedding carbon thresholds alongside purity specifications. Cost compression in standard-grade albumin intensifies as biosynthetic alternatives from recombinant yeast fermentation gain formulary acceptance. Public blood services in Japan exhibit highest price sensitivity, while US specialty clinics absorbing home infusion services show lowest sensitivity due to reimbursement stability.
Supply Chain Analysis
Reverse-logistics frameworks for expired or temperature-deviated plasma units are emerging in Germany and Japan, with fractionators recovering salvageable proteins for non-therapeutic applications. Geographic supply concentrates in the United States, Germany, and Austria, where CSL Behring and Octapharma maintain captive collection networks. Raw material dependencies center on sodium citrate anticoagulants, chromatography resins, and viral validation reagents. Single-source vulnerability in US plasma collection infrastructure creates concentration risk during donor recruitment disruptions. Distribution runs through hospital pharmacy intermediaries and direct-to-patient nursing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing upstream control over donor networks to secure fractionation throughput and lock in institutional contracts.
For Market Incumbents: Hedge against recombinant substitution pressure by accelerating chromatography platform investments and extending half-life formulation pipelines. CSL Limited and Grifols should deepen backward integration into tier-2 city collection infrastructure in India before CDSCO import pathways fully mature. Certification investment in EMA environmental disclosure protocols will defend margin position as German hospital coalitions embed carbon thresholds in tender evaluations. For New Entrants and Emerging Players: The price-point gap between premium subcutaneous immunoglobulin and economy-grade intravenous formulations offers white-space entry in Indian tier-2 specialty clinics and Middle Eastern transfusion centers. Target underpenetrated neurological disorder indications where diagnostic coding improvements are expanding addressable populations. A go-to-market angle through direct-to-patient nursing networks bypasses hospital pharmacy intermediaries and captures margin previously lost to institutional procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European fractionators with validated viral inactivation protocols but lacking vertically controlled donor networks, as EMA sustainability benchmarks elevate fixed costs beyond their capital access. Long-term viability over the next decade hinges on chromatography yield advantages and geographic diversification beyond US-German collection dependence. Monitor CDSCO biological import pathway harmonization and PMDA subcutaneous protocol reimbursement decisions as inflection indicators for volume shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatography Platform Investment | Capto MMC multimodal resins enable simultaneous impurity clearance and yield optimization for fractionators. |
| Direct-to-Patient Distribution Buildout | Home infusion nursing networks in Texas and Florida capture margin from hospital pharmacy intermediaries. |
| EMA Environmental Disclosure Compliance | Scope 3 emissions documentation secures German hospital coalition tender eligibility against carbon thresholds. |
| Indian Collection Infrastructure Expansion | Tier-2 city donor centers in Maharashtra and Gujarat preempt CDSCO import pathway maturation. |
| Extended Half-Life Formulation Development | Monthly administration protocols attract working-age primary immune deficiency patients seeking schedule autonomy. |
Research Methodology
FDA filings, EMA regulatory submissions, and plasma fractionator annual disclosures formed the secondary backbone, supplemented by customs data on plasma derivative trade flows and hospital procurement database extracts. Primary interviews with fractionation facility directors, specialty clinic infusion center managers, blood bank procurement leads, and viral validation biochemists informed capacity utilization assumptions and technology adoption timelines. Bottom-up patient population modeling by therapy area and top-down revenue triangulation against disclosed segment sales ensured cross-validation integrity.
Historical trendline analysis of immunoglobulin and albumin volume growth anchored the baseline, with projection mechanics incorporating therapy area expansion rates, delivery mode switching patterns, and regulatory certification timelines across the analysis window. Segmentation dimensions modeled include product type purification tier, therapy area reimbursement stability, end-user procurement authority, and regional regulatory cluster stringency. CAGRs were derived from slope-adjusted trend extrapolation moderated by plasma collection constraint scenarios and recombinant substitution elasticity assumptions.
Inputs from EMA sustainability disclosure registries and PMDA biological manufacturing standards were available through the study window; gaps in real-time specialty clinic inventory data and patient-reported outcome metrics introduce uncertainty bands around subcutaneous adoption velocity. Practitioners should monitor CDSCO import pathway rulings, German hospital coalition carbon threshold implementations, and Japanese extended half-life formulation reimbursement decisions for early signals of volume and margin trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Chronic Smell and Flavor Loss Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market