
 Moderate-To-Severe Acne Therapeutics Market | 2026-2036
Moderate-To-Severe Acne Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Moderate-To-Severe Acne Therapeutics Market Foresight
Subscription-based patient support programs is pivoting how manufacturers monetize adherence beyond the pill. AbbVie leverages its immunology infrastructure to sustain dermatology prescriber loyalty. Galderma anchors its position through topical retinoid specialization. Sun Pharmaceutical Industries competes on oral isotretinoin manufacturing scale.
Moderate-to-severe acne therapeutics comprise prescription-grade pharmaceutical interventions targeting inflammatory and nodulocystic lesions, typically involving systemic retinoids, antimicrobial agents, or hormonal modulators formulated for dermal penetration and sebaceous gland regulation. These treatments serve to prevent permanent scarring and psychological morbidity in patients failing over-the-counter regimens. Oral isotretinoin commands the deepest margin pools due to REMS-controlled distribution and limited generic substitution. Dermatology clinics represent the fastest-growing application channel as physician-administered combination protocols displace monotherapy homecare. Topical delivery retains volume leadership but faces compression from novel injectable formulations in severe populations.
The FDA's iPLEDGE program and EMA's strengthened teratogenicity warnings constrain isotretinoin dispensing to certified prescribers and pharmacies, directly limiting market access velocity. The EPA and state-level environmental regulators scrutinize topical antibiotic runoff, pushing reformulation toward non-antimicrobial mechanisms. Stakeholders must monitor how FDA guidance on long-term hormonal safety reshapes patient eligibility criteria and reimbursement thresholds.
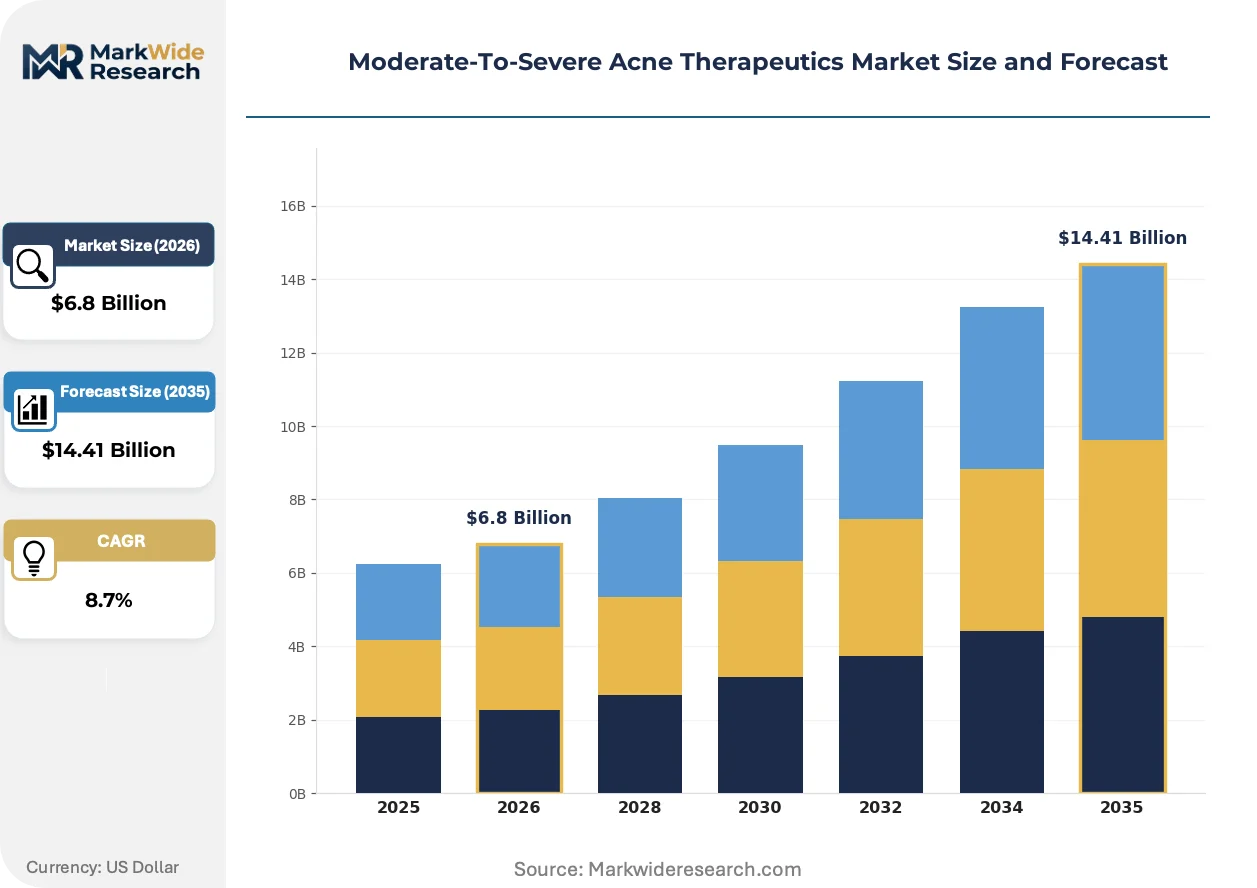
Market Dynamics
The FDA's iPLEDGE risk management program is compressing isotretinoin dispensing velocity while dermatology clinics accelerate combination protocol adoption to circumvent monotherapy limitations.
Growth Catalysts
- REMS-certified pharmacy networks:The FDA's iPLEDGE program creates controlled-access infrastructure that locks in prescriber loyalty and protects margin pools for systemic retinoid formulations.
- Dermatology clinic consolidation:Multi-site dermatology groups in the United States are standardizing physician-administered combination therapy protocols that displace homecare monotherapy.
- Sebaceous gland-targeting biologics:Novel monoclonal antibodies modulating IL-17 and IL-23 pathways are expanding the addressable population beyond retinoid-tolerant patients.
Market Restraints
- Teratogenicity surveillance costs:The FDA's iPLEDGE and EMA's strengthened pregnancy-prevention programs impose multi-layer compliance infrastructure that elevates distribution economics above small-molecule norms.
- Topical antibiotic regulatory pressure:The EPA and state-level environmental regulators scrutinize clindamycin and erythromycin runoff, forcing reformulation toward non-antimicrobial mechanisms with unproven efficacy profiles.
- Isotretinoin API concentration:Oral isotretinoin active pharmaceutical ingredient production clusters in India and China, creating single-source vulnerability for generic manufacturers.
Strategic Opportunities
- Subscription adherence platforms:Patient support programs integrating tele-dermatology, pregnancy testing logistics, and pharmacy coordination are capturing recurring revenue beyond drug dispensing.
- Hormonal modulator expansion:The FDA's evolving guidance on long-term androgen suppression creates eligibility criteria white space for spironolactone and combined oral contraceptives in treatment-resistant female patients.
- Injectable retinoid formulations:Depot delivery technologies bypassing first-pass hepatic metabolism are targeting severe nodulocystic populations with compliance barriers to daily oral regimens.
Industry Challenges
- REMS coordinator talent scarcity:Certified iPLEDGE prescriber and pharmacy designations require specialized training pipelines that dermatology groups struggle to staff at scale.
- Combination protocol standardization:Physician-administered regimens mixing topical retinoids, antimicrobials, and corticosteroids lack consensus guidelines, creating liability exposure and reimbursement friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moderate-To-Severe Acne Therapeutics Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Retinoids, Oral Antibiotics, Hormonal Treatments, Isotretinoin Application: Dermatology Clinics, Homecare, Hospitals, Research Institutions Delivery Mode: Oral, Topical, Injectable, Transdermal End User: Patients, Dermatologists, Pharmacies, Research Organizations |
| Companies Covered | AbbVie, Bausch Health, Galderma, Pfizer, Novartis, Bayer, Johnson & Johnson, Sun Pharmaceutical Industries, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moderate-To-Severe Acne Therapeutics Market Shifts & Advancements
Artificial intelligence diagnostic tools and novel delivery mechanisms are compressing the gap between clinical assessment and personalized therapy selection in dermatology practice.
Machine learning algorithms analyzing lesion photography and sebum biomarkers are automating severity stratification and treatment matching previously requiring specialist consultation. Large dermatology groups in the United States are deploying these platforms across satellite clinics to extend prescriber reach. The technology is automating patient triage into oral isotretinoin, hormonal therapy, or biologic pathways based on predicted response profiles.
The EMA's strengthened pharmacovigilance requirements for teratogenic drugs are extending documentation burdens beyond the FDA's iPLEDGE framework into European dispensing protocols. Manufacturers must now maintain pregnancy-prevention registries across multiple national competent authorities with non-harmonized reporting timelines. Oral isotretinoin marketers in Germany, France, and Italy are consolidating distribution through specialty pharmacy networks capable of cross-border compliance management.
Patients are demanding unbundled care pathways separating diagnostic assessment, prescription fulfillment, and ongoing monitoring into distinct purchasing decisions. Tele-dermatology platforms are capturing the initial consultation segment while traditional clinics retain procedural revenue from extractions and steroid injections. This fragmentation is most visible in the United States, where high-deductible health plans drive price transparency tools and pharmacy shopping behavior previously suppressed by integrated benefit design.
Moderate-To-Severe Acne Therapeutics Market Segmentation
Moderate-to-severe acne therapeutics fragment across four critical dimensions that determine pricing power, regulatory exposure, and channel economics. Product type and delivery mode concentrate margin capture, while application and end-user categories dictate compliance infrastructure requirements.
Product Type:
Volume leadership sits with mass-market formulations, while premium pools concentrate in REMS-controlled systemics.
- Topical Retinoids:First-line comedolytic agents including adapalene and tazarotene penetrate sebaceous follicles to normalize keratinization. Dermatology clinics in the United States favor these for maintenance protocols following isotretinoin courses, though generic substitution compresses realized prices.
- Isotretinoin:Oral 13-cis-retinoic acid remains the only true disease-modifying therapy for nodulocystic acne. FDA's iPLEDGE program restricts dispensing to certified prescribers and pharmacies, creating artificial scarcity that sustains manufacturer margin pools despite API commoditization.
- Oral Antibiotics:Doxycycline and minocycline target inflammatory lesions through antimicrobial and anti-inflammatory mechanisms. Rising EPA scrutiny of wastewater contamination is forcing reformulation toward sub-antimicrobial dosing with unproven efficacy profiles.
- Hormonal Treatments:Spironolactone and combined oral contraceptives modulate androgen-driven sebum production in female patients. EMA's evolving guidance on long-term endocrine safety is expanding prescriber caution and eligibility screening burdens.
Today's leader: Isotretinoin. Tomorrow's challenger: Hormonal treatments.
Application:
Channel selection determines protocol complexity and reimbursement capture rates.
- Dermatology Clinics:Physician-administered settings enable combination therapy protocols mixing retinoids, antimicrobials, and procedural interventions. Multi-site dermatology groups in the United States standardize these regimens across satellite locations, displacing monotherapy homecare.
- Homecare:Patient-directed administration of topical formulations and oral antibiotics dominates prescription volume but faces adherence gaps and inferior outcomes in severe populations. Tele-dermatology platforms are capturing initial triage while pushing fulfillment toward mail-order pharmacies.
- Hospitals:Acute care settings manage acne fulminans and severe inflammatory flares requiring intravenous corticosteroids. Limited dedicated dermatology staffing restricts protocol standardization outside academic medical centers.
- Research Institutions:Clinical trial sites generate safety and efficacy data for novel biologics and delivery technologies. Investigator-sponsored studies concentrate at university hospitals with established acne specialty programs.
Channel economics favor dermatology clinics for margin; homecare retains volume dominance.
Delivery Mode:
Route of administration dictates pharmacokinetic profiles and patient compliance economics.
- Oral:Systemic absorption enables treatment of deep inflammatory and nodulocystic lesions inaccessible to topical agents. First-pass hepatic metabolism limits bioavailability and drives dose escalation requirements.
- Topical:Direct dermal application minimizes systemic exposure but requires patient adherence to multi-step regimens. Formulation innovation focuses on micronized particle sizes and novel vehicles to enhance follicular penetration.
- Injectable:Depot retinoid formulations bypass hepatic metabolism and address compliance barriers in recalcitrant severe populations. Development pipelines target quarterly dosing intervals to displace daily oral isotretinoin.
- Transdermal:Patch and microneedle technologies enable sustained release of hormonal modulators with reduced hepatic load. Limited commercial availability restricts adoption to clinical trial settings.
Oral dominates current revenue; injectable represents steepest expansion trajectory.
End User:
Stakeholder influence over prescribing decisions fragments across clinical, commercial, and regulatory domains.
- Patients:Treatment-resistant individuals with prior OTC failure drive demand for prescription escalation. High-deductible health plans in the United States are producing price-sensitive pharmacy shopping behavior and adherence gaps.
- Dermatologists:Board-certified specialists control isotretinoin prescribing through iPLEDGE certification and combination protocol design. Prescriber loyalty programs and continuing medical education investments sustain manufacturer relationships.
- Pharmacies:REMS-certified specialty pharmacies manage pregnancy testing logistics and dispensing authorization. Consolidation among specialty pharmacy networks is reducing independent retail participation in isotretinoin distribution.
- Research Organizations:Contract research organizations and academic centers generate real-world evidence and post-marketing surveillance data. Registry maintenance requirements for teratogenic drugs expand service revenue opportunities.
Dermatologists anchor prescribing control; pharmacies capture logistics value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States captures premium therapy margins through iPLEDGE-controlled distribution, while India concentrates generic oral isotretinoin API production for cost-sensitive export markets.
United States
Specialty dermatology access and high-deductible health plan dynamics drive prescription escalation toward physician-administered combination protocols. The FDA's iPLEDGE REMS program restricts isotretinoin dispensing to certified prescribers and pharmacies, creating artificial scarcity that sustains manufacturer margins. Multi-site dermatology groups in Texas and Florida standardize these regimens across satellite clinics, displacing homecare monotherapy with higher-revenue in-office administration.
Germany
EMA's strengthened pharmacovigilance requirements for teratogenic drugs extend documentation burdens beyond FDA-equivalent frameworks into national dispensing protocols. The country's national pharmaceutical regulator mandates pregnancy-prevention registries with non-harmonized reporting timelines across EU competent authorities. Specialty pharmacy networks in Bavaria and North Rhine-Westphalia consolidate isotretinoin distribution through cross-border compliance management capabilities.
India
Domestic API manufacturing concentration for oral isotretinoin creates single-source vulnerability for generic manufacturers serving export markets. The Central Drugs Standard Control Organization enforces manufacturing facility inspections that shape export eligibility for US and European markets. Pharmaceutical production clusters in Gujarat and Maharashtra supply active pharmaceutical ingredients to formulation facilities across emerging markets.
Japan
Ministry of Health, Labour and Welfare oversight of systemic retinoid prescribing limits market access velocity through prescriber certification requirements. The Pharmaceuticals and Medical Devices Agency maintains distinct pregnancy-prevention protocols that diverge from FDA iPLEDGE and EMA frameworks. Academic medical centers in Tokyo and Osaka concentrate investigator-sponsored studies for novel biologic therapies targeting IL-17 and IL-23 pathways.
Brazil
Treatment-resistant patient populations in urban centers drive demand for prescription escalation beyond over-the-counter regimens. ANVISA's regulatory framework for teratogenic drugs imposes dispensing controls that mirror REMS-like infrastructure with localized compliance requirements. Dermatology practice consolidation in São Paulo and Rio de Janeiro enables standardized combination therapy protocols previously limited to hospital-based specialty care.
Moderate-To-Severe Acne Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with REMS-controlled systemics concentrating margin capture among certified prescribers while generic API production fragments across Asian manufacturing networks. The market structure tiers between premium disease-modifying therapies and commoditized topical formulations. Three archetypes dominate: immunology-anchored dermatology platforms, topical retinoid specialists, and oral isotretinoin scale manufacturers. Competitive moves concentrate on prescriber loyalty investments and specialty pharmacy network consolidation rather than direct price competition.
Within the immunology-anchored tier, AbbVie leverages existing infrastructure to sustain dermatology prescriber relationships across multiple therapeutic areas. Galderma occupies a position exemplifying topical retinoid specialization with deep formulation expertise in follicular penetration technologies. Sun Pharmaceutical Industries represents the scale-driven archetype for oral isotretinoin API and finished dosage manufacturing. These three anchors demonstrate how competitive positioning stratifies across regulatory control, formulation science, and manufacturing throughput rather than overlapping product substitution.
| Leading Market Players |
|---|
| AbbVie |
| Bausch Health |
| Galderma |
| Pfizer |
| Novartis |
| Bayer |
| Johnson & Johnson |
| Sun Pharmaceutical Industries |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Injectable retinoid formulation development is simultaneously elevating R&D cost structures and concentrating manufacturing partnerships among specialized sterile fill-finish facilities in the United States and Europe. This technological transition reinforces pricing power for depot delivery systems while compressing margins for commoditized oral isotretinoin exposed to API oversupply from Indian and Chinese manufacturers.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for oral isotretinoin API while REMS-controlled distribution sustains premium capture for systemic retinoids. Three-tier pricing structure across REMS-certified specialty, standard retail pharmacy, and economy generic channels reflects certification grade and prescriber access control. Price erosion runs through unbranded oral antibiotics facing EPA-driven reformulation costs. High-deductible health plan enrollees exhibit greatest price sensitivity, driving pharmacy shopping behavior that undermines prescriber-directed channel loyalty.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biologics is elevating landed costs for sebaceous gland-targeting monoclonal antibodies sourced from European contract manufacturing organizations. Active pharmaceutical ingredient production clusters in India and China, with sterile formulation finishing in the United States and Germany. Supply chain risk centers on single-source vulnerability for isotretinoin API concentration in Gujarat manufacturing corridors. Distribution runs through REMS-certified specialty pharmacy networks capable of managing pregnancy-prevention logistics and prescriber authorization workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA iPLEDGE program tightening and EMA pharmacovigilance expansion continuously elevate compliance infrastructure as a competitive moat. The regulatory milestone of harmonized teratogenicity surveillance across North American and European frameworks is driving demand for integrated patient support platforms that monetize adherence beyond drug dispensing.
For Market Incumbents: Lock in prescriber loyalty through subsidized iPLEDGE coordinator training programs and exclusive continuing medical education partnerships with multi-site dermatology groups. Defend against generic oral isotretinoin margin compression by backward integration into API manufacturing or exclusive supply agreements with Indian producers. Expand subscription adherence platforms to capture recurring revenue from pregnancy testing logistics and tele-dermatology coordination.
For New Entrants and Emerging Players: FDA guidance evolution on long-term hormonal safety in the United States opens a window for spironolactone and combined oral contraceptive formulations targeting treatment-resistant female populations underserved by retinoid intolerance. Target hormonal modulator segments with unbundled diagnostic-to-prescription pathways separating initial consultation from ongoing monitoring. Pursue white-space positioning through tele-dermatology platforms capturing initial patient triage while pushing fulfillment toward mail-order pharmacy partnerships.
For Investors and Strategic Acquirers: Valuations sit cheapest among topical retinoid specialists facing generic substitution pressure and lacking REMS-controlled distribution infrastructure. Long-term viability over the next decade rests on regulatory capture through certification investments and specialty pharmacy network consolidation rather than product innovation cycles. Monitor FDA iPLEDGE program modifications and EMA pregnancy-prevention registry harmonization as inflection indicators for distribution economics restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Investment | Creates controlled-access infrastructure that locks in prescriber loyalty and protects margin pools. |
| Specialty Pharmacy Network Consolidation | Enables cross-border compliance management for teratogenic drugs across FDA and EMA jurisdictions. |
| Injectable Retinoid Development | Bypasses first-pass hepatic metabolism to address compliance barriers in severe nodulocystic populations. |
| Tele-Dermatology Platform Integration | Captures initial consultation segment while traditional clinics retain procedural revenue from extractions. |
| API Manufacturing Scale-Up | Reduces single-source vulnerability from Indian and Chinese production concentration for oral isotretinoin. |
Research Methodology
Multiple input streams — structured interviews with dermatology practice administrators, regulatory affairs specialists at REMS-certified manufacturers, specialty pharmacy logistics directors, and formulary access managers at national payers — were reconciled against secondary validation from FDA iPLEDGE program documentation, EMA pharmacovigilance registries, ClinicalTrials.gov acne therapy listings, and customs records for isotretinoin API trade flows. Bottom-up prescription volume modeling and top-down therapeutic category revenue estimates were triangulated to constrain forecast variance.
Data-stream reconciliation across product type, delivery mode, application channel, and end-user stakeholder dimensions enabled segmentation-specific growth trajectory calibration throughout the forecast period. CAGRs were derived from fitted trend extrapolation moderated by regulatory event probability weighting. Forecast inputs incorporated iPLEDGE prescriber certification velocity, dermatology clinic consolidation rates, and hormonal therapy eligibility criteria evolution.
Revisions become necessary when FDA iPLEDGE program structural modifications, EMA pregnancy-prevention registry harmonization delays, or API manufacturing facility inspection failures by CDSCO materialize unexpectedly. Forecasts reflect documented assumptions subject to regulatory enforcement intensity and prescriber behavior adaptation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Healthcare Specialty Enzymes Market