
 Lab Automation in Clinical Diagnostics Market | 2026-2036
Lab Automation in Clinical Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Automation in Clinical Diagnostics Market Foresight
EU IVDR is recalibrating the cost-of-entry calculus for diagnostic automation vendors seeking European market access. Siemens Healthineers leverages its deep installed base of immunoassay platforms to sustain service revenue streams across centralized lab networks. Roche Diagnostics anchors its competitive position through captive supply of reagent chemistries tied to proprietary instrumentation. Abbott Laboratories differentiates via point-of-care automation bridges that connect distributed testing to core laboratory information systems.
Lab automation in clinical diagnostics encompasses integrated hardware-software systems that execute pre-analytical, analytical, and post-analytical workflows with minimal human intervention, typically achieving throughput rates exceeding 1,000 tests per hour on high-volume chemistry and immunoassay lines. These systems primarily serve to reduce turnaround time, minimize pre-analytical errors, and enable continuous operation in high-throughput clinical environments. Automated analyzers command the largest installed base and associated consumable revenue pools, while AI-based diagnostics represents the fastest-expanding technology segment as laboratories deploy machine learning for quality control flagging and result interpretation. Liquid handling systems retain structural importance in genetic analysis workflows, where precision pipetting directly affects downstream sequencing accuracy.
FDA 510(k) clearance requirements shape product development timelines for US-bound automation platforms, while EU IVDR technical documentation demands are extending conformity assessment durations for European market entry. ISO 15189 accreditation standards drive hospital and diagnostic lab purchasing criteria toward closed-system automation with embedded quality management modules. Stakeholders must weigh the capital intensity of full-workflow automation against modular upgrade paths that preserve existing analyzer investments while meeting evolving regulatory documentation burdens.
Market Dynamics
Hospital laboratories are consolidating pre-analytical, analytical, and post-analytical workflows around integrated automation platforms to manage throughput demands exceeding 1,000 tests per hour while EU IVDR compliance deadlines compress vendor certification timelines.
Growth Catalysts
- Rising test volumes in hospital laboratories:Acute care facilities are automating chemistry and immunoassay lines to reduce turnaround time and minimize pre-analytical specimen handling errors during continuous operation.
- EU IVDR technical documentation mandates:The regulation's extended conformity assessment durations are accelerating replacement cycles for legacy systems that cannot meet embedded quality management module requirements.
- AI-based quality control flagging:Machine learning algorithms deployed for result interpretation are expanding the addressable scope of automated analyzer installations beyond high-throughput core labs.
Market Restraints
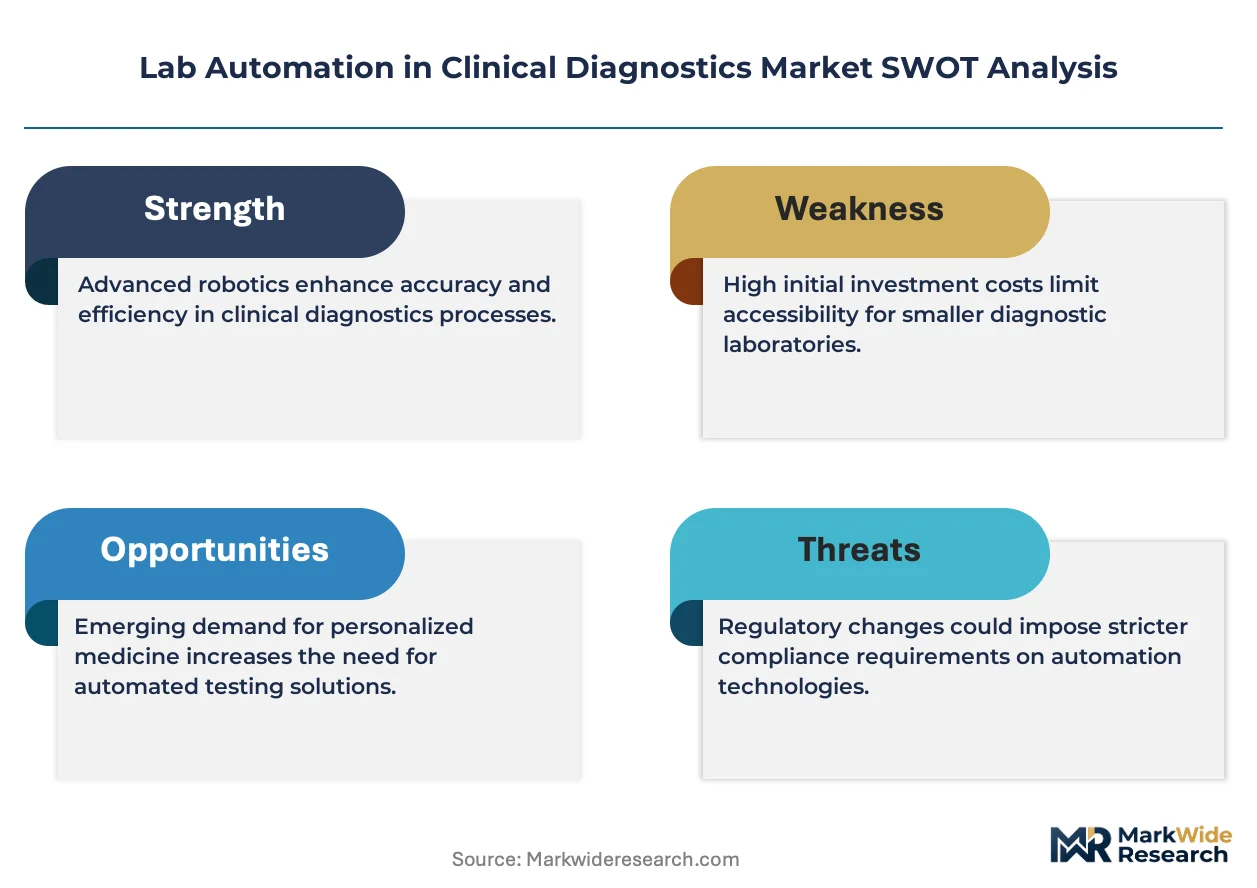
- Capital intensity of full-workflow automation:Closed-system platforms with captive reagent chemistries require substantial upfront investment that constrains modular upgrade paths for mid-sized diagnostic facilities.
- Reagent supply concentration:Proprietary chemistry dependencies tied to specific instrumentation lock purchasers into single-vendor consumable streams with limited price negotiation leverage.
- ISO 15189 accreditation documentation burdens:Hospital and diagnostic lab purchasing criteria increasingly demand embedded quality management modules that extend procurement evaluation cycles.
Strategic Opportunities
- Point-of-care automation bridges:Distributed testing platforms that connect to core laboratory information systems represent underpenetrated white space between centralized labs and satellite clinics.
- Liquid handling precision in genetic analysis:Pipetting accuracy requirements for downstream sequencing workflows are creating demand for specialized automation in molecular diagnostics.
- FDA 510(k) clearance pathway optimization:Streamlined premarket notification processes for US-bound platforms offer faster commercialization timelines compared to EU IVDR technical documentation demands.
Industry Challenges
- Integration complexity with legacy analyzers:Existing immunoassay and chemistry platform investments complicate migration paths to fully integrated pre-analytical and post-analytical modules.
- Specialized technician training requirements:Automated systems demand personnel proficient in both hardware maintenance and software-driven quality control protocols, constraining workforce availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Automation in Clinical Diagnostics Market |
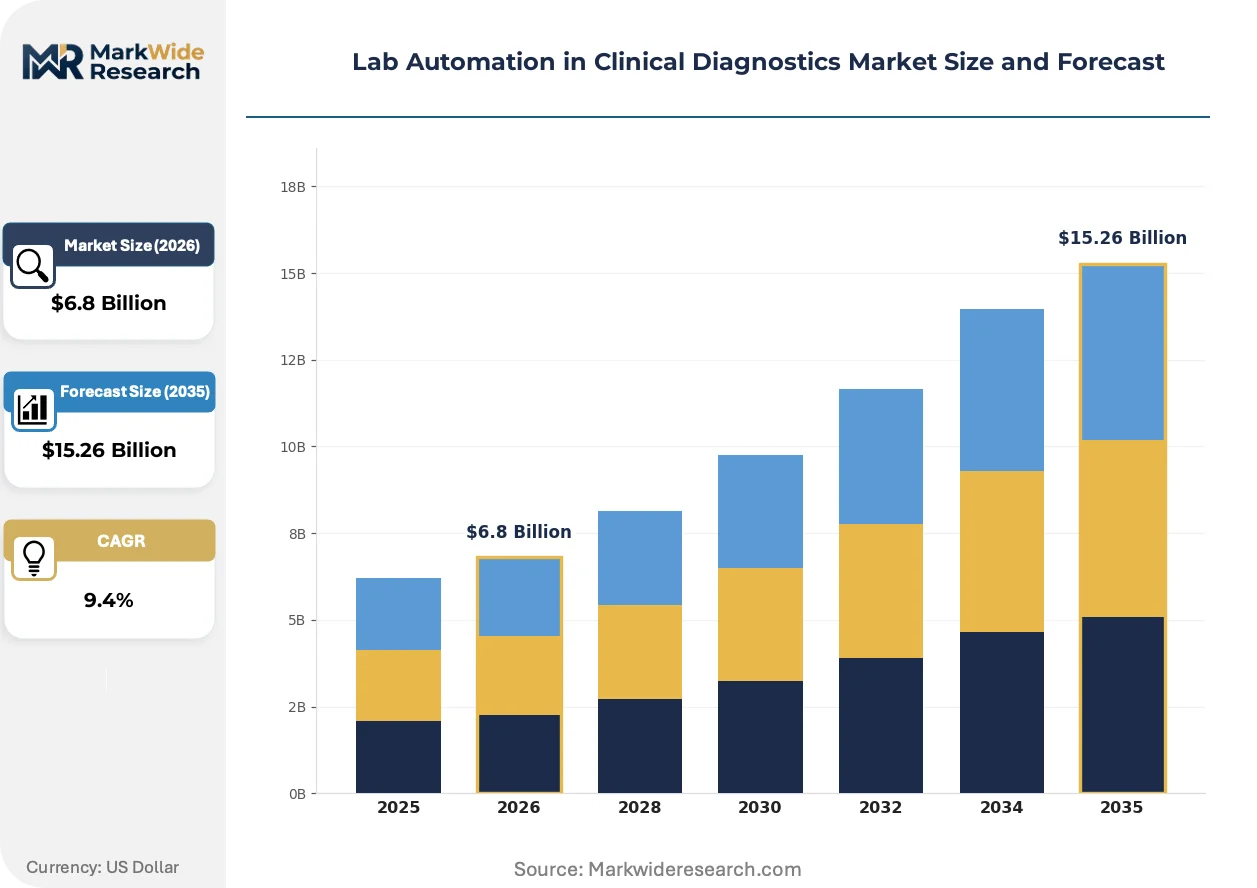
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid handling systems, Automated анализers, Robotics, Software solutions Technology: Microfluidics, LIMS, AI-based diagnostics, Barcode scanning End User: Central laboratories, Clinical research organizations, Hospitals, Diagnostic labs Application: Infectious disease testing, Genetic analysis, Blood testing, Toxicology |
| Companies Covered | Abbott Laboratories, Inpeco, Siemens Healthineers, A&T Corporation, Hitachi High-Tech, Roche Diagnostics, Sysmex Corporation, Shenzhen Mindray Bio-Medical Electronics, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Automation in Clinical Diagnostics Market Shifts & Advancements
Artificial intelligence is embedding into quality control workflows while regulatory frameworks on both sides of the Atlantic recalibrate product development timelines and buyer procurement criteria.
Machine learning algorithms are rewriting how clinical laboratories manage result validation and error flagging. Reference laboratories in Germany and hospital networks in the United States are deploying AI-driven quality control systems at accelerating rates. This technology is compressing the manual review burden while expanding the diagnostic accuracy thresholds that automated platforms must achieve.
EU IVDR technical documentation requirements are extending conformity assessment durations for automation vendors seeking European market access. The regulation's embedded quality management module mandates are reshaping product architecture decisions during early development phases. High-throughput chemistry and immunoassay lines face the steepest compliance recalibration as manufacturers restructure technical files to meet notified body expectations.
Service unbundling from analyzer hardware contracts is altering how hospital laboratories negotiate vendor relationships. Buyers are separating maintenance agreements from reagent supply commitments to retain procurement flexibility. This pattern is most visible in German reference laboratories consolidating around integrated platforms while preserving modular service provider options.
Lab Automation in Clinical Diagnostics Market Segmentation
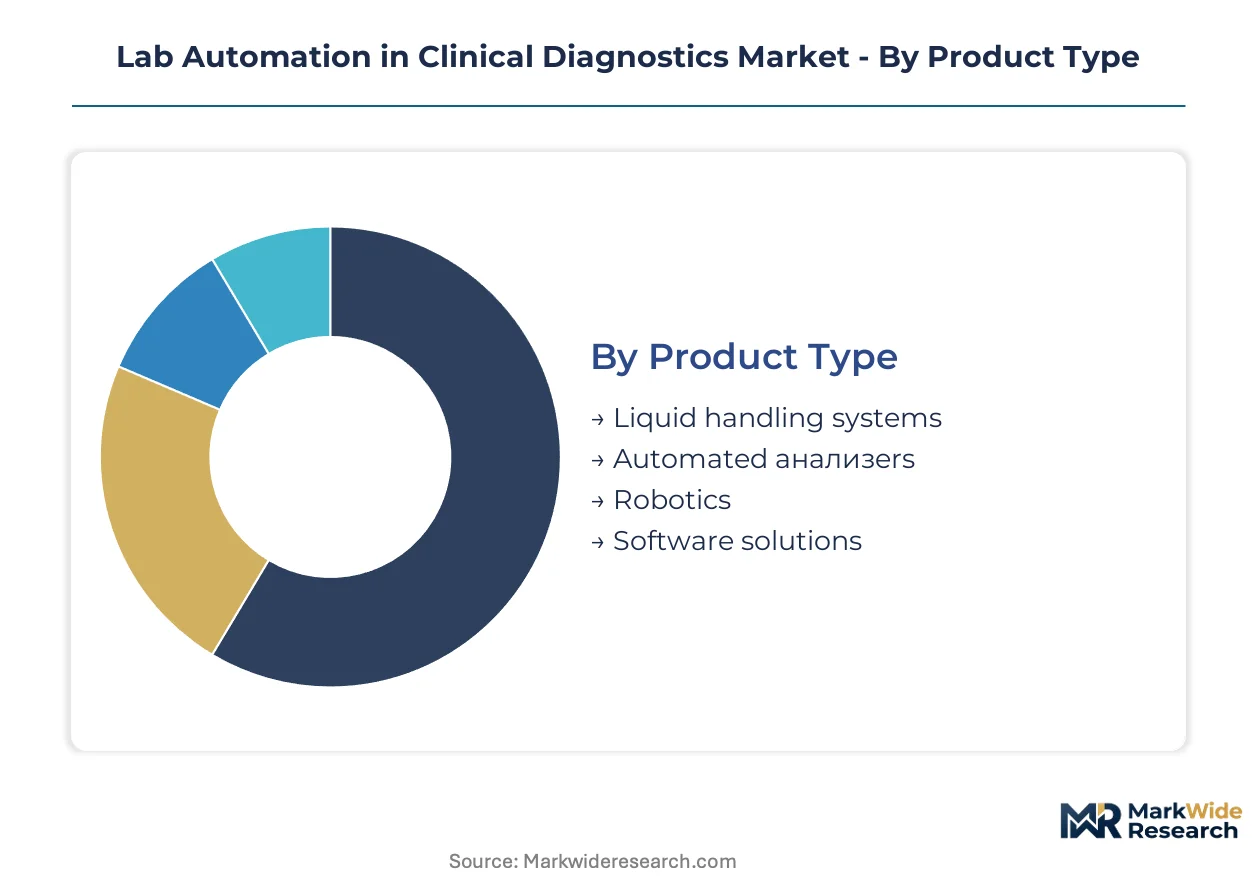
Automation vendors calibrate product portfolios around distinct workflow intensities and regulatory compliance tiers. Segmentation reveals where capital deployment concentrates and which upgrade cycles offer the shortest path to revenue capture.
Product Type:
Replacement cycles diverge sharply between hardware-intensive platforms and software-layer investments, with hospitals weighing modular upgrades against full-workflow overhauls.
- Automated analyzers:Chemistry and immunoassay platforms achieving throughput rates exceeding 1,000 tests per hour anchor the largest installed base and consumable revenue pools. Demand concentrates in German reference laboratories consolidating workflows around integrated lines, driven by EU IVDR embedded quality management mandates that accelerate legacy system retirements.
- Liquid handling systems:Precision pipetting workstations execute pre-analytical specimen processing with direct impact on downstream sequencing accuracy. Clinical research organizations in the United States prioritize these systems for genetic analysis workflows, constrained by specialized technician training requirements that limit workforce scalability.
- Robotics:Articulated arm systems and track-based transport modules automate specimen movement between processing stations.
- Software solutions:Laboratory information system middleware and quality control analytics platforms enable interoperability between distributed testing sites.
Automated analyzers sit at the top of the volume ranking, with software solutions climbing the fastest.
Technology:
Adoption timelines stretch across maturity gradients, from established infrastructure to emerging validation requirements.
- AI-based diagnostics:Machine learning algorithms deployed for quality control flagging and result interpretation are expanding the addressable scope of analyzer installations beyond high-throughput core labs. Hospital laboratories in the United States deploy these systems at accelerating rates, compressing manual review burdens while FDA 510(k) clearance pathways shape product development timelines.
- LIMS:Laboratory information management systems orchestrate data flow between pre-analytical, analytical, and post-analytical modules. Central laboratories demand these platforms for ISO 15189 accreditation compliance, with procurement evaluation cycles extending due to embedded quality management documentation requirements.
- Microfluidics:Miniaturized fluid manipulation technologies enable point-of-care testing with reduced specimen volumes.
- Barcode scanning:Specimen identification and tracking infrastructure underpins error reduction in high-throughput environments.
AI-based diagnostics commands the steepest expansion trajectory, while barcode scanning retains the broadest penetration base.
End User:
Capital intensity thresholds and regulatory exposure levels sort buyers into distinct procurement cadences.
- Hospitals:Acute care facilities automate chemistry and immunoassay lines to manage continuous operation demands and minimize pre-analytical specimen handling errors. Demand concentrates in hospital laboratories consolidating workflows around integrated platforms, with EU IVDR compliance deadlines compressing vendor certification timelines for European market access.
- Central laboratories:High-throughput reference facilities process population-scale testing volumes with minimal turnaround time tolerance. German laboratories anchor demand in this segment, consolidating around integrated platforms while negotiating service unbundling from hardware contracts to preserve procurement flexibility.
- Diagnostic labs:Specialized testing facilities focus on specific analyte categories or patient populations.
- Clinical research organizations:Contract research entities demand precision automation for protocol-driven specimen processing in drug development workflows.
Hospitals dominate absolute spending, with clinical research organizations gaining share fastest.
Application:
Test complexity and reimbursement dynamics determine automation ROI calculations across diagnostic categories.
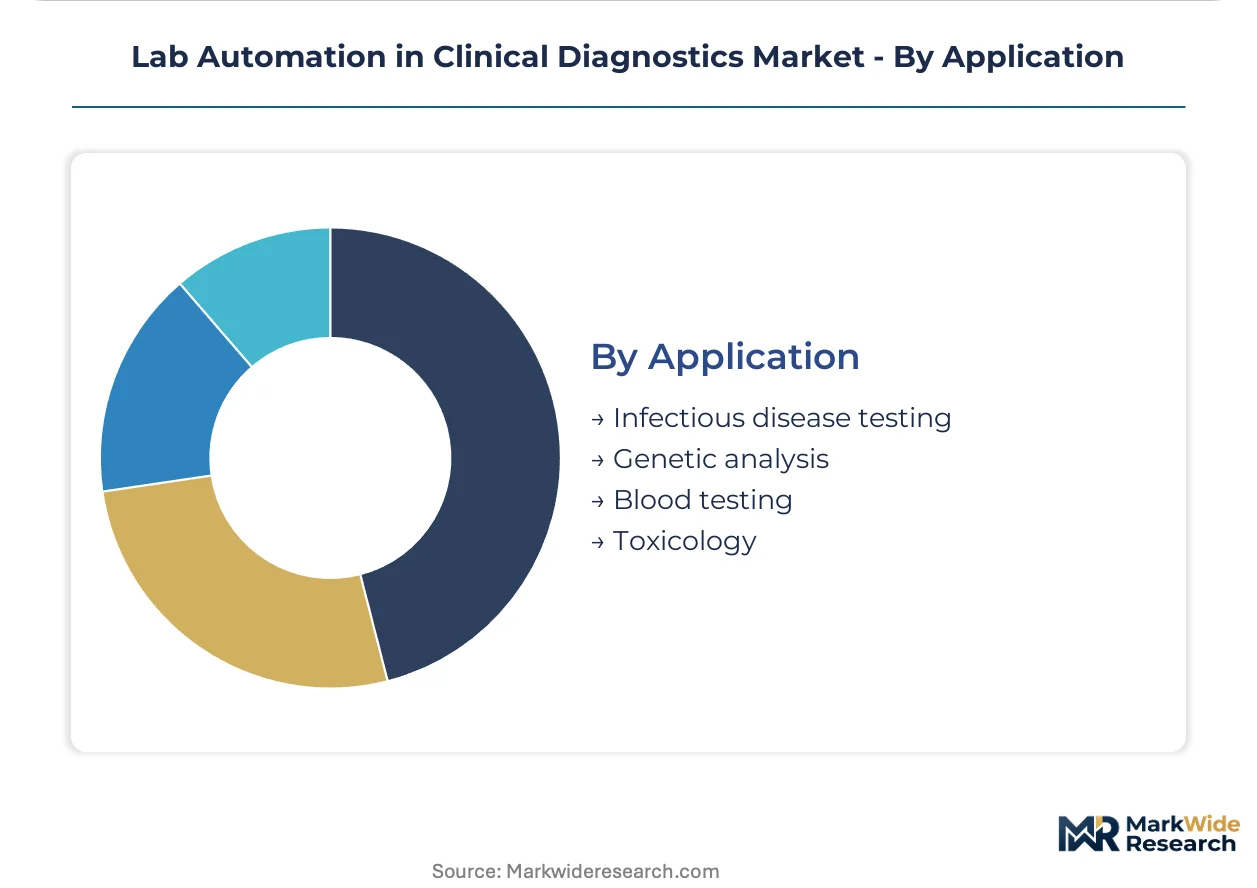
- Genetic analysis:Next-generation sequencing workflows demand liquid handling precision that directly affects downstream accuracy. Clinical research organizations and hospital laboratories in the United States concentrate investment here, with specialized technician training requirements constraining workforce availability for platform operation.
- Infectious disease testing:High-volume PCR and immunoassay workflows for pathogen detection run continuously in acute care settings. Hospital laboratories automate these lines to reduce turnaround time during outbreak response, with reagent supply concentration locking purchasers into single-vendor consumable streams.
- Blood testing:Routine hematology and chemistry panels constitute the highest test volume category.
- Toxicology:Forensic and clinical toxicology workflows require specialized sample preparation and detection methodologies.
Blood testing holds the largest test volume position, with genetic analysis expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technician training programs in Germany, the United States, and Japan anchor the geographic concentration of lab automation expertise. Hospital laboratories and reference facilities in these markets drive procurement volumes while navigating distinct regulatory certification timelines.
United States
Hospital networks in the United States automate chemistry and immunoassay lines to manage continuous operation demands exceeding 1,000 tests per hour. FDA 510(k) clearance requirements compress product development timelines for domestic vendors. Clinical research organizations in Greater Boston and the Research Triangle concentrate investment in liquid handling systems for genetic analysis workflows.
Germany
German reference laboratories consolidate workflows around integrated automation platforms to meet EU IVDR embedded quality management mandates. The regulation's extended conformity assessment durations accelerate replacement cycles for legacy systems. Industrial clusters in North Rhine-Westphalia and Bavaria anchor demand for high-throughput chemistry analyzers with captive reagent supply chains.
Japan
Japanese hospital laboratories deploy AI-based quality control flagging systems to compress manual review burdens. PMDA regulatory frameworks shape domestic product certification timelines for automation vendors. The Kanto region around Tokyo concentrates installed base expansion for immunoassay platforms serving aging population screening programs.
China
Chinese diagnostic facilities scale automated analyzer installations to manage rising test volumes in tier-one hospital networks. NMPA medical device registration requirements extend commercialization timelines for imported platforms. The Yangtze River Delta region around Shanghai anchors demand for modular automation upgrades that preserve existing hardware investments.
Switzerland
Swiss diagnostic laboratories prioritize ISO 15189 accreditation compliance in procurement criteria for closed-system automation. Swissmedic regulatory oversight shapes quality management module requirements for European market entry. The Basel-Zurich corridor concentrates reference laboratory automation serving cross-border pharmaceutical clinical trial workflows.
Lab Automation in Clinical Diagnostics Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with deep installed bases of immunoassay and chemistry platforms. Consolidation dynamics concentrate revenue pools among vendors with captive reagent chemistries and service infrastructure spanning centralized lab networks. Three archetypes dominate: integrated platform specialists with full-workflow automation portfolios, point-of-care bridge developers connecting distributed testing to core systems, and precision liquid handling suppliers for molecular diagnostics. M&A activity targets complementary software layers for AI-driven quality control, while strategic partnerships address EU IVDR technical documentation burdens through shared notified body engagements.
Among diversified health technology conglomerates, Abbott Laboratories, Siemens Healthineers, and Roche Diagnostics exemplify distinct competitive positioning archetypes. Abbott represents point-of-care automation bridge development, connecting satellite clinics to core laboratory information systems. Siemens Healthineers anchors the installed base leverage archetype, sustaining service revenue streams across German and US hospital networks. Roche Diagnostics occupies the captive chemistry supply position, securing consumable revenue through proprietary reagent-instrumentation binding. These three entities collectively illustrate how vendor strategy diverges across workflow integration, geographic service density, and supply chain control vectors.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Inpeco |
| Siemens Healthineers |
| A&T Corporation |
| Hitachi High-Tech |
| Roche Diagnostics |
| Sysmex Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
AI-driven quality control flagging is compressing manual review burdens while simultaneously raising the capital threshold for platform entry, concentrating pricing power among vendors with embedded machine learning modules and tilting procurement toward bundled service contracts in German reference laboratories.
Pricing Analysis
Service unbundling from hardware contracts is reshaping negotiation dynamics as buyers separate maintenance agreements from reagent supply commitments. Pricing stratifies across premium, standard, and economy tiers based on throughput capacity and ISO 15189 accreditation compliance levels. Cost compression in mid-tier chemistry analyzers is intensifying because EU IVDR technical documentation demands extend vendor certification timelines. Hospital laboratories exhibit highest price sensitivity due to capital budget constraints, while central laboratories in Germany demonstrate lowest sensitivity given captive reagent chemistry dependencies.
Supply Chain Analysis
Precision optical sensor supply rests on Japanese and German specialty component producers, with liquid handling robotics drawing from Swiss precision engineering clusters. Critical inputs include photomultiplier tubes, precision syringe pumps, and proprietary reagent chemistries. Single-source vulnerability concentrates in immunoassay antibody supply chains tethered to specific instrumentation platforms. Distribution runs through direct sales forces serving hospital networks and specialized distributors reaching diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lab automation market compounds steadily as hospital test volumes rise continuously and regulatory compliance mandates accelerate replacement cycles for legacy systems.
For Market Incumbents: Deploy embedded quality management modules as the primary defensive lever. Siemens Healthineers and Roche Diagnostics should deepen captive reagent chemistry supply chains to lock in consumable revenue streams against modular service unbundling threats. Accelerate AI-based diagnostics R&D to extend platform relevance beyond high-throughput core labs into distributed testing environments. For New Entrants and Emerging Players: Enter via point-of-care automation bridges connecting satellite clinics to core laboratory information systems, the most penetrable white space between centralized and distributed testing. Target clinical research organizations in the United States with precision liquid handling systems for genetic analysis workflows. Pursue FDA 510(k) clearance pathway optimization for faster commercialization timelines relative to EU IVDR demands. For Investors and Strategic Acquirers: Roll-up economics work for software-layer specialists because AI-driven quality control analytics command recurring revenue multiples and face lower capital intensity than hardware platforms. Acquire laboratory information management system vendors with ISO 15189 accreditation compliance capabilities. Watch EU IVDR notified body capacity constraints as the signal indicating accelerated vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Technical Documentation Pathway | Extended conformity assessments accelerate replacement cycles for legacy chemistry analyzers in German laboratories. |
| AI-Based Quality Control Integration | Machine learning modules expand analyzer addressable scope beyond high-throughput core labs into mid-tier hospitals. |
| Service Unbundling from Hardware Contracts | Maintenance agreement separation preserves procurement flexibility for reference laboratories consolidating workflows. |
| Liquid Handling Precision Investment | Pipetting accuracy requirements create specialized demand in genetic analysis workflows for clinical research organizations. |
| Point-of-Care Automation Bridge Development | Distributed testing platform connectivity opens underpenetrated white space between centralized labs and satellite clinics. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and Switzerland, with primary inputs from each market combining structured interviews with laboratory directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers alongside secondary validation. FDA 510(k) filings, EU IVDR technical documentation databases, ISO 15189 accreditation registries, and hospital procurement databases anchored source triangulation. Bottom-up installed base modeling and top-down revenue reconciliation verified segment-level outputs.
Granularity-level modeling disaggregated volume and value across product type, technology, end user, application, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from regression analysis against historical replacement cycles and forward-looking compliance deadline impacts. Forecast inputs incorporated EU IVDR transition timelines, AI diagnostics adoption curves, and test volume growth trajectories in acute care settings.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time service contract pricing introduce uncertainty bands around vendor revenue share estimates. Forecasts reflect documented assumptions regarding replacement cycle acceleration and notified body capacity constraints. A small set of triggers—EU IVDR implementation delays, FDA clearance pathway revisions, and AI diagnostics validation standards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Bone Metabolism Test Market