
 Hunter Syndrome Treatment Market | 2026-2036
Hunter Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hunter Syndrome Treatment Market Intelligence
Expanded biopharmaceutical research capacity in Japan is reconfiguring the development pipeline for novel Hunter syndrome therapies. Takeda Pharmaceutical Company Limited leverages its extensive rare disease portfolio to sustain a strong presence in established enzyme replacement therapy markets. BioMarin Pharmaceutical Inc. competes by specializing in innovative enzyme replacement therapies focused on improved patient outcomes. JCR Pharmaceuticals Co., Ltd. differentiates through its proprietary J-Brain Cargo technology for delivering biotherapeutics across the blood-brain barrier.
Hunter syndrome treatment addresses a rare genetic disorder, mucopolysaccharidosis type II, which is caused by a deficiency of the iduronate-2-sulfatase (I2S) enzyme. Therapeutic intervention aims to replace this critical enzyme or correct the underlying genetic defect to mitigate the systemic accumulation of glycosaminoglycans in tissues. Enzyme Replacement Therapy currently constitutes the dominant treatment modality by revenue. The emerging field of gene therapy represents the fastest-growing therapeutic approach, while specialty clinics remain the principal end-user setting.
Regulatory pathways for orphan drugs, established by agencies like the US FDA and the European Medicines Agency (EMA), provide critical market exclusivity and financial incentives. In parallel, Japan's PMDA offers a streamlined review process for advanced regenerative medicines, which directly influences clinical trial design and investment priorities. Consequently, navigating the distinct evidentiary requirements for novel gene therapies versus established enzyme replacement therapies is a pivotal strategic decision for all developers.
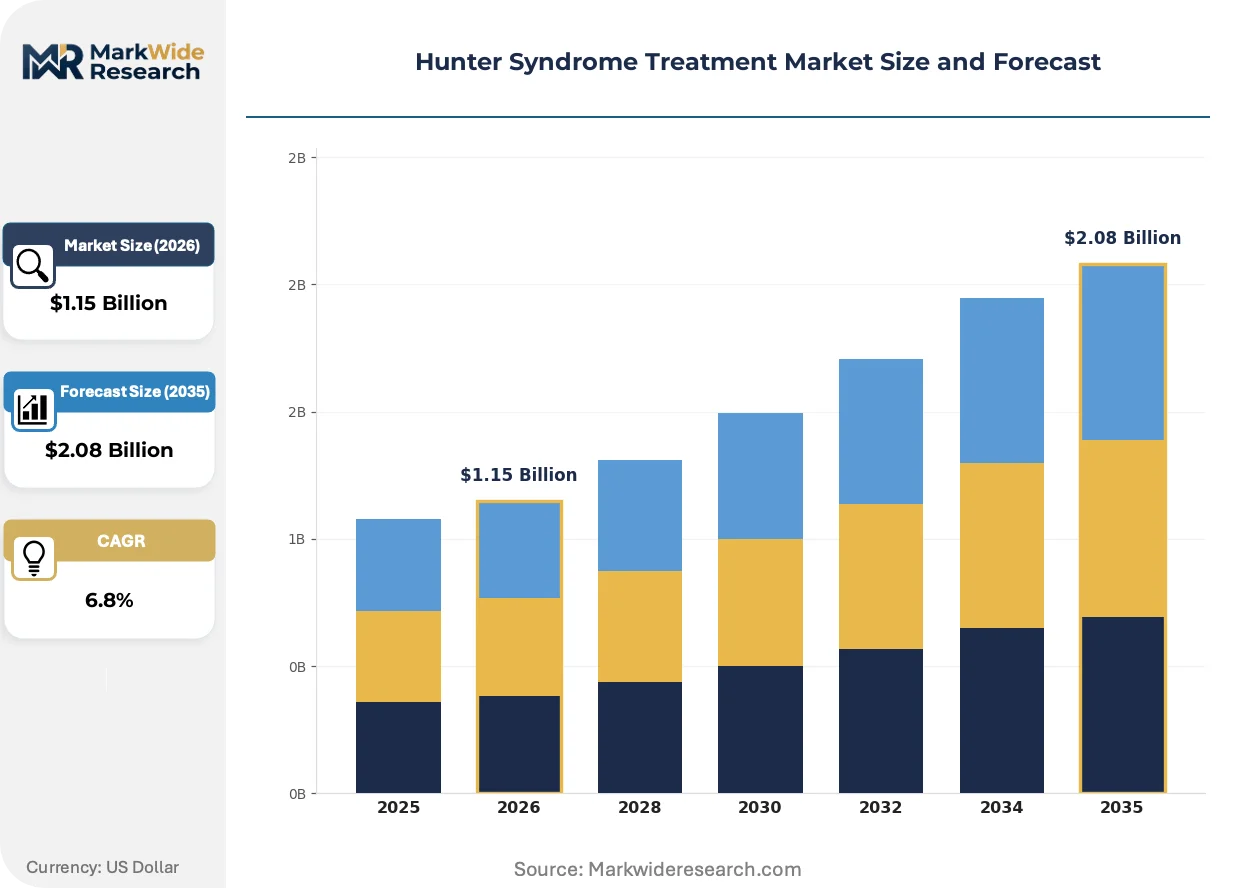
Market Dynamics
The market's central dynamic is the strategic bifurcation between sustaining established enzyme replacement therapies and pioneering curative-intent gene therapies. This split influences all investment, clinical trial design, and regulatory engagement, forcing developers to choose between incremental improvement and transformative risk.
Growth Catalysts
- Orphan Drug Designations:Regulatory frameworks from the US FDA and the European Medicines Agency provide market exclusivity and financial incentives, which encourages investment into therapies for rare diseases like Hunter syndrome.
- Advancements in Delivery Platforms:The development of novel vectors and technologies capable of crossing the blood-brain barrier is expanding the therapeutic potential for addressing the neurological aspects of the disease.
- Newborn Screening Programs:Expanded and standardized newborn screening protocols, particularly in the United States, enable earlier diagnosis and intervention, directly increasing the addressable patient population for available treatments.
Market Restraints
- Extreme Treatment Costs:The very high price of both enzyme replacement therapies and emerging gene therapies creates substantial reimbursement hurdles and limits patient access, especially in healthcare systems with constrained budgets.
- Blood-Brain Barrier Efficacy:A fundamental biological restraint is the inability of most systemic therapies to effectively penetrate the blood-brain barrier, leaving the progressive neurological damage associated with Hunter syndrome largely unaddressed.
- Gene Therapy Safety Profile:Proving the long-term safety and durability of gene therapies presents a significant regulatory and clinical challenge, requiring extensive and lengthy follow-up studies to satisfy agencies like the FDA.
Strategic Opportunities
- Combination Therapy Development:There is a significant opportunity in developing combination regimens that pair existing enzyme replacement therapies with novel delivery agents to enhance efficacy, particularly for neurological symptoms.
- Targeted Regulatory Pathways:Japan's PMDA offers a specific, streamlined review process for regenerative medicines, creating an opportunity for developers to secure early market entry for advanced cell and gene therapies.
- Diagnostic Expansion in Asia-Pacific:Investing in genetic counseling and diagnostic infrastructure in underserved Asia-Pacific countries can unlock new patient populations and create demand for both existing and novel treatments.
Industry Challenges
- Manufacturing Scalability:The complex and capital-intensive process of manufacturing viral vectors for gene therapies at a commercial scale presents a significant operational challenge for developers, impacting cost and supply.
- Specialized Talent Scarcity:A limited pool of clinical researchers, geneticists, and regulatory experts with specific experience in lysosomal storage disorders hinders the pace of clinical development and trial execution.
- Divergent Evidentiary Standards:Navigating the distinct and evolving evidentiary requirements for gene therapies versus established biologics across the FDA, EMA, and PMDA complicates global clinical trial design and marketing authorization strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hunter Syndrome Treatment Market |
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Gene Therapy, Hematopoietic Stem Cell Transplantation, Symptomatic Treatment Administration Route: Intravenous, Intrathecal, Intramuscular, Oral, Subcutaneous Patient Age Group: Pediatric, Adolescent, Adult, Geriatric End User: Specialty Clinics, Research Hospitals, Genetic Counseling Centers, Home Care Providers |
| Companies Covered | Takeda Pharmaceutical Company Limited, BioMarin Pharmaceutical Inc., JCR Pharmaceuticals Co., Ltd., GC Pharma, REGENXBIO Inc., Denali Therapeutics Inc., Sangamo Therapeutics, Inc., ArmaGen Inc., Sanofi Genzyme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hunter Syndrome Treatment Market Strategic Shifts & Innovations
Therapeutic development is pivoting from chronic disease management toward single-administration, potentially curative treatments. This shift is driven by innovations in genetic medicine, which are prompting a re-evaluation of regulatory frameworks and long-term patient care models for rare diseases.
In vivo gene therapies using adeno-associated virus vectors are engineered to deliver a functional copy of the I2S enzyme gene. Biopharmaceutical researchers are advancing these platforms through clinical trials to achieve sustained enzyme expression from a single treatment. This one-time administration approach is rendering obsolete the lifelong, frequent infusion schedules required for conventional enzyme replacement therapy.
The Orphan Drug Act in the United States and parallel regulations from the European Medicines Agency provide essential market incentives for rare disease treatments. These policies help de-risk the substantial investment required to develop therapies for small patient populations. Gene therapy developers are particularly affected, as they depend on these provisions to justify the high R&D expenditures for Hunter syndrome treatments.
Patient advocacy groups are now actively participating in the design of clinical trials and the definition of relevant treatment outcomes. This collaborative model is displacing the traditional, purely clinician-driven approach to establishing trial endpoints. The trend is most prominent in the United States, where a sophisticated patient network partners with researchers, companies, and the FDA to ensure patient-centric data is collected.
Hunter Syndrome Treatment Market Segmentation
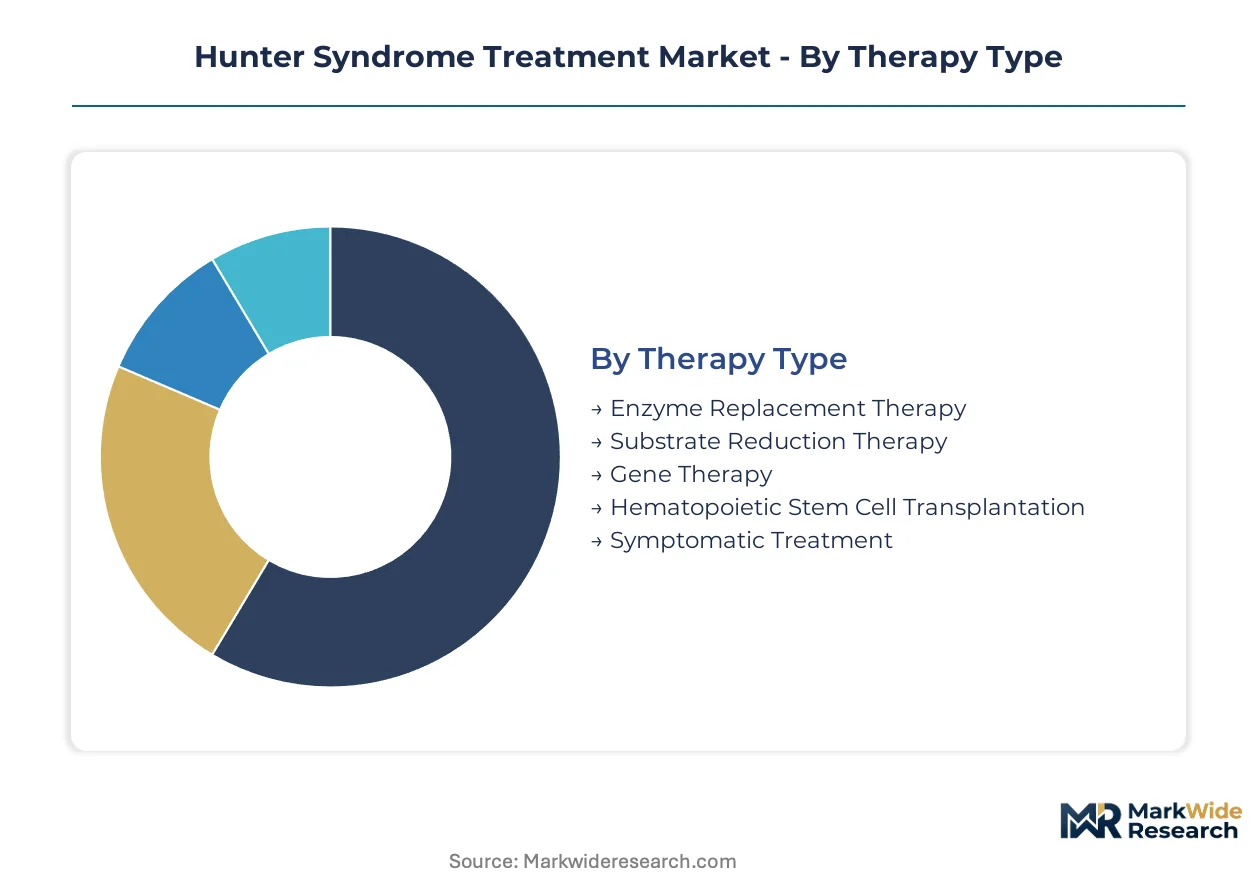
Hunter syndrome treatment market segmentation provides a granular view of therapeutic approaches and patient care delivery models. This detailed breakdown helps stakeholders understand the specific demand drivers and operational complexities within each distinct category. Analyzing these segments reveals where innovation is most concentrated and where established practices continue to dominate.
Therapy Type:
Therapy types exhibit varying development cycles, with gene therapies requiring extensive research and long-term trials, contrasting with the more established and frequently administered enzyme replacement options.
- Enzyme Replacement Therapy:This traditional treatment involves regular intravenous infusions of a manufactured iduronate-2-sulfatase enzyme. It currently constitutes the dominant revenue segment, widely utilized in specialty clinics for systemic symptom management.
- Gene Therapy:This advanced approach aims to deliver a functional I2S gene, often via viral vectors, for a potentially curative, single-administration treatment. Demand for this transformative therapy is concentrating in research hospitals, driven by its potential to address neurological manifestations.
- Substrate Reduction Therapy:This modality uses small molecules to reduce the production of glycosaminoglycans, thereby mitigating their accumulation in tissues. This therapy offers an alternative mechanism of action compared to enzyme replacement.
- Hematopoietic Stem Cell Transplantation:This procedure involves replacing a patient's diseased bone marrow with healthy stem cells capable of producing the deficient enzyme. It is primarily considered for severe cases, particularly in younger patients.
- Symptomatic Treatment:This category encompasses various supportive care measures aimed at managing the specific symptoms and complications of Hunter syndrome, such as pain management or respiratory support.
Enzyme Replacement Therapy anchors the volume base while Gene Therapy gains share at the steepest rate.
Administration Route:
Administration routes directly influence patient convenience and the efficacy of drug delivery to target tissues, with systemic delivery often contrasted against more localized methods.
- Intravenous:This route involves direct administration of the therapeutic agent into a vein, ensuring rapid and complete systemic distribution. It remains the standard delivery method for most enzyme replacement therapies, primarily performed in clinical settings.
- Intrathecal:This method involves direct injection into the cerebrospinal fluid, bypassing the blood-brain barrier to deliver therapies to the central nervous system. This route is critical for addressing the neurological symptoms of Hunter syndrome, a significant unmet need.
- Intramuscular:This route involves injecting the therapeutic agent directly into muscle tissue, allowing for slower absorption into the bloodstream. It offers an alternative for certain therapies requiring sustained release.
- Oral:Oral administration involves taking medication by mouth, providing a non-invasive and convenient option for patients. This route is less common for large biologic molecules like enzymes.
- Subcutaneous:This route involves injecting the therapeutic agent into the tissue layer just under the skin, allowing for slower absorption and potential self-administration. It is gaining traction for home-based enzyme replacement therapy.
Intravenous administration remains the most common delivery method, yet subcutaneous options are increasingly preferred for home-based care convenience.
Patient Age Group:
Patient age groups dictate distinct therapeutic approaches and disease progression patterns, with pediatric cases often presenting higher severity.
- Pediatric:This segment includes patients from infancy through early adolescence, where early diagnosis and intervention are critical for mitigating long-term disease progression. Demand for screening and initial treatment is concentrated here.
- Adult:This segment comprises patients who have progressed into adulthood, often requiring long-term management of chronic symptoms and neurological decline. Neurological care and palliative interventions are significant in this group.
- Adolescent:This group represents patients transitioning from pediatric to adult care, facing evolving disease manifestations and treatment adherence challenges. Specialized support programs are essential for this population.
- Geriatric:This segment includes older adult patients, who may present with advanced disease complications and require comprehensive, multidisciplinary care. The prevalence in this group is lower due to the disease's severity.
Pediatric patients drive the primary diagnostic and treatment initiation volumes, while adult cohorts require sustained, lifelong therapeutic support.
End User:
End-user facilities vary significantly in their specialization and capacity to manage complex rare disease treatments for Hunter syndrome.
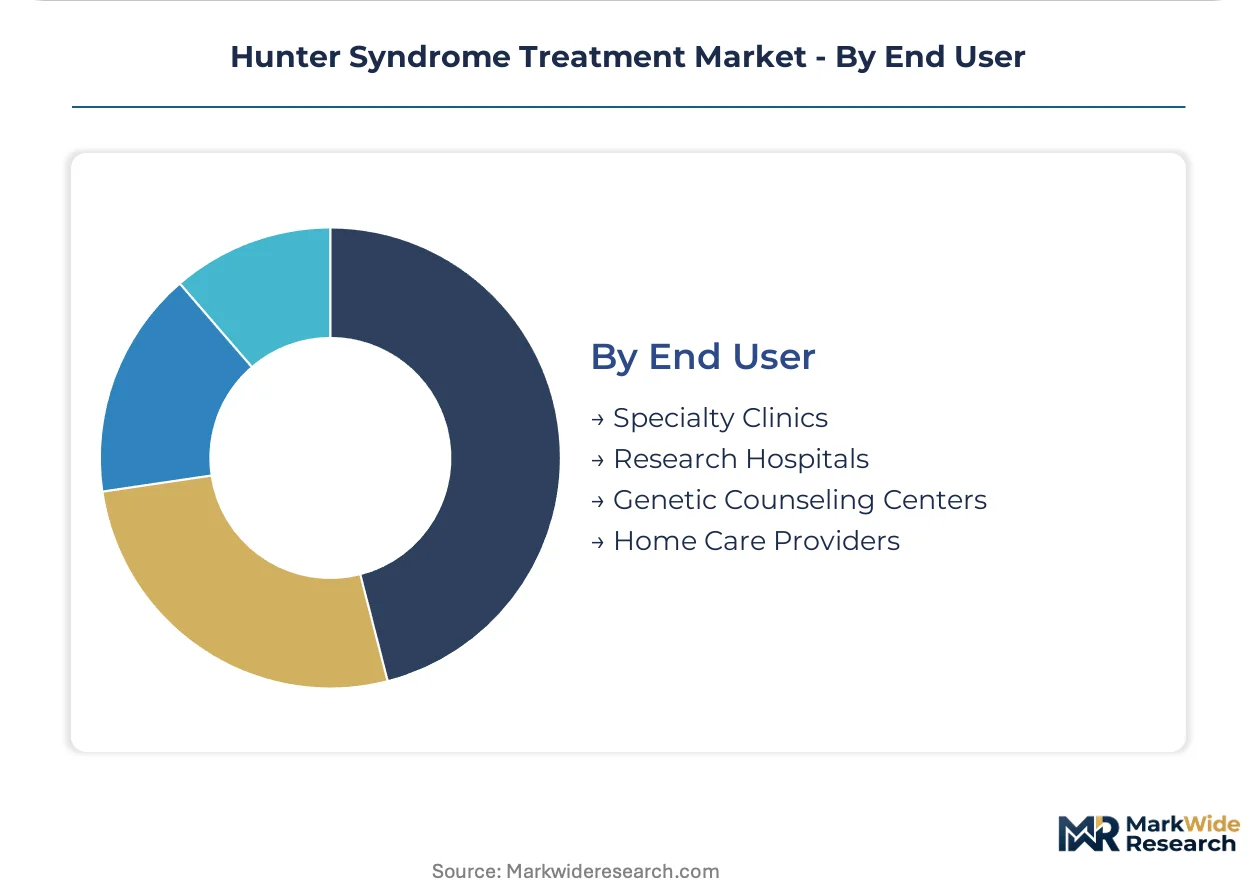
- Specialty Clinics:These facilities are dedicated to the diagnosis, treatment, and long-term management of rare genetic disorders, including Hunter syndrome. They serve as the primary site for enzyme replacement therapy infusions and patient monitoring.
- Research Hospitals:These institutions play a crucial role in conducting clinical trials for novel therapies, including gene therapies and advanced biologics. They attract patients seeking access to investigational treatments and cutting-edge research.
- Genetic Counseling Centers:These centers provide essential services for diagnosis, risk assessment, and family planning related to genetic disorders. They are critical for identifying new patients and supporting families.
- Home Care Providers:These services enable patients to receive certain treatments, such as enzyme replacement therapy infusions, in the comfort of their homes. This end-user segment improves patient quality of life and reduces healthcare facility burden.
Specialty Clinics remain the foundational site for enzyme replacement therapy administration, but Home Care Providers are expanding their role for patient convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The development and commercialization of Hunter syndrome treatments exhibit a pronounced concentration in regions with advanced biopharmaceutical research capabilities and established rare disease infrastructure. This focus on specialized therapeutic development influences global market dynamics, driven by significant investment in gene therapies and innovative delivery platforms. These centers of excellence attract both talent and capital, shaping the future of treatment options.
United States
Demand for Hunter syndrome therapies in the United States is spurred by robust newborn screening programs and a strong patient advocacy network. The US FDA provides critical orphan drug designations and financial incentives, encouraging pharmaceutical investment. Boston and San Francisco Bay Area bioclusters lead in gene therapy research and clinical trials for genetic disorders.
Japan
Japan's expanded biopharmaceutical research capacity is reconfiguring the development pipeline for novel Hunter syndrome therapies. The PMDA offers a streamlined review process for advanced regenerative medicines, accelerating market entry. Tokyo and Osaka serve as major hubs for pharmaceutical innovation, particularly in areas like JCR Pharmaceuticals' J-Brain Cargo technology.
Germany
Germany demonstrates a consistent demand for rare disease treatments, supported by a well-structured healthcare system and strong research institutions. The European Medicines Agency (EMA) orphan drug regulations provide market exclusivity for new therapies. Munich and Heidelberg are prominent centers for biotech research, including enzyme replacement therapy advancements.
United Kingdom
The United Kingdom's demand for Hunter syndrome treatments benefits from its National Health Service (NHS) framework for rare disease care and active clinical research. The UK MHRA's orphan drug incentives support therapeutic development following regulatory divergence from the EMA. London and Cambridge host significant biopharmaceutical research parks, driving innovation in gene therapy platforms.
Hunter Syndrome Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the Hunter syndrome treatment market. The market structure exhibits a tiered consolidation, with established pharmaceutical giants alongside specialized biotech firms. Archetypes include diversified rare disease portfolio holders, innovative gene therapy developers, and advanced drug delivery technology specialists. Companies prioritize strategic partnerships and extensive clinical trial investment to gain market share, often focusing on expanding their therapeutic reach.
Diversified rare disease portfolio holders, such as Takeda Pharmaceutical Company Limited, exemplify a strategy of sustaining strong presence in established enzyme replacement therapy markets. BioMarin Pharmaceutical Inc. represents a specialized approach, focusing on innovative enzyme replacement therapies designed for improved patient outcomes. JCR Pharmaceuticals Co., Ltd. anchors the advanced drug delivery technology segment, leveraging its proprietary J-Brain Cargo technology to address the blood-brain barrier challenge. These firms collectively highlight the bifurcated market strategy between optimizing existing treatments and pioneering novel, potentially curative interventions.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| BioMarin Pharmaceutical Inc. |
| JCR Pharmaceuticals Co., Ltd. |
| GC Pharma |
| REGENXBIO Inc. |
| Denali Therapeutics Inc. |
| Sangamo Therapeutics, Inc. |
| ArmaGen Inc. |
| Sanofi Genzyme |
| Others |
Cost & Logistics Intelligence
Global cold chain logistics for specialized biopharmaceuticals introduce significant cost dynamics, influencing supply concentration and downstream price differentiation. The intricate transport requirements for enzyme replacement therapies and gene therapies contribute to elevated treatment costs.
Pricing Analysis
The Orphan Drug Act and parallel EMA regulations dictate the pricing tier structure for Hunter syndrome therapies, providing market exclusivity incentives. Value-based pricing models are common, particularly for gene therapies, reflecting their potential for single-administration, curative intent. Price differentiation stems from long-term efficacy and improved patient outcomes. Pricing pressure remains high due to substantial research and development investments, making healthcare systems with constrained budgets the most price-sensitive buyers.
Supply Chain Analysis
Upstream sourcing of highly specialized raw materials, such as viral vectors and advanced cell culture media, is critical for Hunter syndrome treatment manufacturing. Supply concentration for these complex biopharmaceutical inputs centers in the United States, Japan, and Germany, reflecting advanced research capabilities. Manufacturing scalability for gene therapies represents a significant structural risk, impacting both cost and availability. Distribution runs through a network of specialty clinics and research hospitals, requiring stringent cold chain management for product integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hunter syndrome treatment market requires a strong substitution defense, as established enzyme replacement therapies must navigate the transformative potential of emerging gene therapies. Incumbents face the imperative to evolve their offerings to remain competitive against potentially curative interventions.
For Market Incumbents: Build a robust intellectual property moat around next-generation enzyme replacement therapies, focusing on enhanced delivery mechanisms. Invest in R&D for central nervous system (CNS) penetration to address neurological symptoms, a key unmet need. Takeda Pharmaceutical Company Limited, for example, must counter the threat of gene therapy's single-shot promise by improving current treatment efficacy. Strategic partnerships with gene therapy developers can also diversify their portfolio.
For New Entrants and Emerging Players: Develop specialized gene therapy platforms targeting the neurological manifestations of Hunter syndrome, a significant unmet need. Focus on early-stage pediatric patients identified through expanded newborn screening programs for maximum impact. Japan's PMDA offers a streamlined regulatory pathway for regenerative medicines, providing a strategic entry point. Investing in diagnostic infrastructure in underserved Asia-Pacific countries can also unlock new patient populations.
For Investors and Strategic Acquirers: Gene therapy developers with proprietary blood-brain barrier penetration technologies represent attractive acquisition targets for long-term viability in this market. The Hunter syndrome treatment landscape offers sustained growth potential over the next decade due to significant unmet medical needs. Watch for clinical trial success achieving meaningful neurological endpoints, as this signals transformative value creation. Companies like JCR Pharmaceuticals Co., Ltd., with its J-Brain Cargo technology, exemplify such strategic assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerate trials for gene therapies addressing neurological symptoms, a critical unmet need. |
| Regulatory Approval Pathway | Leverage Japan's PMDA streamlined process for advanced regenerative medicines. |
| Manufacturing Scale-Up | Invest in commercial-scale viral vector production to meet gene therapy demand. |
| Licensing Agreement | Secure rights to novel delivery platforms for improved enzyme replacement efficacy. |
| Pipeline Diversification | Expand R&D into combination therapies for comprehensive Hunter syndrome patient care. |
Research Approach
Cross-validation between primary interviews and extensive secondary research anchors the qualitative findings of this study. Drug development executives, regulatory affairs leads, hospital procurement managers, and patient advocacy leaders provided critical insights. Secondary data sources included FDA filings, EMA submissions, ClinicalTrials.gov, and company annual reports. This approach ensured robust bottom-up and top-down triangulation for market sizing.
The forecast calibration approach integrates supply-side capacity and demand-side adoption trends across the analysis window. Segmentation dimensions modeled include therapy type, administration route, patient age group, end user, and regional regulatory cluster. Compound annual growth rates derived from historical trends and projected technological advancements. Clinical trial success rates and new product launch timelines served as key industry-specific forecast inputs.
Sensitivities concentrate around unforeseen regulatory changes, gene therapy safety profile developments, and evolving reimbursement policies. Forecasts reflect assumptions regarding clinical trial outcomes and market access. Cross-checking against external market intelligence reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Whim Syndrome Management Market