
 North America Patient Temperature Management Market | 2026-2036
North America Patient Temperature Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Patient Temperature Management Market Analytics
ISO 80601-2-56 certification for clinical thermometers is unwinding competitive access across the North America patient temperature management landscape. Stryker Corporation leverages its integrated surgical equipment portfolio to sustain dominant positioning in operating room warming systems. Medtronic plc anchors its presence through deep entrenchment in critical care temperature modulation for cardiac and neurological procedures. Cincinnati Sub-Zero Products specializes in precision cooling technologies that occupy a defensible niche in therapeutic hypothermia applications.
Patient temperature management encompasses active and passive systems designed to maintain, raise, or lower core body temperature through surface or intravascular contact, typically operating within precision ranges of 0.1°C to 0.5°C accuracy for clinical decision-making. These technologies serve primarily to prevent perioperative hypothermia, manage fever in sepsis, and induce controlled hypothermia for neuroprotection. Cooling devices lead absolute revenue contribution due to higher unit costs and expanded indications in stroke and cardiac arrest protocols, while combination delivery modes represent the fastest-growing structural category as hybrid conduction-convection systems displace single-modality equipment. The accessories segment captures recurring margin pools through disposable warming blankets, temperature probes, and replacement consumables tied to installed device bases.
FDA 510(k) clearance pathways and AAMI thermal performance standards govern market access and product validation requirements for manufacturers serving United States healthcare providers. Health Canada's Medical Devices Bureau imposes parallel but distinct quality system expectations that shape product development priorities for cross-border suppliers. Stakeholders must monitor evolving CMS reimbursement determinations for perioperative temperature management as value-based purchasing metrics increasingly tie institutional payments to hypothermia prevention compliance.
Market Dynamics
ISO 80601-2-56 certification requirements are compressing vendor access and forcing acute care facilities to requalify their installed base of temperature management devices against stricter electromagnetic compatibility and accuracy standards.
Growth Catalysts
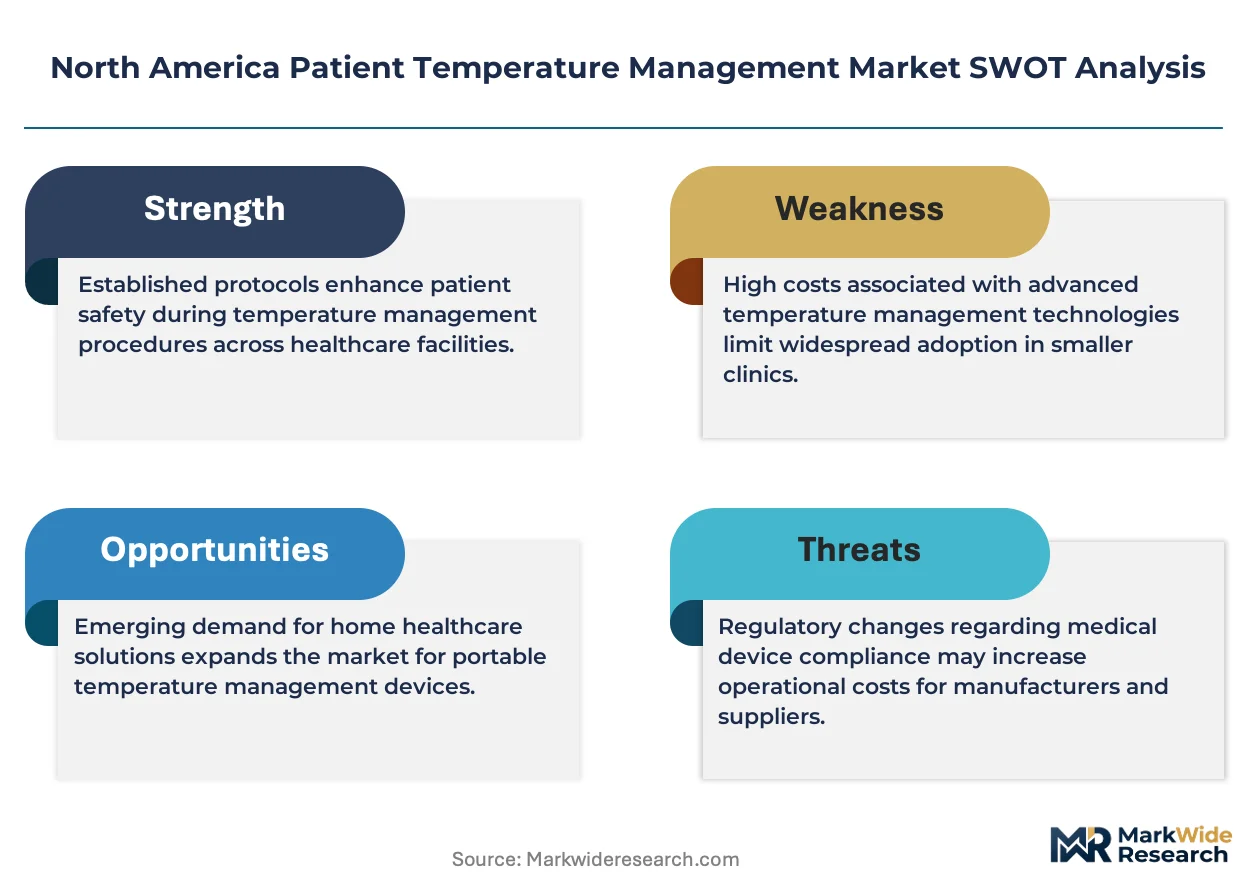
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-based warming and cooling submissions are shortening product launch cycles for manufacturers targeting United States hospital systems.
- Sepsis protocol expansion:Emergency departments across Canada and the United States are mandating active temperature modulation for septic patients, driving replacement of passive monitoring with surface cooling systems.
- Cardiac arrest survivor networks:Regionalized post-arrest care systems in major United States metropolitan areas are standardizing therapeutic hypothermia as a transfer criterion between community hospitals and quaternary centers.
Market Restraints
- Copper and polymer input volatility:Intravascular catheter assemblies depend on medical-grade polyurethane and temperature-conductive alloys subject to spot-market price swings that compress gross margins on disposable sets.
- Single-source sensor dependency:Precision thermistor supply concentrates among three Japanese component houses, exposing North American original equipment manufacturers to allocation risk during demand surges.
- Biocompatibility testing burden:FDA updated guidance on surface-contact warming blanket materials is extending validation timelines and requiring supplemental cytotoxicity studies for legacy product lines.
Strategic Opportunities
- Home-based fever management:Post-acute discharge protocols for oncology and transplant patients in the United States are creating demand for prescription-grade surface cooling devices with remote monitoring capabilities.
- Hybrid conduction-convection systems:Integration of adhesive gel pads with forced-air delivery is opening surgical suites that previously standardized on single-modality warming.
- Canadian provincial procurement consolidation:Ontario and Quebec health authority joint purchasing initiatives are creating volume entry points for mid-tier manufacturers able to meet Health Canada quality system expectations.
Industry Challenges
- Bioengineering talent scarcity:Thermal systems design requires rare cross-training in heat transfer physics and clinical workflow analysis, with fewer than twelve United States universities producing relevant dual-discipline graduates annually.
- Legacy EMR integration friction:Temperature data export from proprietary device protocols into Epic and Cerner environments requires custom interface development that delays hospital system deployments by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Patient Temperature Management Market |
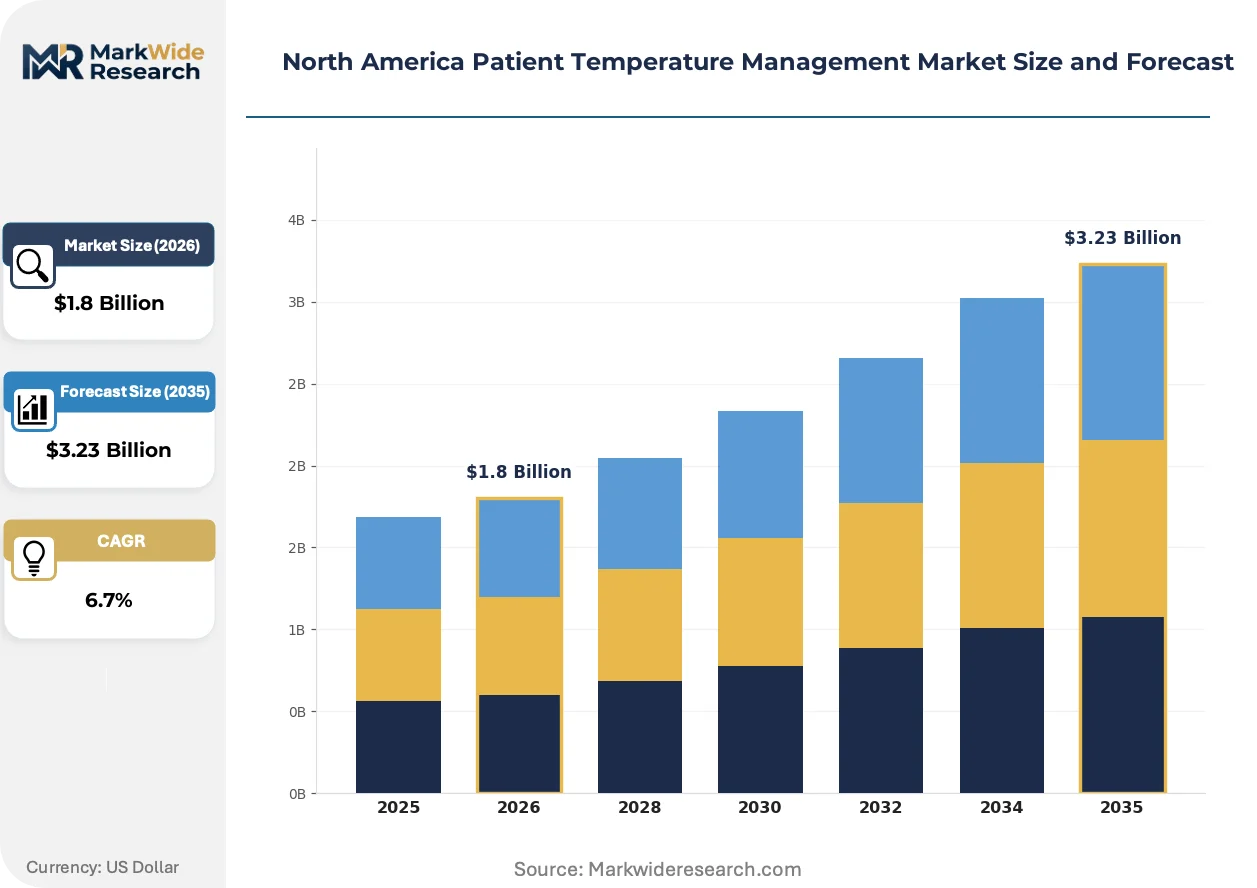
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Monitors, Cooling Devices, Heating Devices, Accessories Delivery Mode: Conduction, Convection, Radiation, Combination End User: Hospitals, Outpatient Clinics, Emergency Care Facilities, Home Care Application: Postoperative Care, Emergency Response, Therapeutic Hypothermia, Fever Management |
| Companies Covered | 3M Company, Stryker Corporation, Medtronic plc, Cincinnati Sub-Zero Products, LLC, ZOLL Medical Corporation, Becton, Dickinson and Company, Smiths Medical, Drägerwerk AG & Co. KGaA, The Surgical Company Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Patient Temperature Management Market Evolving Landscape
Wireless, disposable temperature patches are displacing wired probe systems across perioperative and step-down units, compressing capital requirements while shifting revenue toward recurring consumable models.
Intravascular cooling catheter technology is miniaturizing from 9 French to 5 French profiles, enabling femoral access in smaller patients and expanding addressable indications to pediatric cardiac surgery. United States children's hospitals are piloting these platforms for congenital defect repairs previously excluded from therapeutic hypothermia protocols. The form-factor reduction is miniaturizing the competitive barrier between specialized pediatric device manufacturers and generalist critical care suppliers.
Health Canada's Medical Devices Bureau is aligning post-market surveillance requirements with FDA Medical Device Reporting standards, forcing cross-border manufacturers to unify adverse event documentation systems. This regulatory convergence is accelerating withdrawal of single-market product variants and concentrating investment in platforms certifiable under both jurisdictions. United States vendors with legacy Canadian-only SKUs face re-registration costs that favor portfolio consolidation.
Hospital value analysis committees are unbundling temperature management device procurement from bundled operating room capital packages, creating standalone competitive bids for warming and cooling systems. This purchasing decentralization is elevating clinical engineering input over surgeon preference in vendor selection across integrated delivery networks in Texas and Florida. Independent temperature management specialists are gaining share against surgical equipment conglomerates in these reorganized buying processes.
North America Patient Temperature Management Market Segmentation
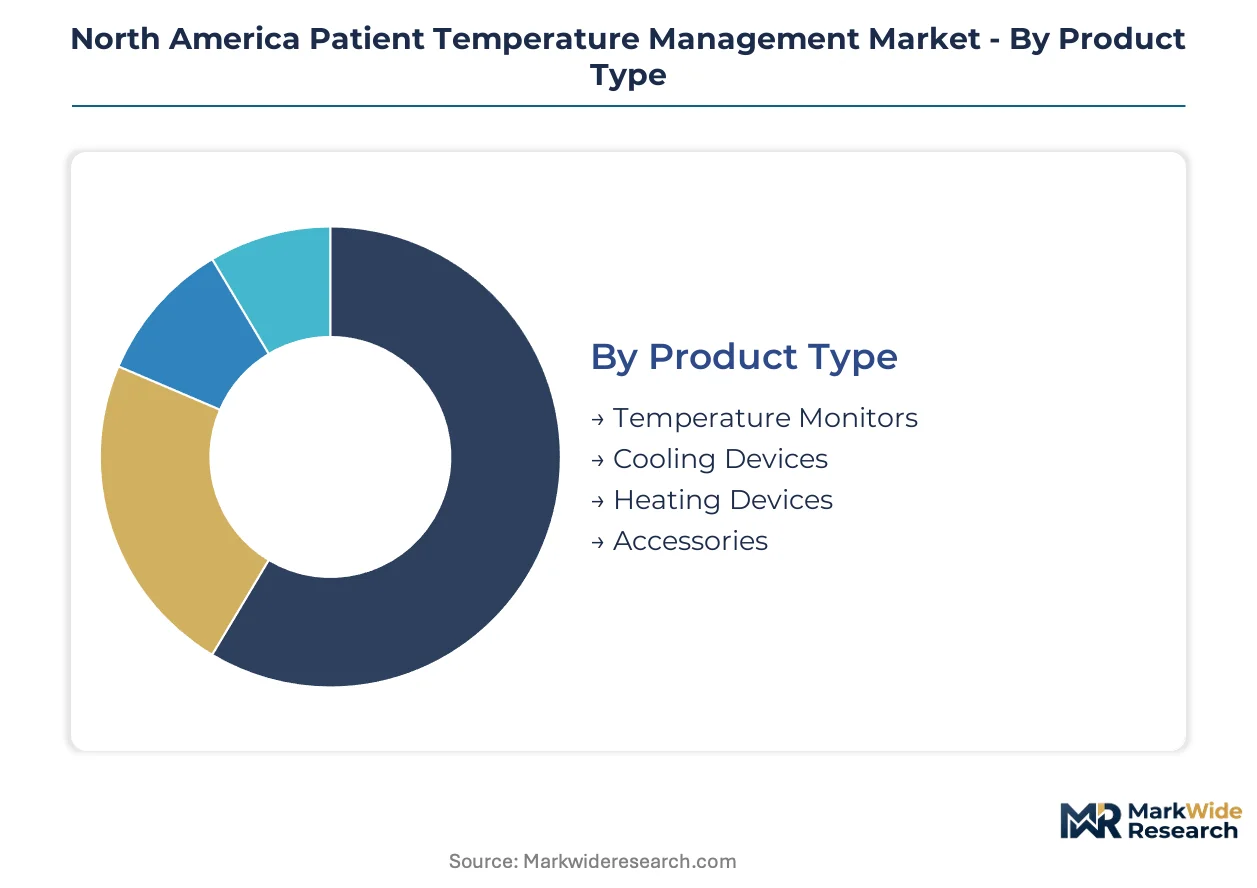
Patient temperature management technologies fragment across four structural dimensions that determine procurement pathways, reimbursement eligibility, and competitive positioning. Product type and delivery mode classifications shape FDA 510(k) submission strategies, while end-user and application segments govern sales channel design and clinical evidence requirements.
Product Type:
FDA device classification rules create divergent regulatory burdens across this category, with Class II and Class III designations dictating clinical trial scale and 510(k) predicate availability.
- Cooling Devices:Intravascular catheters and surface cooling systems operate within precision ranges of 0.1°C to 0.5°C accuracy for neuroprotection and cardiac arrest protocols. United States quaternary medical centers concentrate replacement demand as therapeutic hypothermia standardizes across post-arrest care networks.
- Heating Devices:Forced-air warming blankets and conductive mattresses prevent perioperative hypothermia in surgical populations. Operating room capital budgets in Texas and Florida integrated delivery networks drive procurement cycles as value analysis committees unbundle temperature management from bundled equipment packages.
- Temperature Monitors:Continuous core temperature sensors with wireless telemetry capabilities support step-down unit workflows.
- Accessories:Disposable warming blankets, temperature probes, and replacement consumables generate recurring revenue tied to installed device bases.
Cooling devices handle the majority of throughput; accessories are climbing the fastest on share as facilities shift toward recurring consumable models.
Delivery Mode:
Heat transfer physics and clinical workflow constraints determine adoption patterns, with hybrid systems commanding premium positioning against single-modality alternatives.
- Combination:Hybrid conduction-convection systems integrate adhesive gel pads with forced-air delivery for surgical suites previously standardized on single-modality warming. United States hospital systems in metropolitan areas pilot these platforms to reduce equipment footprint and nursing workflow complexity.
- Convection:Forced-air warming dominates perioperative protocols with established clinical evidence bases and lower capital requirements than intravascular alternatives.
- Conduction:Surface contact systems using conductive fabrics or gel matrices serve neonatal and pediatric populations where intravascular access carries elevated risk.
- Radiation:Infrared and radiant warming technologies occupy niche applications in burn centers and trauma resuscitation bays.
Convection maintains installed base dominance; combination systems show steepest expansion trajectory as hybrid designs displace legacy single-modality equipment.
End User:
Facility type determines reimbursement pathway, capital budget scale, and clinical engineering support requirements for temperature management technology deployment.
- Hospitals:Acute care facilities across the United States and Canada deploy comprehensive warming and cooling portfolios across perioperative, critical care, and emergency departments. Aging surgical volumes and expanded emergency department infrastructure drive replacement cycles and new installations in metropolitan markets.
- Emergency Care Facilities:Freestanding emergency departments and community hospital EDs concentrate demand for rapid-deployment surface cooling systems. Sepsis protocol expansion across Canada and the United States mandates active temperature modulation, displacing passive monitoring with surface cooling platforms.
- Outpatient Clinics:Ambulatory surgery centers prioritize compact warming systems with rapid turnover capabilities.
- Home Care:Post-acute discharge protocols for oncology and transplant patients create demand for prescription-grade surface cooling devices with remote monitoring capabilities.
Hospitals absorb the bulk of capital expenditure; home care is gaining share fastest as post-acute protocols extend temperature management beyond institutional boundaries.
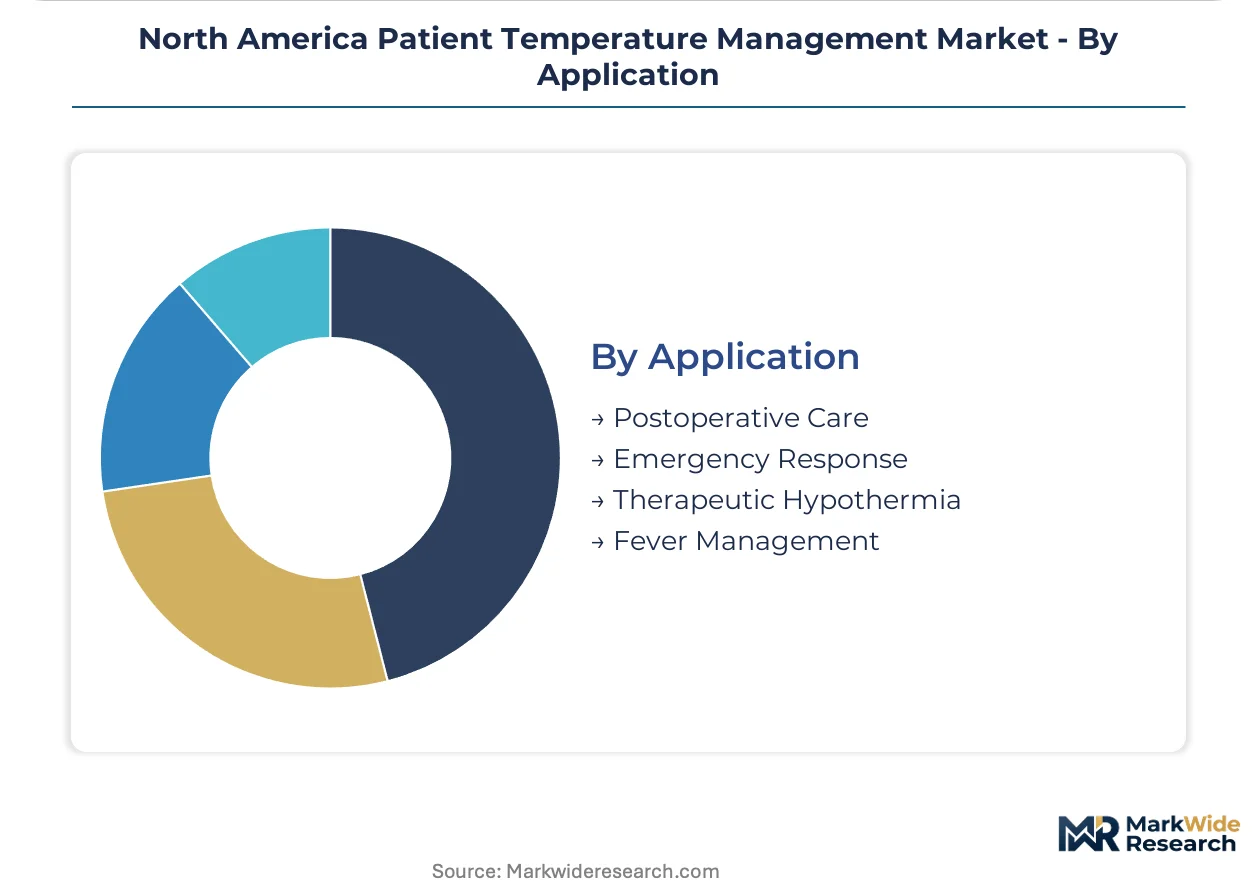
Application:
Clinical indication determines performance specifications, outcome metrics, and payer reimbursement determination for temperature management interventions.
- Therapeutic Hypothermia:Controlled cooling to 32-34°C for neuroprotection following cardiac arrest or traumatic brain injury requires intravascular catheter precision or advanced surface systems. United States regionalized post-arrest care networks standardize therapeutic hypothermia as a transfer criterion between community hospitals and quaternary centers.
- Postoperative Care:Normothermia maintenance prevents surgical site infections and reduces length of stay in recovery units. CMS value-based purchasing metrics increasingly tie institutional payments to hypothermia prevention compliance, elevating procurement priority for warming systems.
- Emergency Response:Pre-hospital and ED-based temperature modulation for sepsis, heat stroke, and trauma resuscitation drives demand for portable, rapid-deployment cooling platforms.
- Fever Management:Active cooling for hyperpyrexia in sepsis, malignancy, or neurologic injury occupies expanding protocol indications.
Postoperative care commands the largest installed base; therapeutic hypothermia is expanding most quickly as cardiac arrest survivor networks proliferate across major United States metropolitan areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway streamlining and CMS value-based purchasing metrics are accelerating hospital system procurement cycles across North America, while Health Canada's regulatory convergence with U.S. standards is reshaping cross-border manufacturer strategies.
United States
Aging surgical volumes and expanded emergency department infrastructure drive replacement cycles for warming and cooling systems in metropolitan markets. CMS reimbursement determinations for perioperative temperature management increasingly tie institutional payments to hypothermia prevention compliance. Texas and Florida integrated delivery networks concentrate demand as value analysis committees unbundle temperature management from bundled operating room capital packages.
Canada
Ontario and Quebec health authority joint purchasing initiatives create volume entry points for manufacturers meeting Health Canada quality system expectations. Health Canada's Medical Devices Bureau aligns post-market surveillance with FDA Medical Device Reporting standards, forcing adverse event documentation unification. Toronto and Vancouver quaternary centers standardize therapeutic hypothermia protocols for cardiac arrest transfer networks.
Mexico
Private hospital chains in Mexico City and Monterrey expand perioperative infrastructure to capture medical tourism flows from the United States and Canada. COFEPRIS medical device registration requirements are streamlining parallel to FDA harmonization initiatives under USMCA provisions. Guadalajara's medical device manufacturing corridor attracts temperature management component assembly for North American supply chain integration.
California
Sepsis protocol mandates across Los Angeles and San Francisco Bay Area emergency departments drive surface cooling system deployments. California's Office of Statewide Health Planning and Development facility standards incorporate active temperature modulation requirements for trauma center certification. San Diego's biomedical cluster hosts pediatric device pilots miniaturizing intravascular cooling catheters for congenital defect repairs.
Texas
Houston and Dallas-Fort Worth cardiac arrest survivor networks standardize therapeutic hypothermia as inter-hospital transfer criteria. Texas Department of State Health Services emergency care regulations mandate temperature management capability for Level I trauma designation. Austin's medical technology corridor attracts clinical engineering talent for thermal systems design cross-trained in heat transfer physics.
North America Patient Temperature Management Market Competitive Landscape
Listed leaders compete with private specialists across integrated surgical equipment portfolios and precision cooling niches. Stryker Corporation and Medtronic plc anchor publicly traded consolidation through operating room warming dominance and critical care temperature modulation entrenchment. Three strategic archetypes define competitive positioning: diversified surgical equipment conglomerates, critical care temperature modulation specialists, and precision therapeutic hypothermia niche players. Dominant competitive moves include portfolio diversification into hybrid conduction-convection systems and strategic partnerships for EMR integration capabilities.
Within the diversified equipment tier, 3M Company and Stryker Corporation exemplify scale-driven consolidation across perioperative warming portfolios. Cincinnati Sub-Zero Products, LLC occupies a private specialist position in precision cooling technologies for therapeutic hypothermia applications. Drägerwerk AG & Co. KGaA represents European-origin diversification into North American critical care temperature management. These archetypes reflect the market's structural tension between integrated capital equipment bundling and standalone clinical engineering procurement.
| Leading Market Players |
|---|
| 3M Company |
| Stryker Corporation |
| Medtronic plc |
| Cincinnati Sub-Zero Products, LLC |
| ZOLL Medical Corporation |
| Becton, Dickinson and Company |
| Smiths Medical |
| Drägerwerk AG & Co. KGaA |
| The Surgical Company Group |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Japanese thermistor suppliers lock in both component access and price visibility for North American original equipment manufacturers navigating single-source sensor dependencies. These arrangements insulate device makers from spot-market volatility while compressing margin flexibility for mid-tier competitors lacking procurement scale.
Pricing Analysis
Certification level (ISO 80601-2-56 and FDA 510(k) grade) creates the primary spread between premium and standard tiers, with electromagnetic compliance-validated devices commanding 15-25% uplifts over legacy equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by accuracy specifications and EMR integration depth. Pricing pressure stems from copper and medical-grade polyurethane input volatility that squeezes gross margins on disposable intravascular catheter sets. Ambulatory surgery centers exhibit highest price sensitivity due to capital budget constraints, while quaternary medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port congestion have elevated landed costs for temperature-conductive alloys and precision thermistors sourced from Japanese component houses. Manufacturing concentration in the United States, Germany, and Japan feeds North American demand, with medical-grade polyurethane resin supply anchored in German chemical production. Single-source vulnerability concentrates in three Japanese thermistor suppliers, exposing allocation risk during demand surges. Distribution runs through GPO contracts and direct hospital system agreements, with value analysis committees increasingly unbundling procurement from bundled capital packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Texas and Florida integrated delivery networks consolidate purchasing through joint value analysis committees, fragmenting vendor access and elevating clinical engineering influence over surgeon preference.
For Market Incumbents: Secure thermistor supply through backward integration or long-term offtake agreements with Japanese component houses to defend against allocation risk. Deepen FDA 510(k) predicate libraries to accelerate clearance timelines and maintain portfolio refresh velocity against emerging hybrid conduction-convection specialists. For New Entrants and Emerging Players: Post-acute home care service-layer gaps expose under-served oncology and transplant discharge protocols where prescription-grade surface cooling with remote telemetry lacks established vendors. Target Canadian provincial procurement consolidation in Ontario and Quebec as volume entry points, leveraging Health Canada quality system alignment with FDA standards to reduce dual-registration costs. For Investors and Strategic Acquirers: The market sits at a regulatory-convergence phase that favors platform consolidators with cross-border certification capabilities. Long-term viability hinges on EMR integration depth and disposable consumable recurring revenue attachment. Watch CMS reimbursement determinations for perioperative temperature management as the inflection signal tying institutional payments to hypothermia prevention compliance.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Accelerated predicate-based submissions shorten launch cycles for warming and cooling systems targeting United States hospital systems. |
| Health Canada Quality System Alignment | Post-market surveillance convergence with FDA standards reduces dual-registration burden for cross-border manufacturers. |
| Hybrid Conduction-Convection Development | Integration of adhesive gel pads with forced-air delivery opens surgical suites previously standardized on single-modality warming. |
| EMR Integration Partnership | Custom interface development with Epic and Cerner environments reduces hospital system deployment delays by four to eight months. |
| Home Care Remote Monitoring Platform | Prescription-grade surface cooling with telemetry capabilities captures post-acute discharge protocols for oncology and transplant patients. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, CMS Medicare data, and hospital procurement databases anchors the qualitative findings. Bottom-up and top-down triangulation reconciles device shipment data with capital budget disclosures from United States and Canadian health systems.
Sensitivity analysis across the projection horizon tests forecast robustness against copper and polymer input volatility scenarios and regulatory timeline variations. The analytical framework models product type, delivery mode, end user, and application segments alongside therapeutic hypothermia protocol adoption curves. CAGRs derive from installed base replacement cycles, sepsis protocol expansion rates, and cardiac arrest survivor network proliferation patterns.
Material uncertainties — FDA guidance updates on surface-contact warming blanket biocompatibility, thermistor supply allocation disruptions, and CMS value-based purchasing metric revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and input cost normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Heart Beat Monitor and Sensor Market