
 Mono Rapid Testing Market | 2026-2036
Mono Rapid Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Mono Rapid Testing Market Foresight
CE marking under the EU In Vitro Diagnostic Regulation is reorganizing competitive access for mono rapid testing suppliers across European markets. Abbott Laboratories leverages extensive lateral flow manufacturing scale to sustain cost advantages in high-volume antigen test production. Siemens Healthineers anchors its position through integrated diagnostic platforms that pair rapid testing with laboratory information systems. Thermo Fisher Scientific competes by extending distribution reach through channel partnerships with hospital procurement networks.
Mono rapid testing encompasses point-of-care diagnostic assays designed to detect specific analytes—typically antigens, antibodies, or nucleic acids—within minutes using immunochromatographic strips, lateral flow membranes, or miniaturized molecular amplification chambers, with sensitivity thresholds ranging from picogram to nanogram per milliliter depending on target pathogen load. These devices serve primarily to enable clinical decision-making at the site of patient presentation, reducing turnaround time from hours to under twenty minutes for infectious disease screening. Antigen tests dominate current volume flows as healthcare systems prioritize throughput and cost containment in respiratory pathogen surveillance, while molecular tests capture expanding margin pools as nucleic acid amplification technology miniaturizes for near-patient deployment. Lateral flow devices remain the structural backbone of home care distribution channels, though antibody tests face demand headwinds as post-infection serology applications narrow in favor of active infection detection.
FDA clearance pathways under the Emergency Use Authorization framework and subsequent de novo classification processes shape product entry timelines and clinical claim scope for US market participants. The EU IVDR's performance evaluation and post-market surveillance requirements impose documentation burdens that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving harmonization gaps between FDA and notified body expectations as jurisdictions diverge on acceptable clinical validation standards for self-testing indications.
Market Dynamics
Hospital emergency departments are consolidating diagnostic workflows around point-of-care platforms that compress infectious disease detection from laboratory turnaround to bedside decision-making, forcing manufacturers to integrate connectivity and data capture into disposable test cartridges.
Growth Catalysts
- Emergency Department Throughput Pressure:Hospital administrators in the United States mandate sub-twenty-minute infectious disease screening to reduce emergency room boarding times and improve patient flow metrics.
- FDA De Novo Pathway Expansion:The FDA's evolving framework for over-the-counter infectious disease testing is clearing commercial pathways for home-use mono rapid tests without prescription requirements.
- Lateral Flow Manufacturing Scale:Automated membrane processing and reel-to-reel assembly lines are driving unit cost reductions that make high-volume antigen testing economically viable for national screening programs.
Market Restraints
- Nitrocellulose Membrane Supply Concentration:Three specialized chemical manufacturers in Germany and the United States control premium-grade membrane substrate production, creating input bottlenecks during demand surges.
- EU IVDR Documentation Burden:The European Union's In Vitro Diagnostic Regulation imposes extensive performance evaluation and post-market surveillance requirements that extend product registration timelines by eighteen to thirty-six months for new market entrants.
- Antigen Test Sensitivity Limitations:Immunochromatographic assays detect pathogen loads above ten thousand copies per milliliter, generating false-negative risks during early infection windows when viral shedding remains below threshold.
Strategic Opportunities
- Retail Pharmacy Distribution Expansion:CVS Health and Walgreens in the United States are building dedicated rapid testing sections that bypass traditional clinical procurement channels and capture direct consumer spend.
- Multiplex Respiratory Panels:Convergent lateral flow and microfluidic technologies enable simultaneous detection of mono, strep, and influenza from a single nasal swab specimen.
- Japan's Decentralized Diagnostic Infrastructure:METI funding for rural clinic point-of-care networks is creating demand for Japanese-language, smartphone-integrated rapid test readers in prefectures outside Tokyo and Osaka.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Manufacturers struggle to hire specialists conversant in both FDA Emergency Use Authorization protocols and EU IVDR technical documentation requirements.
- Laboratory Information System Integration:Point-of-care devices must map to HL7 FHIR standards and legacy LIS architectures that lack standardized middleware for rapid test result ingestion.
- Antibody Test Demand Collapse:Post-infection serology applications narrow as healthcare systems prioritize active infection detection, forcing portfolio reconfiguration toward antigen and molecular platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mono Rapid Testing Market |
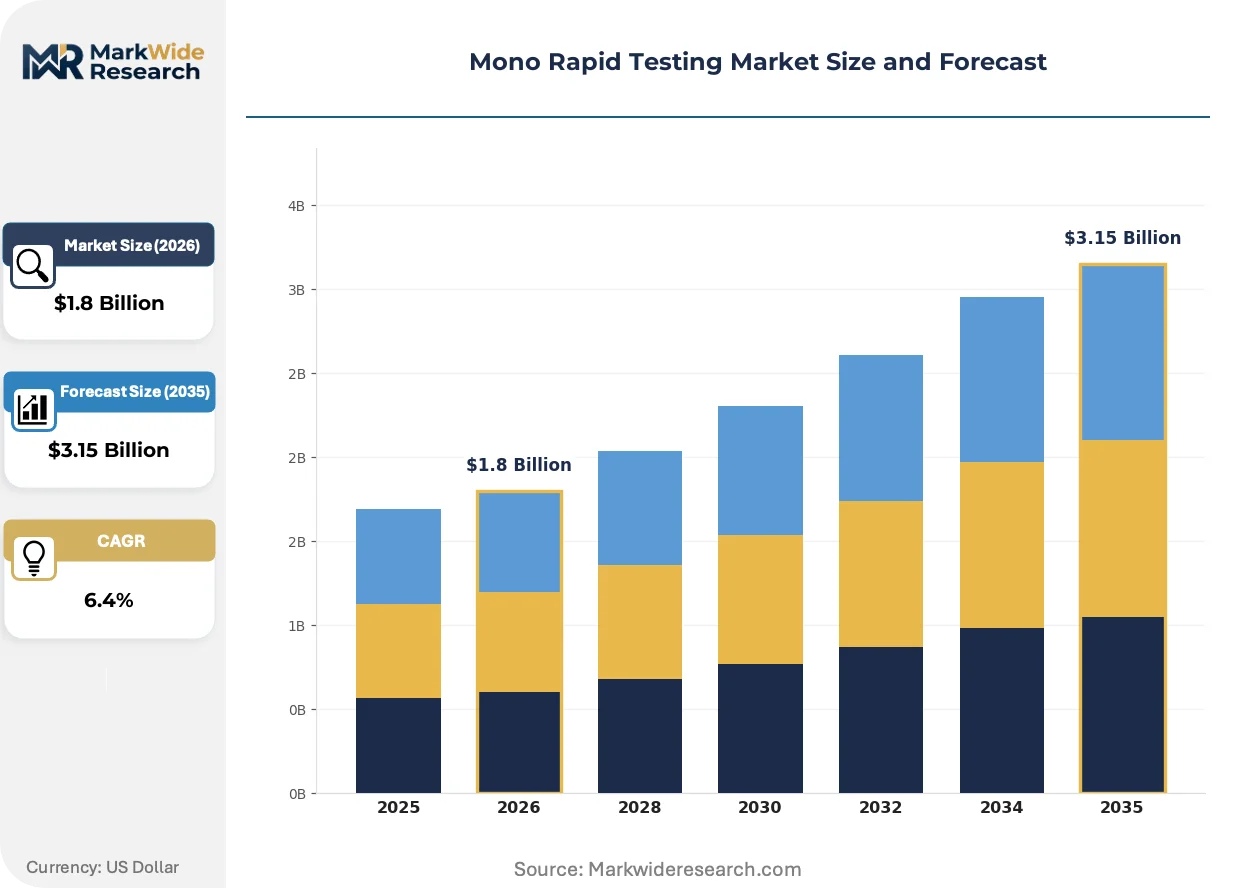
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Tests, Antibody Tests, Molecular Tests, Lateral Flow Devices Therapy Area: Infectious Diseases, Autoimmune Disorders, Infectious Pathogens, Oncology End User: Hospitals, Clinics, Laboratories, Home Care Settings Distribution Channel: Direct Sales, Online Retail, Distributors, Pharmacies |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Quidel Corporation, Thermo Fisher Scientific, Bio-Rad Laboratories, F. Hoffmann-La Roche, Becton, Dickinson and Company, Cardinal Health, Sekisui Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mono Rapid Testing Market Shifts & Advancements
Isothermal nucleic acid amplification is compressing molecular diagnostic workflows into handheld formats, blurring the historical segmentation between laboratory precision and point-of-care convenience. Three interconnected developments are restructuring product architecture and go-to-market approaches.
Loop-mediated isothermal amplification (LAMP) chemistry operates at constant temperature without thermal cycling equipment, enabling battery-powered devices that match antigen test form factors while delivering polymerase chain reaction-equivalent sensitivity. Community health centers in Germany and Japan are piloting these platforms for same-visit mono confirmation. The technology is miniaturizing molecular testing into credit-card-sized cartridges that eliminate cold-chain reagent storage and complex operator training.
The FDA's transition from Emergency Use Authorization to permanent de novo classification for over-the-counter infectious disease tests is forcing manufacturers to generate thirty-day stability data and lay-user error studies that exceed prior EUA evidentiary standards. This regulatory recalibration favors established players with dedicated clinical affairs infrastructure. Home-use self-test indications face the steepest compliance burden as the agency scrutinizes labeling comprehension across literacy levels.
Hospital procurement consortia are consolidating supplier relationships around integrated diagnostic platforms that bundle rapid testing with enterprise data analytics and predictive inventory management. Premier and Vizient in the United States negotiate multi-year sole-source agreements that displace fragmented spot purchasing. This concentration pressures mid-tier manufacturers to demonstrate interoperability with Epic and Cerner electronic health record systems or exit the acute care channel entirely.
Mono Rapid Testing Market Segmentation
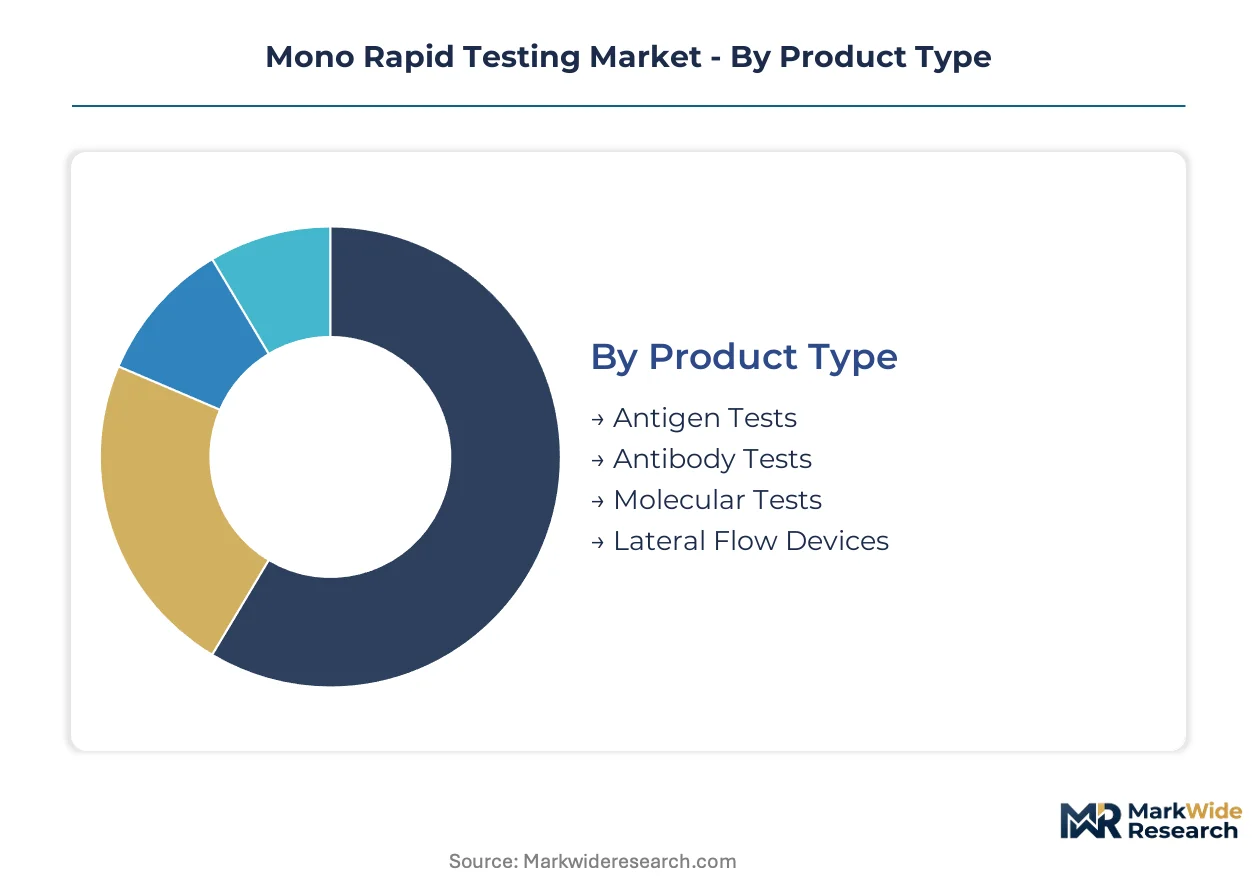
Product architecture in mono rapid testing determines reimbursement pathways, regulatory classification, and manufacturing scale economics. Segment boundaries blur as isothermal amplification compresses molecular workflows into lateral flow form factors, forcing manufacturers to reposition across traditional category lines.
Product Type:
Antigen tests face intensifying substitution pressure from miniaturized molecular platforms that match their speed while delivering superior sensitivity thresholds.
- Antigen Tests:Immunochromatographic strips detect pathogen surface proteins with visual readouts in under fifteen minutes. Hospital emergency departments in the United States prioritize these for throughput, though sensitivity limitations during early infection windows drive parallel molecular confirmation workflows.
- Molecular Tests:Isothermal amplification chemistry—particularly LAMP—now operates in handheld battery-powered devices without thermal cyclers. Germany's community health centers pilot these for same-visit mono confirmation, capturing margin pools previously reserved for laboratory PCR.
- Antibody Tests:Serological assays detect host immune response with declining clinical utility as healthcare systems prioritize active infection detection over post-infection documentation.
- Lateral Flow Devices:The physical substrate architecture—nitrocellulose membranes, conjugate pads, absorbent wicks—underpins all visual-read rapid test formats regardless of analyte target.
Antigen tests anchor the volume base while molecular tests gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates high-margin oncology panels from commoditized infectious disease screening.
- Infectious Diseases:Respiratory pathogen detection—including Epstein-Barr virus for infectious mononucleosis—commands the largest procurement volumes through hospital consortia and national screening programs.
- Infectious Pathogens:Bacterial and viral load quantification for streptococcal pharyngitis and influenza co-testing expands multiplex cartridge applications beyond single-analyte mono detection.
- Autoimmune Disorders:Rheumatoid factor and ANA rapid screening occupies niche point-of-care workflows in rheumatology clinics with limited test menu breadth.
- Oncology:Tumor marker point-of-care testing carries premium pricing but minimal volume overlap with infectious disease rapid test infrastructure.
Infectious diseases anchor the volume base while infectious pathogens gain share at the steepest rate.
End User:
Customer type determines connectivity requirements, operator training depth, and result documentation standards.
- Hospitals:Emergency departments and urgent care units mandate HL7 FHIR interoperability for direct electronic health record ingestion, disqualifying devices lacking standardized middleware.
- Clinics:Rural and community health centers in Japan's METI-funded decentralized networks drive demand for smartphone-integrated readers with Japanese-language interfaces.
- Laboratories:Reference labs deploy rapid tests for STAT processing while maintaining molecular confirmation capacity for discrepant results.
- Home Care Settings:Over-the-counter self-testing indications require FDA de novo clearance with lay-user error studies and thirty-day stability data exceeding prior EUA standards.
Hospitals anchor the volume base while home care settings gain share at the steepest rate.
Distribution Channel:
Supply concentration in membrane substrates and reagent chemistry shapes channel economics and geographic reach.
- Distributors:Medical-surgical distributors like McKesson and Cardinal Health consolidate procurement for hospital systems with contracted formulary access and inventory management services.
- Direct Sales:Manufacturers bypass intermediaries for large integrated delivery networks negotiating enterprise-wide platform agreements with predictive analytics bundling.
- Pharmacies:CVS Health and Walgreens build dedicated rapid testing sections capturing direct consumer spend outside traditional clinical procurement channels.
- Online Retail:E-commerce platforms face regulatory friction for prescription-required tests while expanding access for cleared over-the-counter indications.
Distributors anchor the volume base while pharmacies gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA de novo pathway expansion and EU IVDR implementation are reshaping commercial entry timelines across major diagnostic markets, while Japan's METI funding accelerates decentralized infrastructure buildout in rural prefectures.
United States
Emergency department throughput mandates and CVS Health-Walgreens retail pharmacy expansion drive point-of-care adoption. FDA clearance pathways under Emergency Use Authorization and subsequent de novo classification processes shape product entry timelines. Hospital procurement consortia in Premier and Vizient negotiate multi-year sole-source agreements around integrated diagnostic platforms.
Germany
Community health centers pilot LAMP-based handheld devices for same-visit mono confirmation, capturing margin pools previously reserved for laboratory PCR. CE marking under the EU In Vitro Diagnostic Regulation reorganizes competitive access with extensive performance evaluation requirements. Nitrocellulose membrane supply concentrates with specialized chemical manufacturers in German industrial clusters.
Japan
METI funding for rural clinic point-of-care networks creates demand for Japanese-language, smartphone-integrated rapid test readers. The country's national pharmaceutical regulator maintains stringent post-market surveillance aligned with global harmonization initiatives. Prefectures outside Tokyo and Osaka anchor decentralized diagnostic infrastructure deployment.
United Kingdom
NHS procurement frameworks consolidate supplier relationships around enterprise data analytics and predictive inventory management bundling. The Medicines and Healthcare products Regulatory Agency enforces performance standards for self-testing indications with lay-user comprehension requirements. London and Southeast England clusters host regulatory affairs infrastructure serving European market access.
India
CDSCO streamlined approval pathways for rapid diagnostic kits accelerate market entry for infectious disease screening. The country's national pharmaceutical regulator balances access expansion with quality assurance through notified body harmonization. Maharashtra and Karnataka industrial corridors concentrate manufacturing scale for lateral flow membrane assembly.
Mono Rapid Testing Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with dedicated regulatory affairs infrastructure. Consolidation pressures favor established manufacturers with integrated diagnostic platforms and enterprise data analytics bundling. Two strategic archetypes dominate: lateral flow manufacturing scale operators and molecular miniaturization specialists. Competitive moves center on multi-year sole-source hospital procurement agreements and isothermal amplification technology licensing.
Within the diversified conglomerate tier, Abbott Laboratories and Siemens Healthineers exemplify scale-driven positioning through extensive manufacturing infrastructure and integrated platform architectures. Thermo Fisher Scientific occupies a position emphasizing distribution reach and channel partnerships with hospital procurement networks. These three anchors represent the regulatory affairs depth and clinical validation capacity required for FDA de novo and EU IVDR compliance.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Quidel Corporation |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| Becton, Dickinson and Company |
| Cardinal Health |
| Sekisui Diagnostics |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for nitrocellulose membrane stockpiles concentrate pricing power among German and United States substrate suppliers, forcing antigen test manufacturers to absorb input volatility or sacrifice margin position in high-volume hospital procurement negotiations.
Pricing Analysis
Certification level (FDA de novo versus EU IVDR CE marking) creates the primary spread between premium and standard tier positioning. Three-tier pricing structure across premium, standard, and economy levels dominates, with FDA-cleared devices commanding substantial premiums over notified-body-certified alternatives. Cost compression in the standard tier intensifies as automated reel-to-reel assembly lines proliferate. Hospital procurement consortia exhibit lowest price sensitivity due to throughput mandates, while retail pharmacy channels face acute margin pressure from direct-to-consumer price transparency.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for membrane substrates sourced from German chemical clusters. Manufacturing concentrates in Germany, the United States, and Japan for premium-grade nitrocellulose, while India and China anchor lateral flow assembly scale. Raw material dependencies center on nitrocellulose membranes, conjugate pad polymers, and isothermal amplification reagents. Single-source vulnerability in German membrane production creates structural risk during demand surges. Distribution runs through medical-surgical distributors and direct sales to integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mono rapid testing market represents high-growth disruption as isothermal amplification miniaturization collapses the historical segmentation between laboratory precision and point-of-care speed, with FDA de novo pathway expansion accelerating home-use commercialization.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into nitrocellulose membrane production, eliminating supply bottlenecks that constrain high-volume antigen test output. Secure multi-year sole-source agreements with Premier and Vizient procurement consortia before mid-tier competitors achieve HL7 FHIR interoperability certification. The LAMP-based molecular miniaturization threat demands immediate R&D allocation to handheld platform development.
For New Entrants and Emerging Players: Differentiate on smartphone-integrated reader technology for Japan's METI-funded rural clinic networks, where Japanese-language interfaces and connectivity standards create defendable positioning. Target India's CDSCO-streamlined approval pathways for infectious disease screening kits, leveraging Maharashtra and Karnataka manufacturing corridors for lateral flow assembly scale. Pursue pharmacy-direct distribution partnerships with CVS Health and Walgreens to bypass consolidated hospital procurement channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across isothermal amplification cartridge manufacturing as FDA de novo evidentiary standards demand dedicated clinical affairs infrastructure. Long-term viability favors diversified conglomerates with regulatory depth over pure-play antigen test specialists facing antibody demand collapse. Acquisition target archetype: molecular miniaturization specialists with LAMP chemistry IP and Japanese regulatory clearance. Watch FDA timeline acceleration for over-the-counter self-test indications as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Unlocks over-the-counter self-test indications beyond prior EUA constraints. |
| CE Marking Pathway | Secures EU IVDR compliance for European hospital and retail pharmacy channels. |
| Hospital System Partnership | Integrates rapid testing platforms with Epic and Cerner electronic health record systems. |
| Software Companion Development | Enables smartphone-integrated readers for Japan's decentralized diagnostic networks. |
| Reimbursement Strategy | Aligns point-of-care test coding with CMS and commercial payer coverage policies. |
Research Methodology
The analysis maps antigen test, molecular test, and lateral flow device sub-sectors, each validated through regulatory affairs specialists, hospital procurement managers, GPO contracts managers, and biomedical engineers. Primary interviews with manufacturing executives at membrane substrate suppliers and lateral flow assembly operations combined with secondary validation against FDA 510(k) and de novo filings, EU IVDR notified body documentation, and hospital procurement database records. Bottom-up unit economics and top-down market sizing triangulate volume and value estimates.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework models product type, end user, therapy area, and distribution channel segmentation dimensions with geographic regulatory cluster overlays. CAGRs derive from fitted growth curves calibrated to hospital emergency department throughput mandates, FDA pathway expansion timelines, and retail pharmacy distribution buildout rates. Forecast inputs incorporate lateral flow manufacturing automation diffusion and isothermal amplification miniaturization adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA de novo clearance acceleration, EU IVDR implementation timelines, or nitrocellulose membrane supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization gaps, procurement consortium consolidation patterns, and technology substitution thresholds. Specific risk factors include antibody test demand collapse, laboratory information system integration failures, and post-market surveillance documentation burdens extending registration timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
United States Esoteric Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Cholesterol Test Market
Testing Services
Urine Sediment Testing Market
Testing Services
Global Ovulation Test Market
Testing Services
Zika Virus Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Nipah Virus Testing Market