
 Oncology Blood Testing Market | 2026-2036
Oncology Blood Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Blood Testing Market Analytics
North American diagnostic manufacturers is pivoting toward high-throughput liquid biopsy platforms to serve precision oncology pipelines. F. Hoffmann-La Roche AG anchors European clinical adoption through centralized laboratory workflows. Thermo Fisher Scientific leverages its reagent-to-instrument ecosystem to sustain pricing power in genomic profiling. Illumina competes on sequencing throughput, while QIAGEN N.V. specializes in sample preparation automation for circulating tumor cell isolation.
Oncology blood testing encompasses the detection, quantification, and molecular characterization of cancer-derived analytes in peripheral blood specimens, typically requiring specialized collection tubes with stabilizing additives and temperature-controlled logistics to preserve nucleic acid integrity. These tests enable real-time tumor monitoring, minimal residual disease detection, and therapeutic selection without invasive tissue biopsy. Liquid biopsy commands the largest revenue share among test types due to its clinical utility in tracking resistance mutations, while next-generation sequencing technology captures the fastest expansion as panel sizes broaden and turnaround times compress. Protein biomarkers retain stable demand in community oncology settings where simpler workflows prevail.
The FDA regulates oncology blood tests as in vitro diagnostics or companion diagnostics, requiring analytical and clinical validation that shapes product development timelines and commercial launch sequencing. The European Medicines Agency coordinates with notified bodies under the In Vitro Diagnostic Regulation to enforce post-market surveillance and performance monitoring. The Clinical Laboratory Improvement Amendments govern U.S. laboratory-developed test quality standards, directly influencing whether hospitals internalize testing or outsource to reference laboratories. Stakeholders must monitor how CMS coverage determinations for multi-cancer early detection panels reshape volume forecasts and capital deployment priorities.
Market Dynamics
FDA companion diagnostic approvals are compressing development timelines and forcing manufacturers to synchronize liquid biopsy platforms with oncology drug pipelines. This regulatory-produstrial coupling is redistributing competitive advantage toward vertically integrated diagnostic developers.
Growth Catalysts
- Companion Diagnostic Mandates:FDA requirements for co-developed biomarker tests accelerate liquid biopsy adoption in non-small cell lung cancer and colorectal cancer protocols.
- Academic Medical Center Consolidation:United States cancer centers are standardizing circulating tumor DNA workflows across multisite networks, creating volume anchors for high-throughput platforms.
- Digital PCR Sensitivity Gains:Droplet-based enrichment technologies now detect mutant allele frequencies below 0.1%, expanding clinical utility into minimal residual disease monitoring.
Market Restraints
- Reagent Supply Concentration:Stabilizing additive chemistries for cell-free DNA collection depend on three German specialty chemical suppliers, creating input vulnerability.
- CMS Coverage Uncertainty:Medicare reimbursement determinations for multi-cancer early detection panels remain pending, freezing hospital capital deployment.
- Tissue Biopsy Persistence:Pathology departments retain institutional preference for histological confirmation, limiting liquid biopsy to sequential rather than first-line testing.
Strategic Opportunities
- Community Oncology Penetration:United States physician-owned practices outside academic centers represent untapped volume for simplified protein biomarker workflows.
- Artificial Intelligence Convergence:Machine learning classification of fragmentomic patterns is integrating with sequencing data to improve cancer-of-origin prediction.
- Pharmaceutical Service Contracts:Diagnostic manufacturers can capture recurring revenue through longitudinal monitoring agreements with immuno-oncology drug developers.
Industry Challenges
- Bioinformatician Scarcity:Clinical laboratories face recruitment gaps for variant interpretation specialists capable of annotating complex structural alterations.
- Laboratory Information System Integration:Electronic health record connectivity for real-time biomarker reporting requires costly middleware development across heterogeneous hospital IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Blood Testing Market |
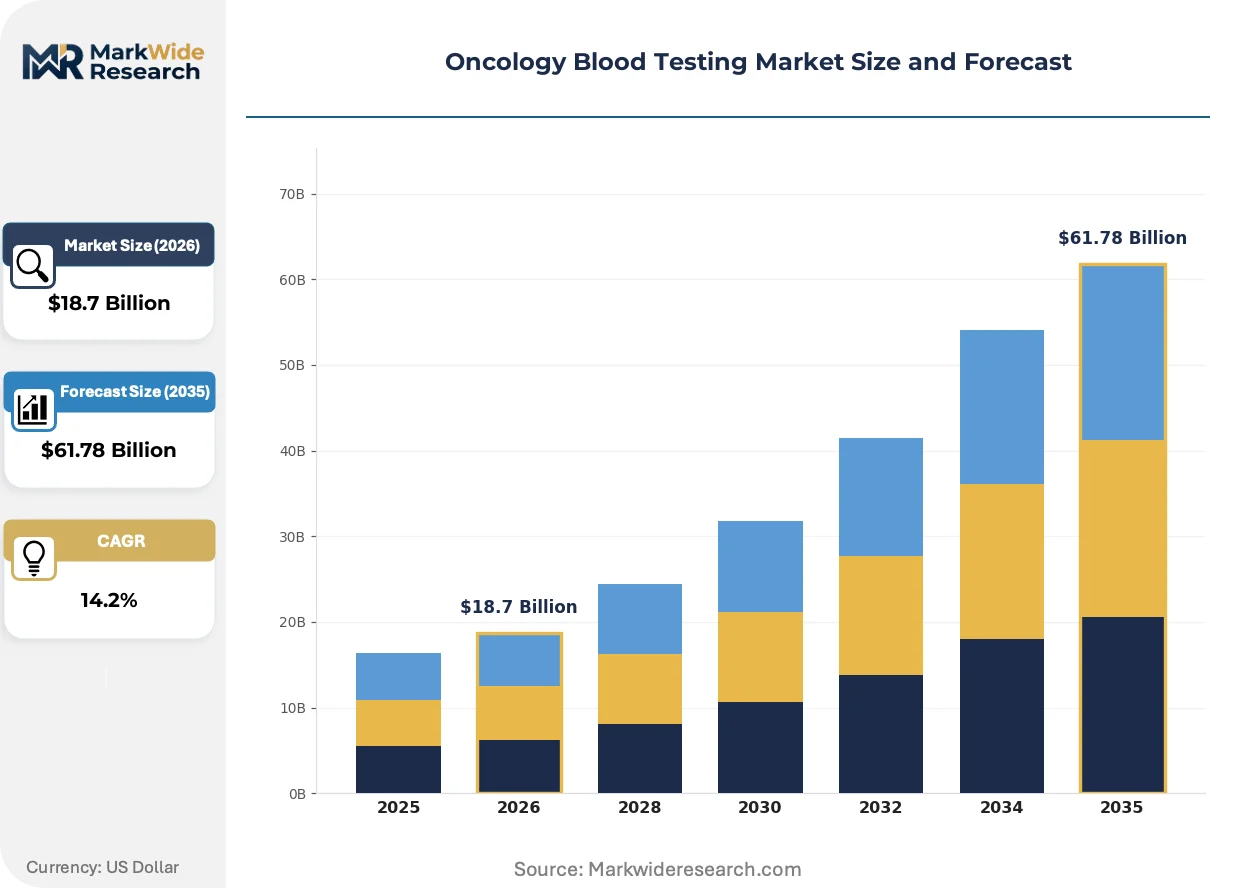
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Liquid Biopsy, Genomic Profiling, Protein Biomarkers, Circulating Tumor Cells Technology: NEXT-Generation Sequencing, PCR, Microarray, Mass Spectrometry Sample Type: Plasma, Serum, Whole Blood, Exosomes End User: Hospitals, Diagnostic Laboratories, Research Institutes, Cancer Treatment Centers |
| Companies Covered | F. Hoffmann-La Roche AG, Abbott Laboratories, Thermo Fisher Scientific, Danaher Corporation, Siemens Healthineers AG, Illumina, Bio-Rad Laboratories, QIAGEN N.V., Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Blood Testing Market Evolving Landscape
Methylation-based classification algorithms are displacing single-analyte detection methods, while regulatory frameworks co-evolve with clinical evidence generation. These intersecting forces are compressing the gap between research-grade performance and reimbursable standard of care.
Multi-omics profiling is integrating genotypic, epigenetic, and proteomic signals into unified liquid biopsy reports. Comprehensive cancer centers in the United States are adopting these platforms for treatment-naive patient stratification. The technology is integrating previously siloed biomarker categories into single-sample workflows, reducing phlebotomy burden while expanding actionable mutation coverage.
EMA coordination with notified bodies under the In Vitro Diagnostic Regulation is enforcing post-market performance monitoring for high-risk oncology devices. Manufacturers must now submit annual safety reports and real-world evidence updates. European reference laboratories are responding by internalizing quality management systems that exceed minimum conformity requirements, creating competitive differentiation through regulatory exceedance.
Hospital procurement departments are consolidating vendor relationships through exclusive liquid biopsy panel contracts rather than maintaining multiple send-out relationships. Community oncology networks in the United States are negotiating system-wide pricing with single diagnostic partners. This concentration is visible most acutely in the southeastern states, where hospital acquisition of independent practices has compressed supplier lists from twelve to three reference laboratories within thirty-six months.
Oncology Blood Testing Market Segmentation
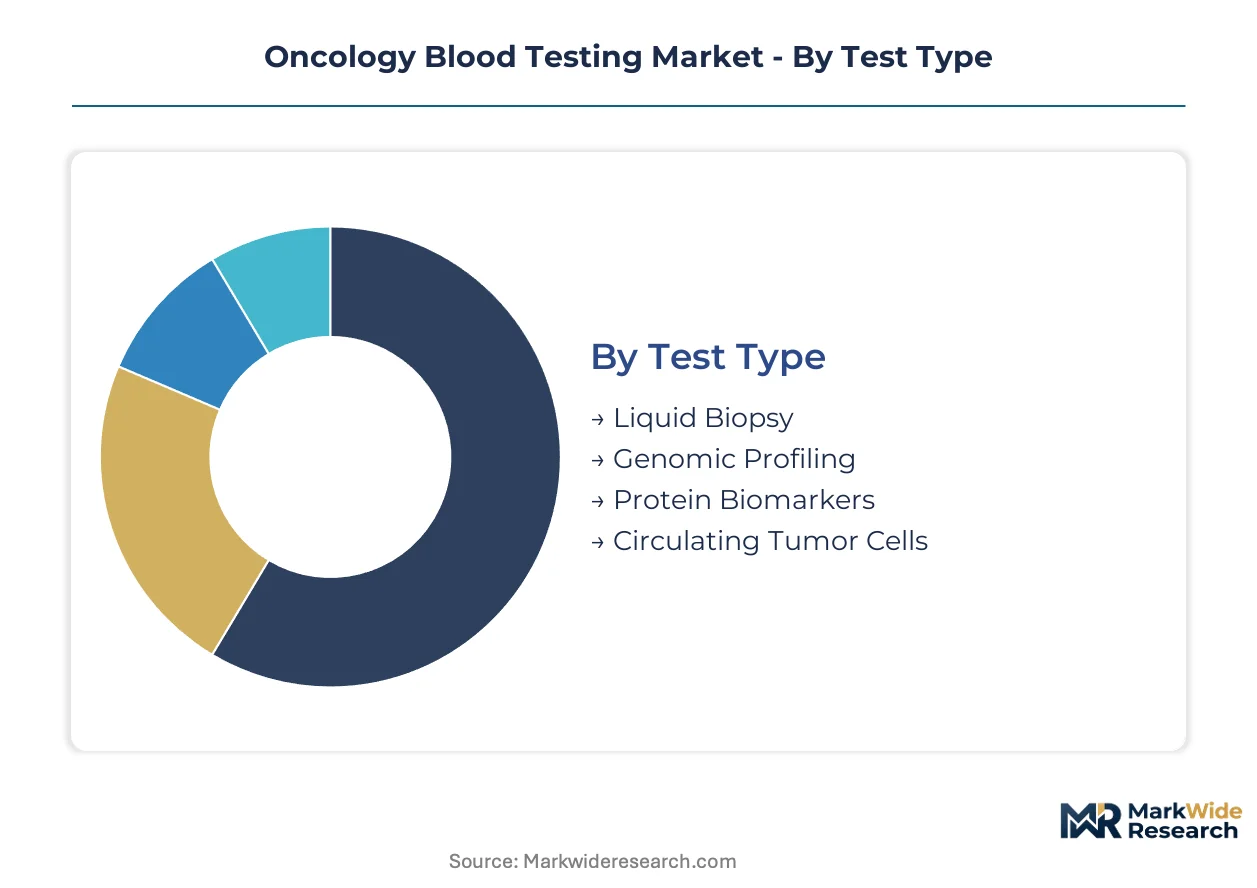
Oncology blood testing segments diverge sharply between standardized platforms for high-throughput screening and customized workflows for rare mutation detection. Manufacturers calibrate product portfolios across this spectrum to capture both volume efficiency and premium analytical services.
Test Type:
Customization intensity varies from off-the-shelf protein panels to bespoke multi-gene liquid biopsy designs negotiated per oncology protocol.
- Liquid Biopsy:Circulating tumor DNA and RNA analysis enables real-time resistance monitoring without tissue acquisition. Academic medical centers in the United States anchor demand as FDA companion diagnostic approvals expand reimbursable indications.
- Genomic Profiling:Broad panel sequencing identifies actionable mutations across solid tumor types. Cancer treatment centers integrate these workflows into first-line therapy selection, though turnaround time constraints limit community adoption.
- Protein Biomarkers:Established immunoassays for PSA, CA-125, and CEA dominate community oncology settings where simpler logistics prevail.
- Circulating Tumor Cells:Enumeration and characterization platforms serve minimal residual disease applications in specialized reference laboratories.
Leading the category by volume: Liquid Biopsy. Growing fastest: Genomic Profiling.
Technology:
Cost tiering separates capital-intensive sequencing infrastructure from deployable point-of-care alternatives.
- NEXT-Generation Sequencing:High-throughput platforms process hundreds of samples weekly with expanding gene panel coverage. United States cancer centers prioritize these systems for clinical trial enrollment and precision therapy matching.
- PCR:Digital and droplet-based methods deliver rapid turnaround for known mutation hotspots at lower per-test cost. Community laboratories favor PCR for EGFR and KRAS testing where single-analyte sensitivity suffices.
- Microarray:Copy number variation profiling supports research applications with lower per-sample reagent costs than sequencing.
- Mass Spectrometry:Proteomic quantification of circulating peptides enables multi-analyte protein signature detection in specialized reference settings.
Highest installed base: PCR. Steepest expansion trajectory: NEXT-Generation Sequencing.
Sample Type:
Stability requirements and nucleic acid yield differentiate collection protocols across clinical and research settings.
- Plasma:Cell-free DNA preservation in specialized stabilizing tubes enables longitudinal monitoring with standardized preanalytical workflows. United States logistics networks have optimized cold-chain handling for plasma specimens.
- Serum:Protein biomarker stability and established assay validation support high-volume community testing without specialized collection infrastructure.
- Whole Blood:Circulating tumor cell isolation requires immediate processing or proprietary preservation systems, limiting deployment to centralized laboratories.
- Exosomes:Emerging isolation methods capture tumor-derived vesicles for RNA and protein cargo analysis in research protocols.
Dominant clinical volume: Plasma. Gaining share fastest: Exosomes.
End User:
Procurement authority and technical sophistication segment demand between integrated health systems and independent service providers.
- Hospitals:Academic medical centers internalize high-complexity testing to capture margin and control turnaround times. IDN consolidation in the United States southeastern states has compressed reference laboratory vendor lists from twelve to three within thirty-six months.
- Diagnostic Laboratories:National reference networks aggregate volume across dispersed oncology practices, achieving scale economies in reagent procurement and bioinformatics staffing.
- Research Institutes:Early-access protocols and custom assay development drive premium pricing for investigational applications.
- Cancer Treatment Centers:NCI-designated comprehensive centers coordinate multi-site biomarker standardization across regional networks.
Largest revenue concentration: Hospitals. Expanding most quickly: Cancer Treatment Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical suppliers anchor the preanalytical supply chain for cell-free DNA collection tubes. Academic medical centers in the United States and cancer research clusters in Switzerland drive clinical validation studies. Manufacturing of stabilizing additives concentrates in the Rhine-Ruhr industrial corridor.
United States
NCI-designated comprehensive cancer centers in Boston and Houston standardize circulating tumor DNA workflows across multisite networks. FDA companion diagnostic approvals for non-small cell lung cancer and colorectal cancer protocols accelerate liquid biopsy integration into precision oncology. The southeastern states exhibit rapid hospital acquisition of independent practices, compressing reference laboratory vendor lists from twelve to three within thirty-six months.
Germany
Centralized laboratory workflows at university hospitals in Heidelberg and Munich anchor European clinical adoption of genomic profiling platforms. EMA coordination with notified bodies under the In Vitro Diagnostic Regulation enforces annual safety reporting and real-world evidence submission for high-risk oncology devices. The Rhine-Ruhr corridor hosts three specialty chemical suppliers producing stabilizing additives for cell-free DNA preservation tubes.
Switzerland
Swissmedic oversight of in vitro diagnostics aligns with EMA frameworks while maintaining distinct post-market surveillance requirements for oncology devices. Basel and Zurich host precision medicine research consortia integrating pharmaceutical development with companion diagnostic validation. Roche's centralized laboratory infrastructure anchors European distribution of liquid biopsy platforms.
China
NMPA streamlined approval pathways for innovative oncology diagnostics accelerate local platform development in Shanghai and Beijing. The country's national pharmaceutical regulator mandates clinical trials conducted within domestic populations for biomarker test registration. Yangtze River Delta biotech clusters specialize in droplet-based digital PCR systems for minimal residual disease monitoring.
United Kingdom
NHS England's genomic medicine service consolidates biomarker testing into regional laboratory hubs in London, Manchester, and Birmingham. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit, creating parallel conformity assessment obligations for European manufacturers. Cambridge cancer research institutes pioneer methylation-based classification algorithms for cancer-of-origin prediction.
Oncology Blood Testing Market Competitive Landscape
Global majors compete with regional champions across regulatory approval velocity and laboratory service integration. The vendor base organizes into three tiers: vertically integrated diagnostic developers with pharmaceutical partnerships, specialized sample preparation automation firms, and regional reference laboratories capturing community oncology volume. Two dominant competitive moves reshape positioning: exclusive liquid biopsy panel contracts with consolidated hospital systems, and longitudinal monitoring service agreements with immuno-oncology drug developers.
Within the vertically integrated tier, F. Hoffmann-La Roche AG and Thermo Fisher Scientific exemplify archetypes of regulatory-produstrial coupling with pharmaceutical pipelines. QIAGEN N.V. occupies a specialist position in preanalytical automation for circulating tumor cell isolation. These three entities represent distinct strategic postures—Roche through centralized laboratory dominance, Thermo Fisher through reagent-to-instrument ecosystem control, and QIAGEN through workflow automation specialization—without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Siemens Healthineers AG |
| Illumina |
| Bio-Rad Laboratories |
| QIAGEN N.V. |
| Agilent Technologies |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up reference laboratory networks in the United States southeastern states anchor supply consolidation and enforce contract-based pricing discipline through exclusive panel agreements with acquired physician practices. This ownership pattern compresses vendor lists from twelve to three within thirty-six months while locking in multi-year service commitments that insulate high-throughput liquid biopsy platforms from spot-market price erosion.
Pricing Analysis
Extended warranty and bioinformatics support bundling separates premium liquid biopsy contracts from unbundled reagent-only transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by turnaround time and panel breadth, with academic medical centers absorbing premium tiers while community oncology practices gravitate toward economy positioning. Cost compression in economy tiers is intensifying because hospital procurement departments consolidate vendor relationships through exclusive liquid biopsy panel contracts. Community oncology networks exhibit highest price sensitivity due to thinner margins and simpler workflow requirements.
Supply Chain Analysis
FDA and EMA quality system certifications gate entry for stabilizing additive chemistries and nucleic acid preservation systems. Manufacturing concentrates in Germany, the United States, and Switzerland, with the Rhine-Ruhr corridor hosting three specialty chemical suppliers producing proprietary tube additives. Raw material dependencies center on cell-free DNA stabilizing chemistries, specialized polymer formulations, and temperature-controlled logistics infrastructure. Single-source vulnerability runs through German specialty chemical suppliers for proprietary additive formulations. Distribution runs through centralized laboratory networks and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncology blood testing sits at a technology-transition inflection where methylation-based classification algorithms displace single-analyte detection methods across minimal residual disease applications. This shift rewards diagnostic developers with fragmentomic pattern recognition capabilities and punishes legacy protein biomarker specialists lacking sequencing infrastructure.
For Market Incumbents: Deploy exclusive liquid biopsy panel contracts as the primary defensive lever. Roche and Thermo Fisher Scientific should extend centralized laboratory dominance through longitudinal monitoring agreements with immuno-oncology drug developers while accelerating FDA companion diagnostic synchronization. Incumbents must neutralize QIAGEN's preanalytical automation specialization by internalizing sample preparation workflows or acquiring workflow automation specialists.
For New Entrants and Emerging Players: Launch via simplified protein biomarker workflows targeting United States community oncology practices outside academic centers. White-space concentration sits in physician-owned practices in the southeastern states where hospital acquisition has not yet consolidated reference laboratory relationships. New entrants should prioritize artificial intelligence convergence for cancer-of-origin prediction as the differentiated go-to-market angle against established genomic profiling platforms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional reference laboratories with captive community oncology volume in United States metropolitan areas outside consolidated IDN networks. Long-term viability hinges on reimbursement resolution for multi-cancer early detection panels and bioinformatician staffing scalability. The signal to watch is CMS coverage determinations for multi-cancer early detection panels as the volume inflection trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Companion Diagnostic Submission | Accelerates liquid biopsy integration into non-small cell lung cancer and colorectal cancer protocols. |
| CE Marking Pathway under IVDR | Enables European market entry through EMA coordination with notified bodies for high-risk oncology devices. |
| Hospital System Partnership | Locks in volume anchors through exclusive panel contracts with consolidated IDN networks. |
| Software Companion Development | Integrates machine learning classification of fragmentomic patterns with sequencing data outputs. |
| Reimbursement Strategy | Secures CMS coverage determinations for multi-cancer early detection panels and companion diagnostic indications. |
Research Methodology
FDA 510(k) and PMA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone for regulatory approval velocity analysis and companion diagnostic pipeline tracking. Primary interviews with clinical laboratory directors, hospital procurement managers, companion diagnostic development executives, and GPO contracts specialists validated workflow adoption patterns and pricing discipline across United States cancer centers. SEC 10-K disclosures and European notified body annual safety reports provided financial and post-market surveillance inputs. Bottom-up volume modeling across test type, technology, and end-user segments triangulated against top-down market sizing from regulatory filing aggregation.
Historical trendline analysis of liquid biopsy adoption curves in academic medical centers informed projection frameworks across the analysis window. Segmentation dimensions modeled include test type intensity, technology capital requirements, sample stability protocols, and procurement authority concentration. CAGRs were derived from regression analysis of FDA approval velocity and hospital capital deployment patterns. Industry-specific forecast inputs incorporated digital PCR sensitivity thresholds and CMS coverage determination timelines.
Companion diagnostic approval delays, CMS reimbursement reversals, and bioinformatician recruitment shortfalls are the dominant revision risks to volume and value assumptions. Forecasts reflect documented assumptions regarding regulatory-produstrial coupling intensity and hospital consolidation velocity. A model refresh is warranted upon material change in FDA companion diagnostic approval timelines or CMS national coverage determination outcomes for multi-cancer early detection panels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market